
 Middle East and Africa Glass Packaging Market | 2026-2036
Middle East and Africa Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Glass Packaging Market Foresight
Plastic is hardening its cost advantage in bulk beverage logistics across North Africa, yet premium spirits and perfumery brands continue specifying molded glass for shelf differentiation and oxygen barrier performance. Saudi Arabian Glass Company leverages captive silica sand reserves and natural gas-fired furnace economics to dominate Arabian Peninsula supply. Consol Glass sustains its position through closed-loop bottle return schemes serving South African breweries. Beta Glass Plc anchors West African distribution through Lagos-based manufacturing and direct shipping networks into Ghana and Cote d'Ivoire.
Middle East and Africa glass packaging encompasses rigid vessels manufactured from soda-lime-silica or borosilicate compositions, formed through blow-and-blow or press-and-blow processes, then annealed to relieve thermal stress and achieve specified burst pressures. These containers provide chemically inert, impermeable, and UV-blocking storage for consumable and sterile products across ambient and refrigerated supply chains. Bottles capture the dominant share of pharmaceutical and alcoholic beverage applications where amber and flint glass grades command margin premiums based on hydrolytic resistance certification. Jars and containers within food service and cosmetics are recording faster volume expansion as Egyptian and Moroccan contract manufacturers qualify for European export compliance. Direct shipping modes are displacing third-party logistics for high-value perfume and pharmaceutical glass where breakage rates and chain-of-custody documentation determine tender awards.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that obligate glass producers to fund post-consumer collection infrastructure, directly elevating recycled cullet input ratios. Egypt's General Organization for Export and Import Control applies harmonized standards aligned with CE marking prerequisites for glassware entering European Union pharmaceutical value chains. The Gulf Standardization Organization issues mandatory technical regulations for food-contact glass across GCC member states, creating compliance thresholds that filter smaller regional converters. Stakeholders must monitor how Egypt's new industrial city clusters and Saudi Arabia's giga-project hospitality pipelines alter volume and specification requirements for container glass procurement.
Market Dynamics
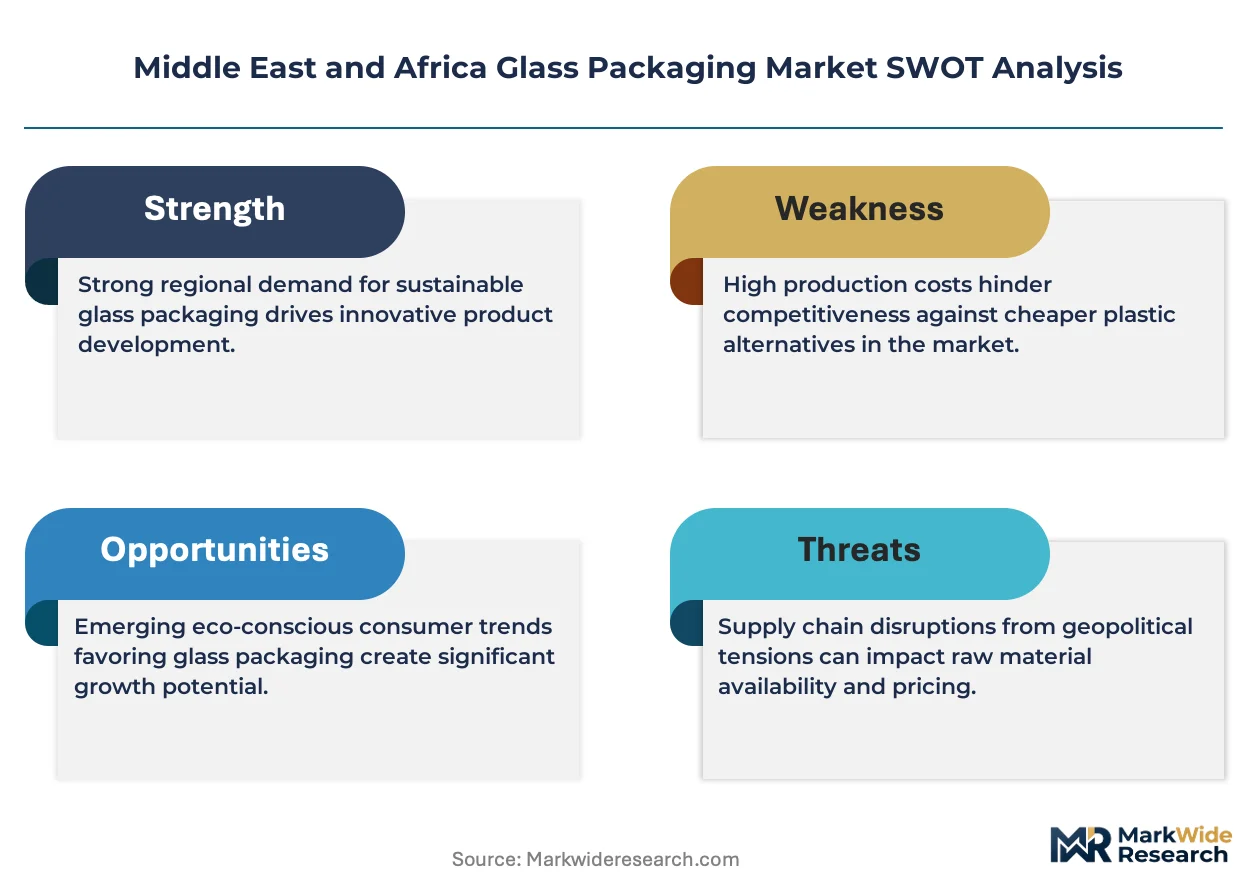
Extended producer responsibility mandates across South Africa and Egypt are forcing glass manufacturers to reconfigure feedstock sourcing around higher cullet ratios, compressing virgin silica demand while elevating furnace energy efficiency requirements.
Growth Catalysts
- Pharmaceutical serialization requirements:Gulf Cooperation Council states now mandate track-and-trace compliance for sterile glass containers, pulling borosilicate vial demand from European contract manufacturers toward regional converters.
- Egypt's Suez Canal logistics access:Multinational pharmaceutical packagers are consolidating procurement contracts in Egyptian industrial zones to exploit direct Mediterranean-Red Sea shipping corridors.
- Natural gas furnace economics:Saudi Arabian silica sand reserves coupled with subsidized energy inputs sustain cost parity against imported plastic alternatives for premium beverage applications.
Market Restraints
- Soda ash price volatility:Egyptian and Turkish soda ash supply disruptions transmit directly to container glass cost structures, eroding margin buffers for mid-scale converters.
- Single-source furnace dependency:West African markets rely on Lagos-based manufacturing clusters, concentrating breakage risk and logistics disruption exposure.
- Plastic substitution in bulk beverages:North African dairy and water distributors are specifying PET for volume logistics, constraining glass to premium spirits and perfumery niches.
Strategic Opportunities
- Moroccan export qualification:Contract manufacturers near Casablanca are achieving CE marking alignment for pharmaceutical glassware, unlocking European Union value chain access.
- Closed-loop brewery collection:South African deposit-return infrastructure creates captive cullet streams that foreign entrants cannot replicate without decade-scale investment.
- Giga-project hospitality pipelines:Saudi Arabia's entertainment and tourism construction wave is specifying custom molded glass for food service and amenity applications.
Industry Challenges
- Hydrolytic resistance certification timelines:Pharmaceutical glassware requires extended laboratory validation against USP Type I standards, stretching product development cycles.
- Furnace rebuild capex intensity:Converting from air-fuel to oxy-fuel combustion for emissions compliance demands capital allocations that strain privately held regional producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Glass Packaging Market |
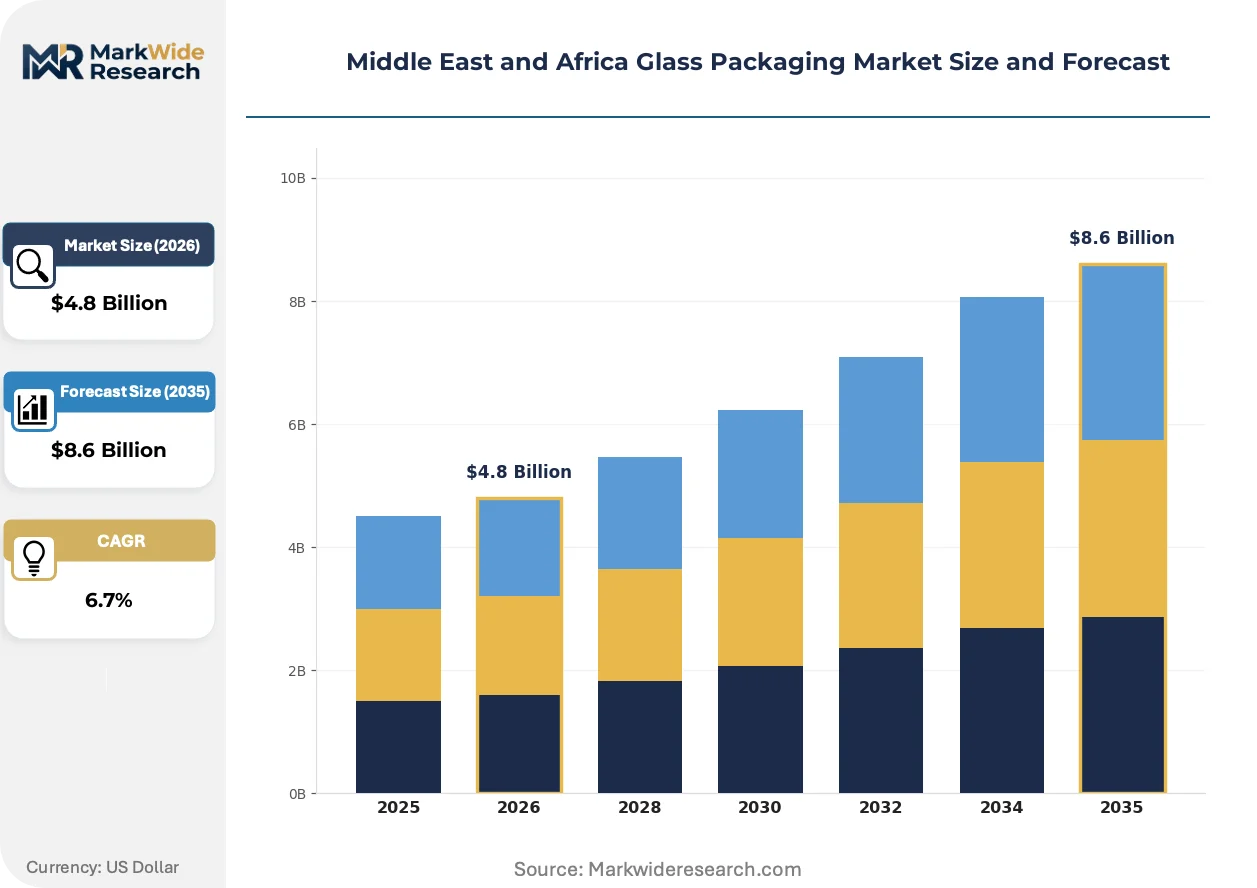
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubes Application: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care End User: Retail, Hospitality, Healthcare, Manufacturing Delivery Mode: Direct Shipping, Third-Party Logistics, Distribution Centers, E-Commerce |
| Companies Covered | Saudi Arabian Glass Company (SAGCO), National Glass Industries Company (ZOUJAJ), Middle East Glass Manufacturing Co. (MEG), Consol Glass (Pty) Ltd., RAK Ghani Glass LLC, Emirates Glass LLC, East African Glass Works Ltd, Beta Glass Plc, Ardagh Group SA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Glass Packaging Market Shifts & Advancements
Digital printing and surface treatment technologies are collapsing minimum order quantities for decorated glass, enabling batch-of-one customization previously restricted to premium European converters.
Ultraviolet-cured organic coatings for amber pharmaceutical glass are converging with laser-etched serialization to eliminate paper label adhesion failures in tropical humidity zones. Gulf-based packagers are adopting these dual-layer systems for insulin and vaccine containers. The technology is compressing lead times for regulatory artwork changes from weeks to hours.
Egypt's General Organization for Export and Import Control has harmonized domestic standards with CE marking prerequisites for pharmaceutical glassware entering European Union markets. This alignment is accelerating contract manufacturing qualification timelines for Cairo and Alexandria industrial zone producers. Multinational pharmaceutical companies are responding by shifting sourcing audits from European suppliers to Egyptian facilities.
Direct shipping contracts are displacing third-party logistics for high-value perfume and pharmaceutical glass where breakage documentation and chain-of-custody verification determine tender awards. Luxury fragrance houses in the United Arab Emirates now specify manufacturer-managed transport from furnace to filling line. This channel compression is most visible in Dubai's Jebel Ali pharmaceutical free zone clusters.
Middle East and Africa Glass Packaging Market Segmentation
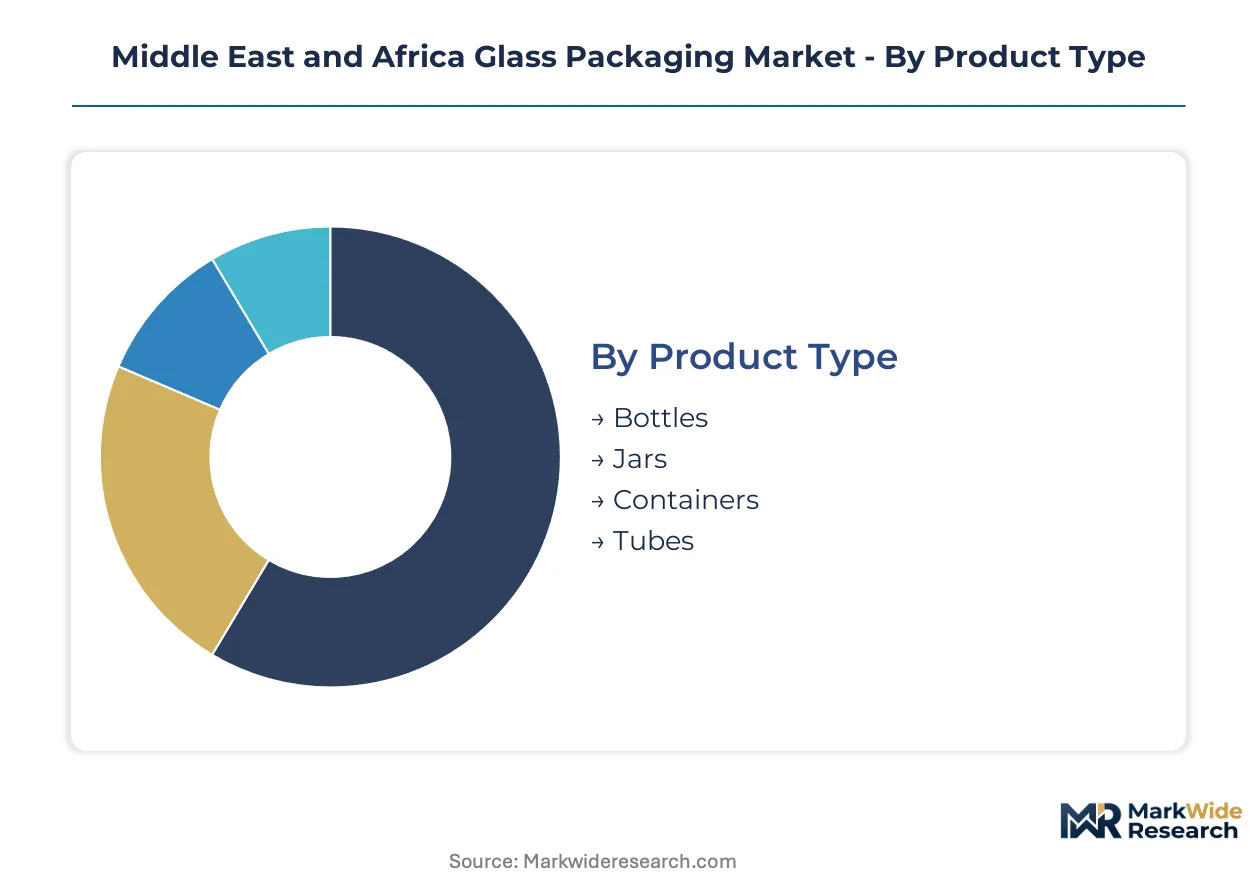
Glass packaging procurement across the Middle East and Africa hinges on thermal performance specifications and logistics infrastructure maturity. Buyers segment offerings by hydrolytic resistance grades for pharmaceutical compliance and by furnace proximity for freight economics.
Product Type:
Borosilicate durability requirements and beverage volume scale drive product selection across Egyptian pharmaceutical clusters and Saudi giga-project pipelines.
- Bottles:Soda-lime-silica and borosilicate compositions formed through blow-and-blow processes dominate sterile pharmaceutical and premium spirits applications. GCC pharmaceutical serialization mandates are pulling borosilicate vial demand toward regional converters in Egypt and Saudi Arabia.
- Jars:Press-and-blow manufactured containers with wide-mouth finishes serve food service and cosmetics sectors. Moroccan contract manufacturers near Casablanca are achieving CE marking alignment for European export qualification.
- Containers:Amber and flint glass grades with specified UV-blocking properties protect light-sensitive formulations. South African extended producer responsibility regulations mandate higher recycled cullet input ratios for this category.
- Tubes:Pharmaceutical ampoules and small-volume vessels require hydrolytic resistance certification against USP Type I standards. Extended laboratory validation timelines stretch product development cycles for regional producers.
Volume sits with bottles; growth tilts toward jars.
Application:
Regulatory compliance thresholds and oxygen barrier performance separate premium specifications from commodity procurement.
- Food & Beverage:Natural gas-fired furnace economics in Saudi Arabia sustain cost parity against PET alternatives for premium spirits. North African dairy distributors are shifting bulk volume to plastic, constraining glass to shelf-differentiated segments.
- Pharmaceuticals:Track-and-trace compliance mandates across GCC states demand borosilicate vials with laser-etched serialization. Suez Canal logistics access is consolidating multinational procurement contracts in Egyptian industrial zones.
- Cosmetics:Ultraviolet-cured organic coatings eliminate label adhesion failures in tropical humidity zones. Dubai's Jebel Ali pharmaceutical free zone clusters specify manufacturer-managed transport for high-value perfume glass.
- Personal Care:Digital printing technologies enable batch-of-one customization for amenity applications. Saudi giga-project hospitality pipelines specify custom molded glass for food service and guest amenities.
Pharmaceuticals command margin premiums; cosmetics are expanding most quickly.
End User:
Collection infrastructure maturity and direct shipping requirements shape procurement channel selection.
- Retail:Closed-loop bottle return schemes in South Africa create captive cullet streams that foreign entrants cannot replicate. Consol Glass sustains position through brewery-serving deposit infrastructure.
- Hospitality:Custom molded glass specifications for Saudi entertainment and tourism construction wave drive specialty volume. Direct shipping contracts displace third-party logistics for breakage-sensitive applications.
- Healthcare:Sterile container requirements from Gulf Standardization Organization technical regulations filter smaller regional converters. Beta Glass Plc anchors West African distribution through Lagos-based manufacturing.
- Manufacturing:Contract manufacturers in Cairo and Alexandria industrial zones qualify for European pharmaceutical value chains. Egyptian General Organization for Export and Import Control harmonization with CE marking accelerates audit timelines.
Retail holds installed base; hospitality shows steepest expansion trajectory.
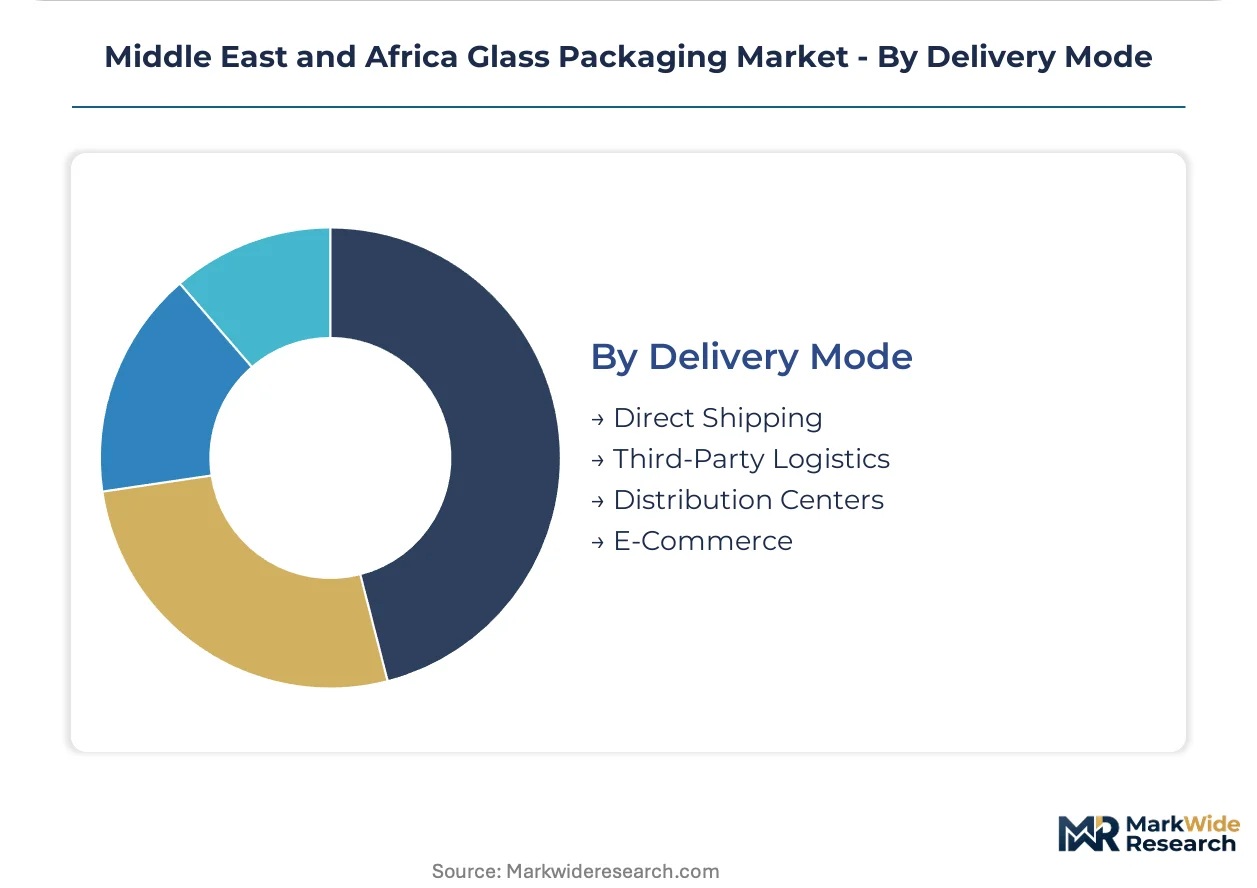
Delivery Mode:
Breakage documentation requirements and chain-of-custody verification determine logistics tender awards for high-value segments.
- Direct Shipping:Manufacturer-managed transport from furnace to filling line captures luxury fragrance and insulin container movements. UAE-based perfume houses specify this mode for Jebel Ali pharmaceutical free zone clusters.
- Third-Party Logistics:Conventional freight consolidation serves standard beverage and food service applications where breakage rates permit pooled distribution. Cost pressure favors this mode for non-pharmaceutical volumes.
- Distribution Centers:Regional warehousing near Suez Canal corridors supports Mediterranean-Red Sea shipping consolidation for multinational pharmaceutical packagers. Egyptian industrial zone proximity enables this configuration.
- E-Commerce:Small-parcel fulfillment for cosmetic and personal care glass demands protective packaging innovation. Minimum order quantity compression from digital printing supports this channel's viability.
Direct shipping dominates value; distribution centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's new industrial city clusters and Suez Canal Economic Zone tax incentives are concentrating multinational pharmaceutical packaging procurement in Cairo and Alexandria corridors. Saudi Arabia's giga-project hospitality pipelines and subsidized natural gas furnace economics anchor Arabian Peninsula supply. South Africa's extended producer responsibility mandates and closed-loop brewery infrastructure sustain Southern African market structure.
Egypt
Pharmaceutical serialization demand and Mediterranean-Red Sea logistics access pull borosilicate vial contracts toward Cairo industrial zones. The General Organization for Export and Import Control harmonizes domestic standards with CE marking prerequisites for European Union value chain entry. Alexandria glass manufacturers qualify for multinational sourcing audits through accelerated compliance timelines.
Saudi Arabia
Captive silica sand reserves and natural gas-fired furnace economics sustain cost parity against plastic alternatives for premium spirits. The Gulf Standardization Organization issues mandatory technical regulations for food-contact glass across GCC member states. Riyadh-based producers supply giga-project hospitality pipelines with custom molded glass for food service and amenity applications.
South Africa
Extended producer responsibility regulations from the Department of Forestry, Fisheries and the Environment mandate higher recycled cullet input ratios for container glass. Closed-loop bottle return schemes create captive cullet streams serving brewery networks. Consol Glass sustains position through deposit infrastructure concentrated in Gauteng and Western Cape provinces.
United Arab Emirates
Luxury fragrance houses specify manufacturer-managed transport from furnace to filling line for high-value perfume glass. Dubai's Jebel Ali pharmaceutical free zone clusters attract direct shipping contracts displacing third-party logistics. MOHAP and SFDA technical regulations filter smaller regional converters from sterile container supply.
Nigeria
Lagos-based manufacturing clusters anchor West African distribution through direct shipping networks into Ghana and Cote d'Ivoire. Single-source furnace dependency concentrates breakage risk and logistics disruption exposure for regional beverage and pharmaceutical demand. Beta Glass Plc occupies position within this concentrated supply structure.
Middle East and Africa Glass Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated silica-to-furnace operators commanding premium beverage and pharmaceutical tiers while regional converters serve price-sensitive food service volumes. Market structure tilts toward consolidation around captive raw material access and energy subsidies, particularly in Arabian Peninsula markets. Three archetypes dominate: state-linked industrial conglomerates with mineral reserves, European multinationals with pharmaceutical certification expertise, and regional specialists with brewery-serving collection infrastructure. Competitive moves center on furnace technology upgrades for emissions compliance and direct shipping contract capture for high-value perfume and insulin container segments.
Within the state-linked industrial tier, Saudi Arabian Glass Company exemplifies captive resource positioning through silica sand reserve control. Among regional specialists with closed-loop infrastructure, Consol Glass and Beta Glass Plc represent contrasting geographic anchors—Southern African deposit-return schemes versus West African manufacturing concentration. European multinational presence surfaces through Ardagh Group SA, which occupies position within pharmaceutical and premium beverage certification tiers. Emirates Glass LLC and RAK Ghani Glass LLC sit within UAE-based specialist manufacturing, serving fragrance and hospitality demand clusters.
| Leading Market Players |
|---|
| Saudi Arabian Glass Company (SAGCO) |
| National Glass Industries Company (ZOUJAJ) |
| Middle East Glass Manufacturing Co. (MEG) |
| Consol Glass (Pty) Ltd. |
| RAK Ghani Glass LLC |
| Emirates Glass LLC |
| East African Glass Works Ltd |
| Beta Glass Plc |
| Ardagh Group SA |
| Others |
Supply & Pricing Matrix
Soda ash price volatility cascades through Egyptian and Turkish supply corridors into container glass cost structures, compressing margin buffers for mid-scale converters while amplifying pricing power for integrated producers with captive mineral reserves.
Pricing Analysis
Lead-time compression commands premium positioning across pharmaceutical and perfumery tiers, with spot inventory liquidated at discounted rates to beverage distributors. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I certified borosilicate vials from commercial-grade soda-lime containers and generic food-service volumes. Cost compression in standard beverage tiers is intensifying because PET substitution erodes glass volume leverage. Bulk dairy distributors exhibit highest price sensitivity; luxury fragrance houses demonstrate inelastic demand for breakage-guaranteed direct shipping.
Supply Chain Analysis
CE marking alignment and Gulf Standardization Organization technical regulations gate Egyptian and Moroccan contract manufacturers from European and GCC pharmaceutical value chains respectively. Supply concentrates in Saudi Arabia, Egypt, and South Africa, with silica sand reserves, Suez Canal logistics access, and closed-loop cullet infrastructure anchoring regional dominance. Furnace operations draw from natural gas subsidies, imported soda ash, and post-consumer recycled cullet. Single-source dependency around Lagos manufacturing clusters concentrates breakage risk and logistics disruption exposure. Distribution runs through direct shipping contracts for high-value segments and third-party consolidation for commodity beverage volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive silica sand access and subsidized energy inputs determine cost parity against plastic substitutes.
For Market Incumbents: Hedge furnace rebuild cycles through oxy-fuel conversion partnerships that spread emissions compliance capex across multi-year contracting. Secure backward integration into silica sand reserves or forward integration into direct shipping logistics to defend margin position against PET erosion in bulk beverage tiers.
For New Entrants and Emerging Players: Enter via Moroccan pharmaceutical contract manufacturing where CE marking alignment unlocks European value chain access with lower qualification friction than Egyptian clusters. Target Saudi giga-project hospitality pipelines for custom molded glass specifications, leveraging digital printing capabilities to collapse minimum order quantities for amenity applications.
For Investors and Strategic Acquirers: The window for entry favors regional specialists with closed-loop brewery collection infrastructure that foreign entrants cannot replicate without decade-scale investment. Monitor South African extended producer responsibility enforcement intensity as the inflection signal for cullet input ratio mandates spreading northward.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Conversion | Emissions compliance investment aligns Saudi and Egyptian producers with Gulf Standardization Organization technical regulations. |
| Direct Shipping Contract Capture | Manufacturer-managed transport from furnace to filling line secures luxury fragrance and insulin container movements in UAE free zones. |
| CE Marking Qualification | Harmonization with Egyptian General Organization for Export and Import Control standards accelerates European pharmaceutical value chain entry. |
| Closed-Loop Collection Infrastructure | Deposit-return schemes serving South African breweries create captive cullet streams that sustain cost-advantaged furnace economics. |
| Digital Printing Capability Deployment | Ultraviolet-cured coating and laser-etched serialization compress regulatory artwork lead times from weeks to hours for GCC pharmaceutical mandates. |
Research Methodology
Multi-period observation of furnace capacity utilization, soda ash import volumes, and pharmaceutical serialization mandate rollout anchored the trend analysis, supplemented by interviews with plant operations managers, procurement leads at multinational beverage packagers, regulatory affairs directors at GCC health ministries, and technical R&D heads at borosilicate converters. Secondary validation drew from Gulf Standardization Organization technical regulation filings, Egyptian General Organization for Export and Import Control harmonization notices, South African Department of Forestry, Fisheries and the Environment extended producer responsibility enforcement records, and customs data on silica sand and cullet trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Segment-weighting across product type, application, end user, and delivery mode dimensions informed volume and value outputs over the projection horizon. Modeled dimensions included hydrolytic resistance grade, oxygen barrier performance specification, and logistics infrastructure maturity. CAGRs derived from regression against macroeconomic drivers and industry-specific demand elasticities. Forecast inputs incorporated natural gas price subsidy durability, pharmaceutical serialization mandate phase-in schedules, and giga-project hospitality construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under soda ash supply disruption scenarios or abrupt PET substitution acceleration in North African dairy distribution. A model refresh is warranted upon material change in Gulf Standardization Organization technical regulation enforcement intensity or Egyptian industrial zone tax incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Spain Packaging Market