
 Glass Packaging Market | 2026-2036
Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Packaging Market Analysis
Premium-grade pharmaceutical glass is collapsing the boundary between sterile drug containment and cold-chain logistics. Gerresheimer dominates this tier through captive supply of Type I borosilicate tubing for biologics. Owens-Illinois anchors North American beverage demand with furnace-level scale across multiple color specifications. Ardagh Group differentiates through lightweighting R&D that reduces per-unit silica consumption without sacrificing burst strength.
Glass packaging denotes rigid containers formed from silica sand, soda ash, and limestone melted at approximately 1500°C, then shaped by blow molding or press-and-blow techniques to create chemically inert, impermeable vessels. Its primary purpose is to preserve product integrity across food, pharmaceutical, and cosmetic applications while enabling infinite recyclability through cullet reintegration. Bottles command the largest volume share across beverage and pharma end users, though jars gain traction in premium food segments where visual product display commands shelf price premiums. Blow molding leads manufacturing technique adoption for high-speed beverage lines, while narrow neck press methods expand in pharmaceutical applications requiring precise dimensional tolerance for automated filling systems.
The EU Green Deal and REACH chemical safety standards enforce recycled content minimums and restrict heavy-metal colorants in food-contact glass. FDA Type I, II, and III classifications in the United States govern pharmaceutical glass hydrolytic resistance, directly determining which manufacturers qualify for injectable drug contracts. Stakeholders must monitor how diverging national EPR fee structures and carbon border adjustment mechanisms reshape total cost of ownership for exported glass packaging.
Market Dynamics
EU Green Deal mandates on recycled content minimums and carbon border adjustments are compressing margin structures for exporters while rewarding furnace-level investments in cullet preprocessing capabilities.
Growth Catalysts
- REACH chemical safety standards:These ECHA-enforced rules restrict heavy-metal colorants in food-contact glass, accelerating demand for compliant borosilicate alternatives across premium beverage segments.
- Refillable bottle mandates:Germany, France, and Italy enforce extended producer responsibility laws that tighten material specifications and lock in glass over single-use substitutes for spirits and wine.
- Lightweighting R&D:Advanced press-and-blow techniques now reduce per-unit silica consumption without sacrificing burst strength, cutting transport emissions for high-volume beer and soft drink bottlers.
Market Restraints
- Natural gas price volatility:Melting furnaces consume fossil fuel inputs at approximately 1500°C, exposing producers to energy cost spikes that aluminum and PET competitors avoid.
- Silica sand supply concentration:High-purity deposits cluster in specific mining jurisdictions, creating geographic chokepoints for pharmaceutical-grade Type I borosilicate tubing manufacturers.
- Plastic substitution threat:PET bottles with oxygen-scavenging additives now match glass shelf-life performance in non-premium beverage categories at 40% lower unit cost.
Strategic Opportunities
- Cold-chain biologics containment:Type I borosilicate vials with thermal shock resistance are capturing injectable drug contracts as mRNA therapies expand frozen distribution networks.
- India FSSAI packaging regulations:New food-contact material standards favor inert glass over polymer alternatives for spice and ghee segments in organized retail.
- Direct-to-consumer wine channels:E-commerce fulfillment is driving demand for shatter-resistant lightweight bottles with molded pulp protective inserts, bypassing traditional three-tier distribution.
Industry Challenges
- Furnace rebuild cycles:Continuous glass melting operations require 10-15 year capital planning horizons that conflict with quarterly ESG reporting pressures from institutional investors.
- Pharmaceutical glass certification timelines:FDA Type I hydrolytic resistance testing delays new supplier qualification for injectable drug contracts by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Packaging Market |
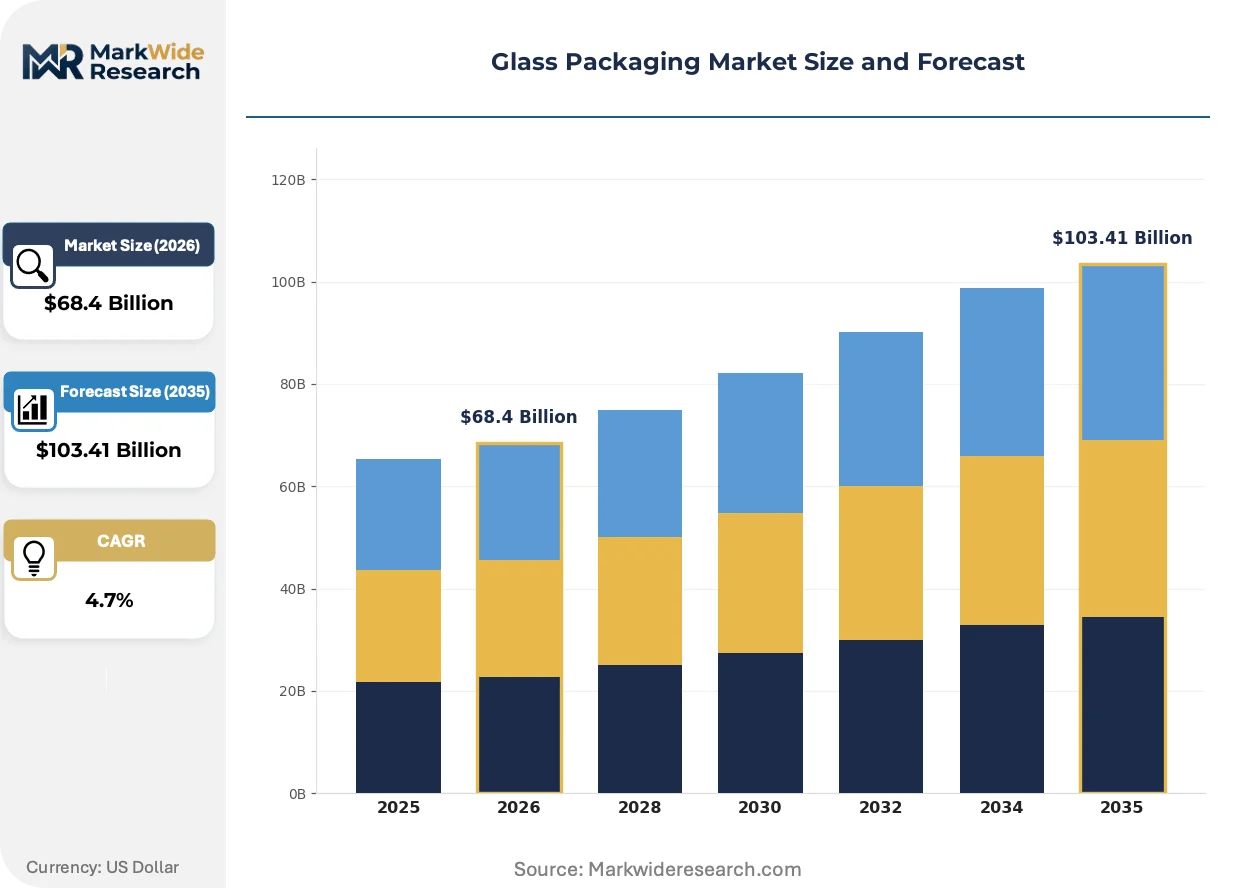
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubes End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Closure Type: Caps, Corks, Flip-tops, Trigger Sprayers Manufacturing Technique: Blow Molding, Press and Blow, Narrow Neck Press, Tubular |
| Companies Covered | Gerresheimer, Amcor, Owens-Illinois, BA Glass, Bormioli Rocco, Ardagh Group, Vitro Packaging, Vetropack, Verallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Packaging Market Emerging Trajectories
Active substitution of legacy materials with engineered glass formulations is compressing traditional competitive boundaries between packaging tiers while regulatory chemistry restrictions accelerate formulation turnover.
Electrochemical refining of cullet is displacing virgin silica dependence for premium container applications. Beverage multinationals in Germany and France now specify 90% post-consumer content for spirits bottles without optical defects. This process is displacing primary sand mining contracts and rewiring raw material procurement toward municipal waste partnerships.
EU F-Gas Regulation phase-down schedules are forcing furnace operators to abandon sulfur hexafluoride refining agents in favor of electric boosting and oxy-fuel combustion. Industrial glassmakers in Italy and Spain face retrofit deadlines that favor greenfield furnace investments over legacy asset upgrades. Pharmaceutical tubing manufacturers respond by consolidating melt capacity near renewable energy grids in Portugal and Denmark.
Consolidated buying by private-label beverage retailers is compressing supplier margins and forcing specification standardization across color and weight categories. German discount chains now mandate uniform 330g wine bottles across multiple SKUs, eliminating brand-specific mold differentiation. This concentration is most visible in private-label sparkling water and table wine segments where shelf price positioning dominates procurement criteria.
Glass Packaging Market Segmentation
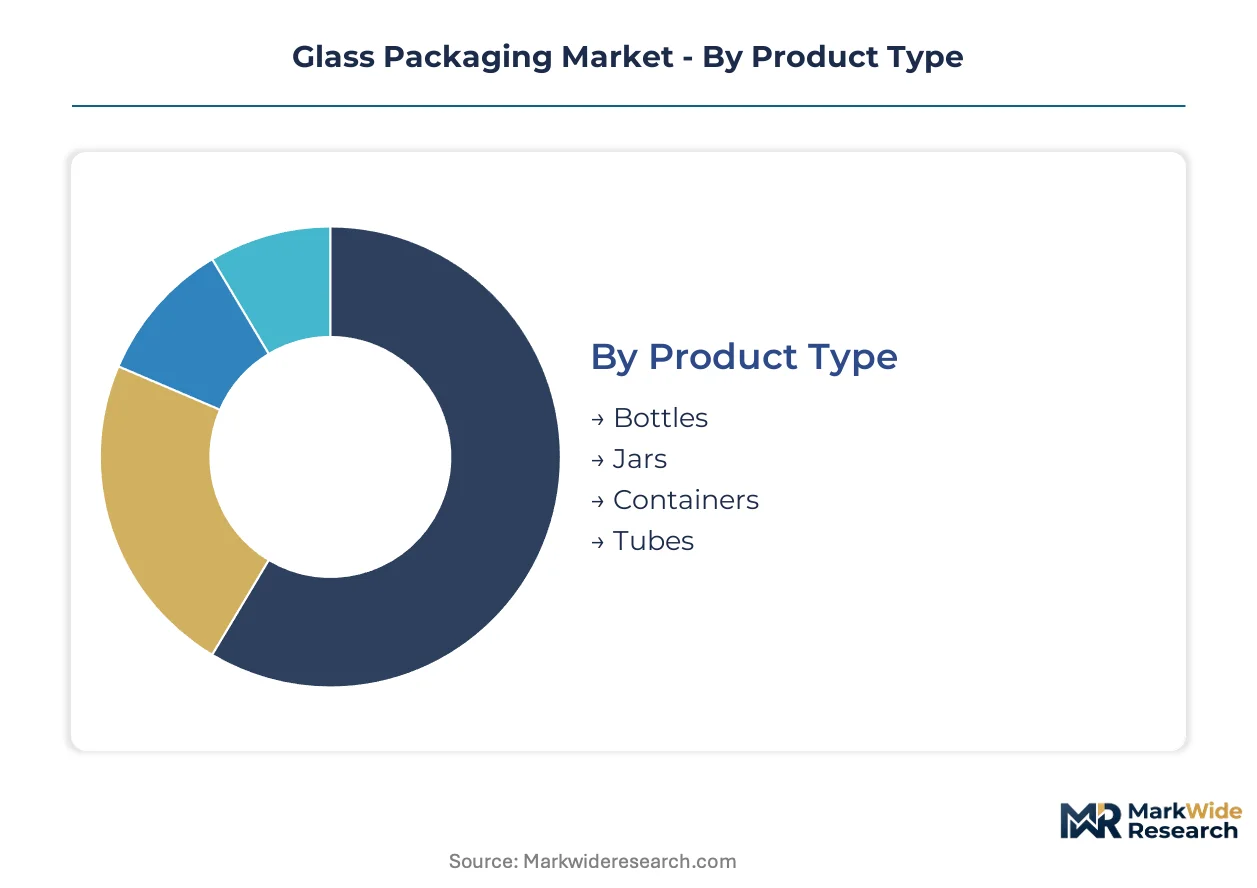
Glass packaging segmentation reveals how substitution pressures concentrate differently across form factors and end-use applications. Understanding these fault lines helps manufacturers prioritize furnace investments and lightweighting R&D where PET and aluminum competition is most acute.
Product Type:
Substitution pressure from PET bottles intensifies unevenly across glass form factors, with beverage-facing segments bearing the heaviest competitive load while pharmaceutical and cosmetic formats retain structural protection through regulatory chemistry requirements.
- Bottles:Formed through blow molding or press-and-blow techniques from soda-lime or borosilicate compositions, these vessels dominate beverage and pharmaceutical containment. Demand concentrates in Germany, France, and Italy where refillable mandates for spirits and wine lock in glass specifications despite PET cost advantages in soft drinks.
- Jars:Wide-mouth containers produced via press-and-blow methods with heavier wall sections for vacuum sealing and thermal processing. Premium food segments in organized retail—artisan preserves, specialty sauces—drive specification tightening as visual product display commands shelf price premiums that polymer alternatives cannot replicate.
- Containers:Rectangular or shaped vessels for bulk food service and institutional pharmaceutical storage. BIS and FSSAI regulations in India favor inert glass for spice and ghee distribution, displacing polymer alternatives in organized retail channels.
- Tubes:Cylindrical formats for pharmaceutical ointments, cosmetic creams, and toothpaste. FDA Type I hydrolytic resistance requirements and EMA sterile barrier standards protect this segment from plastic substitution in dermatological and ophthalmic applications.
Bottles retain volume leadership across the analysis window; tubes hold the steepest expansion curve as biologics containment requirements tighten.
End User:
Cost tier stratification separates commodity beverage procurement from premium pharmaceutical qualification, with margin structures diverging sharply at the furnace level based on certification requirements and batch size economics.
- Food & Beverage:High-volume beer, wine, spirits, and non-alcoholic bottling where lightweighting R&D reduces per-unit silica consumption without sacrificing burst strength. German discount chains now mandate uniform 330g wine bottles across multiple SKUs, compressing supplier margins through specification standardization.
- Pharmaceuticals:Type I borosilicate vials and ampoules for injectable drugs, with thermal shock resistance specifications capturing mRNA therapy contracts as frozen distribution networks expand. Gerresheimer dominates through captive supply of borosilicate tubing for biologics manufacturers.
- Cosmetics:Premium fragrance and skincare packaging where brand differentiation through color, weight, and surface finish commands price premiums. REACH chemical safety standards restrict heavy-metal colorants, accelerating demand for compliant borosilicate alternatives.
- Household:Cleaning product containers and storage vessels facing intense PET competition in non-premium categories. Oxygen-scavenging polymer additives now match glass shelf-life performance at substantially lower unit cost, constraining growth in mass-market segments.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve as sterile drug containment requirements intensify.
Closure Type:
Application-specific sealing performance determines closure selection, with pharmaceutical and premium beverage segments driving specification divergence while commodity categories consolidate toward cost-optimized formats.
- Caps:Screw-thread aluminum or plastic closures for standard beverage and pharmaceutical bottles. ROPP (roll-on pilfer-proof) designs dominate spirits and wine in EU markets with extended producer responsibility laws tightening material specifications.
- Corks:Natural or agglomerated cork for premium wine and spirits, with synthetic alternatives gaining share in price-sensitive segments. Portuguese and Spanish cork producers face consolidation pressure as screw-cap acceptance spreads in New World wine regions.
- Flip-tops:Hinged plastic closures for condiment jars and cosmetic pots, enabling single-handed dispensing. Premium food segments favor glass jar compatibility with molded pulp protective inserts for direct-to-consumer e-commerce fulfillment.
- Trigger Sprayers:Pump mechanisms for household cleaning and cosmetic spray applications, typically paired with blow-molded glass or polymer bottles. Chemical compatibility requirements favor glass in solvent-based formulations.
Caps retain volume leadership; Flip-tops hold the steepest expansion curve as convenience packaging gains share in organized retail.
Manufacturing Technique:
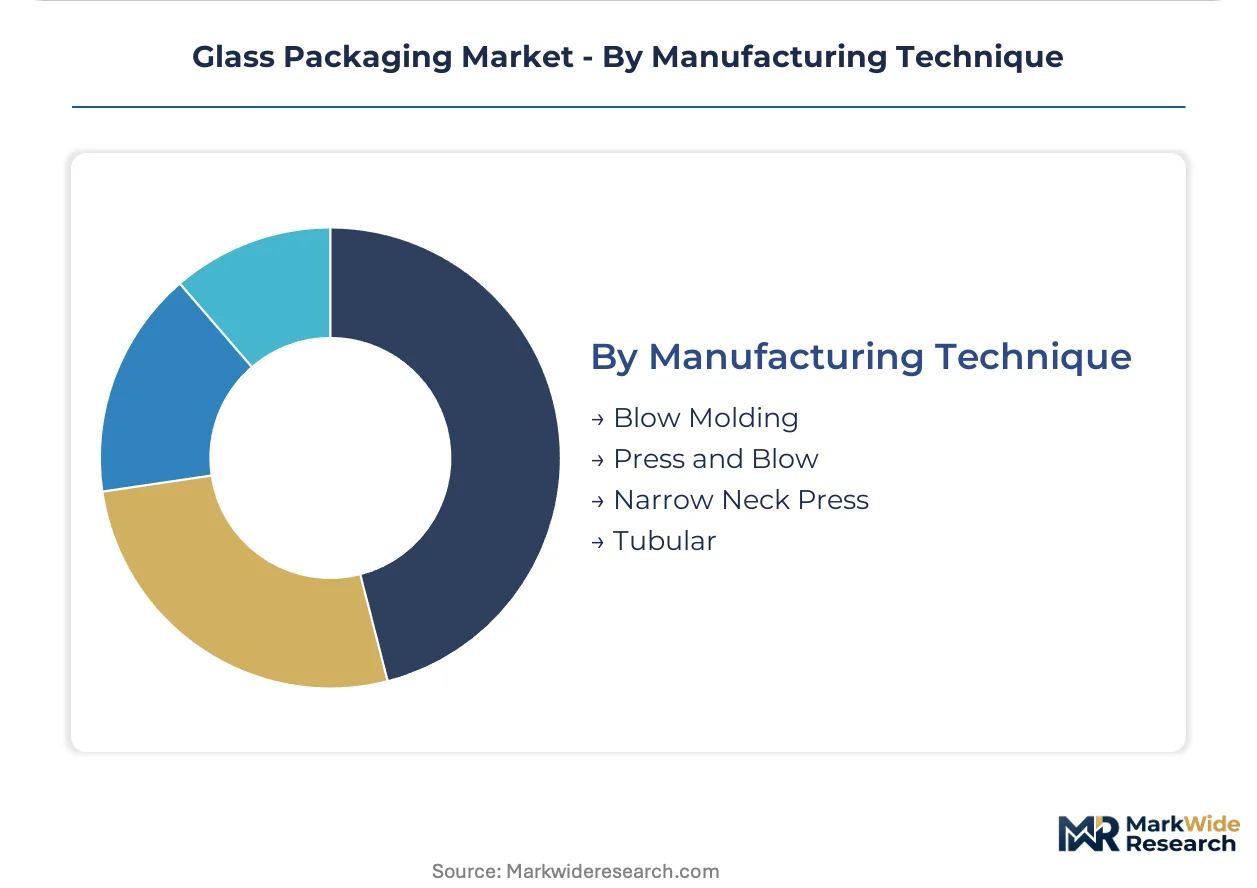
Volume scale and dimensional precision requirements dictate technique selection, with high-speed beverage lines favoring blow molding throughput while pharmaceutical applications demand narrow neck press tolerance for automated filling systems.
- Blow Molding:Compressed air inflation of molten glass parisons for high-speed beverage bottle production. Owens-Illinois anchors North American demand with furnace-level scale across multiple color specifications, achieving output rates that press methods cannot match.
- Press and Blow:Mechanical pressing of parisons followed by blow expansion for jars and wide-mouth containers. Ardagh Group differentiates through lightweighting R&D that reduces per-unit silica consumption without sacrificing burst strength in beer and soft drink applications.
- Narrow Neck Press:Precision pressing for pharmaceutical vials and small-format bottles requiring tight dimensional tolerance. FDA Type I hydrolytic resistance testing delays new supplier qualification by 18-24 months, entrenching incumbent manufacturers.
- Tubular:Continuous drawing of glass tubing for ampoules, vials, and laboratory glassware. Type I borosilicate specifications for biologics containment concentrate supply among manufacturers with captive melt capacity near renewable energy grids in Portugal and Denmark.
Blow Molding retains volume leadership; Tubular holds the steepest expansion curve as cold-chain biologics distribution expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica deposits and furnace infrastructure cluster in Germany, Italy, and the United States, while pharmaceutical-grade borosilicate capacity concentrates near renewable energy grids in Portugal and Denmark. Regulatory chemistry standards and refillable bottle mandates reshape procurement patterns across these supply nodes.
Germany
Extended producer responsibility laws enforce refillable bottle quotas for spirits and wine, locking in glass specifications despite PET cost advantages. ECHA REACH standards restrict heavy-metal colorants, accelerating demand for compliant borosilicate alternatives. The Rhineland industrial corridor hosts furnace-level investments in cullet preprocessing capabilities.
Italy
EU F-Gas Regulation phase-down deadlines force furnace operators to abandon sulfur hexafluoride refining agents. Premium food packaging demand concentrates in Emilia-Romagna, where visual product display commands shelf price premiums that polymer alternatives cannot replicate. Glassmakers face retrofit decisions favoring greenfield investments over legacy asset upgrades.
United States
FDA Type I, II, and III classifications govern pharmaceutical glass hydrolytic resistance, determining supplier qualification for injectable drug contracts. Owens-Illinois anchors North American beverage demand with furnace-level scale across multiple color specifications. Midwest manufacturing clusters supply high-volume beer and soft drink bottlers with lightweighted containers.
France
EU Green Deal recycled content minimums compress margin structures for exporters while rewarding furnace-level investments in cullet preprocessing. Champagne and premium spirits producers specify lightweight borosilicate bottles to meet carbon border adjustment requirements. The Alsace-Lorraine glassmaking region consolidates melt capacity toward electric boosting and oxy-fuel combustion.
India
FSSAI packaging regulations favor inert glass over polymer alternatives for spice and ghee segments in organized retail. BIS standards tighten material specifications for food-contact applications, displacing plastic substitutes in traditional product categories. Gujarat and Maharashtra host expanding container glass capacity serving domestic FMCG distribution networks.
Glass Packaging Market Vendor Landscape
Concentration sits with integrated furnace operators and pharmaceutical tubing specialists who control captive borosilicate supply. Three archetypes dominate: scale-driven beverage container producers with multi-color furnace flexibility, premium pharmaceutical glass specialists with FDA Type I certification pipelines, and regional lightweighting innovators reducing per-unit silica consumption. Competitive dynamics center on M&A consolidation of cullet preprocessing assets and strategic partnerships with municipal waste operators for post-consumer glass feedstock.
Among European specialists, Gerresheimer and Verallia exemplify the premium-tier archetype through positioning around regulatory chemistry requirements. Owens-Illinois represents the scale-driven North American beverage segment. Ardagh Group occupies a position within the lightweighting innovation tier, reflecting R&D focus on burst strength preservation alongside material reduction.
| Leading Market Players |
|---|
| Gerresheimer |
| Amcor |
| Owens-Illinois |
| BA Glass |
| Bormioli Rocco |
| Ardagh Group |
| Vitro Packaging |
| Vetropack |
| Verallia |
| Others |
Supply Flow & Price Mechanics
Furnace-level scale economies in Germany and Italy anchor price floors across European container glass, concentrating supply among operators with cullet preprocessing capabilities while compressing margins for smaller exporters facing carbon border adjustment exposure. Natural gas input costs and high-purity silica sand procurement terms determine competitive positioning across premium pharmaceutical and commodity beverage tiers.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure across glass packaging, separating FDA Type I certified pharmaceutical tubing from commodity beverage containers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with biologics containment commanding substantial premiums over mass-market beer bottles. Cost compression in standard beverage tiers is intensifying because PET substitution with oxygen-scavenging additives matches shelf-life performance at lower unit cost. German discount retail chains exhibit highest price sensitivity through uniform bottle weight mandates, while pharmaceutical biologics manufacturers show lowest sensitivity due to regulatory lock-in.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores energy input risks for furnace operators dependent on liquefied natural gas shipments. Supply concentrates in Germany, Italy, and the United States for container glass, with pharmaceutical-grade borosilicate capacity clustering in Portugal and Denmark near renewable energy grids. Raw material dependencies rest on high-purity silica sand deposits, soda ash from trona mining, and limestone flux. Single-source vulnerability sits with concentrated silica sand jurisdictions for Type I borosilicate tubing. Distribution runs through beverage bottler direct contracts, pharmaceutical OEM captive supply agreements, and retail private-label procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass packaging is entering a cyclical recovery phase as furnace rebuild cycles and ESG capital allocation pressures force capacity rationalization. EU carbon border adjustments and recycled content mandates are compressing marginal supply, tightening effective capacity.
For Market Incumbents: Consolidate cullet preprocessing assets near municipal waste partnerships to secure post-consumer feedstock against emerging competitors. Acquire lightweighting R&D capabilities or pharmaceutical certification pipelines to defend position against PET substitution in beverage tiers and plastic alternatives in mass-market segments. Prioritize furnace investments in Portugal and Denmark where renewable energy grids reduce carbon intensity exposure.
For New Entrants and Emerging Players: Lead with narrow neck press and tubular glass capabilities targeting pharmaceutical biologics containment, where FDA Type I hydrolytic resistance testing creates 18-24 month qualification barriers protecting new suppliers. Target India's FSSAI-regulated spice and ghee segments where organized retail expansion favors inert glass over polymer alternatives. Pursue direct-to-consumer wine fulfillment channels with shatter-resistant lightweight bottles and molded pulp protective inserts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical glass specialists with captive borosilicate melt capacity and FDA Type I certification pipelines over commodity beverage container operators facing PET substitution. Long-term viability across the projection horizon rests on regulatory chemistry requirements tightening rather than loosening for sterile drug containment. Watch for inflection signals in mRNA therapy distribution network expansion and frozen cold-chain infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Preprocessing Partnership | Municipal waste feedstock agreements secure 90% post-consumer content supply for EU Green Deal compliance. |
| Lightweighting R&D Investment | Advanced press-and-blow techniques reduce per-unit silica consumption without sacrificing burst strength specifications. |
| Pharmaceutical Certification Pipeline | FDA Type I hydrolytic resistance qualification captures injectable biologics contracts as mRNA therapies expand. |
| Renewable Energy Grid Relocation | Portugal and Denmark furnace consolidation reduces carbon intensity exposure under EU carbon border adjustments. |
| Direct-to-Consumer Channel Development | E-commerce wine fulfillment with molded pulp inserts bypasses traditional three-tier distribution constraints. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with glass manufacturing executives, pharmaceutical packaging procurement managers, beverage bottler supply chain directors, and municipal waste partnership coordinators; alongside secondary validation through customs and trade data, SEC filings of listed container manufacturers, ECHA REACH substance registrations, and FDA drug master file databases. Bottom-up volume modeling triangulated against top-down value estimates derived from furnace capacity utilization and regional pricing benchmarks.
Across the analysis window, projections integrated product type segmentation by bottles, jars, containers, and tubes; end-user stratification across food and beverage, pharmaceutical, cosmetic, and household applications; and manufacturing technique differentiation between blow molding, press-and-blow, narrow neck press, and tubular methods. CAGRs were derived from regression analysis of historical volume trends against regulatory mandate implementation schedules and substitution elasticity parameters. Forecast inputs incorporated natural gas price volatility scenarios, silica sand supply concentration risk, and pharmaceutical certification timeline delays.
Forecasts assume regulatory continuity in EU Green Deal implementation, FDA Type I classification standards, and India's FSSAI packaging regulations; material policy shifts would require re-modeling across the projection horizon. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms, furnace fuel switching timelines, and biologics distribution network expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Panama Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
India Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Glass Bottle Molds Market