
 Spain Container Glass Market | 2026-2036
Spain Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Container Glass Market Analytics
Modular bottle sizing and customizable decoration bundles is broadening buyer choice across Spanish beverage and cosmetics segments. Verallia Group leverages its Catalonia-based furnace network to sustain high-volume supply to domestic wine exporters. SGD Pharma specializes in molded pharmaceutical vials with borosilicate durability, anchoring its position in drug packaging compliance. Vidrala S.A. competes through container diversity, extending its portfolio across food jars and spirit bottles for private-label clients.
Container glass comprises silica-soda-lime formulations melted at approximately 1,500°C and formed via blow-and-blow or press-and-blow methods to create impermeable, chemically inert vessels for liquid and solid storage. Bottles dominate the product type landscape, absorbing the majority of furnace output for wine, beer, and spirits, while jars command premium margin pools in artisanal food and cosmetics where thick-walled designs and organic print decoration support shelf differentiation. The end use industry segmentation reveals beverages as the volume anchor, though pharmaceuticals generates superior per-unit economics through stringent USP and EP compliance requirements for vial dimensional tolerance.
Spain's packaging sector operates under EU Green Deal circularity mandates and national extended producer responsibility frameworks administered by the Ministry for Ecological Transition, which enforce minimum recycled content thresholds and lightweighting targets. BIS-equivalent Spanish standards for food-contact glass align with EFSA safety protocols, while CE marking requirements govern structural performance claims for pressurized beverage containers. Stakeholders must monitor forthcoming EU packaging regulation revisions that will tighten recycled content mandates and reshape furnace feedstock economics across Iberian glassworks.
Market Dynamics
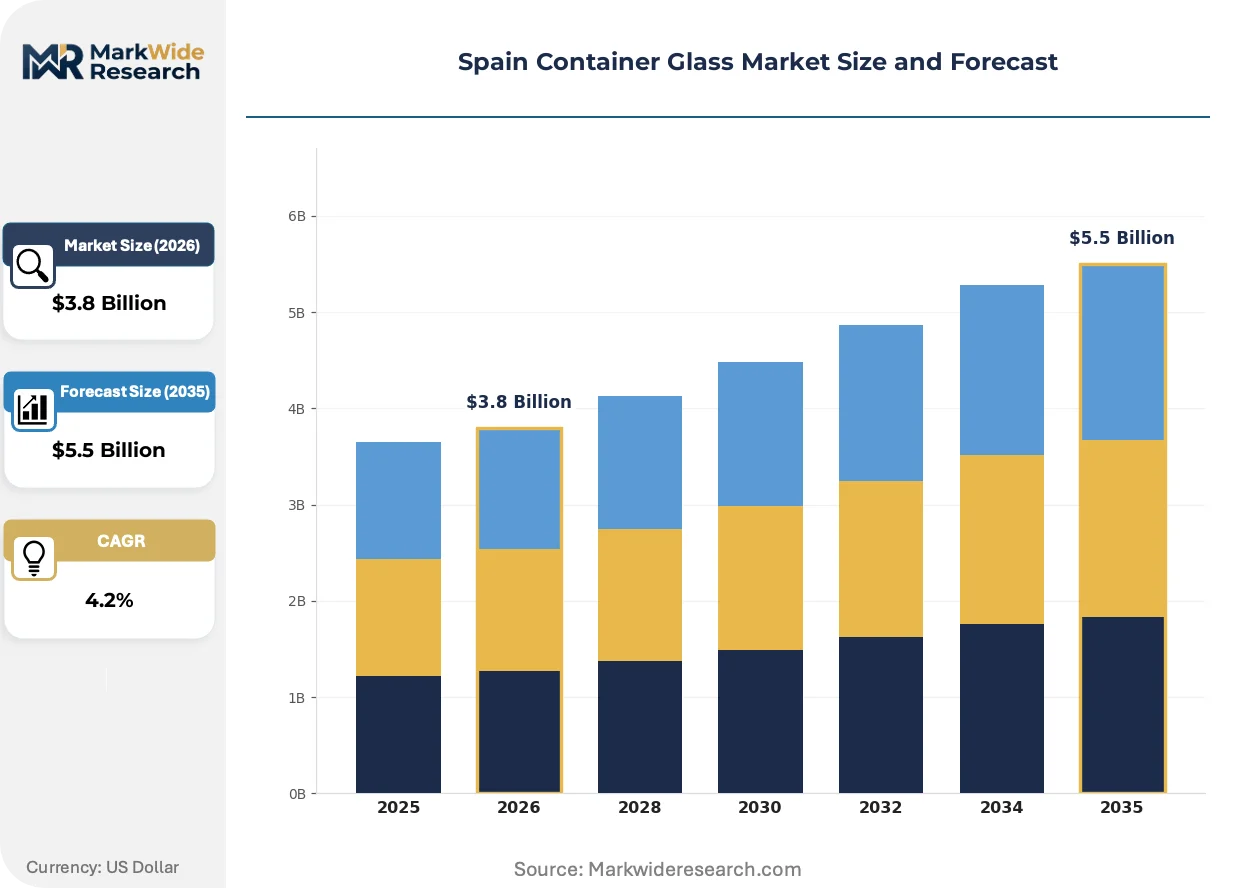
EU Green Deal circularity mandates and Spain's extended producer responsibility frameworks are forcing furnace operators to reconfigure feedstock economics around post-consumer cullet integration and lightweighting targets.
Growth Catalysts
- EU Green Deal recycled content mandates:Binding thresholds for post-consumer cullet in furnace feedstock are accelerating capital deployment toward closed-loop recycling infrastructure.
- Premium wine and spirits decoration demand:Producers in Rioja and Priorat are expanding orders for embossed, organic-print bottles that command shelf differentiation.
- Catalonia logistics corridor concentration:Glassworks clustering near Barcelona's port and rail hub reduce inland freight costs for export-oriented beverage clients.
Market Restraints
- Natural gas price volatility:Furnace operations depend on natural gas for 1,500°C melting, exposing margins to Iberian energy market fluctuations.
- Soda ash supply concentration:Spanish glassworks rely on imported sodium carbonate from Turkey and the United States, creating input cost vulnerability.
- Aluminum can substitution:Beer and soft drink brands are shifting portions of volume to aluminum for logistics efficiency and recycling convenience.
Strategic Opportunities
- Andalusia underpenetration:Southern Spain lacks furnace capacity relative to its growing olive oil and sherry export volumes, creating greenfield potential.
- Pharmaceutical borosilicate vials:CDMO expansion in Madrid and Barcelona is driving demand for USP-compliant molded glass with dimensional precision.
- Lightweighting technology convergence:Integration of laser inspection with predictive furnace control enables thinner-wall designs without strength compromise.
Industry Challenges
- Specialized furnace engineering talent scarcity:Spain's technical institutes produce insufficient graduates in refractory materials and combustion optimization.
- Extended EFSA compliance timelines:New food-contact glass formulations require 18-24 month migration testing before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Container Glass Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End Use Industry: Food, Beverages, Pharmaceuticals, Cosmetics Capacity: Small, Medium, Large, Extra Large Decoration Type: Organic Print, Screen Print, Labels, Coatings |
| Companies Covered | BA Glass Group, SaverGlass Group, Verallia Group, SGD Pharma, Ardagh Group S.A., Vidrala S.A., Gerresheimer AG, Quadpack Industries SA, O-I Glass Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Container Glass Market Evolving Landscape
Digital furnace control and decoration automation are compressing batch changeover times while regulatory pressure on embodied carbon reshapes competitive priorities across Spanish glassworks.
Electrical boosting technology is consolidating hybrid furnace designs that substitute renewable electricity for natural gas combustion. Verallia and Vidrala are retrofitting Catalonia-based furnaces with electrode systems to cut Scope 1 emissions. This shift is consolidating competitive advantage among operators with grid-connected facilities near nuclear and wind generation.
Spain's Ministry for Ecological Transition is enforcing lightweighting targets through extended producer responsibility fee structures that penalize excess packaging mass. Furnace operators must now certify gram-per-milliliter ratios for standard bottle formats. Wine exporters in La Rioja are responding by specifying reduced-weight Bordeaux and Burgundy shapes.
Direct-to-cellar procurement is bypassing traditional distributor networks as medium-sized bodegas aggregate orders through cooperative buying platforms. These digital marketplaces connect Andalusian and Castilian producers directly with furnace scheduling systems. The shift is most visible in Valdepeñas, where private-label spirits brands now contract container volumes in 12-month rolling commitments rather than spot purchases.
Spain Container Glass Market Segmentation
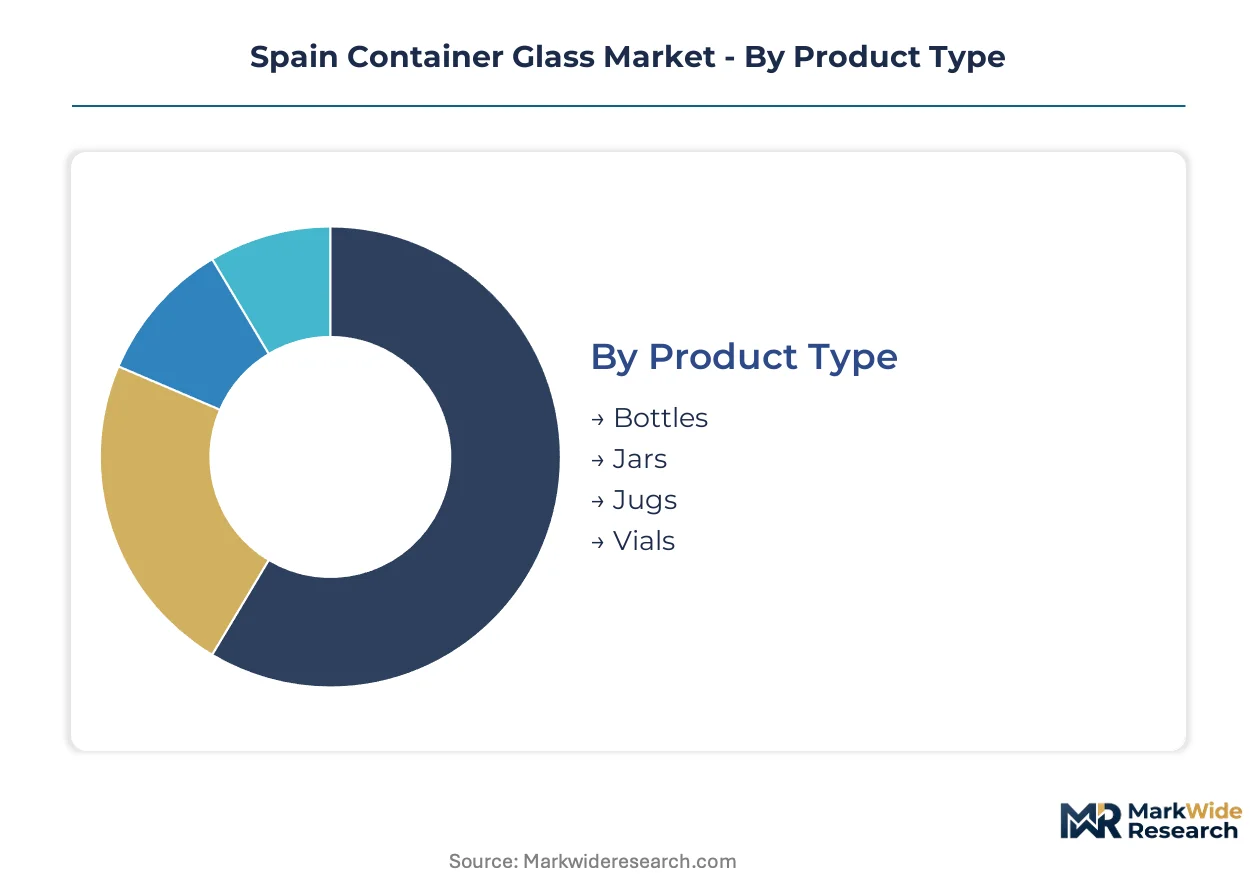
Spain's container glass market fragments across furnace output configurations, decoration technologies, and compliance tiers that determine feedstock allocation and margin capture. Each segmentation axis reveals distinct supply chain pressures from EU Green Deal mandates and export-oriented demand clustering.
Product Type:
Furnace scheduling and mold inventory investments concentrate disproportionately around formats serving Catalonia's beverage export corridor.
- Bottles:Silica-soda-lime formulations formed via blow-and-blow methods dominate furnace output for wine, beer, and spirits. Rioja and Priorat producers drive demand for embossed, reduced-weight Bordeaux shapes that satisfy Ministry for Ecological Transition lightweighting certifications.
- Jars:Thick-walled press-and-blow designs with wide mouths serve artisanal food and cosmetics segments. Catalonia-based glassworks prioritize jar production during Q3 seasonal peaks for preserved olive oil and specialty jam exports.
- Jugs:Reinforced handle-integrated designs for bulk liquid retail. Limited domestic demand restricts jug-dedicated furnace lines to contract manufacturing runs.
- Vials:Borosilicate and soda-lime precision-molded formats for pharmaceutical compliance. Madrid and Barcelona CDMO expansion is tightening USP and EP dimensional tolerance requirements.
Bottles absorb the bulk of installed capacity; vials are expanding most quickly.
End Use Industry:
Margin structures diverge sharply between mass-volume beverage contracts and compliance-heavy pharmaceutical specifications.
- Beverages:Wine, beer, and spirits producers generate the highest furnace tonnage demand. La Rioja bodegas and Andalusian sherry houses specify lightweight decorated formats that reduce EPR fees under Spain's extended producer responsibility framework.
- Pharmaceuticals:USP and EP compliance requirements for molded vials command premium per-unit economics. SGD Pharma's borosilicate specialization anchors this segment's technical barriers.
- Food:Preserved goods and condiment packaging in Catalonia and Andalusia. Olive oil export growth is outpacing regional furnace capacity.
- Cosmetics:Small-batch premium jars with organic print decoration for shelf differentiation. Lower volume but higher decoration value-add per unit.
Beverages command the dominant share of furnace scheduling; pharmaceuticals delivers the steepest margin expansion trajectory.
Capacity:
Logistics economics and EPR fee structures are reshaping order patterns across volume tiers.
- Small:Sub-250ml formats for spirits samples and pharmaceutical unit doses. High mold changeover frequency complicates furnace efficiency.
- Medium:250ml-750ml standard wine and spirits bottles. Valdepeñas cooperative buying platforms aggregate medium-capacity orders through direct-to-cellar procurement.
- Large:750ml-1.5L formats for export wine and premium olive oil. Lightweighting targets bite hardest here as gram-per-milliliter ratios face Ministry certification.
- Extra Large:Above-1.5L bulk and display formats. Niche demand limits dedicated production lines.
Medium capacity handles the majority of batch production; large capacity faces the most intense lightweighting investment pressure.
Decoration Type:
Automation capital deployment and compliance testing timelines differentiate competitive positioning.
- Organic Print:Solvent-free decoration meeting EFSA migration protocols. Priorat and Rioja premium producers specify organic print for export markets requiring 18-24 month compliance documentation.
- Screen Print:High-durability direct surface application for reusable and returnable bottle systems. Verallia's Catalonia furnaces integrate screen print automation with predictive furnace control.
- Labels:Pressure-sensitive and glue-applied paper or polymer substrates. Lower capital barrier enables private-label flexibility for Castilian spirits brands.
- Coatings:Protective and aesthetic surface treatments including UV barrier and frost effects. Emerging demand from cosmetics and premium spirits segments.
Screen print commands the largest installed automation base; organic print is climbing the fastest on regulatory preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Zona Franca tax-incentive regime in Barcelona has concentrated container glass furnace capacity along Catalonia's logistics corridor, drawing feedstock suppliers and decoration specialists into co-located industrial parks.
Catalonia
Wine export demand from Priorat and Penedès drives furnace scheduling for embossed Bordeaux bottles. The Ministry for Ecological Transition enforces lightweighting certifications through extended producer responsibility fee structures. Barcelona's port-rail hub enables direct container loading for Atlantic and Mediterranean shipping routes.
Andalusia
Sherry houses in Jerez and olive oil cooperatives generate unmet container demand exceeding regional furnace capacity. Andalusian authorities administer EU Green Deal circularity mandates through provincial waste management consortia. Sevilla's logistics zone attracts toll-manufacturing arrangements with northern glassworks.
La Rioja
Bodegas specify reduced-weight Burgundy shapes to minimize EPR fees on premium wine exports. Rioja's regional government coordinates with national regulators on food-contact glass compliance documentation. Logroño's industrial estate hosts decoration subcontractors serving cooperative buying platforms.
Madrid
Pharmaceutical CDMO expansion tightens demand for USP-compliant borosilicate vials with dimensional precision. Spain's national pharmaceutical regulator aligns EMA guidelines with domestic manufacturing standards. The Henares Corridor clusters sterile packaging facilities near Barajas air freight terminals.
Valencia
Citrus juice processors and spirits bottlers require medium-capacity formats with seasonal production peaks. Valencian regional authorities implement EU packaging waste directives through municipal collection schemes. Sagunto's port infrastructure supports bulk silica sand import for furnace feedstock.
Spain Container Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's container glass value chain. The market structure tilts toward consolidation among furnace operators with captive cullet recycling networks, while decoration and specialty vial segments retain fragmentation. Two strategic archetypes dominate: integrated glass-ceramic conglomerates with multi-furnace Iberian footprints, and boutique molders serving pharmaceutical compliance niches. Capacity expansion and electrical furnace retrofitting represent the prevailing competitive moves as natural gas volatility reshapes operating economics.
Among Iberian-anchored furnace operators, Verallia Group and Vidrala S.A. occupy positions within the integrated tier, exemplifying scale-driven feedstock consolidation and geographic clustering near Barcelona's logistics hub. SGD Pharma represents the compliance-specialist archetype, anchoring pharmaceutical-grade positioning through borosilicate durability standards. These three entities collectively illustrate the market's bifurcation between volume-scale beverage supply and precision-tolerance medical packaging.
| Leading Market Players |
|---|
| BA Glass Group |
| SaverGlass Group |
| Verallia Group |
| SGD Pharma |
| Ardagh Group S.A. |
| Vidrala S.A. |
| Gerresheimer AG |
| Quadpack Industries SA |
| O-I Glass Inc. |
| Others |
Value Network & Pricing Analysis
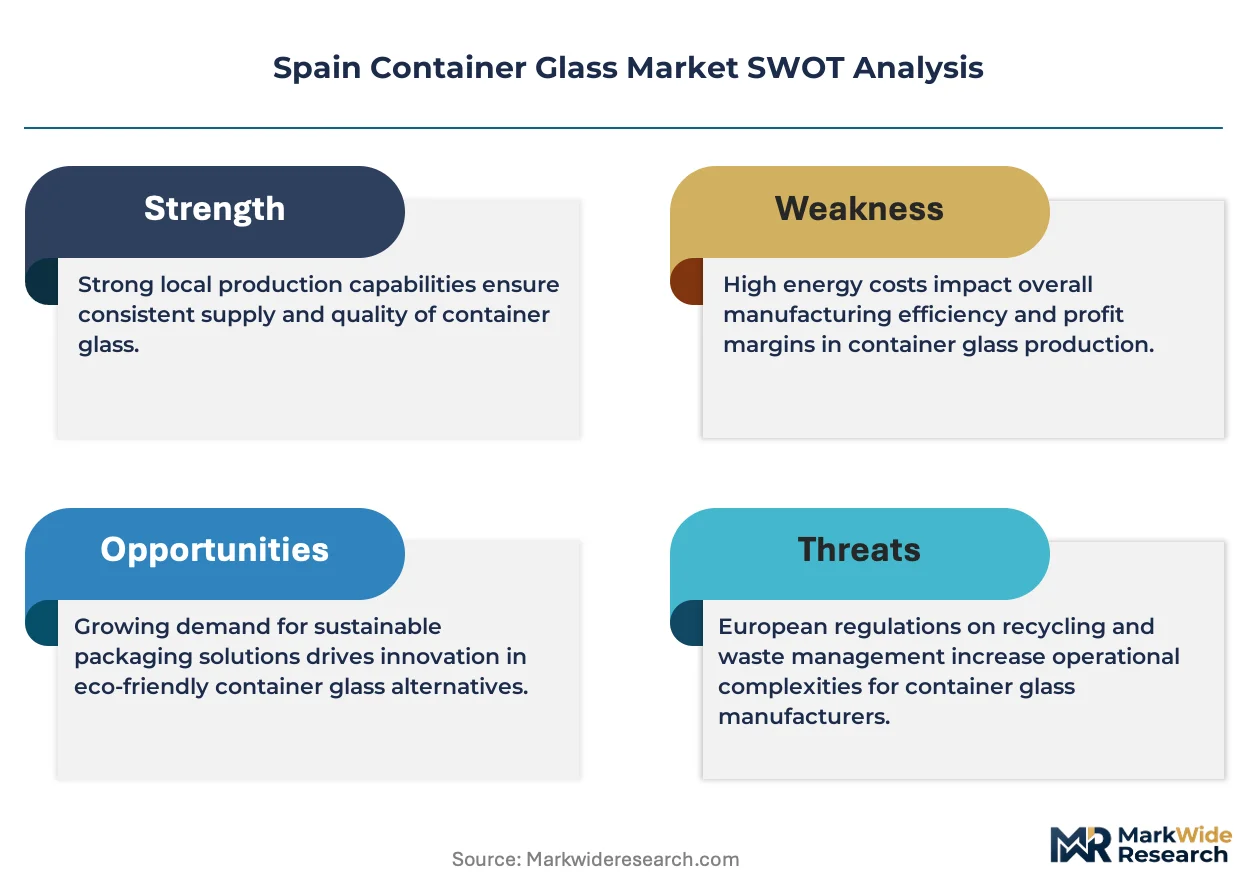
Family-owned mid-cap furnace operators across Castile and León exercise disciplined pricing power through captive cullet recycling networks, while their reliance on Iberian gas spot markets forces cost pass-through negotiations with Rioja bodegas and Catalan exporters.
Pricing Analysis
Margin tightening in medium-capacity wine bottles reflects natural gas cost volatility and Ministry for Ecological Transition lightweighting certification requirements. Contract-based long-term offtage dominates, with price differentiation hinging on EPR fee avoidance through gram-per-milliliter optimization and organic-print decoration tiering. Cost-down pressure accelerates as aluminum can substitution erodes beer segment volume. Private-label spirits brands in Valdepeñas exhibit highest price sensitivity; pharmaceutical vial buyers prioritize USP compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Turkish and United States soda ash suppliers, exposing Spanish glassworks to input cost shocks and maritime logistics disruptions. Feedstock concentration draws from Turkey, the United States, and domestic post-consumer cullet streams. Raw material dependencies center on sodium carbonate, silica sand from Sagunto imports, and borosilicate precursors for pharmaceutical grades. Tariff exposure on Turkish soda ash represents the dominant structural risk. Distribution runs through Barcelona's port-rail hub for Atlantic and Mediterranean export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive cullet recycling infrastructure and electrical furnace retrofitting determine who captures margin from EU Green Deal mandates.
For Market Incumbents: Anchor market position through backward integration into closed-loop cullet collection networks across Catalonia and La Rioja, while accelerating electrode-based furnace retrofits to offset Iberian gas price volatility. Aluminum can substitution in beer packaging demands defensive capacity reallocation toward pharmaceutical borosilicate vials. For New Entrants and Emerging Players: Begin with toll-manufacturing arrangements in Andalusia, where olive oil and sherry export growth outpaces regional furnace capacity. Direct-to-cellar procurement platforms in Valdepeñas offer the most penetrable entry channel, with lightweighting certification as the critical go-to-market credential. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap decoration specialists with organic-print compliance capabilities in La Rioja and Priorat supply zones. Long-term viability hinges on electrical furnace technology maturity and grid-connected renewable access. Watch for natural gas price inflection as the signal triggering consolidation among gas-dependent furnace operators.| Strategic Initiative | Industry Significance |
|---|---|
| Electrical Furnace Retrofitting | Verallia and Vidrala deploy electrode systems to cut Scope 1 emissions near Barcelona's nuclear and wind grid. |
| Closed-Loop Cullet Integration | Extended producer responsibility mandates force feedstock reconfiguration toward post-consumer glass recovery. |
| Lightweighting Technology Investment | Laser inspection with predictive furnace control enables thinner-wall designs without strength compromise. |
| Pharmaceutical Vial Capacity Expansion | CDMO growth in Madrid and Barcelona tightens USP-compliant borosilicate supply. |
| Direct-to-Cellar Procurement Platforms | Digital marketplaces bypass distributor networks, aggregating cooperative orders from Castilian and Andalusian producers. |
Research Methodology
Multi-period observation of furnace output tonnage, EPR fee structures, and electrical retrofitting capex anchored the trend analysis, supplemented by interviews with glassworks plant managers, Rioja bodega procurement leads, pharmaceutical CDMO supply chain directors, and Ministry for Ecological Transition regulatory officers. Secondary validation drew from EU Green Deal implementation reports, EFSA food-contact migration testing documentation, Spanish customs trade data, and SEC filings of listed container glass producers. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Segment-weighting across product type, end-use industry, capacity tier, and decoration technology informed the analytical framework. CAGRs were derived from installed furnace capacity utilization trajectories, lightweighting adoption curves, and pharmaceutical packaging demand elasticity. Forecast inputs incorporated natural gas price scenario modeling and EU packaging regulation revision timelines.
Iberian energy market dislocation, EFSA compliance timeline extensions, and aluminum substitution acceleration in beverage packaging are the dominant revision risks. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market