
 Amber Glass Packaging Market | 2026-2036
Amber Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Amber Glass Packaging Market Outlook
Pharmaceutical buyer concentration is pivoting toward consolidated contract manufacturers with multi-year supply agreements. Owens-Illinois leverages its North American furnace network to anchor high-volume amber bottle production for generic drug distributors. Gerresheimer AG competes through specialized molded glass expertise for injectable vials, while SGD Pharma dominates European demand for Type III amber glass used in oncology formulations.
Amber glass packaging consists of soda-lime silica glass doped with iron, sulfur, and carbon to achieve UV absorption below 450 nm, protecting photosensitive contents from degradation. Manufacturers employ the blow-and-blow or press-and-blow process to form containers with wall thickness ranging from 2 mm to 6 mm depending on pharmaceutical stability requirements. The bottles segment leads volume due to oral solid dosage demand, though vials command premium margins from biologic drug compatibility requirements. Food and beverage applications in craft beer and cold-pressed oils represent the fastest-expanding end-user channel as brands adopt UV-blocking claims for shelf differentiation.
FDA's container closure guidance and the EU MDR's material traceability mandates compel amber glass producers to maintain batch-level cobalt and iron oxide documentation. Germany's BfArM and France's ANSM enforce pharmacopeial compliance for glass delamination resistance, filtering smaller molders from approved supplier lists. Stakeholders must monitor how USP Type I borosilicate substitution and recycled content mandates from the EU Green Deal reshape raw material sourcing economics.
Market Dynamics
Pharmaceutical procurement consolidation is compressing supplier margins while elevating batch-level traceability requirements for iron and sulfur oxide documentation across European and North American supply chains.
Growth Catalysts
- EU MDR material traceability mandates:Device manufacturers in Germany and France now require cobalt oxide batch records for every amber vial shipment, locking in multi-year supplier contracts.
- Light-sensitive biologic formulations:Oncology drug developers specify Type III amber glass for monoclonal antibody stability, creating dedicated furnace allocations at specialized molders.
- Rhineland-Palatinate manufacturing cluster:Proximity to pharmaceutical corridors in Frankfurt and Basel reduces logistics costs for just-in-time bottle deliveries.
Market Restraints
- Natural gas price volatility:Furnace operations in Germany face input cost swings that erode margin predictability for high-volume amber bottle runs.
- Concentrated soda ash supply:European producers depend on Turkish and Bulgarian suppliers for sodium carbonate, exposing production schedules to geopolitical disruption.
- USP Type I borosilicate substitution:Injectable drug manufacturers in Switzerland and the Netherlands are qualifying clear borosilicate with UV-absorbing sleeves for premium oncology applications.
Strategic Opportunities
- India CDMO expansion:Contract manufacturers in Hyderabad and Ahmedabad are qualifying amber glass for export formulations targeting EU and US markets.
- Craft beer UV-blocking claims:Cold-pressed oil and small-batch brewers in the US Pacific Northwest adopt amber bottles for shelf differentiation against clear glass competitors.
- EU Green Deal recycled content mandates:Post-consumer cullet integration targets create first-mover advantage for furnace operators investing in optical sorting technology.
Industry Challenges
- Pharmacopeial glass delamination testing:BfArM and ANSM enforcement of surface durability protocols extends qualification timelines for new mold designs by 8-14 months.
- Specialized furnace engineering talent:Germany's glass manufacturing workforce faces retirement-driven attrition in combustion optimization and thermal control disciplines.
- Legacy ERP traceability gaps:Mid-tier molders struggle to integrate batch-level cobalt documentation into existing quality management systems for MDR compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amber Glass Packaging Market |
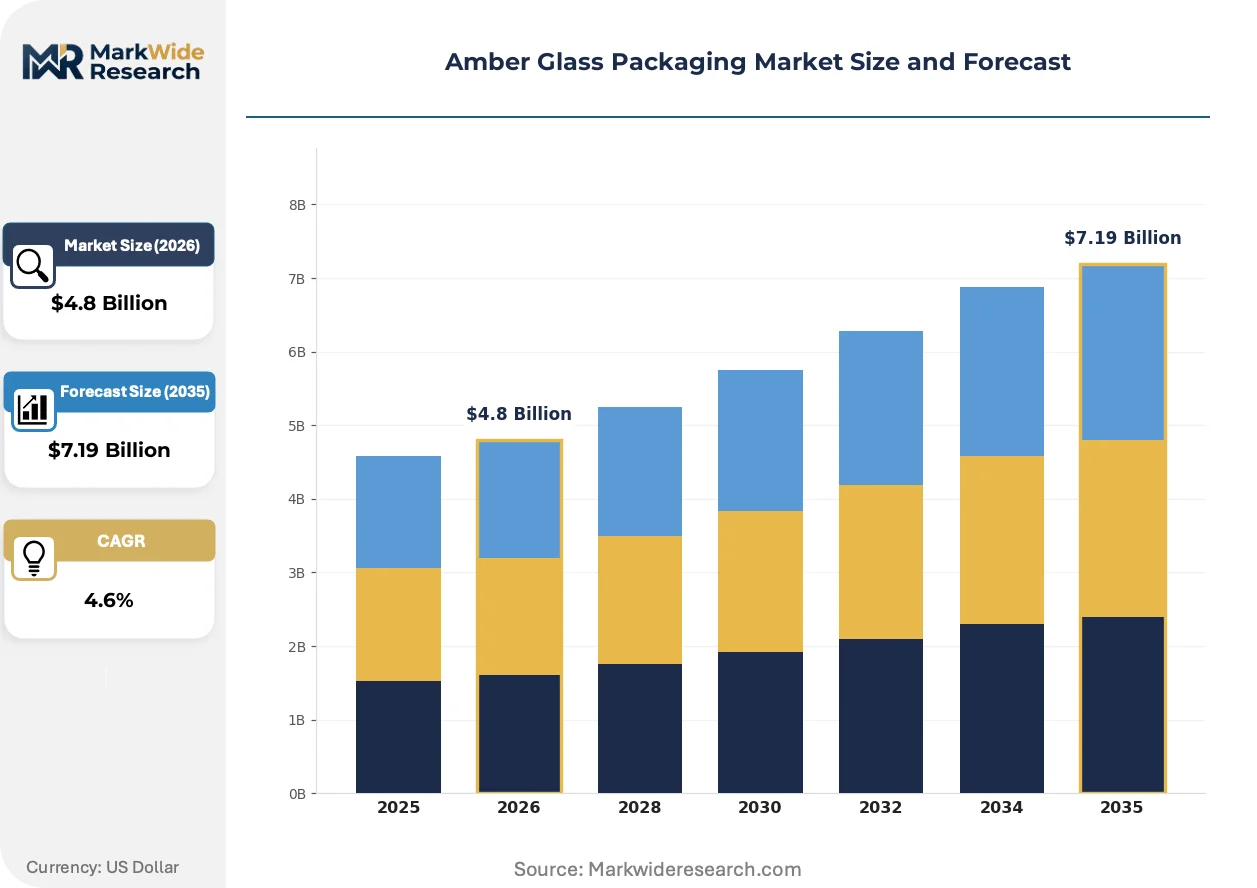
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
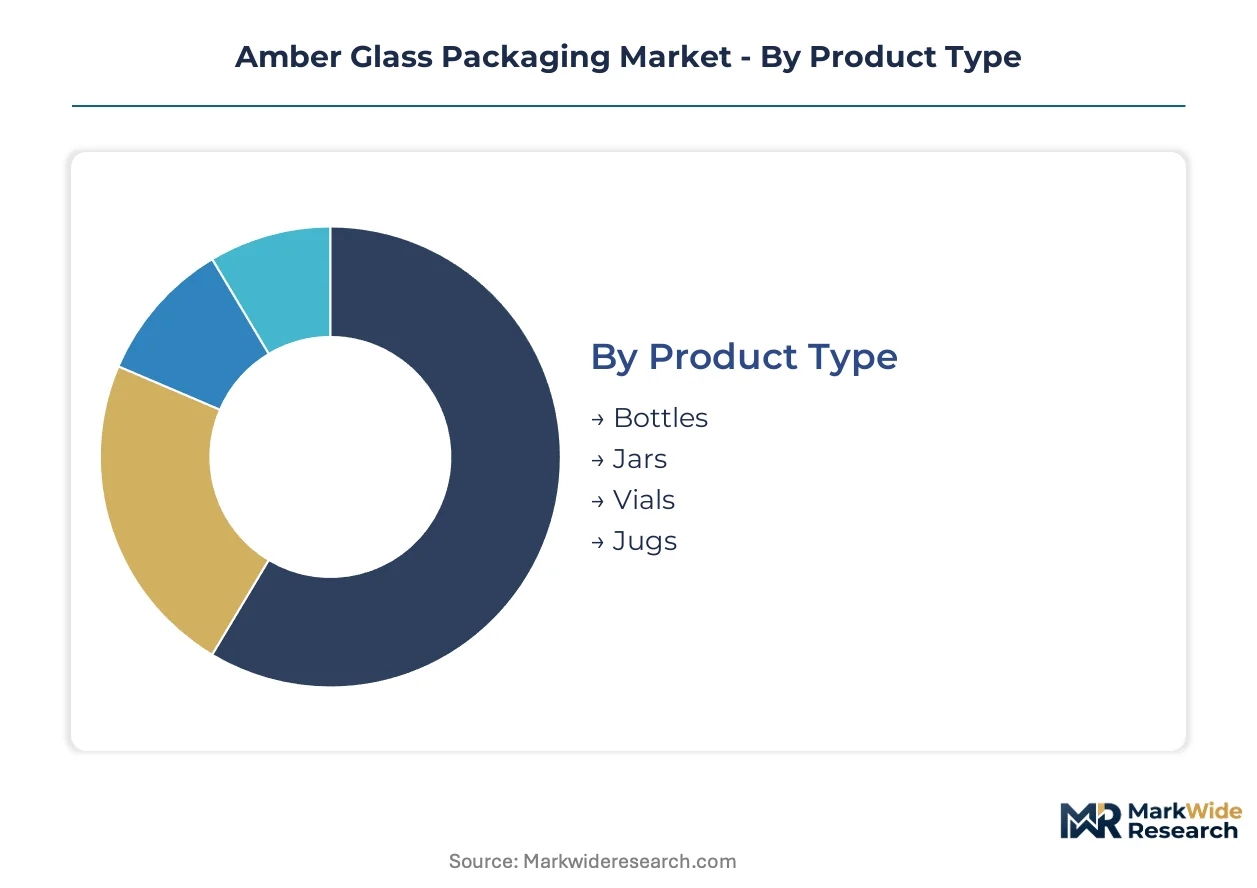
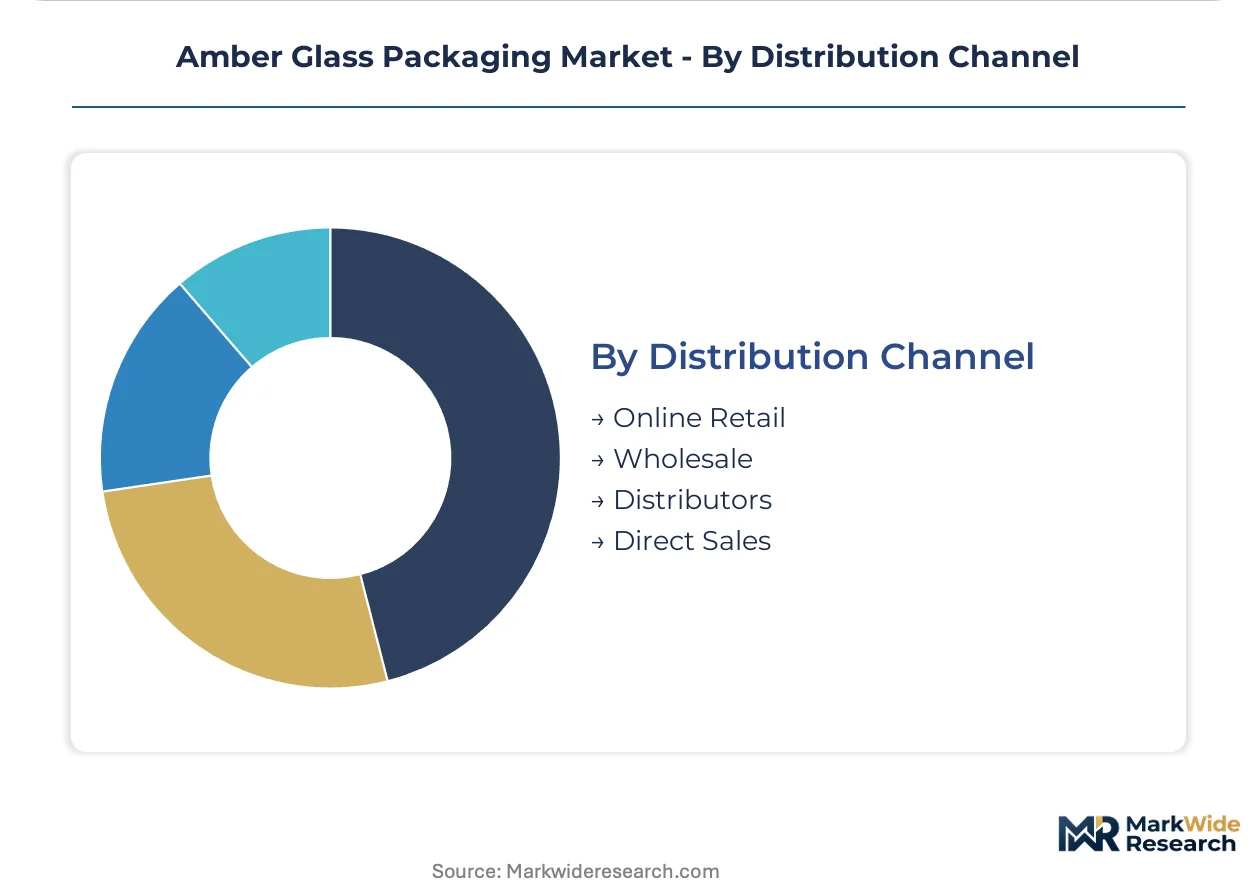
| Segmentation | Product Type: Bottles, Jars, Vials, Jugs End User: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals Capacity: 30ml, 100ml, 250ml, 500ml Distribution Channel: Online Retail, Wholesale, Distributors, Direct Sales |
| Companies Covered | Ardagh Group, Owens-Illinois, Gerresheimer AG, Schott AG, Piramal Glass, Verallia, SGD Pharma, Stölzle Glass Group, Vitro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amber Glass Packaging Market Strategic Shifts
Digital furnace control and automated optical inspection are compressing defect rates while enabling real-time sulfur oxide dosing adjustments for consistent UV absorption profiles.
Laser-induced breakdown spectroscopy is converging with inline quality systems to verify iron and carbon dopant concentrations at production speed. SGD Pharma and specialized German molders are deploying this technology for oncology vial lines where pharmacopeial compliance is non-negotiable. The convergence is compressing laboratory testing cycles from days to minutes, enabling just-in-release logistics for contract manufacturers.
France's ANSM and Germany's BfArM are harmonizing glass delamination resistance testing protocols under revised pharmacopeial standards. The alignment forces dual-qualified suppliers to maintain parallel documentation systems during transition periods. Injectable drug packagers in the Basel corridor face the steepest compliance burden as they serve both regulatory regimes simultaneously.
Buyer concentration among consolidated CDMOs is displacing fragmented procurement across small generic distributors. Three-year master service agreements with volume commitments now dominate sourcing for oral solid dosage bottles. The shift is most visible in Germany's pharmaceutical packaging corridor, where Owens-Illinois and Gerresheimer compete for exclusive furnace allocations tied to forecasted biologic pipeline launches.
Amber Glass Packaging Market Segmentation
Pharmaceutical procurement teams segment amber glass by UV protection performance and pharmacopeial compliance tiers. Cosmetic and food brands prioritize shelf differentiation through color intensity and bottle geometry rather than regulatory documentation.
Product Type:
Pharmaceutical buyers differentiate containers by sterilization compatibility and closure system integration rather than base material alone.
- Bottles:Soda-lime silica construction with 2-4mm wall thickness accommodates oral solid dosage forms. Germany's Rhineland-Palatinate cluster supplies high-volume runs for generic drug distributors facing MDR traceability mandates.
- Vials:Type III molded glass with controlled iron oxide dosing protects monoclonal antibodies from photodegradation below 450nm. Oncology formulation demand in France's pharmaceutical corridor commands dedicated furnace allocations and premium batch documentation.
- Jars:Wide-mouth configurations suit topical creams and ointments requiring spatula access.
- Jugs:Higher capacity formats serve chemical reagent and industrial laboratory supply chains.
Volume sits with bottles; growth tilts toward vials.
End User:
Regulatory burden intensity separates customer tiers more sharply than order volume or price sensitivity.
- Pharmaceuticals:FDA container closure guidance and EU MDR material traceability requirements enforce cobalt oxide batch records for every shipment. German and French manufacturers now require three-year master service agreements with volume commitments.
- Food & Beverage:Craft beer and cold-pressed oil brands in the US Pacific Northwest adopt amber glass for UV-blocking shelf claims against clear glass competitors. This channel climbs the fastest as wellness positioning drives packaging premiumization.
- Cosmetics:Serum and essential oil formulations leverage amber tint for ingredient stability signaling and brand aesthetic differentiation.
- Chemicals:Laboratory reagent suppliers specify wall thickness and thermal shock resistance for autoclave compatibility.
Revenue concentrates in pharmaceuticals; margin expansion favors food and beverage.
Capacity:
Unit economics and logistics optimization drive procurement patterns across volume tiers.
- 100ml:Mid-range capacity dominates oral liquid dosage and cosmetic serum applications. Contract manufacturers in Hyderabad and Ahmedabad qualify this format for export formulations targeting EU pharmacopeial compliance.
- 30ml:Compact format aligns with injectable and high-value biologic stability requirements. Swiss and Dutch oncology developers specify this capacity for monoclonal antibody presentations requiring Type III glass delamination resistance.
- 250ml:Standard for multi-dose pharmaceutical liquids and premium culinary oils.
- 500ml:Bulk format serves chemical reagent and institutional food service channels.
Procurement frequency peaks at 100ml; qualification complexity steepens below 50ml.
Distribution Channel:
Traceability requirements and order fragmentation reshape channel economics for amber glass suppliers.
- Direct Sales:Pharmaceutical manufacturers with dedicated quality teams negotiate furnace allocations and batch-level cobalt documentation. Owens-Illinois and Gerresheimer compete for exclusive supply agreements tied to biologic pipeline launches.
- Distributors:Regional medical supply networks aggregate fragmented generic drug packaging demand across Central and Eastern Europe.
- Wholesale:Food and beverage brands access standardized bottle geometries through packaging wholesalers serving craft production clusters.
- Online Retail:Small-batch cosmetic and home-apothecary suppliers source limited quantities through digital procurement platforms.
Contract value aggregates through direct sales; customer acquisition costs favor distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soda ash deposits in Turkey and Bulgaria anchor European amber glass supply chains, while furnace networks in Germany and France process these inputs into pharmacopeial-grade containers. Natural gas pricing volatility and regulatory tightening across the EU MDR framework are reshaping regional production economics.
Germany
Pharmaceutical manufacturers in Frankfurt and the Rhineland-Palatinate cluster drive amber bottle procurement for light-sensitive generics. BfArM enforces pharmacopeial glass delamination resistance protocols that filter smaller molders from approved supplier lists. Gerresheimer AG anchors specialized molded glass capacity for injectable vials serving oncology formulations.
France
Oncology drug developers in the Paris-Saclay corridor specify Type III amber glass for monoclonal antibody stability requirements. ANSM harmonizes testing protocols with German counterparts under revised pharmacopeial standards. SGD Pharma dominates furnace allocations for premium vial production with batch-level cobalt documentation.
United States
Generic drug distributors and craft brewers in the Pacific Northwest sustain dual-channel amber glass demand. FDA container closure guidance mandates batch-level traceability for iron oxide doping concentrations. Owens-Illinois leverages its North American furnace network to anchor high-volume production for consolidated contract manufacturers.
India
CDMOs in Hyderabad and Ahmedabad qualify amber glass formats for export formulations targeting EU pharmacopeial compliance. CDSCO oversight of pharmaceutical packaging materials intensifies documentation requirements for cobalt and sulfur oxide batch records. Contract manufacturers invest in furnace partnerships to secure dedicated capacity for biologic pipeline launches.
Switzerland
Injectable drug packagers in the Basel corridor serve both German and French regulatory regimes simultaneously. Swissmedic enforcement of dual-qualified supplier documentation creates compliance burdens during pharmacopeial transition periods. Oncology developers here qualify USP Type I borosilicate with UV-absorbing sleeves as amber glass alternatives for premium applications.
Amber Glass Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized pharmacopeial certifications and recycled content integration. The vendor base concentrates around furnace-owning conglomerates with multi-continental footprints and mid-tier molders serving regional pharmaceutical corridors. Strategic archetypes include scale-driven volume producers, specialized oncology-grade specialists, and sustainability-focused cullet integrators. Dominant competitive moves span exclusive furnace allocation contracts with CDMOs and optical sorting technology investments for EU Green Deal compliance.
Among European specialists, Gerresheimer AG and SGD Pharma exemplify the pharmacopeial-grade archetype through dedicated oncology vial production and batch-level documentation capabilities. Owens-Illinois occupies a position as the North American scale anchor, leveraging furnace network breadth for generic drug distributor consolidation. Stölzle Glass Group represents the mid-tier regional specialist model, serving fragmented cosmetic and food-grade demand across Central European production clusters.
| Leading Market Players |
|---|
| Ardagh Group |
| Owens-Illinois |
| Gerresheimer AG |
| Schott AG |
| Piramal Glass |
| Verallia |
| SGD Pharma |
| Stölzle Glass Group |
| Vitro |
| Others |
Value Chain & Pricing Dynamics
Consolidated contract manufacturers with multi-year master service agreements command tiered pricing leverage, compressing margins for high-volume amber bottle runs while preserving premium capture for specialized oncology vial production.
Pricing Analysis
Volume concentrates in oral solid dosage bottles where per-unit transactional pricing faces compression from procurement consolidation, while vial margins expand on pharmacopeial certification premiums and batch-level cobalt documentation. Price differentiation hinges on EU MDR compliance tier and furnace allocation exclusivity. Pricing pressure stems from natural gas cost volatility eroding predictability for German furnace operators. Generic drug distributors exhibit highest price sensitivity; oncology developers accept premium positioning for delamination-resistant Type III glass.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle consolidated CDMO demand with dedicated furnace allocations, while distributor networks aggregate fragmented generic packaging orders across Central Europe. Supply concentrates in Germany's Rhineland-Palatinate cluster and France's pharmaceutical corridor, with soda ash sourcing anchored in Turkish and Bulgarian deposits. Raw material dependencies encompass sodium carbonate, iron oxide dopants, and cobalt oxide for UV absorption. Single-source vulnerability in soda ash exposes production schedules to geopolitical disruption. Distribution runs through three-tier structures: direct sales for traceability-intensive buyers, regional medical distributors, and packaging wholesalers serving food-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU MDR material traceability mandates erect formidable barriers to entry, rewarding incumbents with established batch-documentation infrastructure and filtering undercapitalized molders from approved supplier lists.
For Market Incumbents: Anchor furnace allocations through exclusive three-year agreements with CDMOs launching biologic pipelines, locking in volume commitments before USP Type I borosilicate substitution gains traction in Swiss and Dutch injectable markets. Invest in laser-induced breakdown spectroscopy for real-time cobalt verification to compress release cycles and defend against mid-tier competitors struggling with legacy ERP traceability gaps.
For New Entrants and Emerging Players: Small-batch craft brewers and cold-pressed oil brands in the US Pacific Northwest represent the most penetrable buyer archetype, as these wellness-positioned segments prioritize UV-blocking shelf claims over pharmacopeial documentation. Pursue optical sorting technology partnerships to qualify for EU Green Deal recycled content mandates, creating differentiation against furnace-constrained incumbents.
For Investors and Strategic Acquirers: The window for entry favors specialized molders with pharmacopeial certifications and captive cullet integration capabilities, as regulatory tightening and sustainability mandates accelerate consolidation. Monitor German BfArM and French ANSM harmonization timelines as inflection indicators for compliance burden shifts that will strain dual-qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Deployment | Enables EU Green Deal recycled cullet integration targets ahead of furnace-constrained competitors. |
| Exclusive Furnace Allocation Contracts | Locks CDMO volume commitments for biologic pipeline launches against borosilicate substitution threats. |
| Laser-Induced Breakdown Spectroscopy Integration | Compresses cobalt documentation cycles from days to minutes for MDR-compliant just-in-release logistics. |
| Backward Integration into Soda Ash Sourcing | Reduces Turkish and Bulgarian supply concentration risk for furnace operators facing gas price volatility. |
| Pharmacopeial Dual-Qualification Investment | Positions suppliers for BfArM-ANSM harmonized testing protocols serving Basel corridor packagers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with furnace operations managers, pharmaceutical packaging procurement leads, CDMO supply chain directors, and glass delamination testing laboratory heads. Secondary sources encompassed EU MDR implementation guidance, FDA container closure guidance documents, BfArM pharmacopeial standards, ANSM inspection protocols, and soda ash trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-user vertical, capacity tier, and distribution channel dimensions.
Data-stream reconciliation connected furnace capacity utilization metrics with pharmaceutical pipeline launch announcements and CDMO contract award disclosures across the projection horizon. Segmentation modeling incorporated product format, regulatory compliance tier, end-use application, and geographic production cluster. CAGRs derived from trend-line analysis of historical volume trajectories, adjusted for regulatory implementation timelines and substitution elasticity parameters. Forecast inputs included natural gas price scenario curves, biologic drug approval velocity indices, and recycled content mandate compliance cost estimates.
Revisions become necessary when EU MDR enforcement intensity shifts, soda ash supply disruptions materialize, or USP Type I borosilicate substitution accelerates beyond modeled penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Mason Jars Market