
 Congo Container Glass Market | 2026-2036
Congo Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Congo Container Glass Market Insights
Beverage bottlers is bifurcating demand away from informal traders toward formal sector buyers with certified supply chains. Beta Glass plc leverages its West African manufacturing footprint to serve Congo through regional distribution networks. Hongxing Glass Congo SARL anchors local production capacity with furnace operations positioned near raw material sources. O-I Glass, Inc. competes through technical assistance programs that transfer blow molding expertise to African bottling partners.
Container glass denotes soda-lime silica vessels formed through blow molding or press-and-blow processes, typically comprising silica sand, soda ash, and limestone with thermal shock resistance between 40-60°C for standard amber and flint grades. The material serves as the primary barrier packaging for carbonated beverages, injectable pharmaceuticals, and cosmetic formulations requiring inert, impermeable, and recyclable containment. Bottles dominate volume throughput in the beverage sector, while jars capture margin concentration in pharmaceutical and cosmetics applications where amber glass and narrow-neck specifications command quality premiums. Blow molding technology leads unit economics for high-speed beverage lines, though press-and-blow methods gain traction in pharmaceutical containers requiring precise neck finish tolerances.
The country's national standards body enforces food-contact material certifications that restrict lead and cadmium migration limits in container glass surfaces, while the central bank's foreign exchange regulations shape import timing for soda ash and specialized colorants. BIS-aligned technical committees in neighboring jurisdictions indirectly influence Congo through regional trade harmonization pressures on packaging safety protocols. Stakeholders must monitor furnace energy costs and silica sand beneficiation capacity as determinants of local versus imported supply competitiveness.
Market Dynamics
Kinshasa's brewing clusters are scaling output and demanding certified returnable glass packaging, forcing converters to upgrade furnace capacity and secure soda-lime certifications under tightening national standards.
Growth Catalysts
- Returnable bottle mandates:Beverage bottlers in Kinshasa and Lubumbashi are expanding procurement of multi-trip glass containers to reduce per-unit packaging costs and meet corporate sustainability targets.
- Food-contact certification tightening:The country's national standards body is enforcing stricter lead and cadmium migration limits, pushing informal converters toward certified soda-lime compositions and formal sector supply chains.
- Pharmaceutical packaging expansion:Injectable drug manufacturers in Lubumbashi are increasing amber glass demand for light-sensitive formulations, creating premium volume anchors beyond beverages.
Market Restraints
- Soda ash import dependency:The central bank's foreign exchange regulations create timing volatility for soda ash and specialized colorant shipments, compressing furnace run schedules.
- Silica sand beneficiation gaps:Local sand deposits require washing and iron reduction processing that domestic capacity cannot yet deliver at commercial scale.
- Natural gas supply intermittency:Furnace energy costs fluctuate with pipeline reliability, disadvantaging continuous melt operations against regional imports.
Strategic Opportunities
- Katanga Province underpenetration:Mining corridor towns between Lubumbashi and Kolwezi lack local glass supply, creating distribution white space for regional logistics investments.
- Lightweighting technology convergence:Thin-wall blow molding combined with surface coating treatments can reduce glass weight by 15-20 percent, cutting transport costs for export-bound beverages.
- Regional harmonization tailwinds:BIS-aligned technical committees in neighboring jurisdictions are pressuring packaging safety protocol alignment, advantaging early-certified Congo producers.
Industry Challenges
- Furnace rebuild capex intensity:Cold repair cycles for 150-tonne day tanks require 18-24 month capital commitments that local balance sheets struggle to finance.
- Blow molding skill scarcity:High-speed IS machine operation and mold maintenance expertise concentrates with expatriate technicians, constraining output scaling.
- Certification timeline compression:Food-contact material testing queues at the national standards body extend market entry timelines for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congo Container Glass Market |
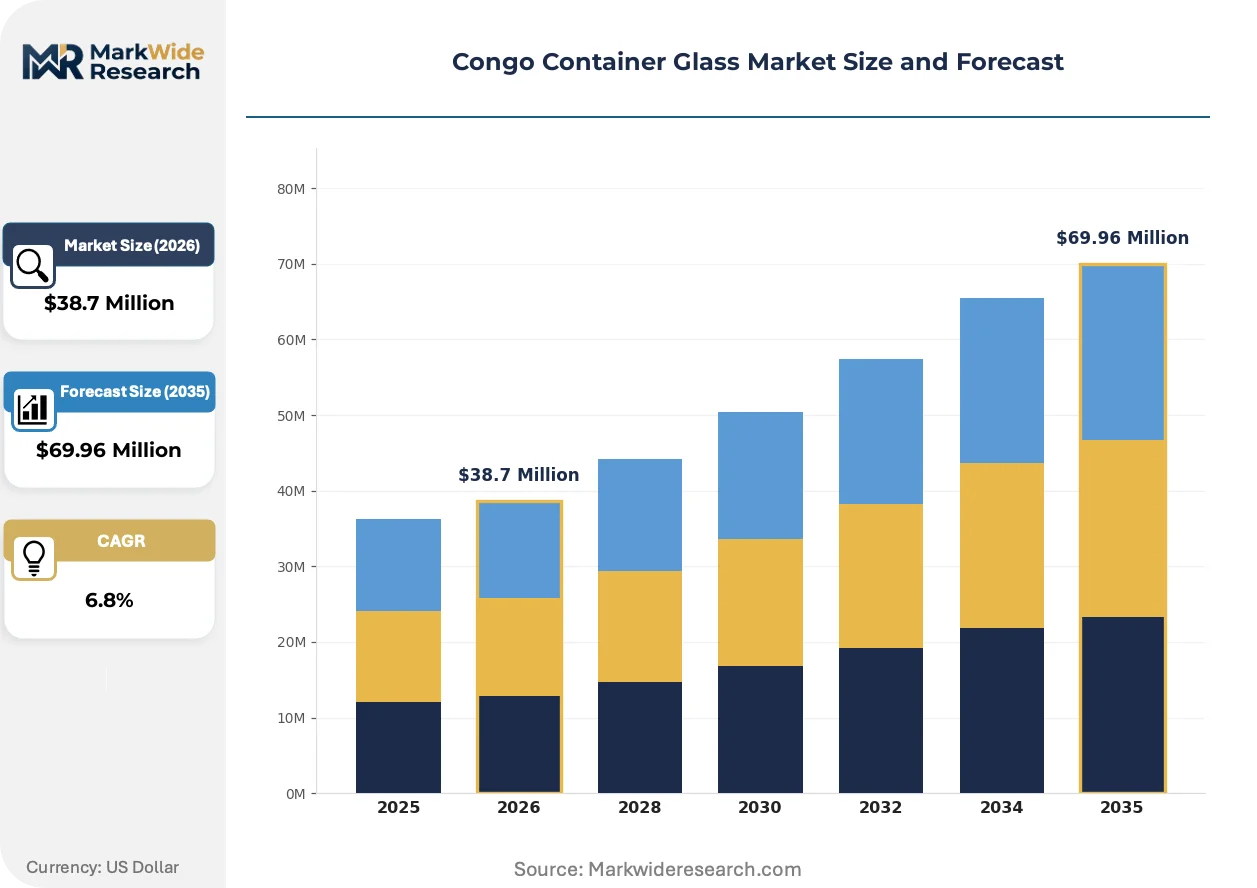
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Jugs End User: Food Industry, Beverage Sector, Pharmaceutical Companies, Cosmetics Sector Technology: Blow Molding, Press and Blow, Narrow Neck, Wide Mouth Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Beta Glass plc, Ardagh Group S.A., Hongxing Glass Congo SARL, Nampak Glass (Pty) Limited, XuzhouAnt Glass Products Co., Ltd., Boukin SARL, Consol Glass, AGI Glaspac, O-I Glass, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congo Container Glass Market Trends and Innovations
Container glass manufacturing in Congo is experiencing technology-driven capability gaps, regulatory compliance escalation, and buyer consolidation that together reshape competitive requirements for local producers.
Lightweighting through thin-wall forming and external protective coatings is fragmenting the traditional thick-wall bottle standard that dominated Congo beverage packaging. Breweries in Kinshasa are piloting 280-gram 330ml bottles against previous 330-gram specifications, accepting higher breakage rates in exchange for freight cost reductions on long-haul routes to interior provinces. This weight reduction is fragmenting supplier tiers between technically capable regional exporters and domestic furnaces lacking coating application equipment.
The country's national standards body is aligning food-contact material rules with BIS technical committees in neighboring jurisdictions, creating cross-border certification pressure. Industrial consequence includes mandatory third-party testing for lead and cadmium migration limits that informal sector converters cannot access. Pharmaceutical amber glass manufacturers in Lubumbashi are most affected, responding by consolidating procurement with certified regional suppliers rather than domestic informal sources.
Beverage bottlers are consolidating procurement away from fragmented informal traders toward formal sector buyers with certified supply chains and batch traceability. Kinshasa's major brewing clusters now require supplier audits and furnace energy source documentation, displacing spot-market glass purchases. This consolidation is most visible in carbonated soft drink and beer segments, where multinational bottling partners are enforcing global packaging standards on African operations.
Congo Container Glass Market Segmentation
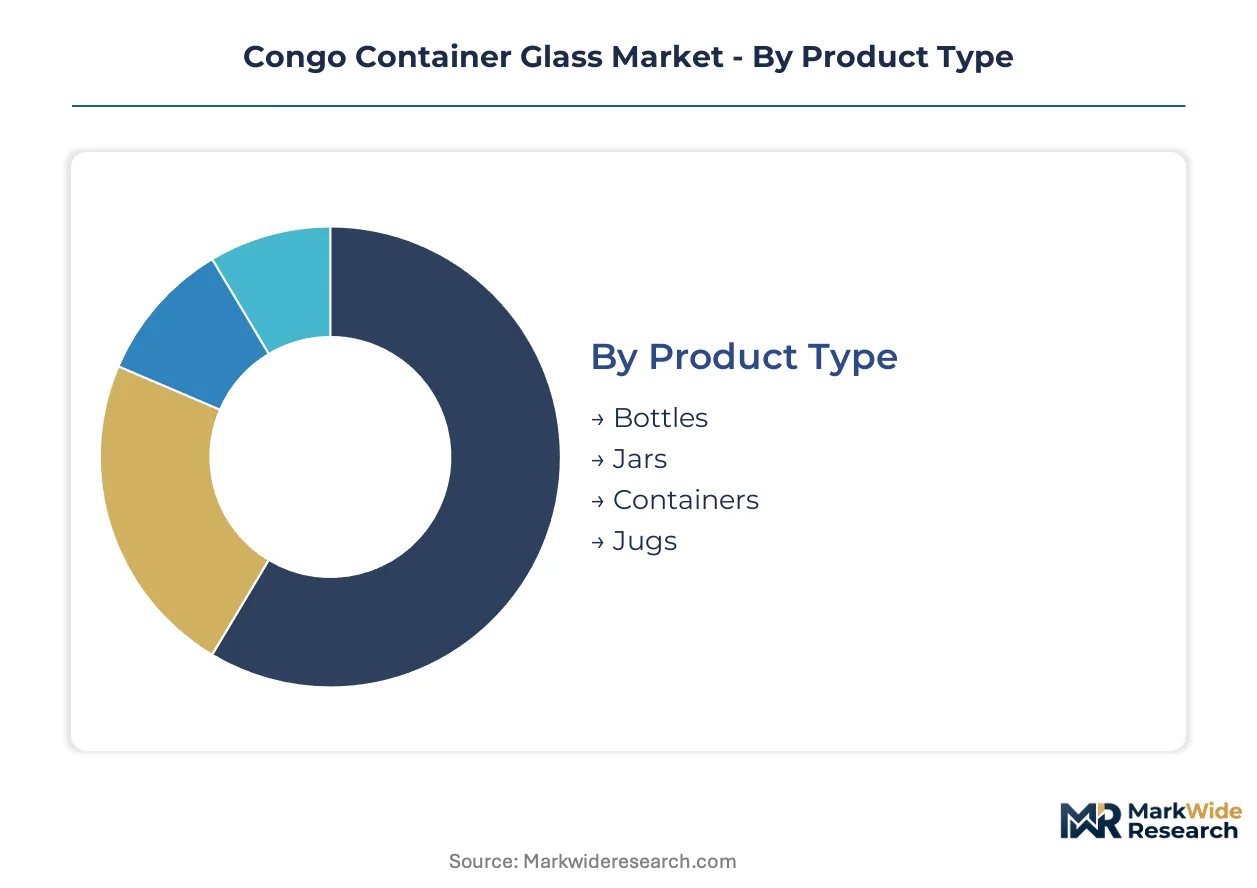
Segmentation in Congo's container glass market reveals how furnace capacity, certification requirements, and distribution logistics fragment supply across distinct buyer tiers. Understanding these divisions exposes where formal sector procurement is consolidating and where informal channels retain footholds.
Product Type:
Channel flow diverges sharply: bottles move through high-volume beverage bottler contracts with strict certification requirements, while jars and specialty containers still tolerate some informal trader intermediation in interior provinces.
- Bottles:Standard amber and flint soda-lime vessels dominate carbonated beverage and beer packaging. Kinshasa's brewing clusters now mandate returnable multi-trip specifications with documented furnace energy sources, squeezing uncertified domestic suppliers out of formal procurement channels.
- Jars:Wide-mouth pharmaceutical and food-packaging containers command quality premiums through amber glass and precise neck-finish tolerances. Lubumbashi's injectable drug manufacturers are consolidating purchases with certified regional suppliers as national standards tighten lead and cadmium migration limits.
- Containers:General-purpose vessels serve cosmetics and bulk food applications through mixed formal-informal distribution.
- Jugs:Large-format beverage and industrial chemical packaging flows primarily through spot-market purchases with minimal certification requirements.
By volume, bottles lead. By growth pace, jars are climbing the fastest as pharmaceutical packaging expands.
End User:
Cost-tier stratification separates premium-certified supply chains from economy-grade informal sourcing, with certification compliance costs acting as the primary sorting mechanism.
- Beverage Sector:Carbonated soft drink and beer bottlers in Kinshasa and Lubumbashi drive demand for lightweighted returnable bottles. Corporate sustainability targets and multinational parent-company standards are forcing procurement consolidation away from spot-market glass toward audited suppliers with batch traceability.
- Food Industry:Processed food packagers are migrating toward certified food-contact materials under national standards body enforcement, though informal sourcing persists for commodity products in interior markets.
- Pharmaceutical Companies:Injectable drug manufacturers require amber glass with strict light-protection specifications and third-party migration testing.
- Cosmetics Sector:Premium skincare and fragrance brands demand flint glass with decorative surface treatments, sourcing primarily through regional importers.
Beverage applications absorb the highest tonnage. Pharmaceutical demand is gaining share fastest as Lubumbashi's drug manufacturing base scales.
Technology:
Volume concentration favors high-speed blow molding for beverage lines, while margin concentration sits with press-and-blow precision for pharmaceutical narrow-neck specifications.
- Blow Molding:High-speed IS machine production dominates beverage bottle economics. Kinshasa's major brewing clusters require this technology for lightweighted 280-gram 330ml specifications, though domestic furnace operators lack coating application equipment to match regional exporter capabilities.
- Press and Blow:Precision forming for pharmaceutical containers with tight neck-finish tolerances. Lubumbashi's amber glass demand for light-sensitive injectables relies on this method, with skill scarcity concentrating expertise among expatriate technicians.
- Narrow Neck:Specialized pharmaceutical and cosmetic bottle specifications requiring precise finish dimensions.
- Wide Mouth:Food jar and cosmetic container formats with lower precision requirements and broader supplier base.
Blow molding handles the largest output volumes. Press-and-blow applications are expanding most quickly as pharmaceutical packaging requirements tighten.
Capacity:
Geographic supply concentration shapes availability: large and extra-large formats require continuous melt operations that domestic furnaces struggle to maintain given natural gas intermittency.
- Large:500ml to 1-liter beverage and pharmaceutical containers anchor regional production economics. Kinshasa's brewing clusters specify this capacity range for returnable bottle programs, with lightweighting trials reducing per-unit glass weight by 15-20 percent to cut interior distribution costs.
- Medium:250-500ml pharmaceutical and cosmetic applications capture margin concentration through amber and flint specialty grades.
- Small:Sample-size pharmaceutical and premium cosmetic vials, often imported due to precision forming requirements.
- Extra Large:Bulk chemical and industrial containers, limited domestic production due to furnace scale constraints.
Large capacity leads by tonnage. Medium formats are gaining share fastest as pharmaceutical packaging diversifies beyond bulk beverages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass furnace capacity clusters along Congo's eastern mining corridor and western urban belt, with supply logistics dictating where formal procurement channels penetrate. The national standards body's certification requirements fragment market access between certified coastal importers and informal interior traders.
Kinshasa
Kinshasa's brewing clusters drive demand for returnable multi-trip bottles with documented furnace energy sources. The national standards body enforces food-contact material certifications that restrict lead migration limits in container glass surfaces. Major bottling operations in the capital now mandate supplier audits and batch traceability, displacing spot-market glass purchases.
Lubumbashi
Injectable drug manufacturers in Lubumbashi are increasing amber glass procurement for light-sensitive pharmaceutical formulations. The central bank's foreign exchange regulations create timing volatility for specialized colorant shipments, compressing furnace run schedules. Pharmaceutical packaging lines in this southern hub anchor regional consumption for narrow-neck press-and-blow specifications.
Katanga Province
Mining corridor towns between Lubumbashi and Kolwezi lack local glass supply, creating distribution white space for regional logistics investments. Natural gas supply intermittency disadvantages continuous melt operations against regional imports in this underpenetrated zone. Informal traders currently bridge supply gaps for bulk chemical and industrial container demand.
Kongo Central
Port-proximate storage and transshipment facilities in Kongo Central province handle soda ash and silica sand imports for western furnace operations. The central bank's foreign exchange regulations shape import timing for raw materials entering through Atlantic gateways. Beneficiation gaps for local sand deposits push converters toward washed import grades.
North Kivu
Beverage distribution networks in North Kivu rely on returnable bottle programs extending from Kinshasa-based brewing clusters. Fragile transport infrastructure elevates breakage costs for lightweighted bottles on long-haul routes to interior markets. Regional harmonization pressures from BIS-aligned technical committees in neighboring jurisdictions indirectly influence packaging safety protocols.
Congo Container Glass Market Competitive Landscape
Concentration sits with regional exporters possessing certified soda-lime compositions and formal sector supply chain documentation. The competitive terrain splits between West African manufacturers leveraging distribution networks, Chinese-origin fabricators with furnace operations near raw material sources, and multinational technical assistance programs transferring blow molding expertise. Three archetypes dominate: regional scale players with cross-border logistics capabilities, local furnace operators anchored to silica sand deposits, and technology licensors providing equipment and process know-how. Competitive moves center on certification acquisition for food-contact compliance and lightweighting technology deployment to reduce per-unit freight costs.
Among West African regional players, Beta Glass plc exemplifies the cross-border distribution archetype, while Hongxing Glass Congo SARL represents local furnace capacity positioned near beneficiation sites. O-I Glass, Inc. occupies the technology-licensor tier, anchoring competitive positioning through technical assistance programs rather than direct manufacturing presence. These three patterns illustrate how certification barriers, raw material proximity, and equipment expertise sort market access in Congo's container glass sector.
| Leading Market Players |
|---|
| Beta Glass plc |
| Ardagh Group S.A. |
| Hongxing Glass Congo SARL |
| Nampak Glass (Pty) Limited |
| XuzhouAnt Glass Products Co., Ltd. |
| Boukin SARL |
| Consol Glass |
| AGI Glaspac |
| O-I Glass, Inc. |
| Others |
Pricing and Supply Chain Analysis
The national standards body's food-contact material certification regime gates both supply qualification and price differentiation simultaneously, forcing converters to absorb third-party testing costs that informal competitors cannot shoulder while allowing certified producers to command premiums from audited buyers.
Pricing Analysis
Food-contact material certification dictates the pricing tier structure across Congo's container glass market. Three-tier pricing separates certified premium grades from transitional standard tiers and uncertified economy spot-market glass. Price differentiation rests on migration-test documentation and furnace energy source verification as primary sorting mechanisms. Pricing pressure stems from lightweighting trials that accept higher breakage rates in exchange for freight cost reductions on interior distribution routes. Beverage bottlers show least price sensitivity due to multinational parent-company sustainability mandates, while commodity food packagers in interior provinces remain most cost-responsive.
Supply Chain Analysis
Soda ash import dependency through Atlantic port gateways underwrites supply vulnerability for Congo's container glass converters. Raw material sourcing draws from Egyptian and Turkish soda ash producers, alongside South African silica sand beneficiators. Furnace operations hinge on natural gas pipeline reliability that fluctuates with regional infrastructure maintenance cycles. Distribution runs through Kinshasa-based brewing cluster procurement offices for formal sector volumes, while informal traders bridge gaps in Katanga Province mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a regulatory entrenchment defensive moat, where certification sunk costs and buyer audit requirements create switching barriers that protect incumbent positions against informal competition.
For Market Incumbents: Fortify certification moats by accelerating third-party migration testing capacity before the national standards body extends queue backlogs. Deepen backward integration into silica sand beneficiation to reduce import dependency exposure. Prioritize lightweighting technology deployment to defend margin position against regional exporters with coating application capabilities. For New Entrants and Emerging Players: Lead with logistics infrastructure investments targeting Katanga Province mining corridor towns between Lubumbashi and Kolwezi, where distribution white space and natural gas intermittency disadvantage incumbent furnace operations. Pursue pharmaceutical amber glass specialization as the most penetrable segment, leveraging press-and-blow precision requirements that concentrate expertise among expatriate technicians and limit domestic competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade amber glass production due to specialized colorant inventory financing and narrow-neck precision equipment requirements. Five-to-ten year viability favors acquisition targets with existing food-contact certifications and documented furnace energy sources rather than greenfield furnace proposals. Monitor central bank foreign exchange regulation volatility as the primary inflection signal for soda ash import timing and working capital stress.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Expansion | Third-party migration testing investment secures queue priority at the national standards body for new product lines. |
| Backward Integration into Silica Beneficiation | Captive sand washing and iron reduction processing reduces import dependency and furnace feedstock cost volatility. |
| Lightweighting Technology Deployment | Thin-wall blow molding combined with surface coating treatments cuts per-unit transport costs for export-bound beverages. |
| Regional Distribution Logistics Investment | Warehouse and fleet positioning in Katanga Province mining corridors captures underpenetrated demand from bulk chemical users. |
| Pharmaceutical Amber Glass Specialization | Press-and-blow precision capability for narrow-neck specifications commands quality premiums from Lubumbashi injectable drug manufacturers. |
Research Methodology
The analysis maps beverage bottler procurement clusters, pharmaceutical packaging lines, and informal trader distribution networks, each validated through primary interviews with furnace operations managers, procurement leads at Kinshasa brewing clusters, pharmaceutical quality assurance directors, and national standards body certification officers. Secondary validation draws from customs import records for soda ash and silica sand, central bank foreign exchange regulatory filings, and BIS-aligned technical committee documentation in neighboring jurisdictions. Bottom-up volume triangulation from furnace capacity utilization rates converges with top-down demand aggregation from end-user procurement surveys.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including product type, end-user sector, forming technology, and capacity tier alongside geographic supply concentration patterns. CAGRs derive from trend extrapolation of furnace rebuild cycles, certification timeline compression effects, and lightweighting adoption curves. Industry-specific forecast inputs incorporate natural gas pipeline reliability indices and returnable bottle mandate enforcement trajectories.
Forecasts assume regulatory continuity in food-contact material certification regimes and central bank foreign exchange administration; material policy shifts would require re-modeling of import timing and working capital assumptions. Practitioners should keep alternative scenarios live as BIS-aligned technical committee harmonization pressures and mining corridor infrastructure investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
France Container Glass Market