
 Glass Bottles Market | 2026-2036
Glass Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Bottles Market Analysis
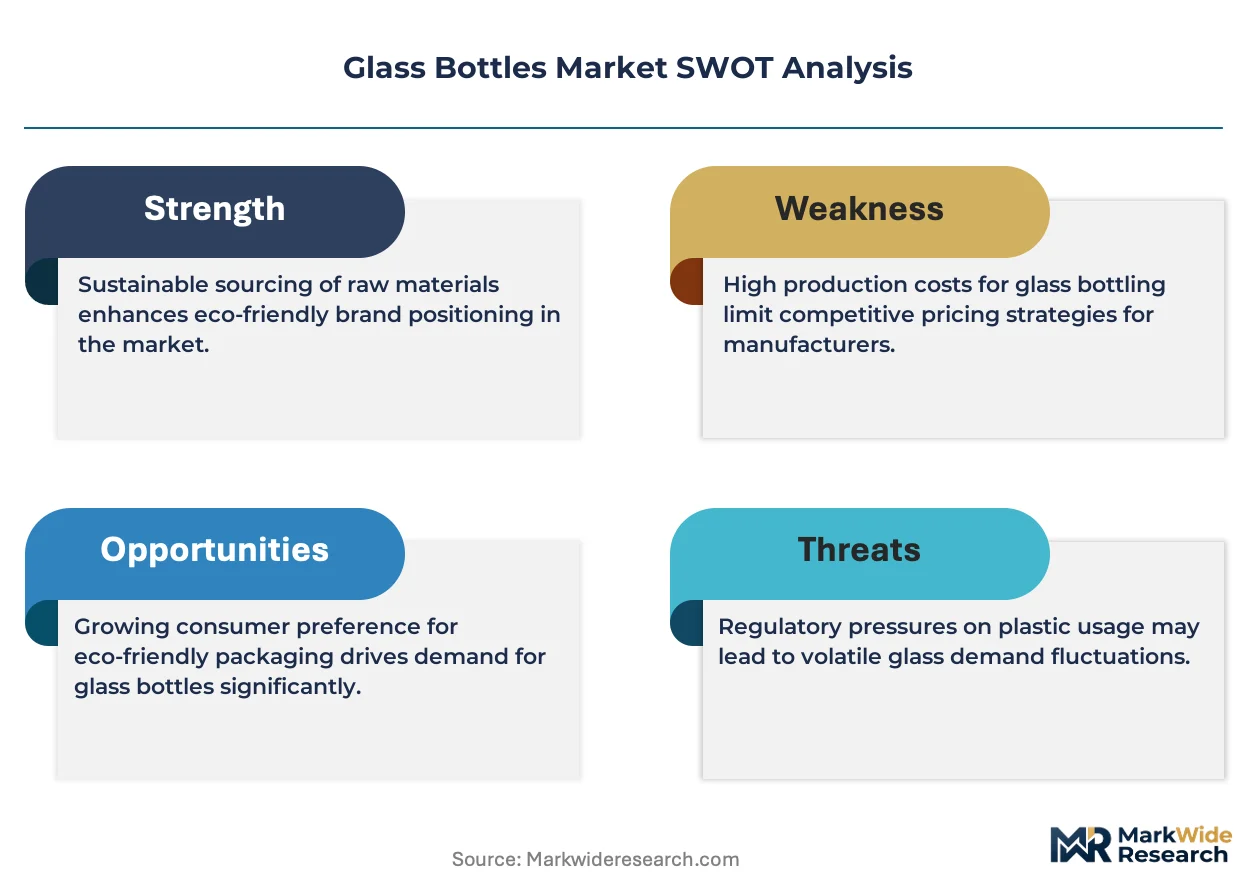
Asset-light leasing models for glass-forming equipment is reconfiguring capital barriers for mid-tier entrants. Owens-Illinois leverages its furnace network across multiple continents to sustain energy-efficient production. Ardagh Group anchors its position through captive cullet processing and lightweighting R&D. Verallia competes via specialized color-glass capabilities for premium beverage clients.
Glass bottles are rigid containers formed from silica sand, soda ash, limestone, and recycled cullet, melted at approximately 1,500°C and shaped by blow-and-blow or press-and-blow forming; they provide inert, impermeable, and infinitely recyclable packaging for liquids and semi-solids. The Food & Beverage end-user segment dominates volume, with 750ml and 1L capacities leading wine and spirits applications where premiumization supports thicker-walled, decorated formats. Clear glass commands share in pharmaceutical and cosmetics uses where product visibility drives specification, while colored variants—particularly amber and flint—absorb UV wavelengths for light-sensitive formulations.
The U.S. EPA and state-level bottle-bill programs enforce post-consumer collection targets that elevate cullet feedstock costs for non-compliant producers. EU REACH and F-Gas Regulation constrain furnace emissions and alternative fuel transitions, reshaping plant upgrade schedules across the continent. Stakeholders must monitor carbon-border adjustment mechanisms and recycled-content thresholds as these frameworks harden market access conditions for virgin-glass-dependent suppliers.
Market Dynamics
Extended producer responsibility frameworks across the EU and US state-level bottle-bill programs are forcing glassworks to reconfigure furnace feedstock ratios and upgrade cullet processing infrastructure ahead of tightening recycled-content mandates.
Growth Catalysts
- EU Green Deal recycled-content mandates:Member states are hardening post-consumer cullet quotas that push beverage packagers toward domestic glassworks with verified closed-loop systems.
- Premium spirits embossing and heavyweight formats:Super-premium whiskey and craft gin producers are specifying thicker-walled, decorated bottles that command price premiums and resist lightweighting pressures.
- Pharmaceutical serialization requirements:Track-and-trace regulations for prescription drugs are favoring glass over polymer alternatives where laser-etched codes adhere durably to container surfaces.
Market Restraints
- Natural gas price volatility:Furnace operations depend on pipeline gas or LNG, with European glassworks exposed to Nord Stream supply discontinuities and Asian spot-market spikes.
- Cullet quality fragmentation:Post-consumer collection systems in southern and eastern Europe yield contaminated or mixed-color feedstock that degrades furnace efficiency and final product clarity.
- Aluminum can substitution in beer:Breweries are converting volume to infinitely recyclable metal formats that reduce shipping weight and chill faster, compressing glass share in mainstream lager segments.
Strategic Opportunities
- India PLI scheme for packaging:Production-linked incentives for advanced manufacturing are drawing furnace investments to serve domestic beverage and pharmaceutical growth.
- Carbon-border adjustment mechanism positioning:EU importers of virgin-glass-dependent containers face escalating compliance costs, creating white space for regional producers with verified low-carbon cullet ratios.
- Returnable bottle pooling systems:Refillable formats for mineral water and beer are expanding in Germany and Austria, requiring durable glass engineered for 50+ wash cycles.
Industry Challenges
- Furnace rebuild cycle compression:Electrification and hydrogen-ready retrofits demand capital outlays of 100-150 million euros per site, straining mid-tier glassworks with aged asset bases.
- Color-glass formulation expertise scarcity:Amber and UV-absorbing flint specifications require precise redox control that retiring European technicians have not fully transferred to successor generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Bottles Market |
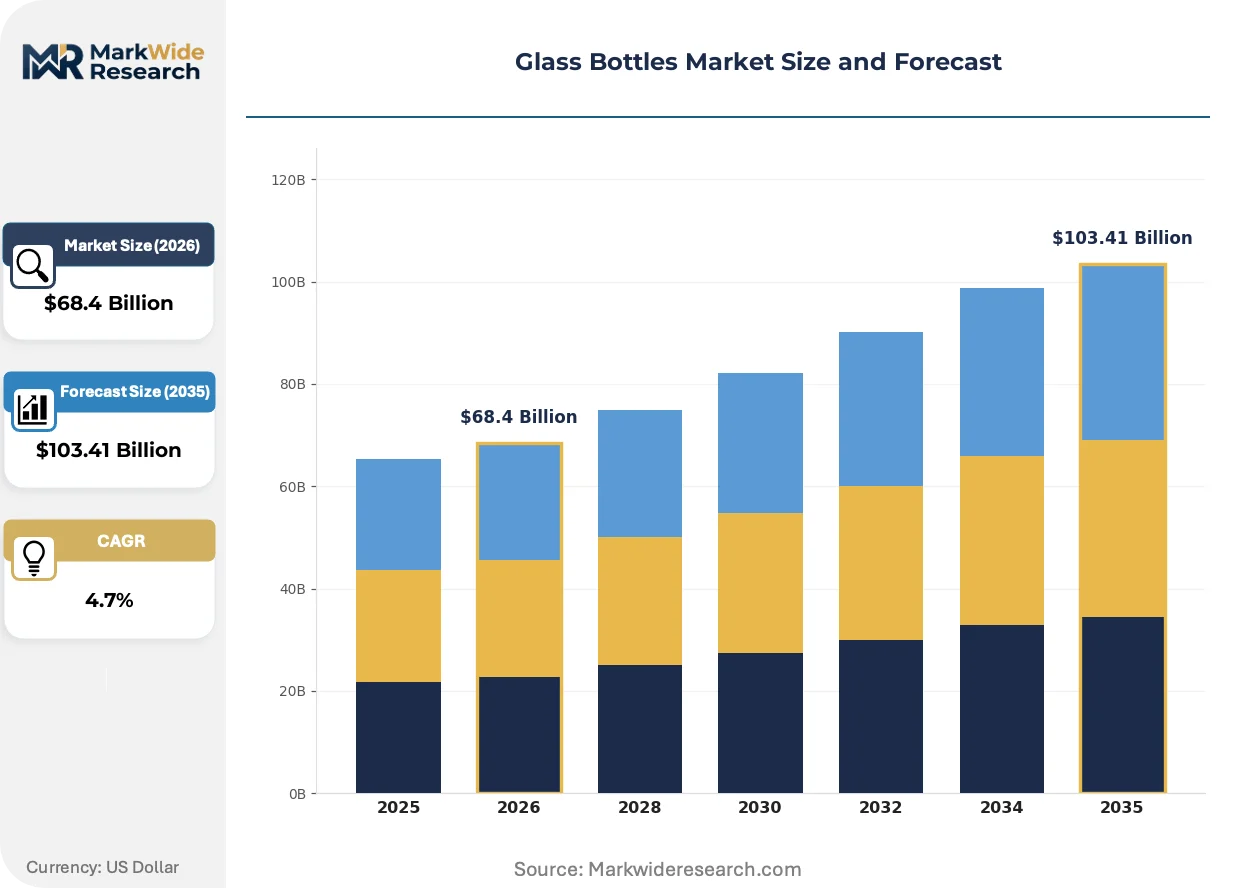
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opaque, Clear, Frosted, Colored Closure Type: Cork, Twist-off, Snap-on, Swing-top End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Capacity: 200ml, 500ml, 750ml, 1L |
| Companies Covered | Owens-Illinois, Ardagh Group, Verallia, Gerresheimer AG, Vetropack Holding Ltd, Vidrala, Anchor Glass Container Corporation, Piramal Glass, AGI Glasspack Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Bottles Market Emerging Trajectories
Digital simulation of furnace combustion and forming processes is compressing product development timelines while enabling lightweighting designs that maintain structural integrity under fill-pressure and pallet-stacking loads.
Computational fluid dynamics coupled with machine-vision inspection is virtualizing quality assurance protocols that previously required physical prototyping and destructive testing. Premium wine and spirits producers are adopting these digitally validated formats to accelerate seasonal label launches. The technology is virtualizing the traditional mold-making workflow, collapsing six-month design cycles to eight-week iterations.
REACH Annex XVII restrictions on heavy-metal colorants and the F-Gas Regulation's hydrofluorocarbon phase-down are constraining decorative coating options and alternative fuel trials respectively. Glassworks are reformulating enamel inks and accelerating hydrogen burner pilots to maintain compliance. Southern European container plants face the tightest retrofit deadlines given their reliance on legacy furnace architectures.
Direct procurement relationships between beverage multinationals and specialized glassworks are displacing traditional distributor intermediaries in Germany, France, and Italy. Buyers are consolidating supplier panels to four-to-six approved glassworks per region, demanding dedicated furnace capacity and real-time production visibility. This concentration is most pronounced in Champagne and Prosecco supply chains where provenance labeling requires traceable container origins.
Glass Bottles Market Segmentation
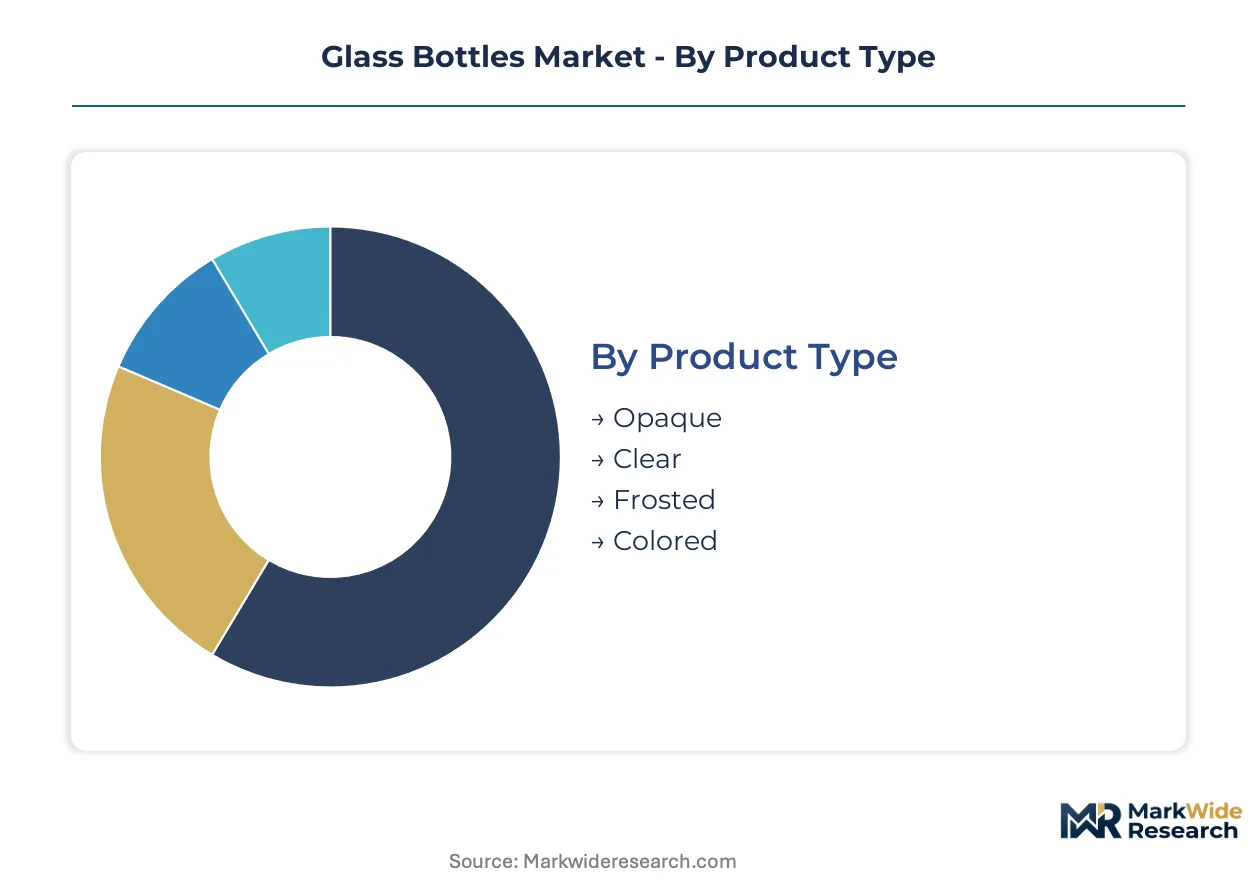
Glass bottle specifications diverge sharply across end-use requirements, with pharmaceutical serialization, beverage premiumization, and cosmetics visibility each demanding distinct material grades and forming precision. The report examines four structural dimensions that determine furnace feedstock ratios, forming method selection, and customer procurement patterns.
Product Type:
Glass clarity and surface treatment define barrier performance, aesthetic positioning, and UV protection levels across the use-case spectrum from pharmaceutical stability to luxury spirits presentation.
- Clear:High-transmission soda-lime silica permits complete product visibility for pharmaceuticals and premium cosmetics where ingredient clarity drives consumer trust. Demand concentrates in injectable drug packaging across Germany and France where EMA serialization mandates favor laser-etch-compatible surfaces.
- Colored:Amber and flint variants incorporate iron oxide and sulfur compounds to absorb UV wavelengths below 450nm, protecting light-sensitive formulations in pharmaceutical and craft beer applications. Italian glassworks in Tuscany and Veneto anchor supply for wine producers requiring provenance-verified container origins.
- Opaque:Ceramic-coated or fully pigmented glass blocks all light transmission for photosensitive biologics and high-end skincare where formulation integrity overrides visibility concerns.
- Frosted:Acid-etched or molded matte surfaces diffuse light for premium fragrance and spirits segments where tactile differentiation commands shelf price premiums.
The dominant share belongs to Clear, while Colored is closing the gap fastest as pharmaceutical light-protection specifications harden across EU member states.
Closure Type:
Sealing mechanism selection hinges on oxygen ingress tolerance, reseal frequency, and line-speed compatibility across bottling operations from artisanal wineries to high-throughput pharmaceutical fillers.
- Cork:Natural or agglomerated bark closures provide micro-oxygenation for wine aging protocols, with Portuguese and Spanish suppliers dominating premium still and sparkling wine specifications. Champagne houses mandate specific cork dimensions and compression rates for secondary fermentation containment.
- Twist-off:Threaded aluminum or plastic caps enable consumer resealing and tamper-evident integrity for spirits, juices, and condiments where convenience outweighs ritual. German mineral water bottlers specify twist-off compatibility for returnable bottle pooling systems requiring 50+ wash cycles.
- Snap-on:Press-fit plastic or metal closures suit single-serve beverages and sample-sized pharmaceuticals where opening torque must accommodate elderly or impaired users.
- Swing-top:Wire-bale ceramic or glass stoppers serve craft brewing and artisanal water segments in Germany and Austria where refillable deposit systems reward durable container investments.
Cork retains volume leadership in wine, yet Twist-off is expanding most quickly as spirits producers prioritize supply security and aluminum price stability.
End User:
Regulatory intensity and margin structure vary dramatically across customer categories, with pharmaceutical serialization and beverage premiumization each imposing distinct technical validation requirements.
- Food & Beverage:Wine, spirits, beer, and non-alcoholic beverages consume furnace capacity across 750ml and 1L standardized formats, with super-premium whiskey and craft gin driving embossed, heavyweight specifications that resist lightweighting pressures.
- Pharmaceuticals:Injectable, oral, and topical drug packaging demands Type I borosilicate or Type III soda-lime glass with documented USP or EP compliance, laser-etched track-and-trace codes, and child-resistant closure compatibility.
- Cosmetics:Skincare, fragrance, and color cosmetic containers prioritize aesthetic differentiation through color matching, surface decoration, and ergonomic shaping for vanity display.
- Household:Cleaning agents, oils, and specialty chemicals utilize standardized amber or clear formats where chemical compatibility and label adhesion outweigh premium finishing.
Food & Beverage commands installed furnace capacity, though Pharmaceuticals is climbing the fastest as serialization mandates expand beyond Europe into India and North America.
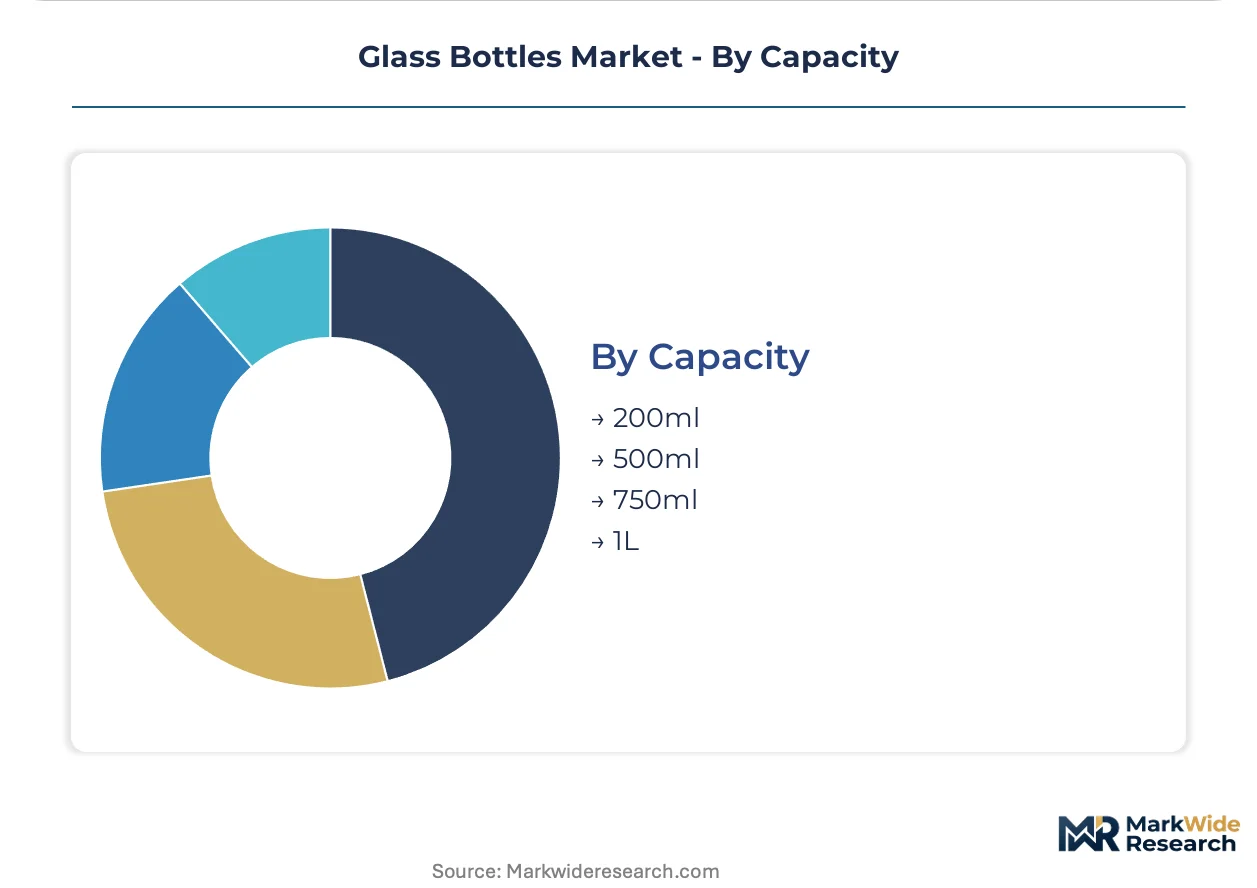
Capacity:
Volume standardization enables pallet optimization and line efficiency, yet premium segments increasingly specify non-standard formats for shelf differentiation.
- 750ml:The wine industry reference standard permits 12-bottle case stacking and retail shelving compatibility across Bordeaux, Burgundy, and Champagne bottle families with distinct shoulder angles and punt depths.
- 1L:Spirits and olive oil producers favor this format for duty-free and retail channels where volume-per-price positioning drives purchase decisions.
- 500ml:Craft beer, mineral water, and pharmaceutical syrup applications utilize this mid-size for single-serve or short-course dosing convenience.
- 200ml:Sample sizes, airline miniatures, and pediatric pharmaceuticals specify this compact format where portability and precise dosing control matter.
750ml maintains structural dominance in value terms, while 500ml is gaining share fastest as portion-controlled consumption patterns reshape beverage and pharmaceutical packaging specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glassworks command pricing premiums through verified low-carbon cullet ratios, while southern European producers absorb feedstock quality penalties that compress margins. This asymmetry is reshaping procurement patterns as beverage multinationals consolidate supplier panels.
Germany
Returnable bottle pooling systems for mineral water and beer drive durable glass demand engineered for fifty-plus wash cycles. The EU Green Deal mandates push domestic glassworks toward closed-loop cullet systems ahead of tightening recycled-content quotas. Glassworks clusters in Bavaria and North Rhine-Westphalia serve beverage multinationals with dedicated furnace capacity and real-time production visibility.
France
Champagne and Prosecco supply chains require traceable container origins, concentrating demand around provenance-verified glassworks. REACH Annex XVII restrictions on heavy-metal colorants constrain decorative coating options across French container plants. Specialized color-glass capabilities in Île-de-France and Hauts-de-France anchor supply for premium beverage clients demanding amber and UV-absorbing flint specifications.
Italy
Super-premium whiskey and craft gin producers specify thicker-walled, embossed bottles that resist lightweighting pressures and command shelf price premiums. F-Gas Regulation hydrofluorocarbon phase-downs accelerate hydrogen burner pilots across legacy furnace architectures. Tuscan and Veneto glassworks maintain dominant positions in wine packaging where provenance labeling requirements favor domestic container sourcing.
United States
State-level bottle-bill programs enforce post-consumer collection targets that elevate cullet feedstock costs for non-compliant producers. FDA serialization mandates for prescription drugs favor glass over polymer alternatives where laser-etched track-and-trace codes adhere durably to container surfaces. Glass-forming equipment clusters in the Midwest and Southeast reconfigure capital barriers for mid-tier entrants through asset-light leasing models.
India
Domestic beverage and pharmaceutical growth draws furnace investments through production-linked incentives for advanced manufacturing. CDSCO track-and-trace regulations expand serialization mandates beyond Europe, favoring laser-etch-compatible glass surfaces. Glassworks in Maharashtra and Gujarat position for carbon-border adjustment mechanism compliance as EU importers face escalating costs for virgin-glass-dependent containers.
Glass Bottles Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive technologies. The market structure concentrates around furnace-network operators with multi-continental footprints and specialized color-glass formulators with provenance-verified supply chains. Two strategic archetypes dominate: scale-driven furnace consolidators with energy-efficient production networks, and premium-tier specialists with lightweighting R&D and embossing capabilities. Competitive moves center on strategic partnerships for cullet processing infrastructure and geographic expansion into production-linked incentive jurisdictions.
Among North American and European furnace-network operators, Owens-Illinois and Ardagh Group exemplify scale-driven archetypes with multi-continental asset footprints. Verallia occupies a position within the premium-tier specialist segment through specialized color-glass capabilities. These three companies represent the dominant competitive positioning patterns visible across the supplier base, anchoring procurement consolidation trends as beverage multinationals reduce approved glassworks to four-to-six per region.
| Leading Market Players |
|---|
| Owens-Illinois |
| Ardagh Group |
| Verallia |
| Gerresheimer AG |
| Vetropack Holding Ltd |
| Vidrala |
| Anchor Glass Container Corporation |
| Piramal Glass |
| AGI Glasspack Ltd |
| Others |
Supply Flow & Price Mechanics
Italian and Tuscan glassworks clusters anchor premium color-glass supply for Champagne and Prosecco provenance requirements, concentrating margin capture among furnace operators with verified closed-loop cullet systems and embossing capabilities.
Pricing Analysis
Configured-to-order pricing for embossed, heavyweight spirits bottles commands spreads of 40-60% above standard 750ml wine formats, with premiumization drivers including UV-absorbing flint specifications and laser-etch serialization compatibility. Price differentiation rests on cullet-ratio verification for EU Green Deal compliance and dedicated furnace capacity allocation. Cost compression in mainstream beer glass is intensifying because aluminum can substitution erodes volume; craft distilleries show least price sensitivity due to bottle-as-brand positioning.
Supply Chain Analysis
Export-control regimes on hydrogen burner technology and advanced furnace simulation software limit retrofit equipment flows to southern European glassworks, compressing upgrade timelines. Supply concentrates in Germany, France, and Italy for beverage multinationals, with silica sand and soda ash drawn from Nordic and Mediterranean sources. Single-source vulnerability sits with Portuguese cork closure suppliers for premium wine. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in core EU markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cullet processing and returnable-bottle logistics represent service-attach layers expanding faster than container production, as EU extended producer responsibility frameworks mandate closed-loop infrastructure ownership.
For Market Incumbents: Entrench position through captive cullet processing investments ahead of tightening recycled-content mandates, and secure dedicated furnace capacity agreements with beverage multinationals consolidating supplier panels. Aluminum can substitution in mainstream beer threatens volume; vertical integration into color-glass formulation expertise counters lightweighting pressures. For New Entrants and Emerging Players: India's production-linked incentive jurisdictions offer underpenetrated furnace investment opportunities serving domestic pharmaceutical serialization growth. Target CDSCO track-and-trace compliance as the most penetrable regulatory wedge, with asset-light leasing models for glass-forming equipment reducing capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward specialized color-glass formulators with provenance-verified supply chains and hydrogen-ready furnace architectures. Long-term viability favors operators with verified low-carbon cullet ratios positioned for EU carbon-border adjustment mechanism exposure. Watch hydrogen burner pilot scale-up rates as inflection signal for retrofit capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Processing Infrastructure Investment | Captive closed-loop systems secure EU Green Deal compliance ahead of mandate tightening. |
| Hydrogen-Ready Furnace Retrofit | F-Gas Regulation phase-downs accelerate alternative fuel transitions across legacy assets. |
| Direct Procurement Relationship | Beverage multinationals consolidate panels to four-to-six approved glassworks per region. |
| Returnable Bottle Pooling System | German and Austrian deposit systems require durable glass engineered for 50+ wash cycles. |
| Digital Simulation Capability | Computational fluid dynamics compresses mold-making cycles from six months to eight weeks. |
Methodological Framework
Desk research of furnace capacity databases, EU regulatory filings, and beverage industry procurement disclosures preceded structured interviews with glassworks plant managers, beverage packaging procurement leads, cullet processing operators, and pharmaceutical serialization specialists. Secondary validation drew from ECHA REACH registrations, F-Gas Regulation implementation reports, and national extended producer responsibility frameworks. Bottom-up capacity modeling and top-down demand segmentation were triangulated against trade flow data.
Assumptions held furnace electrification timelines and natural gas price volatility within observed ranges across the projection horizon, with segmentation dimensions including product clarity grade, closure mechanism, end-use regulatory intensity, and regional cullet collection infrastructure maturity. CAGRs were derived from installed capacity utilization trends and premium format mix shifts. Forecast inputs incorporated EU carbon-border adjustment mechanism implementation pacing and pharmaceutical serialization mandate expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese furnace equipment suppliers or accelerated hydrogen infrastructure deployment would shift outcomes. Material shifts in EU recycled-content threshold schedules or Nordic silica sand export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market