
 Elastomeric Closures Market | 2026-2036
Elastomeric Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Closures Market Analysis
Modular packaging configurations is pivoting buyer choice toward integrated closure-vial systems that reduce assembly risk. West Pharmaceutical Services anchors North American supply through captive elastomer formulation capabilities. Gerresheimer AG leverages European manufacturing scale to dominate high-barrier pharmaceutical closures. Daikyo Seiko specializes in fluoropolymer-coated stoppers for sensitive biologics, competing on material purity rather than volume.
Elastomeric closures are elastic sealing devices manufactured from silicone, EPDM, or halobutyl rubber compounds, typically compressed between 20% and 50% to maintain hermetic integrity in parenteral drug containers. These components prevent gas permeation, particulate ingress, and microbial contamination during shelf life and administration. Stopper formulations command the deepest margin pools due to extractables testing burdens and custom compounding requirements. Silicone materials lead in biologics applications where inertness outweighs cost, while EPDM competes in multi-dose vials where permeation resistance matters less. Drug delivery applications are structurally tightening specifications as prefilled syringes and auto-injectors displace traditional vial formats.
FDA container closure guidance and USP Chapter 381 shape elastomer qualification protocols for US market access, while EU EMA and MDR enforce leachable thresholds through centralized marketing authorization reviews. The EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of certain curing agents and processing aids. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to avoid dual qualification costs.
Market Dynamics
Prefilled syringes and auto-injectors are compressing demand for traditional vial stoppers while simultaneously elevating technical specifications for elastomeric components that must interface with complex drug delivery mechanisms.
Growth Catalysts
- Biologics proliferation:Monoclonal antibodies and cell therapies require ultra-pure halobutyl and silicone formulations that command premium qualification cycles.
- REACH chemical restrictions:The EU's tightening controls on curing agents are accelerating reformulation investments that create first-mover advantages for compliant suppliers.
- Injectable diabetes management:GLP-1 receptor agonists and insulin analogues are expanding multi-dose vial requirements across North American and European patient populations.
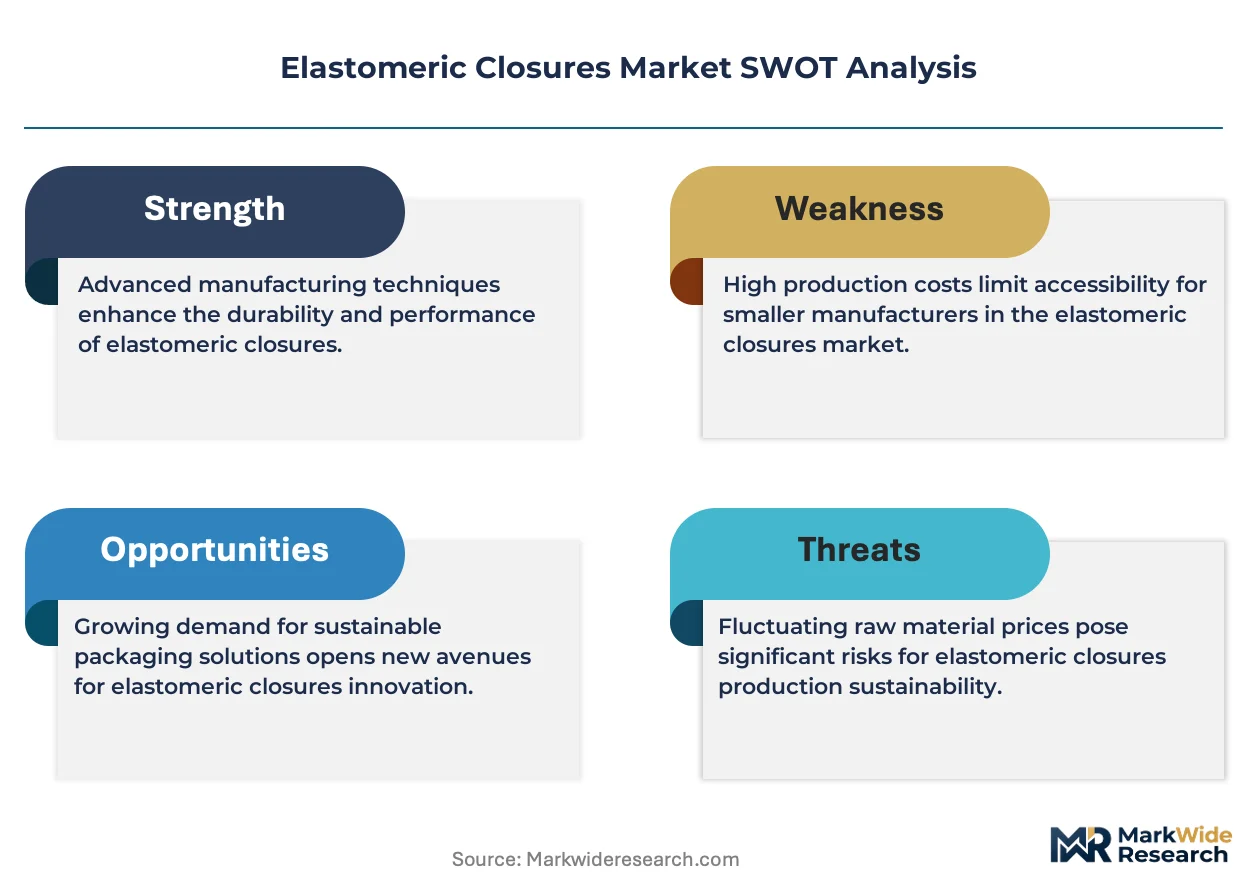
Market Restraints
- Raw material concentration:Halobutyl rubber feedstock depends on concentrated petrochemical supply chains in the US Gulf Coast and Middle East.
- Extractables testing burden:USP Chapter 1664 and EMA leachable thresholds extend qualification timelines by 18-24 months for new formulations.
- Fluoropolymer substitution:Daikyo Seiko's fluoropolymer-coated stoppers compete on material purity for high-value biologics, compressing margins on uncoated alternatives.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH guidelines creates pathways for Western-qualified closure suppliers to serve domestic injectable producers.
- Integrated closure-vial systems:Modular packaging configurations reduce assembly risk and lock in supplier relationships through combined qualification protocols.
- Cell and gene therapy cold chain:Cryogenic storage requirements below -150°C demand specialized elastomer formulations with retained elasticity at ultra-low temperatures.
Industry Challenges
- Compounding expertise scarcity:Formulation chemists capable of balancing cure kinetics with extractables profiles command salaries 40% above general polymer engineering roles.
- Dual pharmacopeial harmonization:Divergent USP, EP, and JP test methods force redundant validation studies that inflate regulatory submission costs.
- Cleanroom capacity constraints:ISO 14644 Class 7 manufacturing space for pharmaceutical-grade closures faces 18-month lead times in established European clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Closures Market |
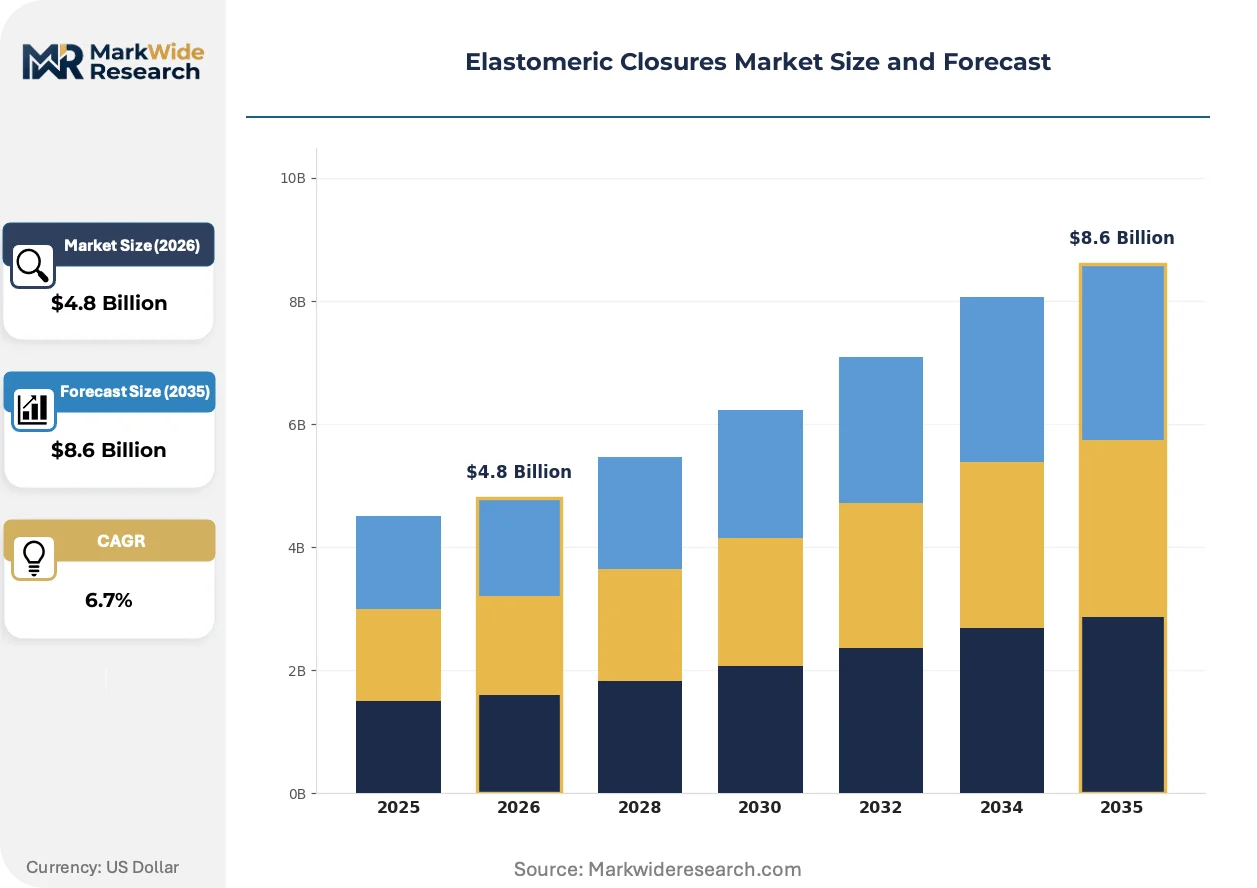
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stopper, Cap, Plug, Valve Material: Silicone, EPDM, Neoprene, Natural Rubber End User: Pharmaceutical, Biotechnology, Food & Beverage, Cosmetics Application: Drug Delivery, Packaging, Sealing, Laboratory |
| Companies Covered | Berry Global, Inc., Gerresheimer AG, West Pharmaceutical Services, Inc., Westar Medicorp Limited, Stevanato Group, AptarGroup, Inc., SCHOTT AG, Daikyo Seiko, Ltd., Datwyler Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Closures Market Emerging Trajectories
Automation of quality assurance and the convergence of material science with digital traceability are redefining competitive advantage in elastomeric closure manufacturing.
Laser-based particulate inspection systems are automating defect detection at production speeds exceeding 1,200 units per minute. Large parenteral drug manufacturers are retrofitting existing lines with this capability to eliminate manual visual inspection bottlenecks. This technology is automating the shift from batch sampling to 100% inline verification, compressing release timelines and reducing human error rates.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in pharmaceutical manufacturing processes. Closure producers dependent on fluorinated processing aids face reformulation mandates that alter cure chemistry and shelf-life performance. German and Swiss manufacturers are responding fastest, leveraging existing REACH compliance infrastructure to validate alternative blowing agents.
Consolidated buying by contract development and manufacturing organizations is compressing supplier rosters and extending master service agreement terms. CDMOs now demand dedicated manufacturing lanes and real-time inventory visibility in exchange for volume commitments. This pattern is most pronounced in the Boston-Cambridge biotech corridor, where three CDMOs control 60% of regional injectable packaging procurement.
Elastomeric Closures Market Segmentation
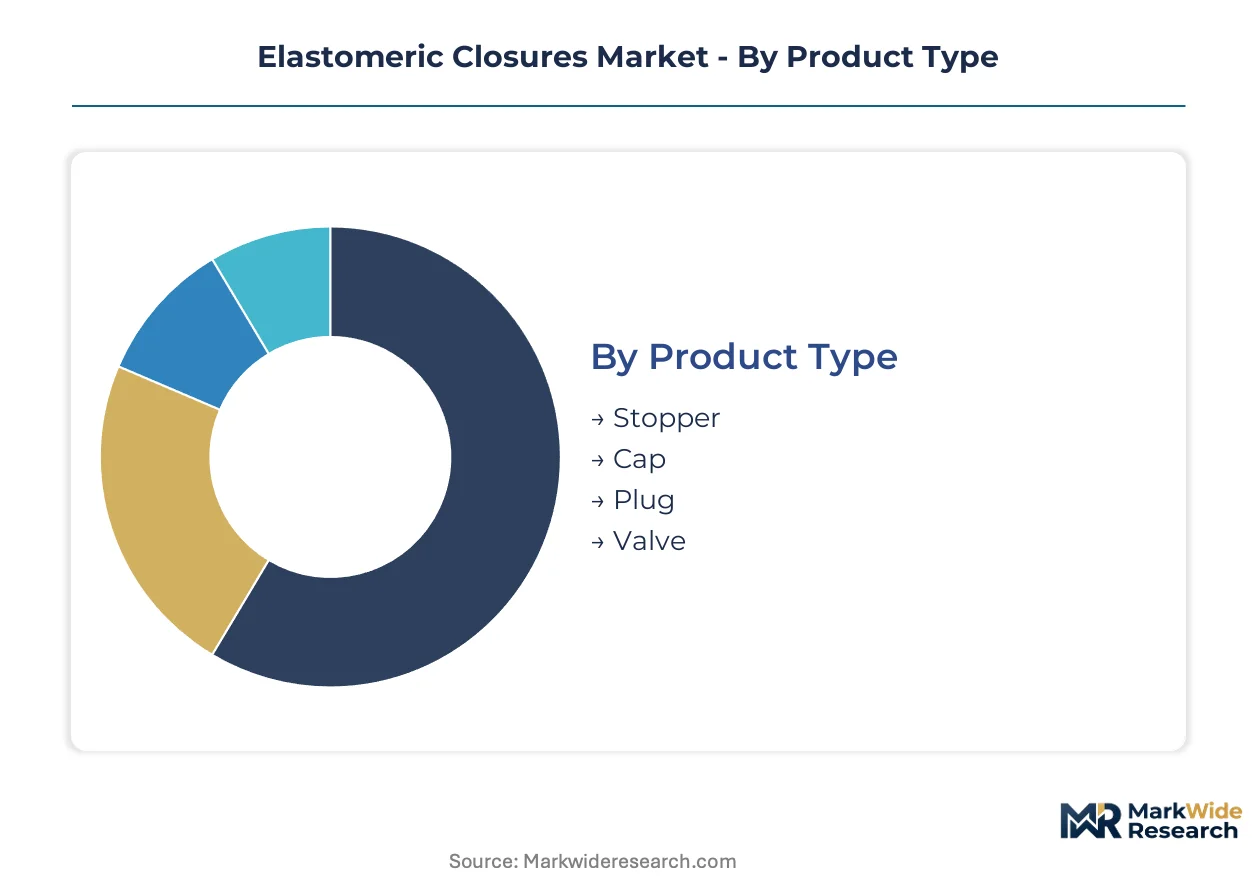
Elastomeric closure specifications diverge sharply across end-use contexts, with pharmaceutical purity demands commanding formulation investments that commodity packaging segments cannot justify. Material selection and geometric design must align precisely with container closure integrity requirements, sterilization protocols, and regulatory filing pathways.
Product Type:
Volume concentrates in stoppers and caps, while premium margins pool in specialized geometries requiring custom tooling and extended qualification cycles.
- Stopper:Compression-molded elastomeric cylinders designed for vial and bottle sealing, typically formulated from halobutyl or silicone compounds. Demand clusters in parenteral drug packaging across Germany and Switzerland, where Gerresheimer and Datwyler operate specialized manufacturing facilities. Extractables testing burdens and custom compounding requirements command the deepest margin pools in this segment.
- Cap:Threaded or snap-fit closures providing secondary sealing and tamper-evidence for bottles and containers. Pharmaceutical applications in the US drive specifications, with FDA container closure guidance shaping dimensional tolerances and torque requirements. Screw-cap formats for oral solid dose bottles dominate volume, though flip-top designs for multi-dose vials are expanding.
- Plug:Tapered elastomeric inserts for syringe barrels, cartridge tubes, and diagnostic vessels. Single-use diagnostic applications in Massachusetts and California concentrate procurement for serum and plasma collection tubes.
- Valve:Elastomeric components controlling fluid flow in dispensing closures, bag ports, and aseptic transfer systems. Bioprocessing applications in South Korea and Singapore drive demand for platinum-cured silicone formulations.
Today's leader: Stopper. Tomorrow's challenger: Valve.
Material:
Silicone commands premium positioning for biologics, while EPDM and natural rubber serve cost-sensitive multi-dose applications where permeation resistance matters less.
- Silicone:Platinum-cured or peroxide-cured polydimethylsiloxane formulations offering thermal stability and chemical inertness. Monoclonal antibody packaging in Massachusetts and Cambridge concentrates demand for ultra-pure grades with controlled extractables profiles. Daikyo Seiko's fluoropolymer-coated variants compete on material purity for high-value biologics.
- EPDM:Ethylene-propylene-diene terpolymer compounds providing ozone resistance and electrical insulation. Multi-dose insulin vials across North American patient populations drive volume, with compounding expertise in halobutyl-EPDM blends creating differentiation.
- Neoprene:Polychloroprene formulations balancing oil resistance with elasticity. Industrial and laboratory applications in Texas and Louisiana concentrate procurement for chemical storage containers.
- Natural Rubber:Hevea brasiliensis latex-derived compounds offering high resilience and tear strength. Food and beverage closures in Brazil and Southeast Asia sustain residual demand despite pharmaceutical migration to synthetic alternatives.
Silicone leads on specification; EPDM leads on unit economics.
End User:
Pharmaceutical procurement dominates value capture, while biotechnology applications impose the steepest technical barriers to supplier qualification.
- Pharmaceutical:Injectable drug manufacturers requiring container closure integrity for shelf-life stability and patient safety. US FDA and EU EMA regulations on extractables and leachables tighten material compliance thresholds, extending qualification timelines. Prefilled syringe and auto-injector growth elevates specifications for elastomeric components interfacing with complex delivery mechanisms.
- Biotechnology:Cell therapy, gene therapy, and monoclonal antibody producers demanding ultra-pure formulations. Cryogenic storage requirements below -150°C demand specialized elastomer formulations with retained elasticity at ultra-low temperatures. Boston-Cambridge CDMOs consolidate buying power across regional procurement.
- Food & Beverage:Carbonated beverage and condiment packaging requiring gas barrier properties and organoleptic neutrality. European F-Gas Regulation compliance shapes processing aid selection for closure manufacturing.
- Cosmetics:Premium skincare and fragrance packaging emphasizing aesthetic finish and dispensing precision. French and Italian luxury brands drive specifications for custom-colored and metalized closure surfaces.
Pharmaceutical volume anchors revenue; biotechnology applications expand fastest.
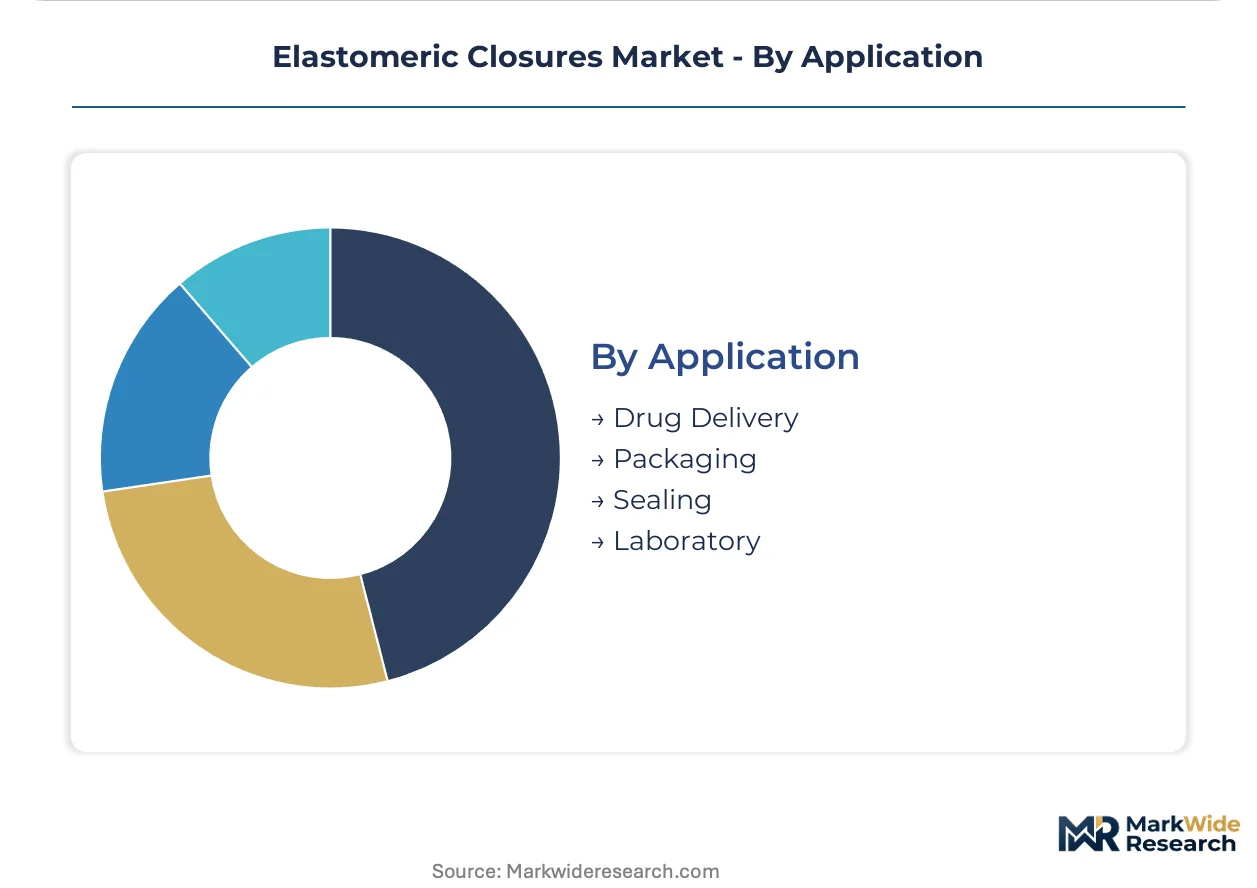
Application:
Drug delivery specifications are structurally tightening as prefilled syringes and auto-injectors displace traditional vial formats.
- Drug Delivery:Elastomeric components integrated into injection devices, infusion sets, and inhalation systems. Auto-injector plunger stoppers and needle shields in Germany and Switzerland require precise friction control and lubrication management. West Pharmaceutical Services anchors North American supply through captive elastomer formulation capabilities.
- Packaging:Primary and secondary sealing for pharmaceutical, food, and industrial containers. Modular packaging configurations pivot buyer choice toward integrated closure-vial systems that reduce assembly risk and lock in supplier relationships.
- Sealing:Static and dynamic gasket applications for process equipment, analytical instruments, and transportation containers. Aseptic manufacturing in Singapore and South Korea drives demand for validated sterilization compatibility.
- Laboratory:Closure components for cell culture vessels, diagnostic reagent bottles, and sample collection systems. COVID-19 diagnostic demand sustained capacity expansion for serum tube stoppers across US and European supply chains.
Drug delivery commands technical premium; packaging commands volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering traditions established pharmaceutical-grade elastomer manufacturing during the mid-twentieth century, with specialized compounding expertise concentrating in the Rhine-Main and Lake Constance industrial corridors before spreading to North American and Asian production centers.
United States
GLP-1 diabetes therapies and monoclonal antibody production drive demand for ultra-pure silicone formulations across Massachusetts and New Jersey manufacturing clusters. FDA container closure guidance and USP Chapter 381 enforce extractables testing protocols that extend supplier qualification timelines. The Boston-Cambridge corridor concentrates CDMO procurement power, with three contract manufacturers controlling the majority of regional injectable packaging spend.
Germany
Gerresheimer AG and Datwyler anchor specialized manufacturing clusters for premium halobutyl and silicone closure components serving European pharmaceutical exporters. EU EMA leachable thresholds through centralized marketing authorization reviews tighten material compliance requirements. The Lake Constance region combines precision molding heritage with REACH-compliant formulation chemistry, creating first-mover advantages for alternative curing agent validation.
Switzerland
Swissmedic oversight of biologics packaging elevates specifications for elastomeric components in cell therapy and gene therapy cold chain applications. The country's pharmaceutical precision manufacturing base demands cryogenic-compatible formulations retaining elasticity below -150°C. Basel and Zurich industrial zones concentrate compounding expertise for platinum-cured silicone grades.
Japan
Daikyo Seiko's fluoropolymer-coated stopper technology originates from Japanese material science specialization in high-purity pharmaceutical packaging. PMDA pharmacopeial standards shape elastomer qualification protocols for domestic biologics manufacturers. The Kanto region around Tokyo maintains advanced coating and surface treatment capabilities for sensitive therapeutic applications.
India
Domestic injectable drug production expansion creates procurement pathways for Western-qualified closure suppliers as CDSCO aligns with ICH guidelines. Maharashtra and Gujarat pharmaceutical manufacturing zones drive volume requirements for multi-dose vial stoppers and serum tube closures. Hyderabad and Mumbai clusters concentrate formulation chemistry expertise for cost-competitive EPDM compounds.
Elastomeric Closures Market Vendor Landscape
Premium-margin players sit above commodity-margin players across qualification depth and captive formulation chemistry capabilities. The market structures into three tiers: integrated packaging systems providers with in-house elastomer compounding, specialized closure manufacturers with regional regulatory expertise, and commodity converters dependent on toll compounding relationships. Consolidation pressure intensifies as CDMOs demand dedicated manufacturing lanes and real-time inventory visibility in exchange for multi-year volume commitments.
Among European-headquartered specialists, Gerresheimer AG exemplifies the integrated systems archetype combining closure manufacturing with glass vial production, while Datwyler Holding Inc. occupies a position emphasizing halobutyl rubber formulation depth. West Pharmaceutical Services, Inc. anchors North American supply through captive elastomer capabilities and drug delivery device integration. These three represent divergent strategic postures: vertical packaging integration, material science specialization, and delivery system convergence.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Gerresheimer AG |
| West Pharmaceutical Services, Inc. |
| Westar Medicorp Limited |
| Stevanato Group |
| AptarGroup, Inc. |
| SCHOTT AG |
| Daikyo Seiko, Ltd. |
| Datwyler Holding Inc. |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification tiers bifurcate elastomeric closures into premium silicone formulations commanding extended qualification cycles and commodity EPDM alternatives competing on unit economics, with this divergence mapping directly onto supply chain configurations where REACH-compliant German compounding clusters serve FDA-validated buyers while Asian toll manufacturers feed cost-sensitive multi-dose vial producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates elastomeric closures, with platinum-cured silicone stoppers for monoclonal antibodies separating sharply from halobutyl alternatives for insulin vials and natural rubber plugs for diagnostics. Price differentiation rests on USP Chapter 381 compliance depth and extractables testing documentation. Cost compression in uncoated EPDM segments is intensifying because fluoropolymer-coated alternatives from Japanese suppliers capture high-value biologics share. CDMO procurement teams in Massachusetts exhibit lowest price sensitivity due to combined qualification protocol lock-in, while Indian domestic injectable manufacturers remain most sensitive to per-unit landed costs.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA container closure guidance and EMA centralized authorization reviews force pharmaceutical buyers to qualify redundant suppliers across Germany, Switzerland, and the United States. Raw material dependencies center on halobutyl rubber feedstock from US Gulf Coast petrochemical complexes, platinum catalysts for silicone curing, and fluoropolymer resins for coated stopper applications. Single-source vulnerability concentrates in specialized compounding expertise for cryogenic-compatible formulations. Distribution runs through validated cold-chain logistics networks serving Boston-Cambridge and Basel biotech manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in elastomeric closures stem from reformulation investments that capture premium positioning as EU F-Gas Regulation phases out conventional processing aids, shifting buyer preference toward compliant suppliers with validated alternative chemistries.
For Market Incumbents: Lock in CDMO relationships through dedicated manufacturing lanes and real-time inventory visibility systems that match consolidated procurement patterns in the Boston-Cambridge corridor. Invest in captive halobutyl compounding capacity to defend against fluoropolymer substitution threats from Japanese coating specialists. Prioritize REACH-compliant curing agent validation to secure first-mover positioning as EU chemical restrictions tighten. For New Entrants and Emerging Players: Contract development and manufacturing organizations represent the most penetrable channel partner type for qualification-light closure variants targeting Indian pharmaceutical manufacturing expansion. Target Maharashtra and Gujarat injectable production zones where CDSCO alignment with ICH guidelines creates pathways for Western-validated suppliers. Pursue serum tube and diagnostic plug segments where friction-control specifications remain less stringent than biologics applications. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European specialists possessing REACH-compliant formulation infrastructure but lacking integrated packaging systems scale. Long-term viability favors acquisition targets with demonstrated cryogenic elasticity retention below -150°C and established EMA filing support capabilities. Watch for inflection signals in cell therapy cold chain capacity buildouts across Swissmedic-regulated manufacturing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halobutyl Compounding | Captive feedstock control reduces dependency on US Gulf Coast petrochemical supply volatility. |
| Fluoropolymer Coating Capacity Expansion | Daikyo Seiko's technology leadership in high-purity biologics applications commands premium positioning. |
| Integrated Closure-Vial System Development | Combined qualification protocols lock in supplier relationships through modular packaging configurations. |
| Cryogenic Formulation R&D Investment | Cell therapy storage below -150°C demands specialized elastomer grades with retained elasticity. |
| Indian Regulatory Alignment Partnership | CDSCO ICH guideline convergence creates procurement pathways for Western-qualified closure suppliers. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with pharmaceutical packaging procurement managers, regulatory affairs specialists at elastomer manufacturers, CDMO supply chain directors, and formulation chemistry consultants. Secondary validation draws from FDA container closure guidance documents, EMA centralized marketing authorization submissions, USP pharmacopeial revision notices, and trade data on halobutyl rubber imports. Bottom-up demand modeling triangulates against top-down pharmaceutical production capacity estimates.
Rate-of-change decomposition across the analysis window segments volume and value by product type, material grade, end-user industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves for biologics packaging, GLP-1 therapy expansion trajectories, and cold chain infrastructure investment patterns. Industry-specific forecast inputs include prefilled syringe format displacement rates and EU F-Gas Regulation compliance timelines for processing aid reformulation.
Revisions become necessary when regulatory harmonization between USP, EP, and JP test methods accelerates or stalls, when fluoropolymer coating technology achieves cost parity with uncoated alternatives, or when CDMO consolidation patterns shift procurement concentration beyond current Boston-Cambridge dominance. Deviation in REACH chemical restriction enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Snap-On Closures Market