
 Syringe Labels Market | 2026-2036
Syringe Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Syringe Labels Market Analytics
Modular label-to-syringe bundling is repositioning how procurement teams evaluate total cost of ownership in high-volume injection settings. Schreiner MediPharm leverages its deep specialization in pharmaceutical serialization to anchor premium positioning across European hospital networks. Avery Dennison competes through material science leadership, particularly in adhesive formulations that withstand cryogenic storage conditions essential for mRNA distribution. CCL Industries dominates in North American pharmacy and diagnostic laboratory channels through extensive manufacturing scale and regulatory compliance infrastructure.
Syringe labels are pressure-sensitive or heat-transfer substrates applied to glass or polymer syringe barrels to convey drug identity, dosage, expiration, and traceability data, typically incorporating tamper-evident features and barcoded serialization to satisfy supply chain integrity requirements. Self-adhesive formats lead volume due to compatibility with existing high-speed applicator equipment across fill-finish lines, while heat transfer labels represent the fastest-growing category as biologics manufacturers seek permanent marking solutions that resist alcohol swabbing and gamma sterilization. Material selection stratifies across application risk tiers, with PET commanding preference in vaccination and blood collection workflows for its chemical resistance, and paper substrates retaining share in short-rotation diagnostic applications where cost sensitivity dominates.
The FDA enforces label content and format standards through drug approval processes and cGMP inspections, while the EMA's Falsified Medicines Directive mandates unique identifier integration that directly shapes European label specification requirements. ISO 13485 quality management certification and EU MDR technical documentation obligations further constrain supplier qualification, filtering market access toward manufacturers with validated cleanroom production environments. Stakeholders must monitor evolving DSCSA implementation timelines and emerging AI-assisted visual inspection requirements that could redefine acceptable defect thresholds for printed variable data on syringe labels.
Market Dynamics
Serialization mandates from the FDA's DSCSA and EMA's Falsified Medicines Directive are forcing biopharmaceutical manufacturers to replace legacy label infrastructure with track-and-trace capable systems, compressing supplier qualification timelines and concentrating procurement among validated cleanroom producers.
Growth Catalysts
- mRNA Cold Chain Expansion:Cryogenic storage requirements for lipid nanoparticle formulations are pulling demand for adhesive chemistries that maintain bond integrity at sub-zero temperatures through distribution networks.
- Track-and-Trace Mandates:The FDA's Drug Supply Chain Security Act deadlines are compelling fill-finish facilities to upgrade applicator lines for serialized, tamper-evident label formats.
- Specialty Pharmacy Proliferation:United States hospital systems are accelerating procurement of temperature-indicating labels for high-value injectable therapies administered in outpatient settings.
Market Restraints
- Adhesive Raw Material Volatility:Acrylic resin and silicone feedstock prices fluctuate with petrochemical markets, squeezing margin structures for pressure-sensitive label converters.
- Cleanroom Production Concentration:ISO 13485-certified manufacturing capacity clusters in Western Europe and the United States, creating geographic supply risk for Asian fill-finish customers.
- Gamma Sterilization Compatibility Limits:Paper substrates yellow and embrittle under ionizing radiation, restricting their use in terminally sterilized single-use syringe applications.
Strategic Opportunities
- Indian Biologics Manufacturing:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting contract manufacturing investment requiring serialization-ready label supply.
- Smart Label Convergence:Integration of NFC chips and printed sensors with conventional pressure-sensitive substrates enables real-time cold chain verification for temperature-sensitive biologics.
- Direct-to-Patient Distribution:Specialty pharmacies are bypassing wholesale channels, creating demand for patient-centric label formats with enhanced readability and handling instructions.
Industry Challenges
- Serialized Data Verification Talent:Shortage of technicians trained in aggregation hierarchy management and line-level vision system validation is extending commissioning timelines for new label applicators.
- EU MDR Technical Documentation Burden:Extended supplier audit cycles and clinical evidence requirements are delaying label qualification for Class III device syringe combinations.
- Legacy ERP Integration Friction:Track-and-trace data exchange between modern serialization platforms and established manufacturing execution systems requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringe Labels Market |
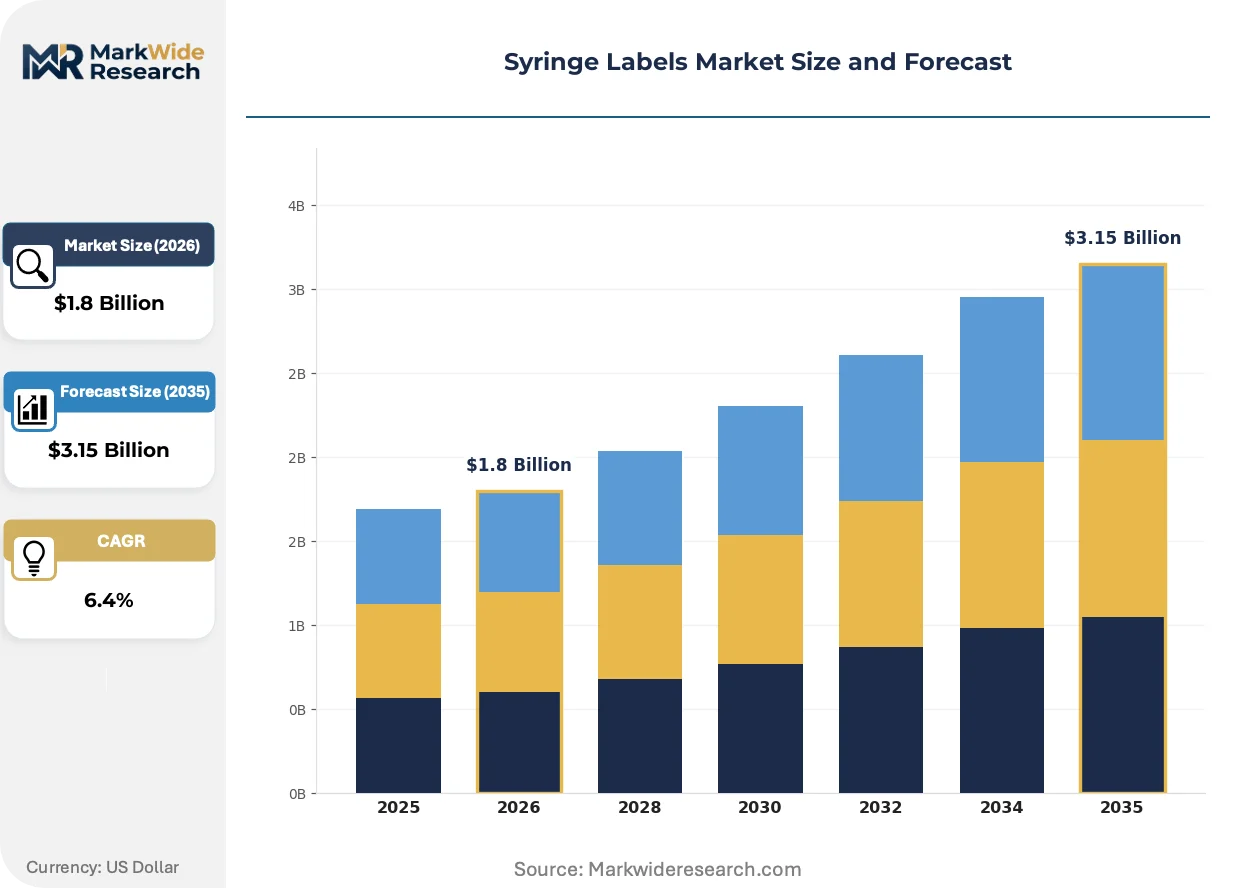
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Pre-Printed, Blank, Heat Transfer Material: PVC, PET, Paper, Polypropylene End User: Hospitals, Clinics, Pharmacies, Laboratories Application: Medication, Vaccination, Diagnostic, Blood Collection |
| Companies Covered | Avery Dennison, CCL Industries, Schreiner MediPharm, Herma, Multi-Color Corporation, SATO Holdings, Essentra, Hospicode, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringe Labels Market Evolving Landscape
Digital printing and automated inspection systems are compressing production lead times while regulatory mandates harden data integrity requirements. Material science advances are expanding the operational envelope for labels in extreme storage conditions.
Laser-marking systems paired with machine vision verification are automating variable data application on glass and polymer syringe barrels. Biologics manufacturers in the United States and Germany are retrofitting fill-finish lines to eliminate mechanical printing stations. This convergence is automating defect detection at speeds exceeding 600 units per minute, reducing reliance on manual sampling protocols.
REACH restrictions on per- and polyfluoroalkyl substances are compelling adhesive reformulation across European supply chains. Manufacturers must validate alternative chemistries that maintain release liner performance without fluorinated silicones. Small-molecule injectable producers in Germany and Switzerland are experiencing extended qualification timelines as they test substitute materials for alcohol swab resistance.
Consolidated buying by United States health system purchasing organizations is compressing supplier margins while demanding enhanced service tiers. Group purchasing organizations now require dedicated inventory programs and same-day technical support for label specification changes. This concentration is visible most acutely in oncology and autoimmune therapeutic categories where syringe labels must accommodate frequent dosing regimen updates.
Syringe Labels Market Segmentation
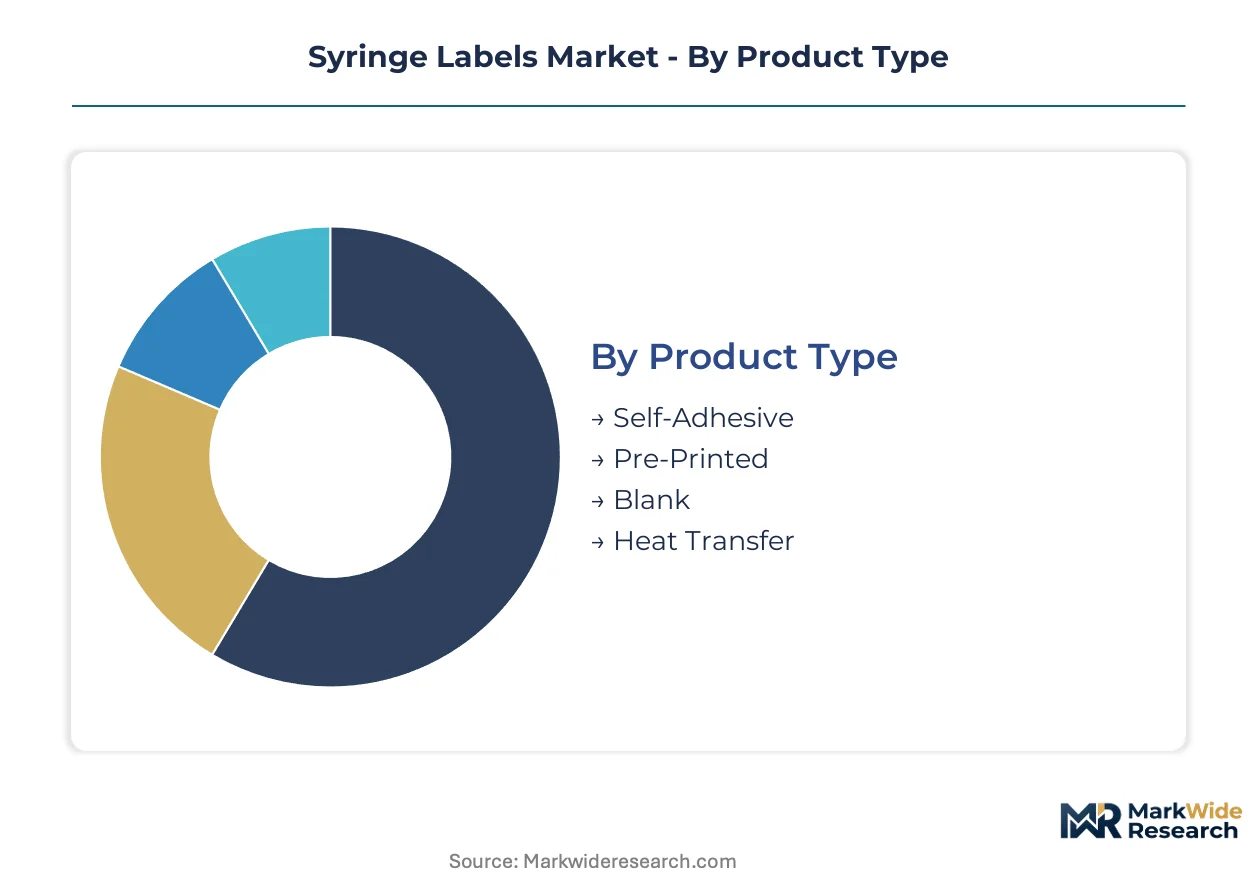
Syringe label procurement stratifies across four dimensions that determine capital allocation, regulatory burden, and margin structure. Material selection and product format drive equipment investment, while end-user channel and application dictate compliance intensity and volume concentration.
Product Type:
Capital intensity peaks with serialized, tamper-evident formats requiring validated applicator lines and vision inspection systems, while commodity blank labels demand minimal upfront tooling.
- Self-Adhesive:Pressure-sensitive substrates with release liners bond to syringe barrels through automated applicators running at fill-finish line speeds. Biopharmaceutical manufacturers in the United States deploy these formats for mRNA vaccines, with adhesive chemistries validated for cryogenic storage through distribution networks.
- Heat Transfer:Permanent marking systems fuse resin-based inks directly onto polymer or glass surfaces through thermal transfer heads. German biologics producers are retrofitting lines with laser-verified heat transfer stations to eliminate mechanical printing and survive gamma sterilization cycles.
- Pre-Printed:Serialized labels with fixed graphics and variable data zones reduce line-side complexity for high-volume injectable producers.
- Blank:Unprinted substrates for on-demand thermal or laser marking in low-volume or customized dosing scenarios.
Most installed capacity flows through Self-Adhesive. Expansion is steepest in Heat Transfer.
Material:
Material selection maps directly to sterilization method and storage temperature, with premium synthetics commanding price multiples over paper for terminal sterilization compatibility.
- PET:Polyester films deliver chemical resistance and dimensional stability across alcohol swabbing, gamma irradiation, and sub-zero storage. United States vaccination workflows and blood collection networks specify PET for multi-year stability requirements.
- Paper:Cellulose-based substrates with acrylic or hot-melt adhesives serve short-rotation diagnostic applications where cost sensitivity outweighs sterilization demands. Diagnostic laboratories in India and Southeast Asia specify paper for rapid-turnaround test kits with limited shelf life.
- PVC:Flexible vinyl films conform to curved syringe barrels in manual-application settings.
- Polypropylene:Olefin films balance moisture resistance with heat-seal compatibility for peel-open pouch configurations.
PET captures the highest value per square meter. Polypropylene is gaining share fastest in pre-filled syringe formats.
End User:
Procurement sophistication diverges sharply, with hospital systems demanding inventory programs and same-day specification support while laboratories prioritize cost minimization over service tiers.
- Hospitals:Integrated delivery networks and specialty pharmacy units within United States health systems procure temperature-indicating, tamper-evident labels for high-value biologics administered in outpatient infusion centers.
- Pharmacies:Retail and specialty pharmacy chains in Germany and France require patient-centric formats with enhanced readability and handling instructions for direct-to-patient distribution.
- Clinics:Ambulatory care settings specify standard pressure-sensitive formats for routine immunization and therapeutic injection.
- Laboratories:Diagnostic and research facilities prioritize cost-optimized substrates for non-sterile or single-use consumable applications.
Hospitals concentrate the highest service-margin revenue. Pharmacies are expanding procurement most quickly as direct-to-patient channels bypass wholesale intermediaries.
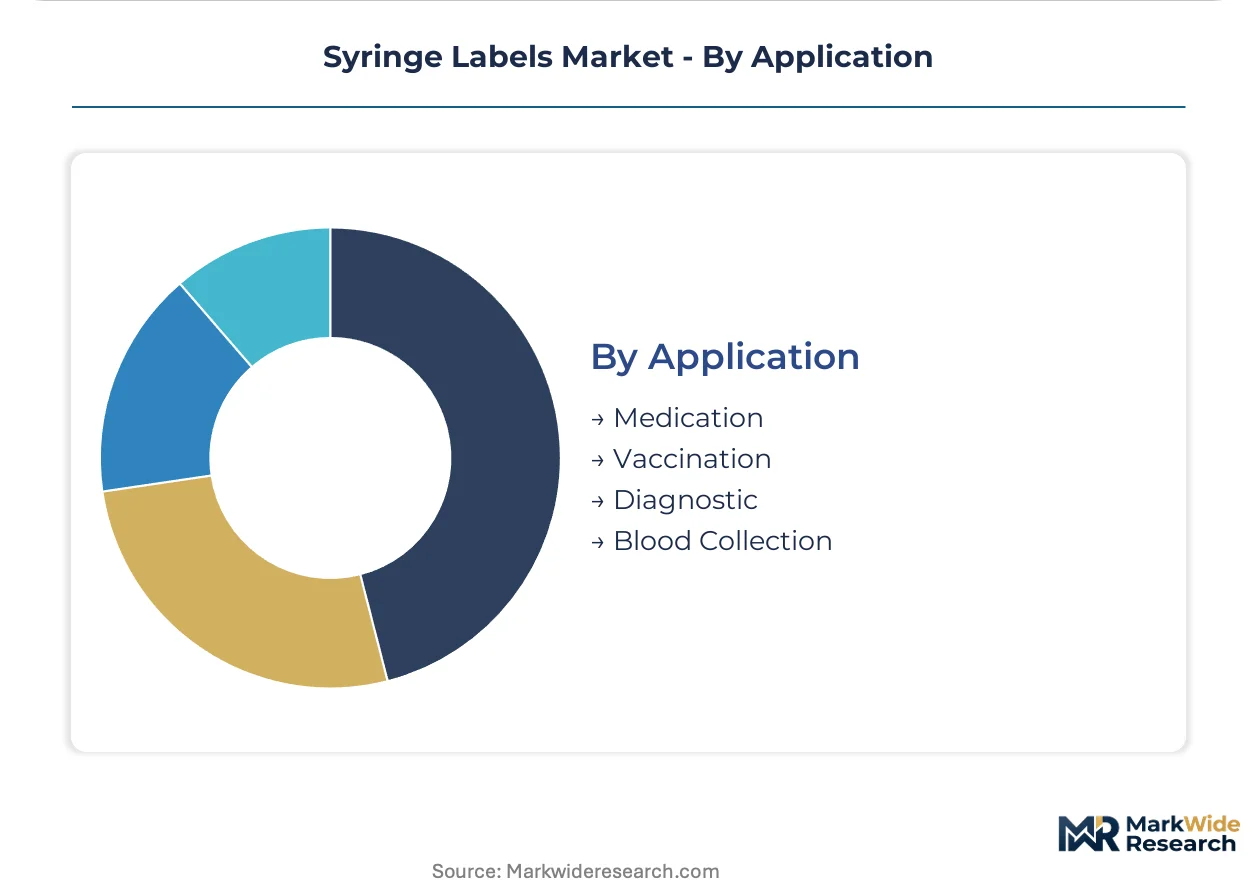
Application:
Regulatory stringency escalates from diagnostic through medication to vaccination and blood collection, with serialization mandates and traceability requirements tightening proportionally.
- Medication:Injectable therapeutics for oncology and autoimmune conditions require serialized, tamper-evident labels with space for frequent dosing regimen updates. United States specialty pharmacies and hospital systems drive specification complexity.
- Vaccination:Mass immunization programs demand high-volume, multi-language formats with cold chain indicators. National health authorities in India and Brazil specify PET-based labels for extended stability through variable storage conditions.
- Diagnostic:In-vitro and point-of-care test kits use cost-optimized paper or polypropylene labels with limited variable data fields.
- Blood Collection:Vacutainer and syringe-based collection systems require durable substrates surviving centrifugation and refrigerated storage.
Medication commands the highest specification density. Vaccination is climbing the fastest as national immunization programs expand serialization infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Syringe label manufacturing first industrialized in German pharmaceutical packaging clusters during the 1970s, then migrated to North American health system supply chains as FDA serialization mandates took hold. Production geography now tracks biopharmaceutical fill-finish capacity, with validated cleanroom sites concentrating near major drug manufacturing hubs.
United States
Hospital systems and specialty pharmacies drive procurement of temperature-indicating, tamper-evident formats for high-value biologics administered in outpatient infusion centers. The FDA's DSCSA implementation deadlines force fill-finish facilities to upgrade applicator lines for serialized labels. The Philadelphia-Camden corridor hosts concentrated label converting capacity serving Pennsylvania and New Jersey biomanufacturing zones.
Germany
Biologics manufacturers retrofit fill-finish lines with laser-verified heat transfer stations to eliminate mechanical printing and survive gamma sterilization cycles. The EMA's Falsified Medicines Directive mandates unique identifier integration that shapes European label specifications. The Rhine-Main cluster around Frankfurt anchors serialization-ready label production for export to EU hospital networks.
India
CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives attract contract manufacturing investment requiring serialization-ready label supply. Domestic converters expand ISO 13485-certified capacity to serve emerging biologics fill-finish sites. The Hyderabad-Bangalore corridor concentrates new cleanroom label production for export to regulated markets.
Switzerland
Swissmedic's stringent device-drug combination requirements filter supplier qualification toward manufacturers with validated cleanroom environments and extended technical documentation capabilities. REACH restrictions on per- and polyfluoroalkyl substances compel adhesive reformulation across Swiss supply chains. The Basel region hosts specialized label converters integrated with neighboring German and French pharmaceutical manufacturing.
China
NMPA's evolving track-and-trace regulations for injectable pharmaceuticals drive domestic label infrastructure upgrades alongside imported serialization technology. Local converters develop cryogenic-compatible adhesive formulations for mRNA vaccine distribution. The Yangtze River Delta around Shanghai concentrates advanced label manufacturing serving both domestic biopharmaceutical producers and export markets.
Syringe Labels Market Competitive Landscape
The competitive structure tilts toward material science specialists with validated pharmaceutical serialization capabilities. Three tiers operate: global converters with multi-continent manufacturing footprints, regional specialists with deep regulatory expertise in single geographies, and niche players focused on extreme-environment adhesive formulations. Consolidation pressure intensifies as health system purchasing organizations demand inventory programs and same-day technical support. Dominant competitive moves include backward integration into adhesive resin production and strategic partnerships with vision system integrators for automated inspection.
Among European-based pharmaceutical packaging specialists, Schreiner MediPharm and Herma occupy positions anchored in serialization and regulatory compliance infrastructure. CCL Industries and Multi-Color Corporation represent North American scale-driven converters with extensive manufacturing footprints across pharmacy and diagnostic laboratory channels. Avery Dennison exemplifies material science leadership through adhesive formulations engineered for cryogenic storage conditions essential for mRNA distribution networks.
| Leading Market Players |
|---|
| Avery Dennison |
| CCL Industries |
| Schreiner MediPharm |
| Herma |
| Multi-Color Corporation |
| SATO Holdings |
| Essentra |
| Hospicode |
| Amcor |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up label converters in the United States and Western Europe have consolidated ISO 13485-certified capacity, tightening supply discipline and compressing margin structures for mid-tier competitors serving hospital procurement networks. This ownership pattern concentrates pricing power among validated cleanroom producers while forcing smaller converters toward commodity diagnostic segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates serialized tamper-evident formats with full regulatory documentation from basic pressure-sensitive labels for diagnostic applications. Price differentiation hinges on ISO 13485 certification grade and volume commitment scale, with United States health system GPOs extracting steepest discounts through consolidated procurement. Cost compression in the standard tier is intensifying because acrylic resin feedstock volatility squeezes converter margins. Diagnostic laboratories in India and Southeast Asia exhibit highest price sensitivity, while German biologics manufacturers prioritize sterilization compatibility over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from United States and European biopharmaceutical manufacturers mandate multi-supplier qualification for serialized label formats, fragmenting procurement across validated cleanroom sites. Geographic supply concentration centers on Germany, the United States, and China, with adhesive resin production drawing from petrochemical feedstocks in the Gulf Coast and Rotterdam clusters. Supply chain risk rests on single-source vulnerability for cryogenic-compatible silicone adhesives essential for mRNA distribution. Distribution runs through fill-finish line integrators who bundle label applicators with vision inspection systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Syringe Labels Market functions as a stable compounder, with regulatory serialization mandates providing durable demand visibility across biopharmaceutical production cycles.
For Market Incumbents: Anchor market position through backward integration into adhesive resin production and captive supply of release liners, defending against margin erosion from petrochemical volatility. Expand ISO 13485-certified capacity in the Hyderabad-Bangalore corridor to capture contract manufacturing migration under India's PLI scheme. Prioritize partnerships with vision system integrators for automated inspection capabilities that hospital GPOs now require. For New Entrants and Emerging Players: Capture white-space opportunity in temperature-indicating smart labels for specialty pharmacy direct-to-patient distribution, where incumbent converters lack NFC sensor integration capabilities. Target Indian biosimilar contract manufacturers needing serialization-ready supply with faster qualification timelines than Western competitors. Lead with adhesive formulation expertise for gamma sterilization compatibility rather than competing on scale. For Investors and Strategic Acquirers: Material science specialists with validated pharmaceutical serialization capabilities are the most active acquirer in this space, consolidating regional converters to build multi-continent manufacturing footprints. The acquisition target archetype combines ISO 13485 certification with proprietary cryogenic adhesive chemistries. Watch for CDSCO regulatory harmonization with FDA serialization standards as the inflection signal for Indian manufacturing investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin Production | Captive supply of acrylic and silicone feedstocks insulates margin structures from Rotterdam and Gulf Coast petrochemical volatility. |
| ISO 13485 Certification Investment | Validated cleanroom production environments unlock access to FDA and EMA-mandated serialization contracts from biopharmaceutical manufacturers. |
| Smart Label Technology Partnership | NFC chip integration with pressure-sensitive substrates enables real-time cold chain verification for temperature-sensitive mRNA therapies. |
| Indian Manufacturing Footprint Expansion | Hyderabad-Bangalore corridor capacity captures CDSCO-aligned biosimilar contract manufacturing under PLI scheme incentives. |
| Vision System Integration Alliance | Automated inspection partnerships satisfy United States health system GPO requirements for defect detection exceeding 600 units per minute. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fill-finish operations directors, regulatory affairs managers at biopharmaceutical manufacturers, hospital GPO procurement leads, and label converter technical sales executives. Secondary validation draws from FDA DSCSA implementation guidance, EMA Falsified Medicines Directive documentation, CDSCO biosimilar approval pathway circulars, and SEC filings from publicly traded packaging converters. Bottom-up volume modeling triangulates against top-down pharmaceutical production forecasts.
Granularity-level framing applies product type, material substrate, end-user channel, and application-specific regulatory intensity as core segmentation dimensions modeled at the country-cluster level. CAGRs derive from trend extrapolation of fill-finish line investment cycles and serialization mandate implementation timelines. Industry-specific forecast inputs include mRNA cold chain expansion trajectories and REACH adhesive reformulation compliance schedules.
Regulatory timeline slippage, raw material supply disruption, and biopharmaceutical capital expenditure contraction are the dominant revision risks to the projection framework. Deviation in FDA or EMA serialization enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Water Dissolvable Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Global Waterproof Labels Market
Labels
GCC Labeling Market
Labels
Sustainable Labels Market
Labels
India Print Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Self-Laminating Tags Market
Labels
Sheeted Labels Market
Labels
Wrap Around Labels Market
Labels
Shrink Sleeve Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Pin Feed Labels Market
Labels
Repositionable Labels Market
Labels
Direct Thermal Linerless Labels Market