
 Argentina Container Glass Market | 2026-2036
Argentina Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Container Glass Market Insights
Modular bottle sizing and lightweighting configurations is recalibrating procurement patterns across Argentine beverage producers. Verallia Packaging Argentina S.A. leverages its furnace network to supply standardized neck finishes that reduce changeover downtime for filling lines. Rigolleau S.A. anchors the domestic vial segment through dedicated pharmaceutical-grade production. O-I Argentina competes on scale, operating multiple furnaces with capacity to serve both local brands and multinational exporters from its Argentine base.
Container glass comprises silica-soda-lime formulations melted at approximately 1500°C and formed through blow-and-blow or press-and-blow processes to create impermeable, chemically inert packaging for liquids and solids. The material's zero-porosity barrier protects product integrity across extended shelf lives in food, pharmaceutical, and cosmetic applications. Bottles dominate the product type landscape, carrying the bulk of wine and beer volumes, while jars capture margin pools in premium food preservation and artisanal packaging. Clear glass leads form demand for product visibility, though colored variants gain traction in UV-sensitive categories like olive oil and certain pharmaceutical formulations.
Argentina's national food safety authority enforces food-contact compliance standards that govern batch composition and surface migration limits for all glass destined for edible contents. The Secretary of Industry and Commerce oversees domestic manufacturing certifications that affect import substitution incentives and local content requirements for publicly supported projects. Stakeholders must monitor evolving extended producer responsibility frameworks and energy tariff structures that could reshape furnace economics and regional supply priorities.
Market Dynamics
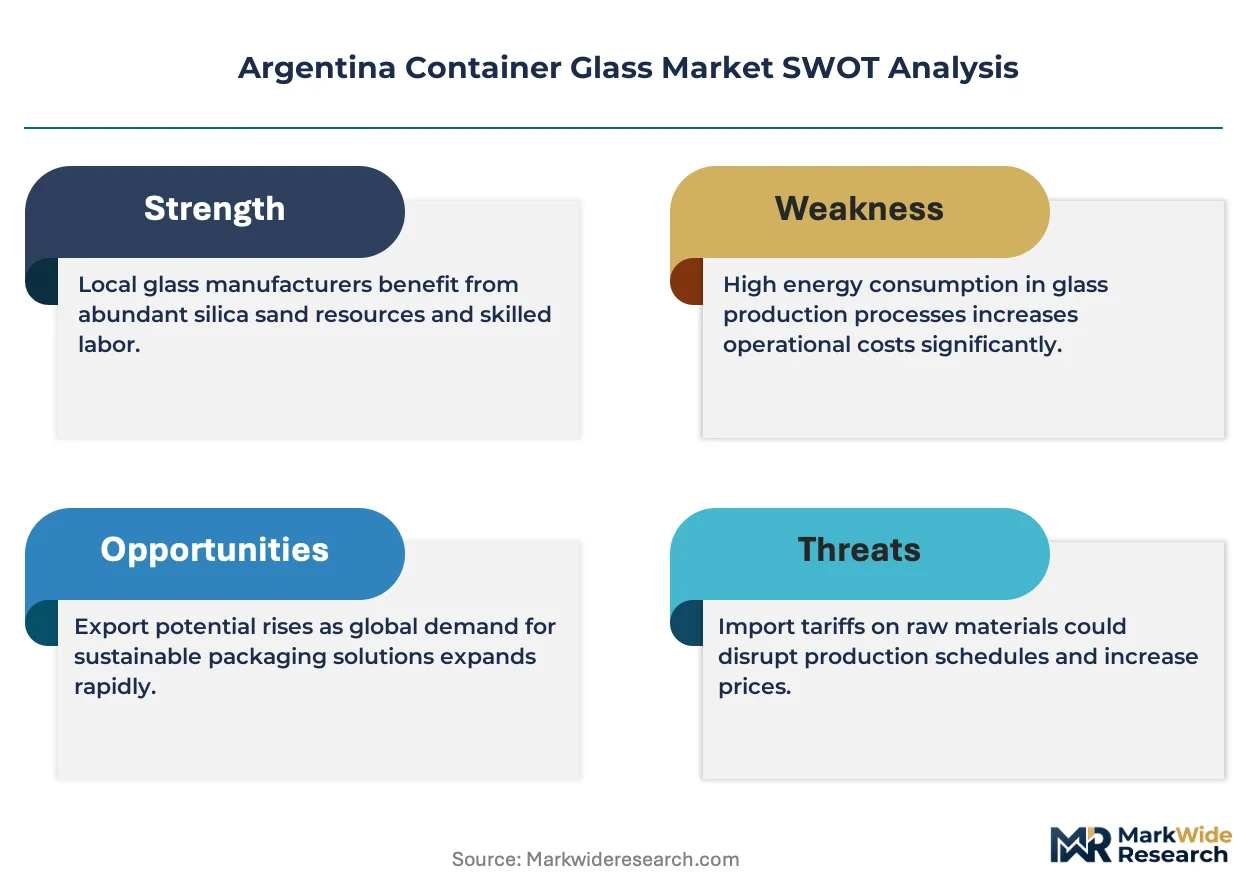
Argentina's container glass sector faces furnace economics recalibration as natural gas tariff volatility compresses operating margins and forces capacity consolidation among legacy producers.
Growth Catalysts
- Export-oriented wine sector expansion:Mendoza-based bodegas are scaling custom amber and flint glass procurement for premium bottled exports, pulling dedicated furnace capacity toward specialty finishes.
- Food-contact compliance mandates:The Secretary of Industry and Commerce enforces batch formulation certification that locks out uncertified imports and secures domestic converter market share.
- Lightweighting process innovation:Modular bottle sizing standardization reduces filling line changeover downtime and cuts per-unit material throughput for Argentine beverage producers.
Market Restraints
- Natural gas input cost volatility:Furnace operations depend on subsidized hydrocarbon pricing that fluctuates with federal fiscal adjustments, destabilizing production cost forecasting.
- Silica sand supply concentration:Domestic high-purity silica sourcing clusters in San Luis and Córdoba provinces, creating geographic vulnerability to regional logistics disruptions.
- Aluminum can substitution pressure:Beer and soft drink bottlers are testing metal alternatives for single-serve formats, threatening volume retention in standard bottle categories.
Strategic Opportunities
- Pharmaceutical-grade vial underpenetration:Rigolleau S.A. currently anchors this segment, leaving white space for furnace operators to add dedicated borosilicate and tubular glass capacity.
- Extended producer responsibility frameworks:Pending federal packaging waste legislation would mandate post-consumer cullet collection infrastructure, creating captive recycled material streams for compliant producers.
- Digital printing-blow molding convergence:Direct-to-glass decoration technology enables short-run customization for craft spirits brands without label substrate costs.
Industry Challenges
- Specialized furnace engineering talent scarcity:Argentina's technical institutes produce limited glass-ceramic engineering graduates, constraining operational optimization and maintenance scheduling.
- Import substitution certification timelines:Local content verification for publicly supported projects requires extensive documentation that delays contract awards and capacity allocation decisions.
- Legacy batch house system integration:Automated raw material handling upgrades must interface with decades-old silo infrastructure, complicating precision formulation control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Container Glass Market |
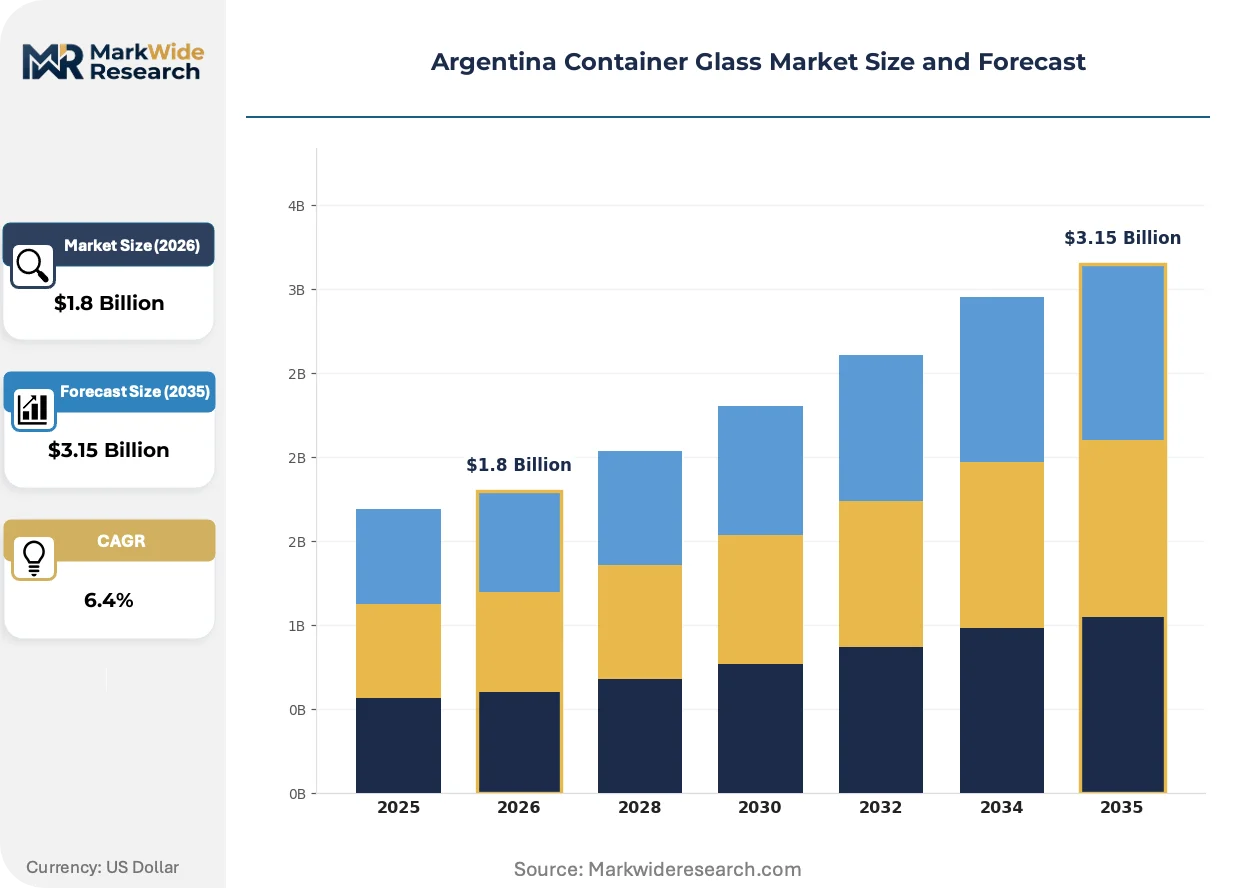
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Jugs End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Form: Clear, Colored, Frosted, Textured Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Verallia Packaging Argentina S.A., Cattorini Hermanos, Rigolleau S.A., Domingo Mangone S.A., O-I Argentina, Ardagh Group, Nueva Cristalería Rosario, MOMA Food S.R.L., Micro Envases S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Container Glass Market Trends and Innovations
Active furnace technology upgrades and regulatory compliance automation are compressing production economics while reshaping buyer-supplier contracting structures across Argentine glass manufacturing.
Electrical boosting systems in hybrid furnace designs are converging with oxy-fuel combustion to cut carbon intensity per ton of melted glass. Mendoza wine corridor bottlers are piloting these configurations to meet export market sustainability verification requirements. The structural consequence is a bifurcation between capital-renewed furnaces qualifying for premium supply contracts and gas-dependent legacy assets facing margin compression.
Argentina's national food safety authority is tightening surface migration testing protocols for all glass contacting edible contents. Batch composition documentation and leachate testing are now mandatory pre-shipment requirements. Pharmaceutical and premium olive oil segments are absorbing compliance costs fastest, driving supplier consolidation toward certified furnace operators with in-house laboratory capacity.
Direct mill-to-bodega procurement contracts are displacing traditional distributor intermediation in Mendoza's wine packaging supply chain. Large export-oriented wineries are negotiating multi-year volume commitments with furnace operators in exchange for dedicated color runs and embossed mold exclusivity. This pattern concentrates most visibly in Luján de Cuyo and Maipú sub-regions where foreign-owned bodegas command procurement scale.
Argentina Container Glass Market Segmentation
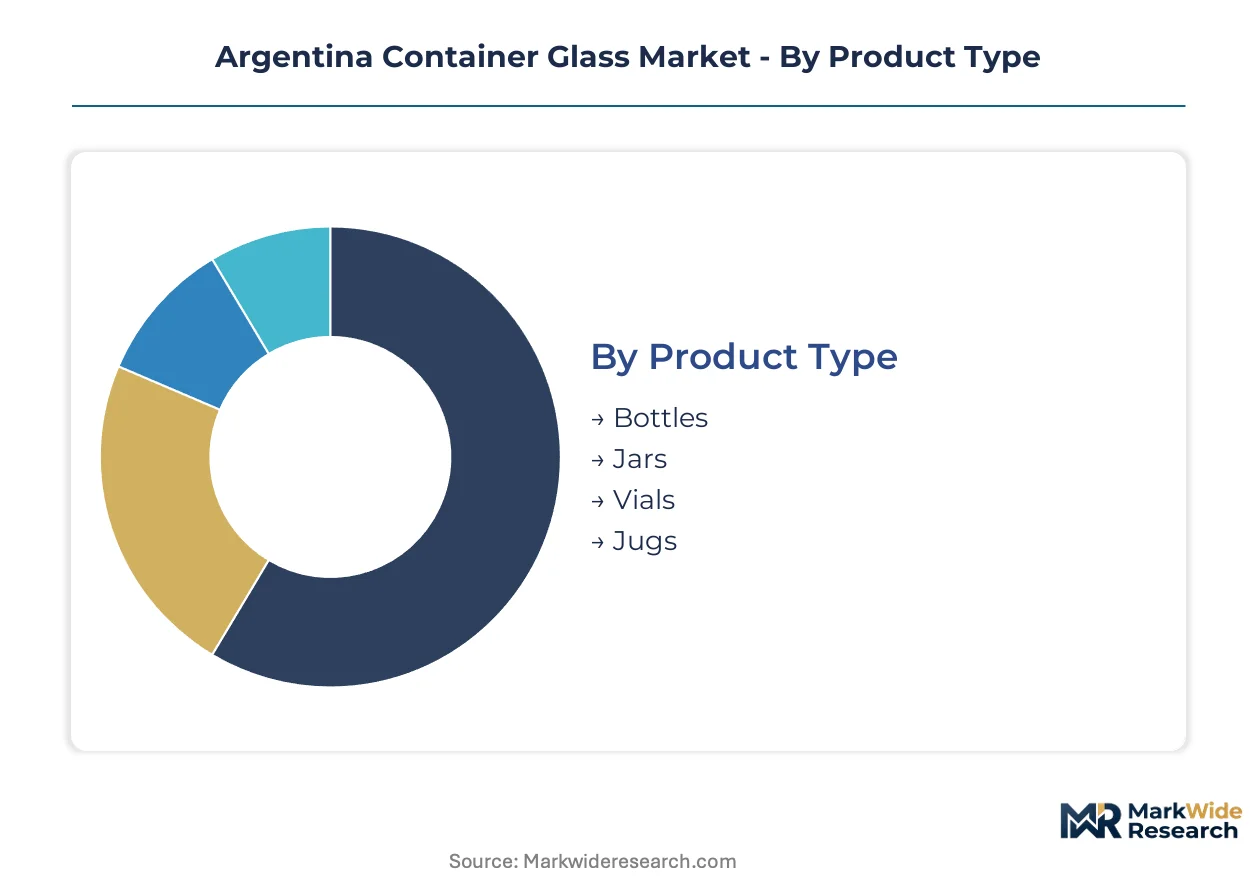
Segmentation in Argentina's container glass market reveals distinct procurement patterns across product configurations and end-use applications. Wine exporters in Mendoza drive specialized bottle demand, while pharmaceutical-grade vial specifications anchor premium margin pools. Understanding these segment boundaries enables furnace operators to optimize batch formulations and color run scheduling.
Product Type:
Standalone packaging formats dominate beverage and pharmaceutical applications, while embedded systems integration remains minimal in this sector.
- Bottles:Silica-soda-lime formulations formed through blow-and-blow processes carry wine, beer, and spirits volumes across Argentine beverage production. Mendoza-based bodegas source custom amber and flint variants for premium export lines, pulling dedicated furnace capacity toward specialty embossed finishes.
- Jars:Wide-mouth press-and-blow configurations preserve food integrity in premium olive oil and artisanal packaging segments. The Secretary of Industry and Commerce enforces food-contact compliance testing that locks procurement toward certified domestic converters with in-house laboratory capacity.
- Vials:Pharmaceutical-grade borosilicate and tubular glass serve injectable and diagnostic applications under strict national health authority protocols.
- Jugs:High-capacity formats target bulk household and institutional liquid storage with standardized neck finishes for dispensing systems.
Bottles lead volumes today; vials are gaining share fastest.
End User:
Cost tier stratification separates commodity beverage procurement from premium pharmaceutical and cosmetic specifications.
- Food & Beverage:Wine, beer, and olive oil bottlers constitute the dominant demand base, with export-oriented producers absorbing compliance costs for international market access. Natural gas tariff volatility compresses operating margins across this price-sensitive segment.
- Pharmaceuticals:Injectable drug packaging and diagnostic containers require borosilicate durability and surface migration certification under national health authority protocols. Rigolleau S.A. anchors this high-margin segment through dedicated production lines.
- Cosmetics:Frosted and textured glass variants serve premium skincare and fragrance positioning, with shorter production runs favoring flexible furnace scheduling.
- Household:Standard jars and jugs for cleaning products and bulk storage compete on material throughput efficiency rather than specialized finishes.
Food & Beverage commands absolute volume; Pharmaceuticals delivers the steepest expansion trajectory.
Form:
Application requirements determine optical and barrier property specifications across UV-sensitive and visibility-driven categories.
- Clear:Maximum transparency supports product visibility for premium olive oils, spirits, and cosmetics where consumer inspection drives purchase decisions.
- Colored:Amber and green variants protect UV-sensitive wine, beer, and pharmaceutical formulations from light degradation during extended shelf life.
- Frosted:Acid-etched surface treatments differentiate premium cosmetic and spirits positioning without label substrate costs.
- Textured:Embossed and specialty-finish surfaces enable brand differentiation for craft spirits and artisanal food producers in Mendoza's export corridor.
Clear glass dominates current procurement; Colored variants are climbing the fastest as UV-protection awareness spreads.
Distribution Channel:
Volume scale separates direct mill-to-bodega contracting from fragmented retail and wholesale intermediation.
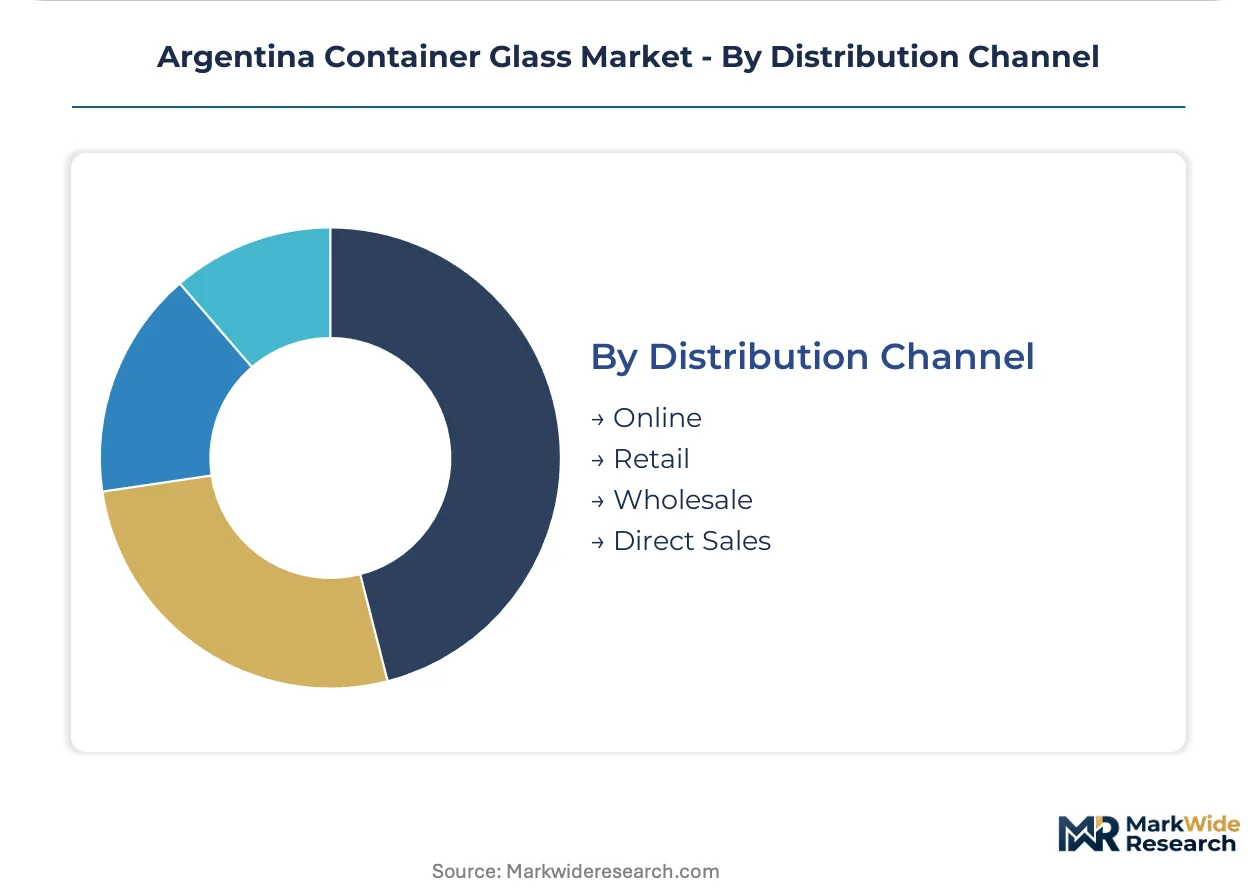
- Online:Digital platforms serve small-batch craft producers and regional distributors with modular sizing and short-run customization capabilities.
- Retail:Hardware and packaging supply stores cater to artisanal food producers and household buyers with standardized jar and bottle inventories.
- Wholesale:Regional distributors aggregate demand from mid-sized beverage producers unable to meet direct furnace minimum order quantities.
- Direct Sales:Large export-oriented wineries in Luján de Cuyo and Maipú negotiate multi-year volume commitments with furnace operators for dedicated color runs and mold exclusivity.
Direct Sales captures the largest contract values; Online channels are expanding most quickly among craft producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's container glass industry traces its modern foundation to post-war industrialization in the 1940s-1950s, when state-led development established furnace capacity to serve domestic beverage and food preservation demand. Regional production gravity now concentrates in specific sub-regions where raw material access, wine export infrastructure, and regulatory enforcement intersect.
Mendoza Province
Export-oriented bodegas in Luján de Cuyo and Maipú drive specialized amber and flint glass procurement for premium wine bottling. The Secretary of Industry and Commerce enforces batch formulation certification that locks procurement toward domestic converters. Furnace operators in Guaymallén and Godoy Cruz supply custom embossed finishes for foreign-owned wineries.
Buenos Aires Province
Pharmaceutical-grade vial demand anchors high-margin production in Greater Buenos Aires industrial corridors. The national food safety authority mandates surface migration testing for all glass contacting edible contents. San Martín and La Matanza host dedicated borosilicate capacity serving injectable drug packaging under strict health authority protocols.
Córdoba Province
High-purity silica sand deposits in the Sierras de Córdoba supply critical raw material for batch formulations across Argentine furnace networks. The central government oversees domestic manufacturing certifications affecting import substitution incentives. Villa María and Río Cuarto process silica for distribution to glass plants nationwide.
San Luis Province
Quartzite mining operations in the Sierras de San Luis provide secondary silica sourcing for container glass batch houses. Provincial mining regulations govern extraction permits and environmental compliance for open-pit operations. Villa de Merlo and Juana Koslay concentrate crushing and screening infrastructure for furnace-ready sand.
Santa Fe Province
Rosario's port infrastructure enables cullet import and export logistics for recycled glass supply chains. Pending federal extended producer responsibility legislation would mandate post-consumer collection infrastructure. Nueva Cristalería Rosario operates furnace capacity serving regional beverage and food producers.
Argentina Container Glass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and furnace technology vintage. The Argentine container glass sector structures around three operational archetypes: multinational furnace networks with dedicated export capacity, domestic specialists in pharmaceutical-grade vial production, and regional converters serving price-sensitive beverage markets. Competitive moves concentrate on multi-year procurement contracting with Mendoza wineries and automated batch house upgrades to meet tightening food-contact compliance mandates.
Among multinational furnace operators, Verallia Packaging Argentina S.A., O-I Argentina, and Ardagh Group exemplify scale-driven archetypes with capacity to serve both local brands and export-oriented producers. Rigolleau S.A. occupies a distinct position as a domestic specialist anchoring the pharmaceutical-grade vial segment. Cattorini Hermanos and Domingo Mangone S.A. represent mid-tier regional converters with established positions in standard bottle categories. These five entities collectively illustrate the competitive spectrum from premium-certified specialty production to commodity beverage supply.
| Leading Market Players |
|---|
| Verallia Packaging Argentina S.A. |
| Cattorini Hermanos |
| Rigolleau S.A. |
| Domingo Mangone S.A. |
| O-I Argentina |
| Ardagh Group |
| Nueva Cristalería Rosario |
| MOMA Food S.R.L. |
| Micro Envases S.A. |
| Others |
Pricing and Supply Chain Analysis
Hybrid furnace technology adoption across Argentine glass plants is compressing energy costs for capital-renewed operators while stranding gas-dependent legacy assets, concentrating supply power among furnace networks with electrical boosting capabilities and tightening price competition for commodity bottle tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade borosilicate vials from certified food-contact bottles and commodity beverage containers. Price differentiation hinges on batch formulation certification under Secretary of Industry and Commerce mandates and furnace technology vintage. Cost compression in standard beer and soft drink bottle tiers is intensifying because aluminum can substitution pressures volume retention. Export-oriented wineries in Mendoza exhibit the lowest price sensitivity, while regional beverage converters serving domestic markets absorb the steepest margin pressure.
Supply Chain Analysis
Glass-ceramic engineering talent shortages in Buenos Aires and Mendoza provinces constrain operational optimization and maintenance scheduling for automated batch house upgrades. Supply concentrates in Argentina's furnace networks, with critical silica sand sourcing from San Luis and Córdoba provinces and boron compounds imported for pharmaceutical-grade formulations. Single-source vulnerability runs through the San Luis quartzite corridor where open-pit mining permits face environmental compliance delays. Distribution runs through direct mill-to-bodega contracting for large wineries and wholesale intermediation for mid-sized beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's container glass market functions as a stable compounder anchored by structural import substitution mandates that permanently advantage domestic certified converters over uncertified imports.
For Market Incumbents: Lock in multi-year procurement contracts with Mendoza export-oriented bodegas before pending extended producer responsibility legislation reshapes cullet collection economics. Prioritize automated batch house upgrades to meet tightening surface migration testing protocols from the national food safety authority. Vertical integration into captive silica sand processing in Córdoba Province secures formulation control against logistics disruptions. For New Entrants and Emerging Players: The mid-tier pricing gap between Rigolleau's pharmaceutical-grade vial premiums and commodity beverage bottle margins offers white-space entry for borosilicate capacity targeting diagnostic container demand. Pharmaceutical-grade tubular glass for injectable applications represents the most penetrable segment given single-supplier concentration. A go-to-market angle anchored on dedicated laboratory certification capacity bypasses incumbent batch formulation documentation advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with established distributor relationships because import substitution certification timelines create acquisition barriers for greenfield entrants. Target mid-tier furnace operators in Santa Fe and Córdoba with legacy assets suitable for hybrid technology retrofit. Watch natural gas tariff adjustment announcements as the inflection signal for margin compression acceleration across gas-dependent production tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Hybridization Investment | Electrical boosting systems qualify operators for premium Mendoza wine corridor supply contracts under export sustainability verification. |
| Batch House Automation Upgrade | Precision formulation control meets Secretary of Industry and Commerce food-contact compliance mandates for pharmaceutical segments. |
| Direct Mill-to-Bodega Contracting | Multi-year volume commitments with Luján de Cuyo wineries secure dedicated color runs and embossed mold exclusivity. |
| Silica Sand Upstream Integration | Captive supply from Sierras de Córdoba deposits insulates against regional logistics disruptions and extraction permit delays. |
| Pharmaceutical Vial Capacity Addition | Borosilicate and tubular glass production captures premium margins under national health authority injectable packaging protocols. |
Research Methodology
Multiple input streams — furnace operator production disclosures, bodega procurement records, and regulatory filing databases — were reconciled through structured primary interviews with glass-ceramic engineering directors, Mendoza winery supply chain managers, pharmaceutical packaging procurement leads, and batch house operations supervisors. Secondary validation drew from Secretary of Industry and Commerce certification registries, national food safety authority surface migration testing protocols, provincial mining permit records, and customs trade data on boron compound imports. Bottom-up volume modeling across product type, end-use application, and form specifications was cross-checked against top-down furnace capacity utilization estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning bottle-jar-vial-jug product configurations, food-beverage-pharmaceutical-cosmetic-household end-use tiers, and clear-colored-frosted-textured form variants. CAGRs were derived from trend extrapolation of furnace output volumes adjusted for natural gas tariff scenarios and lightweighting adoption curves. Industry-specific forecast inputs included Mendoza wine export shipment trajectories and pharmaceutical injectable drug production forecasts from national health authority manufacturing licenses.
Caveats apply where natural gas subsidy adjustments, silica sand extraction permit moratoria, or aluminum can substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding furnace technology retrofit rates and extended producer responsibility implementation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
France Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Tunisia Container Glass Market