
 Bottles Market | 2026-2036
Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Bottles Market Analysis
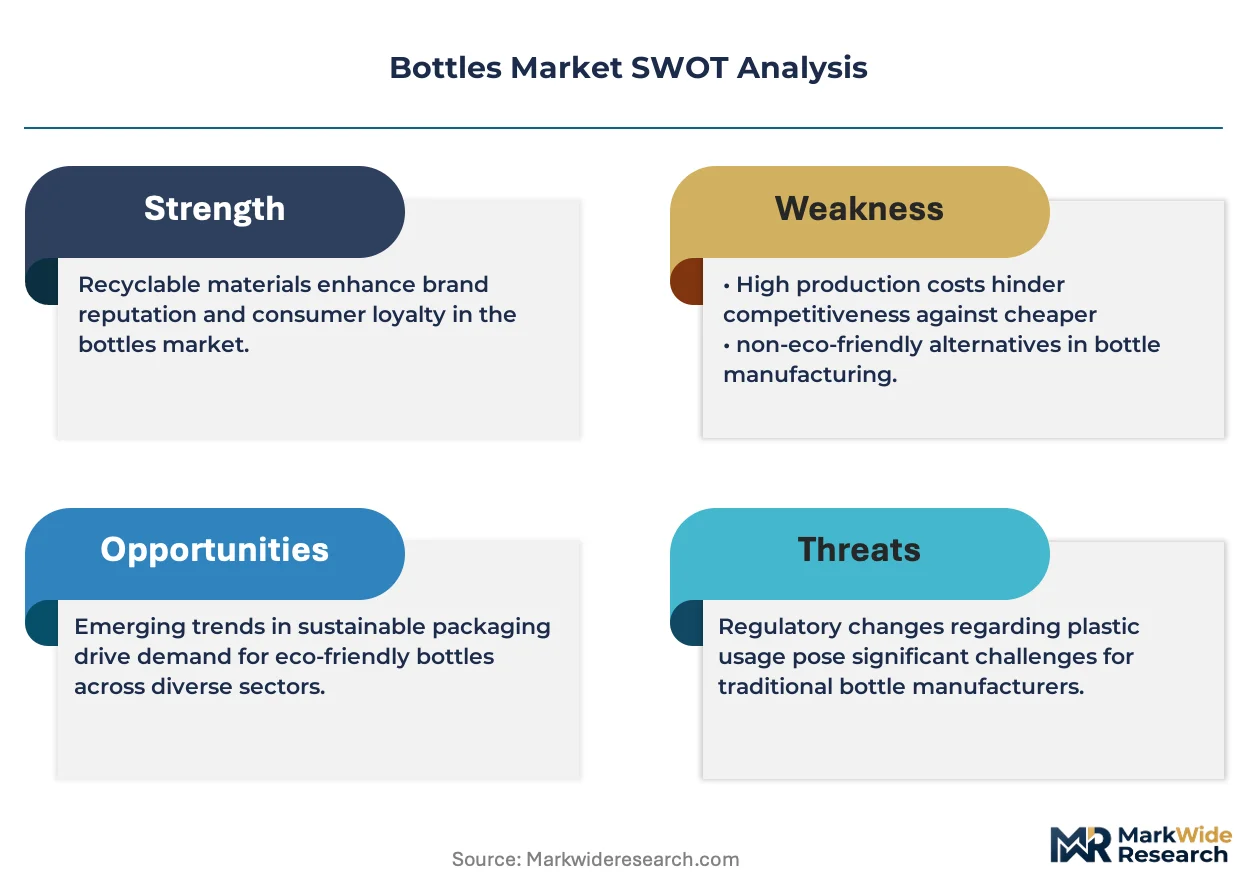
Lightweighting technology is fragmenting traditional blow-molding economics as rPET and bio-based polymers displace virgin resin formulations. The Coca-Cola Company leverages its proprietary PlantBottle platform to anchor sustainable sourcing across Latin America and Southeast Asia. Nestlé S.A. sustains category leadership through captive spring-water assets and direct-store-delivery infrastructure. PepsiCo, Inc. differentiates via Gatorade and Tropicana bottle redesigns that reduce gram weight per unit while preserving shelf impact.
A bottle is a rigid or semi-rigid container with a narrow neck and sealed closure, typically manufactured through injection stretch blow molding, extrusion blow molding, or glass forming at temperatures exceeding 1,500°C, designed to store, transport, and dispense liquids, semi-solids, or granular materials while preserving contents from contamination, oxidation, or UV degradation. Plastic dominates unit volume due to polyethylene terephthalate's clarity, shatter resistance, and recyclability infrastructure, though glass retains premium positioning in spirits and pharmaceutical applications where inertness and barrier properties command price premiums. Food & Beverage applications absorb the majority of output, with pharmaceutical-grade bottles attracting stricter compliance costs and correspondingly higher margins per unit. Closure type selection increasingly tracks dispensing convenience requirements, with pump and dispensing formats gaining traction in personal care and household chemicals.
FDA food-contact notifications govern polymer additives and recycling content claims in the United States, while EU REACH and the F-Gas Regulation constrain fluorinated barrier coatings and propellant systems used in certain dispensing formats. China's SAMR enforces GB standards for food-contact plastics that diverge from ISO testing protocols, creating separate certification burdens for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme expansions that will determine which material formats retain cost competitiveness against alternative packaging substrates.
Market Dynamics
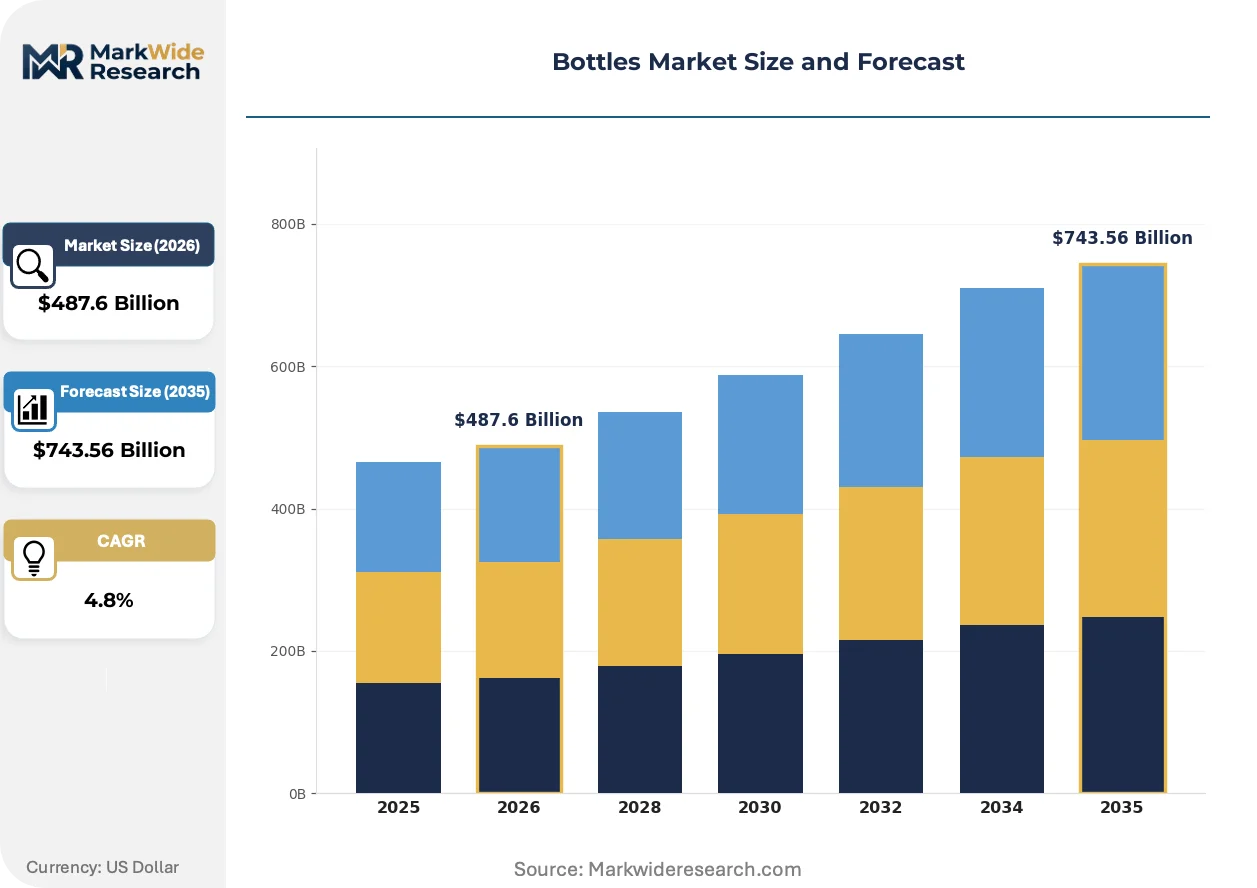
Lightweighting technology and rPET adoption are compressing virgin resin economics while forcing capital retooling across blow-molding supply chains.
Growth Catalysts
- EU REACH compliance mandates:Chemical migration limits on bisphenol and phthalate additives accelerate food-grade rPET conversion in beverage packaging.
- China's urban retail density:Organized modern trade expansion in tier-2 and tier-3 cities drives single-serve bottle volume for bottled water and ready-to-drink tea.
- Injection stretch blow molding automation:Servo-electric machine controls reduce cycle times and energy intensity per unit, improving margin capture for high-volume converters.
Market Restraints
- Crude-linked virgin PET pricing:Feedstock volatility from naphtha and paraxylene markets compresses converter margins when rPET flake premiums widen.
- Glass furnace concentration:European container glass capacity clusters in Germany, France, and Italy, creating geographic supply risk for premium spirits and pharmaceutical clients.
- Fluorinated barrier coating restrictions:EU F-Gas Regulation limits per- and polyfluoroalkyl substance use in high-barrier cosmetic and chemical dispensing bottles.
Strategic Opportunities
- India's organized beverage retail:Modern trade penetration below 15 percent in secondary cities leaves headroom for PET bottle preform localization.
- Deposit-return scheme expansion:Germany's DSD system and emerging French consigne models create closed-loop feedstock security for food-contact rPET.
- Pharma-ophthalmic convergence:Multi-dose preservative-free eye drop bottles combining blow-fill-seal with silicone valve dispensing open premium pricing tiers.
Industry Challenges
- Blow mold technician scarcity:Servo-electric machine programming and process optimization skills lag equipment deployment in Southeast Asian converter bases.
- Food-contact certification timelines:FDA notification reviews for novel rPET decontamination technologies extend 12-18 months, delaying capacity qualification.
- Legacy injection mold retrofit costs:Converting single-stage to two-stage stretch blow systems for lightweight preforms demands capital outlays that strain mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottles Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Paper Application: Food & Beverage, Pharmaceuticals, Personal Care, Household Closure Type: Screw Cap, Cork, Pump, Dispensing Size: Small, Medium, Large, Extra Large |
| Companies Covered | Danone S.A., Gerolsteiner Brunnen GmbH & Co. KG, Nestlé S.A., National Beverage Corp., Nongfu Spring, The Coca-Cola Company, Primo Brands Corporation, Keurig Dr Pepper Inc., PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottles Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are rewriting specification standards across rigid packaging value chains.
High-speed continuous rPET decontamination using super-cleaning extrusion and solid-state polymerization is rendering obsolete batch-based flake washing systems that dominated early recycling infrastructure. European beverage brand owners now specify super-clean rPET content thresholds above 50 percent for carbonated soft drink bottles, compressing capital recovery timelines for virgin resin plants. This technology shift enables bottle-to-bottle closed loops that bypass fiber and sheet downcycling destinations.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are forcing reformulation of bag-on-valve and aerosol dispensing systems in personal care bottles. Manufacturers serving the European market must qualify hydrocarbon or compressed gas alternatives, retooling filling lines and pressure-testing protocols. Cosmetic and household chemical segments bear the compliance burden, with German and French converters leading alternative barrier coating development.
Direct-store-delivery consolidation among beverage distributors is compressing order lot sizes and expanding SKU proliferation for regional flavor variants. Bottled water and functional drink producers now demand shorter production runs with faster mold changeover capabilities, favoring modular blow-molding cells over monolithic high-speed lines. This pattern concentrates in North American and Western European markets where retailer private-label penetration drives format fragmentation.
Bottles Market Segmentation
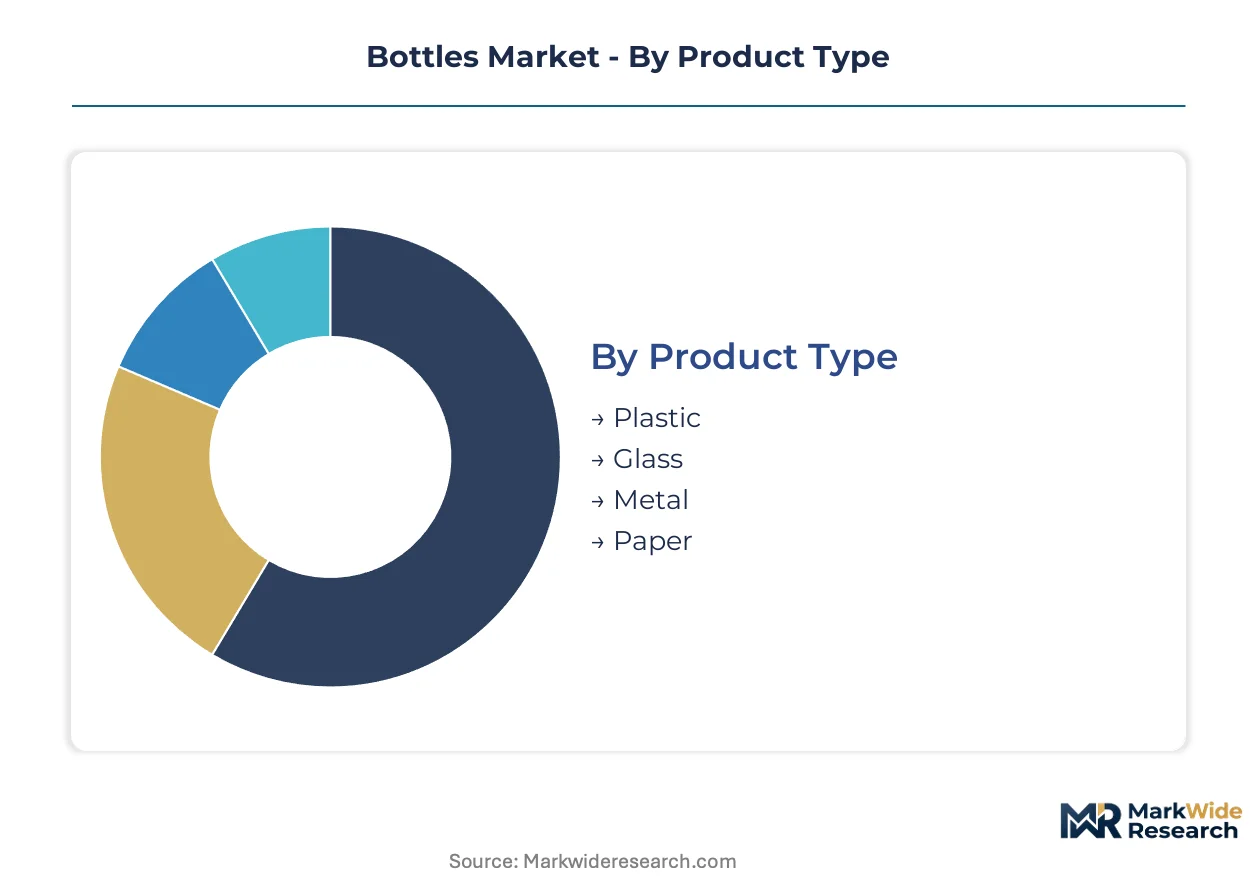
Bottle specifications cascade from material chemistry through closure mechanics to dimensional format, with each axis determining barrier performance, regulatory compliance, and manufacturing capital requirements. Segmentation discipline separates commodity converters from specialists capturing premium margins in pharmaceutical and high-barrier applications.
Product Type:
Material selection governs oxygen transmission rates, UV blocking, and recycling pathway economics across the use-case spectrum from single-serve beverages to multi-year pharmaceutical stability.
- Plastic:Polyethylene terephthalate dominates through clarity, shatter resistance, and established mechanical recycling infrastructure. Food-grade rPET conversion accelerates in Germany and France under EFSA decontamination protocols.
- Glass:Soda-lime silicate formulations retain premium positioning in spirits and injectable pharmaceuticals where inertness commands price multiples. Furnace capacity concentrates in Italy and Germany, creating geographic supply risk for premium clients.
- Metal:Aluminum and tinplate formats serve aerosol propellant and high-pressure dispensing applications with superior barrier against light and gas ingress.
- Paper:Fiber-based bottles with bio-barrier coatings emerge in mineral water and personal care trials, constrained by moisture resistance and FDA food-contact certification timelines.
The dominant share belongs to Plastic, while Glass is closing the gap fastest through pharmaceutical-grade borosilicate expansion.
Application:
End-use requirements dictate compliance tier, batch traceability, and sterilization protocol intensity.
- Food & Beverage:Carbonated soft drinks and bottled water absorb the majority of PET volume, with lightweighting programs reducing gram weight per unit while preserving shelf impact. China's SAMR enforces GB standards for food-contact plastics that diverge from ISO testing protocols.
- Pharmaceuticals:Blow-fill-seal and sterile blow-molding formats serve parenteral and ophthalmic applications with USP Class VI compliance and extractables testing. FDA notification reviews for novel container systems extend qualification timelines.
- Personal Care:Pump and dispensing closures gain traction in skincare and haircare, with EU F-Gas Regulation constraining fluorinated barrier coatings.
- Household:Chemical resistance and child-resistant closure mandates shape HDPE and PET formats for cleaners and disinfectants.
Food & Beverage commands volume leadership, though Pharmaceuticals is expanding most quickly through biologic drug delivery formats.
Closure Type:
Dispensing convenience and tamper-evidence requirements segment converter capabilities across torque specification and capping line automation.
- Screw Cap:Polypropylene and HDPE threaded closures dominate beverage and chemical applications with established induction sealing and pilfer-band integration.
- Cork:Natural and synthetic stopper formats retain wine and spirits positioning, with TCA-free micro-agglomerated alternatives displacing traditional cork in premium segments.
- Pump:Lotion and foam dispensing systems serve personal care with precision dose control and airless chamber designs extending product shelf life.
- Dispensing:Trigger sprayers and flip-top formats concentrate in household chemicals with chemical compatibility testing for aggressive solvents.
Screw Cap maintains installed base dominance, while Pump is gaining share fastest through skincare premiumization.
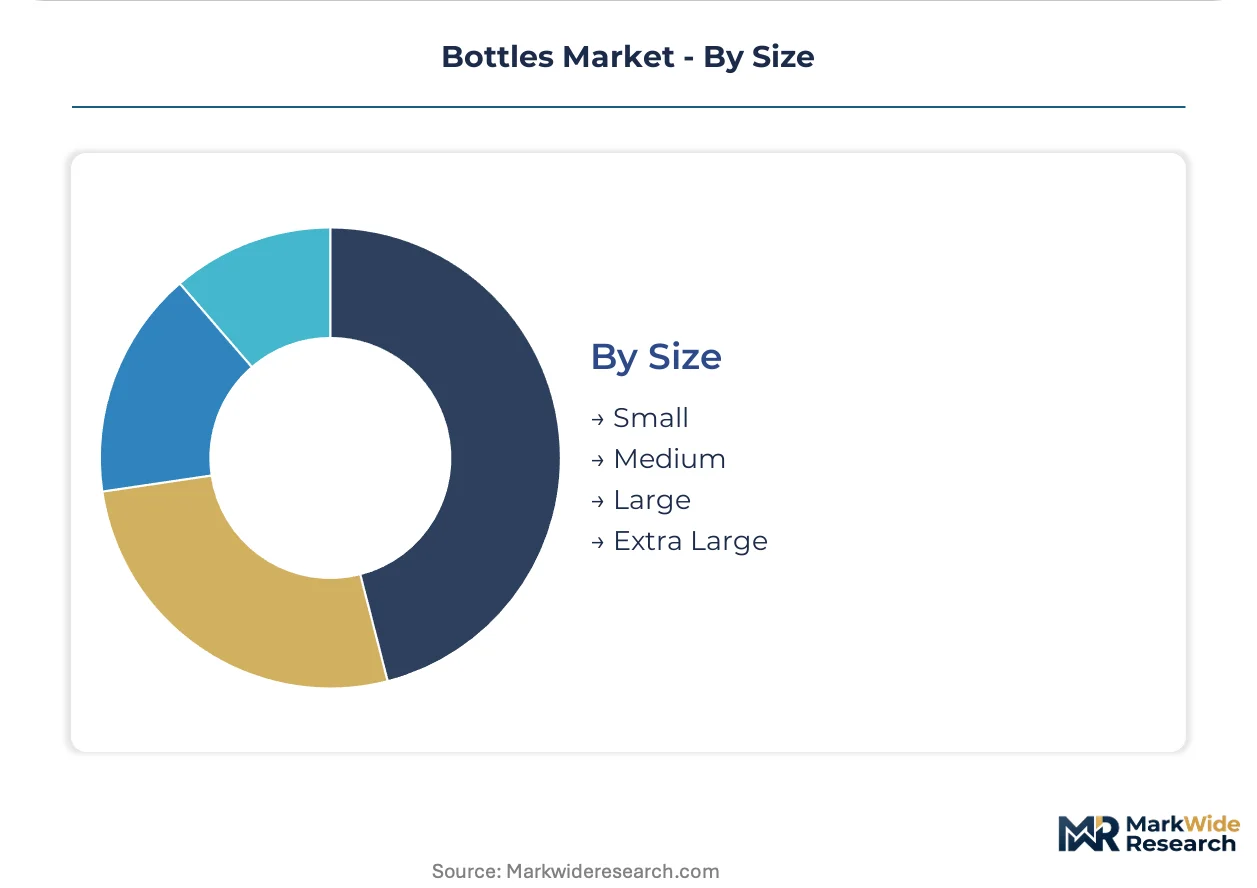
Size:
Volume tier determines blow-molding equipment scale, logistics cube efficiency, and retail shelf space allocation.
- Small:Sub-100ml formats serve travel retail, pharmaceuticals, and sample distribution with high cavity count molds and fast cycle economics.
- Medium:250ml to 1 liter bottles anchor single-serve beverage and personal care mainstream with balanced material efficiency and handling convenience.
- Large:1.5 to 5 liter formats concentrate in bulk household chemicals and water with handle integration and stackability requirements.
- Extra Large:Industrial and institutional containers above 5 liters demand structural ribbing and UN certification for hazardous material transport.
Medium sizes capture the largest production volume, while Small is climbing the fastest through airline travel retail recovery and pharmaceutical unit-dose expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German blow-molding equipment and preform technology flows primarily into Chinese and Indian converter installations, establishing a trade corridor that shapes capacity expansion timelines across Asia-Pacific beverage packaging.
United States
Carbonated soft drink volume and bottled water consumption drive PET preform demand across the Southeast and Midwest. FDA food-contact notifications govern polymer additive approvals and recycling content claims for beverage containers. Dallas-Fort Worth and Atlanta anchor major converter clusters where direct-store-delivery networks service regional retail chains.
China
Urban retail density in tier-2 and tier-3 cities accelerates single-serve bottle consumption for ready-to-drink tea and functional beverages. SAMR enforces GB standards for food-contact plastics that diverge from ISO testing protocols, creating separate certification burdens. Yangtze River Delta manufacturing bases around Shanghai and Suzhou concentrate injection stretch blow molding capacity for domestic brands.
Germany
Deposit-return scheme infrastructure under the DSD system secures closed-loop feedstock for food-contact rPET conversion. EFSA decontamination protocols and EU REACH chemical migration limits reshape material selection for beverage packaging. Container glass furnace capacity clusters in Bavaria and North Rhine-Westphalia, creating geographic supply concentration for premium spirits clients.
India
Organized modern trade penetration below 15 percent in secondary cities leaves headroom for PET bottle preform localization and blow-molding equipment deployment. FSSAI food safety standards and BIS certification requirements govern domestic manufacturing compliance. Maharashtra and Gujarat host emerging converter bases where servo-electric machine adoption lags skilled technician availability.
Brazil
Tropical climate conditions and expanding retail distribution networks drive demand for UV-resistant beverage packaging formats. ANVISA pharmaceutical and food-contact regulations align with Mercosur technical standards while maintaining distinct registration requirements. São Paulo state anchors Southeast regional production clusters serving carbonated soft drink and bottled water brand owners.
Bottles Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by captive spring assets, retail distribution reach, and blow-molding technology access. Consolidation concentrates among beverage brand owners leveraging direct-store-delivery infrastructure, while mid-tier converters fragment across regional preform supply. Three archetypes dominate: vertically integrated beverage conglomerates, captive spring-water specialists, and independent packaging converters serving private-label retail. Competitive moves center on rPET capacity partnerships and lightweighting technology licensing rather than price-based rivalry.
Within the beverage conglomerate tier, The Coca-Cola Company and PepsiCo, Inc. occupy positions defined by global brand portfolios and proprietary bottle design platforms. Nestlé S.A. anchors the captive spring-water specialist archetype through direct ownership of source assets and regional filling infrastructure. Among Asia-Pacific origin competitors, Nongfu Spring exemplifies market positioning built on domestic source control and organized retail channel penetration. Danone S.A. and Keurig Dr Pepper Inc. sit within diversified beverage portfolios where bottled water and functional drinks represent strategic volume pillars. These entities collectively illustrate how asset control over springs, preform manufacturing, and distribution networks determines competitive positioning.
| Leading Market Players |
|---|
| Danone S.A. |
| Gerolsteiner Brunnen GmbH & Co. KG |
| Nestlé S.A. |
| National Beverage Corp. |
| Nongfu Spring |
| The Coca-Cola Company |
| Primo Brands Corporation |
| Keurig Dr Pepper Inc. |
| PepsiCo, Inc. |
| Others |
Supply Flow & Price Mechanics
European rPET furnace undercapacity relative to brand-owner demand specifications is forcing converters toward premium flake sourcing and extended contract tenors, compressing margin flexibility across blow-molding supply chains. This utilization asymmetry between decontamination capacity and food-grade specification requirements anchors supplier pricing power while reshaping procurement strategies for mid-tier beverage packagers.
Pricing Analysis
Cost-plus contracts indexed to paraxylene and PTA futures dominate virgin PET procurement, with rPET premiums widening during seasonal beverage production peaks. Price differentiation rests on EFSA decontamination certification tier and volume commitment scale, with pharmaceutical-grade bottles commanding substantial premiums over commodity beverage formats. Cost compression in standard PET preforms is intensifying because Chinese capacity additions are flowing into Southeast Asian export markets. Private-label retail chains exhibit highest price sensitivity, while captive spring-water specialists with direct-store-delivery infrastructure demonstrate lowest elasticity due to format control.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for blow-molding equipment and preform resin flows. Manufacturing gravity centers on China, Germany, and the United States for injection stretch blow molding systems and high-cavity mold fabrication. Raw material feeds draw from naphtha crackers in South Korea and Saudi Arabia for paraxylene, with rPET flake sourcing anchored in German and French deposit-return scheme collection networks. Single-source vulnerability concentrates in servo-electric machine control systems sourced from Japanese and German automation suppliers. Distribution runs through direct-store-delivery networks for beverage brand owners and wholesale distribution centers serving private-label retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as bottle design specifications consolidate around interoperable preform standards, with The Coca-Cola Company's PlantBottle licensing framework creating ecosystem lock-in effects across Latin American and Southeast Asian converters.
For Market Incumbents: Harden rPET decontamination capacity positions through backward integration into European flake washing and solid-state polymerization assets, defending against emerging chemical recycling entrants. Deepen captive spring-water source control in India's tier-2 and tier-3 city catchments before organized retail penetration accelerates. Prioritize FDA food-contact notification pipelines for novel barrier coating technologies to outpace EU F-Gas Regulation compliance timelines. For New Entrants and Emerging Players: Build out pharma-ophthalmic blow-fill-seal capabilities targeting preservative-free multi-dose eye drop formats, where silicone valve dispensing technology creates defensible premium positioning. India's sub-15 percent modern trade penetration in secondary cities offers the most penetrable geography for PET preform localization. Pursue white-label manufacturing partnerships with regional beverage distributors seeking shorter production runs and faster mold changeover capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among deposit-return scheme infrastructure operators with long-term municipal concessions, offering contracted feedstock security that transcends commodity resin volatility. Five-to-ten year viability favors converters with demonstrated EFSA super-clean certification and established brand-owner offtake agreements. Target acquisition archetypes include mid-tier European rPET decontamination specialists with underutilized capacity and pending FDA qualification pipelines. Monitor German DSD system collection rate trends as the signal for food-contact rPET feedstock availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Decontamination Capacity Expansion | EFSA super-clean certification unlocks bottle-to-bottle closed loops above 50 percent content thresholds for carbonated beverages. |
| Servo-Electric Machine Retrofit Programs | German and Japanese automation suppliers reduce cycle times and energy intensity per unit for high-volume converters. |
| Deposit-Return Scheme Infrastructure Concession | Long-term municipal contracts in Germany and France secure closed-loop feedstock against virgin resin price volatility. |
| Pharma-Ophthalmic Blow-Fill-Seal Development | USP Class VI compliance and extractables testing open premium pricing tiers in biologic drug delivery formats. |
| Lightweighting Technology Licensing | Proprietary preform design platforms reduce gram weight per unit while preserving shelf impact and brand differentiation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with blow-molding equipment manufacturers, beverage brand owner procurement directors, and rPET decontamination facility operators; and secondary validation against customs trade databases, FDA food-contact notification filings, and EFSA scientific opinions on recycling processes. Primary fieldwork engaged plant managers at German and Chinese converter bases, category buyers at North American retail chains, and regulatory affairs leads navigating EU REACH and SAMR GB standard compliance. Secondary sources included SEC 10-K filings from publicly traded packaging converters, trade flow data from Eurostat and UN Comtrade, and technical specifications from injection stretch blow molding equipment suppliers. Bottom-up capacity modeling and top-down demand estimation were triangulated against observed operating rates.
Forecast inputs considered material substitution elasticities between virgin PET and rPET, regulatory phase-in schedules for extended producer responsibility frameworks, and automation adoption curves across Asian converter bases. Segmentation dimensions modeled include material chemistry tier, closure mechanism type, end-use application compliance grade, and regional regulatory cluster. CAGRs were derived from installed capacity growth rates, per-capita consumption benchmarks, and channel penetration trajectories across the projection horizon. Industry-specific inputs encompassed EFSA decontamination protocol adoption timelines and servo-electric machine deployment rates in emerging manufacturing bases.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-sponsored packaging conglomerates or accelerated deposit-return scheme rollouts in India would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Candle Box Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Glass Vape Cartridge Market