
 IV Infusion Bottle Seals and Caps Market | 2026-2036
IV Infusion Bottle Seals and Caps Market Size, Share, and Industry Trends Forecast 2026-2036
IV Infusion Bottle Seals and Caps Market Foresight
Hospital procurement of sealed infusion systems is hardening as patient safety protocols tighten. West Pharmaceutical Services leverages integrated elastomer and aluminum seal platforms to dominate North American supply chains for high-risk parenterals. Aptar Pharma anchors European demand through specialized flip-off cap designs that reduce needlestick injuries in oncology settings. Nipro Corporation sustains cost-competitive manufacturing scale across Asian fill-finish markets.
IV infusion bottle seals and caps are sterile closure systems manufactured from elastomeric rubber, silicone, or thermoplastic compounds, typically laminated with aluminum or polypropylene overcaps, designed to maintain container closure integrity while enabling aseptic needle puncture or luer access. These components prevent microbial ingress, control gas permeation, and ensure drug stability throughout shelf life and administration. Rubber and silicone seals capture premium margin pools in biologics and cytotoxic applications where extractables profiles determine regulatory acceptance. Plastic caps compete aggressively in cost-sensitive generics markets where single-use sterile presentation drives purchasing decisions. Homecare and clinic end-use segments are expanding fastest as infusion therapy shifts from inpatient to ambulatory settings.
The US FDA enforces container closure integrity testing under guidance for sterile drug products, while the EU MDR requires biocompatibility documentation for all patient-contacting closure materials. ISO 8871-5 standards govern elastomeric closures for aqueous parenteral solutions, creating compliance barriers for uncertified suppliers. Japan's PMDA maintains distinct pharmacopoeial specifications for silicone oil content in rubber stoppers used with protein-based therapies. Stakeholders must monitor evolving extractables testing thresholds as regulatory agencies align with United States Pharmacopeia Chapter 1661 for plastic packaging systems.
Market Dynamics
Container closure integrity mandates from the FDA and EU MDR are compressing supplier qualification timelines while hospital procurement consolidates around pre-validated seal platforms. This regulatory tightening favors manufacturers with in-house extractables testing capabilities and integrated aluminum-elastomer supply chains.
Growth Catalysts
- EU MDR biocompatibility documentation:Mandatory patient-contacting material traceability is accelerating hospital conversions to certified seal suppliers with complete DMF filings.
- Homecare infusion expansion:Ambulatory chemotherapy and immunoglobulin protocols are multiplying annual seal consumption per patient by three to five times inpatient rates.
- Silicone oil specification thresholds:Japan's PMDA pharmacopoeial limits for protein-based therapies are pulling premium fluoropolymer-laminated seal demand from standard rubber formulations.
Market Restraints
- Butyl rubber feedstock concentration:Four petrochemical complexes supply pharmaceutical-grade halobutyl globally, exposing molders to coordinated input price volatility.
- Aluminum overcap tariff exposure:Trade friction between major economies is elevating landed costs for European and Asian fill-finish operations dependent on imported coil stock.
- Extractables testing capacity bottleneck:Third-party analytical laboratories face twelve to eighteen month queues for USP Chapter 1661 compliance studies, freezing new supplier entry.
Strategic Opportunities
- Indian sterile injectables expansion:CDSCO manufacturing license reforms and PLI scheme subsidies are attracting multi-year supply contracts from global pharma fill-finish relocations.
- Ready-to-use integrated closure-vial systems:Pre-sterilized nested components eliminate washing and depyrogenation capital for emerging biologics contract manufacturers.
- ISO 8871-5 harmonization:Convergence of elastomeric closure standards across US, EU, and Japanese pharmacopoeias enables single-SKU global supply strategies.
Industry Challenges
- Specialized polymer compounding expertise:Formulation chemists capable of tuning extractables profiles for cytotoxic drug compatibility command salary premiums that strain mid-tier seal producers.
- Legacy steam sterilization validation:Converting hospital customers from established autoclave protocols to gamma-irradiated ready-to-use alternatives requires parallel stability studies extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Infusion Bottle Seals and Caps Market |
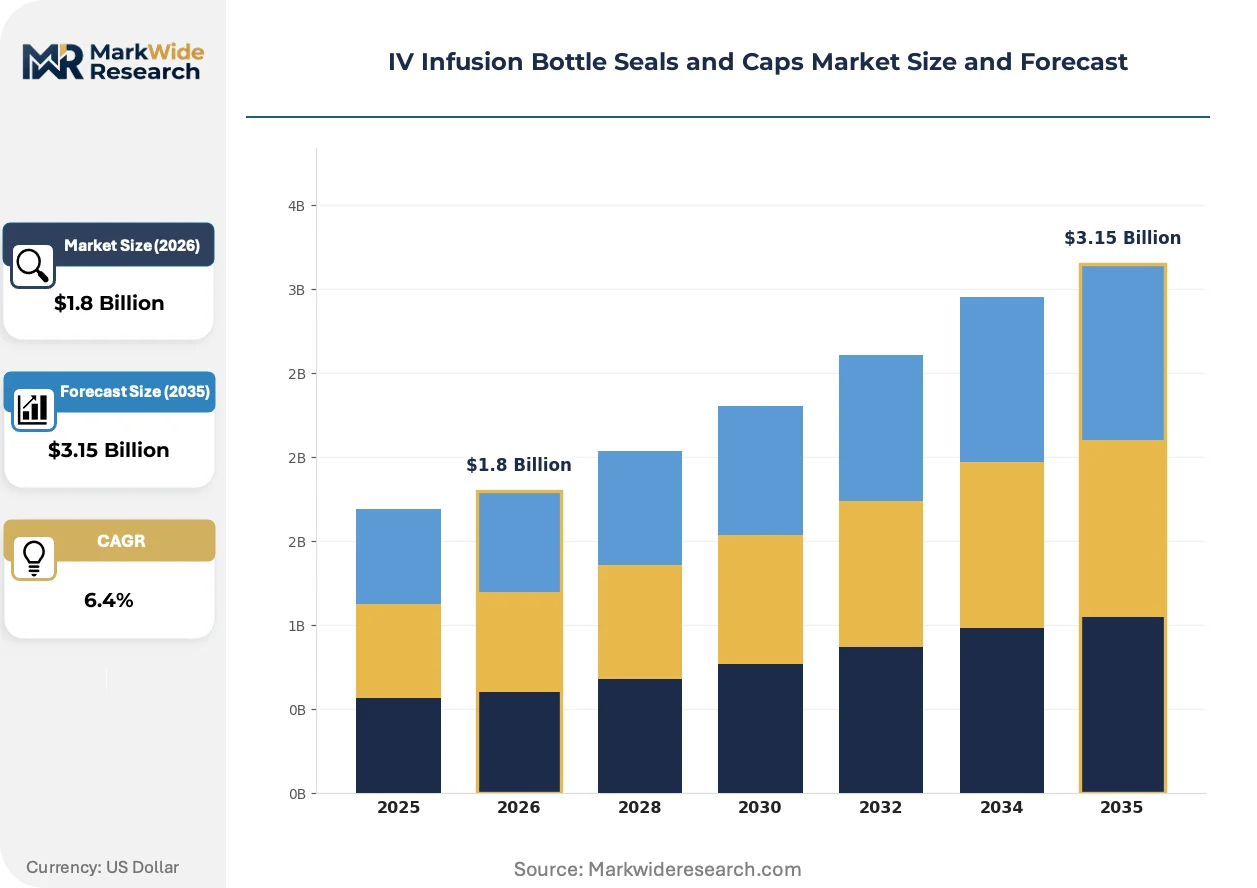
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seals, Caps, Puncture, Screw Caps Material: Rubber, Silicone, Plastic, Metal End User: Clinics, Hospitals, Homecare, Laboratories Usage: Single-Use, Reusable, Sterile, Non-Sterile |
| Companies Covered | Aptar Pharma, Nipro Corporation, West Pharmaceutical Services, SGD Pharma, Stevanato Group, Gerresheimer, SCHOTT AG, Daikyo Seiko Ltd., Datwyler Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Infusion Bottle Seals and Caps Market Shifts & Advancements
Pre-sterilized nested component formats are compressing fill-finish line changeover times while digital track-and-trace mandates permeate secondary packaging. These shifts reward suppliers with modular manufacturing architectures and integrated serialization capabilities.
Multi-layer co-extruded barrier films are replacing conventional aluminum-laminated seals in temperature-sensitive biologics applications. Large-molecule drug manufacturers are adopting these fluoropolymer barriers at pilot scale for mRNA lipid nanoparticle formulations. The technology is decentralizing cold-chain seal sourcing from traditional metalworking clusters to polymer film extrusion regions.
REACH Annex XVII restrictions on certain rubber curing accelerants are forcing reformulation of standard chlorobutyl seals used in European parenteral markets. Compounders are migrating to sulfur-vulcanized or peroxide-cured alternatives with altered compression set characteristics. High-volume generics fill-finish operations in Germany and Italy are absorbing the transition costs through multi-year contract renegotiations.
Hospital group purchasing organizations are consolidating seal and cap procurement into multi-product infusion system contracts with single-source accountability clauses. Regional health systems are displacing fragmented supplier panels with integrated platform agreements covering vials, seals, and administration sets. This concentration is most pronounced in US IDN consolidations and NHS England procurement frameworks.
IV Infusion Bottle Seals and Caps Market Segmentation
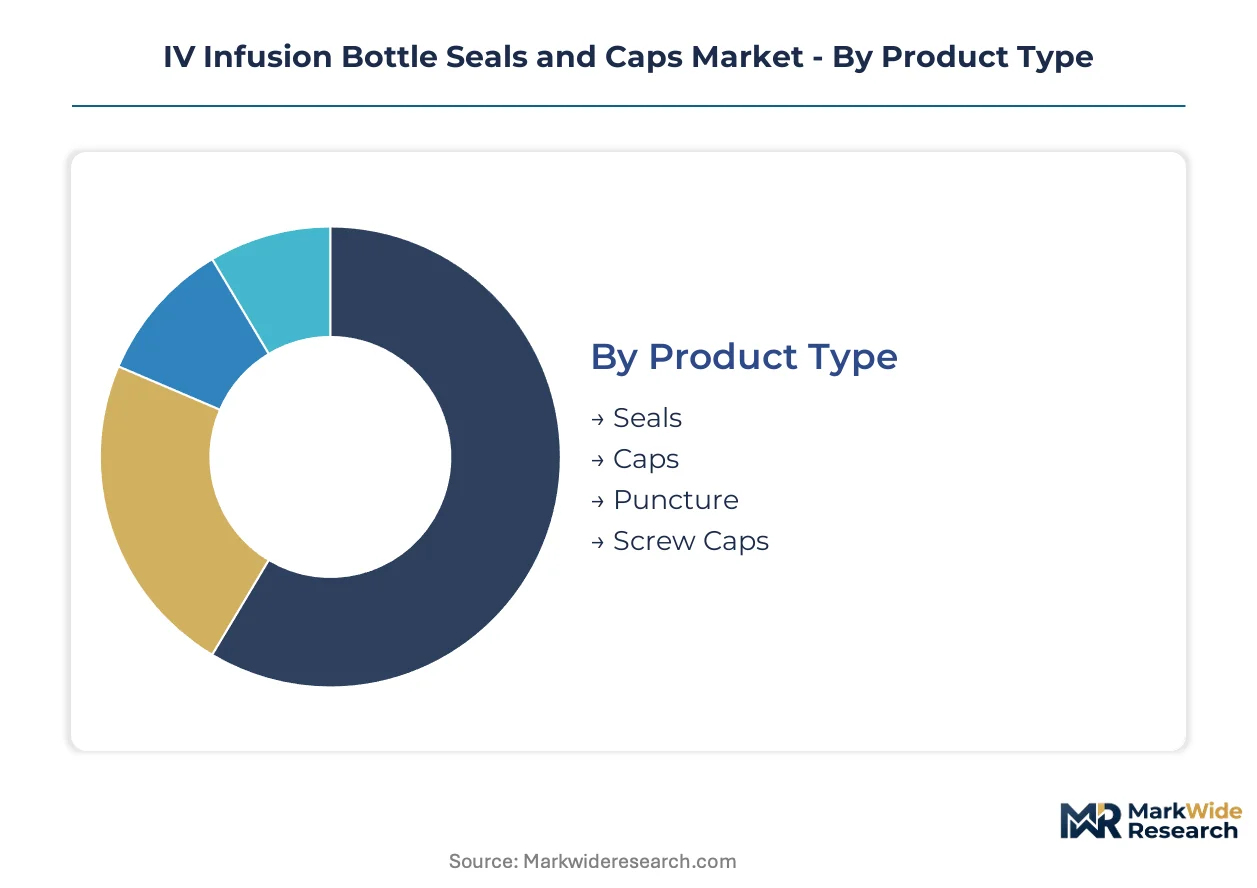
IV infusion bottle seals and caps demand fragments across material grades, sterility protocols, and care settings. Procurement managers weight extractables profiles against total cost of ownership when specifying closure systems for parenteral drug portfolios.
Product Type:
Fill-finish line configuration and drug stability requirements determine seal geometry selection.
- Seals:Elastomeric closures laminated with aluminum retain container closure integrity across temperature excursions. Hospital pharmacies in Germany specify these for high-risk cytotoxic admixtures where barrier performance is non-negotiable.
- Caps:Polypropylene flip-off designs enable single-handed aseptic access during oncology nursing protocols. US hospital group purchasing organizations are consolidating procurement around integrated cap-seal platforms to reduce needlestick injury liability.
- Puncture:Septum configurations for multi-dose vials accommodate repeated needle entries without coring. Compounding pharmacies favor these for batch preparation of anesthesia and antibiotic solutions.
- Screw Caps:Threaded closures for large-volume parenteral bottles secure screw-top access for irrigation and nutritional fluids. Cost-sensitive generics manufacturers in India deploy these for non-sterile manufacturing steps.
Volume sits with Seals; growth tilts toward Caps.
Material:
Regulatory acceptance thresholds for extractables concentrate purchasing power among compounders with validated formulation libraries.
- Rubber:Halobutyl and bromobutyl compounds dominate parenteral applications requiring gas barrier properties. Japan's PMDA enforces strict silicone oil limits for rubber stoppers used with protein-based therapies, pulling demand toward fluoropolymer-laminated alternatives.
- Silicone:Platinum-cured silicone seals offer ultra-low extractables profiles for biologics and mRNA formulations. CDSCO manufacturing license reforms in India are attracting multi-year supply contracts for silicone-laminated nested components.
- Plastic:Thermoplastic elastomer caps compete aggressively in single-use sterile presentation for cost-sensitive generics. REACH Annex XVII restrictions on rubber curing accelerants are forcing European fill-finish operations to evaluate plastic alternatives.
- Metal:Aluminum overcaps provide tamper-evidence and mechanical protection for elastomeric seals. Tariff exposure on imported coil stock is elevating landed costs for European and Asian manufacturers dependent on non-domestic supply.
Volume concentrates in Rubber; expansion is steepest in Silicone.
End User:
Care setting migration from inpatient to ambulatory channels is multiplying annual seal consumption per patient.
- Clinics:Outpatient infusion centers administer chemotherapy and immunoglobulin therapies on compressed schedules. These facilities prioritize ready-to-use nested components that eliminate on-site washing and depyrogenation.
- Hospitals:Acute care settings maintain the most stringent container closure integrity protocols. FDA enforcement of extractables documentation is compressing supplier qualification timelines for hospital procurement departments.
- Homecare:Self-administered infusion therapies require intuitive cap designs with fail-safe aseptic access. Homecare protocols consume three to five times more seals per patient annually compared to inpatient regimens.
- Laboratories:Research and diagnostic applications utilize non-sterile closures for reagent containment. Contract research organizations specify color-coded cap systems for sample tracking across multi-site trials.
Volume remains with Hospitals; Homecare is gaining share fastest.
Usage:
Sterility assurance level determines manufacturing overhead and downstream handling protocols.
- Single-Use:Pre-sterilized disposable closures eliminate cross-contamination risk in multi-patient settings. Gamma-irradiated nested formats are compressing fill-finish line changeover times for emerging biologics contract manufacturers.
- Reusable:Autoclavable seal systems persist in research environments and veterinary applications. Legacy steam sterilization validation requirements extend qualification cycles for hospital customers converting to ready-to-use alternatives.
- Sterile:Aseptic presentation is mandatory for all patient-contacting parenteral applications. EU MDR biocompatibility documentation mandates complete material traceability from certified suppliers with DMF filings.
- Non-Sterile:Bulk unsterilized closures serve pharmaceutical manufacturing steps prior to final fill-finish. These configurations compete on unit economics for high-volume oral liquid and topical packaging.
Volume sits with Sterile; growth tilts toward Single-Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and pharmaceutical clusters in Germany concentrate manufacturing investment through targeted tax incentives and streamlined regulatory pathways. These zones attract multi-year supply contracts from global fill-finish relocations seeking cost-competitive sterile component sourcing.
United States
Hospital group purchasing organizations consolidate procurement around integrated seal-cap platforms to reduce needlestick injury liability. FDA enforcement of container closure integrity testing compresses supplier qualification timelines for acute care settings. West Pharmaceutical Services anchors North American supply chains from Pennsylvania manufacturing bases serving high-risk parenteral markets.
Germany
Gerresheimer and SCHOTT AG anchor specialized glass-and-seal integrated supply to European pharma fill-finish operations. EU MDR biocompatibility documentation mandates accelerate hospital conversions to certified suppliers with complete DMF filings. Bavarian industrial clusters concentrate elastomer compounding expertise for cytotoxic drug compatibility applications.
India
CDSCO manufacturing license reforms and PLI scheme subsidies attract multi-year supply contracts from global pharmaceutical relocations. Cost-competitive generics manufacturers deploy thermoplastic elastomer caps for single-use sterile presentation. Maharashtra and Gujarat pharmaceutical zones expand sterile injectables capacity through nested component formats.
Japan
PMDA pharmacopoeial specifications for silicone oil content in rubber stoppers pull premium fluoropolymer-laminated seal demand from standard formulations. Protein-based therapy manufacturers specify platinum-cured silicone for ultra-low extractables profiles. Kanto region biologics clusters drive nested component adoption for mRNA lipid nanoparticle formulations.
China
NMPA alignment with international pharmacopoeial standards enables domestic suppliers to compete for export contracts to regulated markets. Yangtze River Delta pharmaceutical manufacturing bases expand gamma-irradiated ready-to-use closure capacity. State-backed investment in sterile injectables infrastructure reduces import dependence for high-barrier elastomeric seals.
IV Infusion Bottle Seals and Caps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in biologics while regional molders capture cost-sensitive generics volume. The vendor base organizes around three archetypes: multinational integrated closure-vial systems suppliers, regional elastomer compounders with validated formulation libraries, and emerging Asian fabricators leveraging PLI subsidies and CDSCO reforms. Consolidation pressures intensify as hospital procurement demands single-source accountability across infusion system portfolios. Capacity expansion and backward integration into pharmaceutical-grade halobutyl compounding represent the dominant competitive vectors.
Among the integrated systems tier, West Pharmaceutical Services exemplifies the North American archetype of elastomer-aluminum platform dominance, while Gerresheimer occupies a parallel position in European glass-and-seal integration. Aptar Pharma represents the specialized European design orientation toward flip-off cap configurations that address occupational safety requirements in oncology settings.
| Leading Market Players |
|---|
| Aptar Pharma |
| Nipro Corporation |
| West Pharmaceutical Services |
| SGD Pharma |
| Stevanato Group |
| Gerresheimer |
| SCHOTT AG |
| Daikyo Seiko Ltd. |
| Datwyler Holding |
| Others |
Supply & Pricing Matrix
Gamma-irradiated ready-to-use nested component formats are compressing fill-finish capital requirements while simultaneously concentrating supply power among manufacturers with integrated sterilization infrastructure. This production-method transition elevates pricing premiums for validated sterile presentation while squeezing margins for conventional steam-sterilized alternatives.
Pricing Analysis
Short lead-time premiums command substantial markups in the spot market for certified elastomeric seals, while extended contract offtakes secure volume discounts for hospital group purchasing organizations. Three-tier pricing structure across premium, standard, and economy levels stratifies by extractables certification grade and DMF filing completeness. Cost compression in the generics tier is intensifying because REACH Annex XVII reformulation mandates are elevating compounder R&D overhead. Emerging biologics contract manufacturers exhibit the lowest price sensitivity, while Indian cost-sensitive generics producers drive aggressive unit economics negotiations.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement departments and pharmaceutical fill-finish operators mandate multi-supplier qualification for all elastomeric closure categories. Pharmaceutical-grade halobutyl rubber draws from concentrated petrochemical complexes in the United States, Germany, and Japan. Aluminum coil stock for overcap fabrication rests on imported supply chains exposed to tariff volatility. Single-source vulnerability concentrates in third-party extractables testing capacity, where laboratory queues freeze new supplier entry. Distribution runs through direct OEM supply agreements and specialized pharmaceutical component distributors serving regional fill-finish clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractables testing laboratory capacity constraints are propping pricing power for incumbent seal manufacturers with in-house analytical capabilities. This supply bottleneck protects margin structures across the forecast window.
For Market Incumbents: Cement dominance by accelerating backward integration into pharmaceutical-grade halobutyl compounding and expanding gamma-irradiated sterile capacity in Indian special economic zones. Emerging Asian fabricators leveraging PLI subsidies threaten volume share in cost-sensitive generics tiers. In-house extractables testing infrastructure represents the critical defensive lever against qualification timeline compression.
For New Entrants and Emerging Players: Homecare infusion therapy providers represent an underserved buyer archetype demanding intuitive cap designs with minimal training requirements. This ambulatory channel offers the most penetrable entry point, with three-to-five-fold annual seal consumption multiples per patient versus inpatient protocols. Compounding pharmacies seeking multi-dose septum configurations for anesthesia batch preparation provide a secondary white-space target. A direct-to-clinic distribution model bypassing established hospital GPO contracts enables initial traction.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated closure-vial systems suppliers seeking regional manufacturing footprints. The five-to-ten year viability window favors compounders with validated formulation libraries for cytotoxic drug compatibility. Acquisition target archetypes include regional elastomer molders with CDSCO manufacturing licenses and established DMF filings. The signal to watch is PMDA silicone oil specification threshold tightening, which would accelerate fluoropolymer-laminated seal substitution and reward premium technology holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halobutyl Compounding | Captive supply of pharmaceutical-grade rubber insulates margin from petrochemical feedstock volatility. |
| Gamma-Irradiated Sterile Capacity Expansion | Ready-to-use nested formats command pricing premiums from biologics contract manufacturers. |
| CDSCO Manufacturing License Acquisition | Indian regulatory certification unlocks PLI scheme subsidies and global pharma relocation contracts. |
| Fluoropolymer Lamination Technology Investment | PMDA-compliant ultra-low extractables profiles capture protein-based therapy demand. |
| Hospital GPO Direct Partnership | Single-source accountability clauses consolidate procurement across integrated infusion system portfolios. |
Research Methodology
Independent corroboration across regulatory submission databases, hospital procurement contract records, and pharmaceutical manufacturing license filings underwrites the qualitative findings. Primary interviews with regulatory affairs leads, hospital GPO contracts managers, fill-finish operations directors, and elastomer compounding R&D heads combined with secondary validation from FDA guidance documents, EU MDR technical specifications, and PMDA pharmacopoeial standards. Bottom-up demand modeling across care settings and top-down supply capacity assessment triangulate volume estimates.
Comparable-period anchoring to historical regulatory enforcement intensity and procurement consolidation patterns structured the forecast window. Segmentation dimensions modeled include material grade, sterility protocol, care setting, and regional regulatory cluster complexity. CAGRs derive from elasticity-adjusted demand projections and capacity-constrained supply growth rates across the projection horizon. Industry-specific inputs encompass extractables testing queue durations and PLI scheme subsidy disbursement timelines.
Revisions become necessary when PMDA silicone oil specification thresholds tighten, EU MDR biocompatibility documentation mandates accelerate, or third-party laboratory testing capacity expands materially. Deviation in extractables testing bottleneck severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Screw Closure Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Bag Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Metal Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Drop Sealers Market