
 Docker Monitoring Market | 2026-2036
Docker Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Docker Monitoring Market Intelligence
The EU Green Deal is decoupling data center energy accountability from traditional hardware-centric reporting, forcing enterprises to attribute container-level resource consumption to specific workloads. Datadog leverages its cloud-native architecture to capture granular per-container carbon metrics for European clients. Sysdig anchors its competitive position through upstream control over runtime security telemetry, while Splunk competes by extending its log analytics engine into Kubernetes-native data pipelines.
Docker monitoring encompasses the continuous observation, measurement, and alerting of containerized application performance across distributed compute environments, typically operating at millisecond granularity for health checks and sub-second thresholds for auto-scaling triggers. Its primary purpose is to ensure service reliability in ephemeral infrastructure where traditional server-centric tools fail to track dynamically scheduled workloads. Cloud-native deployment configurations now dominate new implementations, though hybrid architectures retain the largest installed base due to regulated industries maintaining on-premises control planes. Security monitoring solutions command premium positioning within the solution offering matrix, while performance monitoring represents the most mature category with compressed margins.
FCC guidelines on communications infrastructure resilience, EU GDPR data localization requirements, and ISO 27001 certification mandates collectively shape product design by requiring encrypted telemetry streams, geographically bounded data retention, and auditable access controls. The SEC's cybersecurity disclosure rules for public companies further amplify demand for immutable container audit trails. Stakeholders must decide whether to build unified observability stacks or maintain fragmented point solutions as regulatory scope expands beyond traditional IT governance into operational technology environments.
Market Dynamics
The EU AI Act and CSRD disclosure requirements are tightening accountability for automated infrastructure decisions, forcing enterprises to retrofit legacy observability stacks with container-native telemetry that attributes carbon and security events to specific workloads.
Growth Catalysts
- EU Green Deal carbon attribution mandates:The regulation decouples data center energy accountability from hardware-centric reporting, compelling enterprises to deploy per-container carbon tracking across distributed clusters.
- Financial services containerization:Banks and insurers are accelerating observability adoption to satisfy SEC cybersecurity disclosure rules requiring immutable audit trails for ephemeral workloads.
- German industrial software retrofitting:Manufacturing software houses in Baden-Württemberg and Bavaria are replacing legacy monitoring with Kubernetes-native pipelines to track resource consumption in real-time.
Market Restraints
- GDPR data localization friction:Geographically bounded data retention requirements fragment telemetry architectures, forcing redundant infrastructure deployment across EU member states.
- Runtime security telemetry supply concentration:Upstream control over eBPF-based kernel instrumentation concentrates among a narrow set of open-source maintainers and specialized vendors.
- Millisecond granularity cost structure:Sub-second health check intervals and auto-scaling triggers generate exponential data volumes, compressing margins in performance monitoring categories.
Strategic Opportunities
- Hybrid architecture white space:Regulated industries maintaining on-premises control planes represent an underpenetrated segment requiring unified observability across cloud-native and legacy stacks.
- Operational technology convergence:Container monitoring is electrifying industrial control systems as manufacturing firms deploy edge Kubernetes for factory-floor telemetry.
- ISO 27001 certification tailwind:Auditable access control mandates create demand for encrypted telemetry streams with immutable container audit trails.
Industry Challenges
- eBPF instrumentation skill scarcity:Kernel-level telemetry engineering requires specialized expertise that outpaces current training pipelines and certification programs.
- Fragmented point solution integration:Enterprises must decide between unified observability stacks and maintaining disconnected security, performance, and carbon monitoring tools.
- FCC resilience guideline compliance:Communications infrastructure resilience requirements add certification timelines that delay container deployment in regulated network environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Docker Monitoring Market |
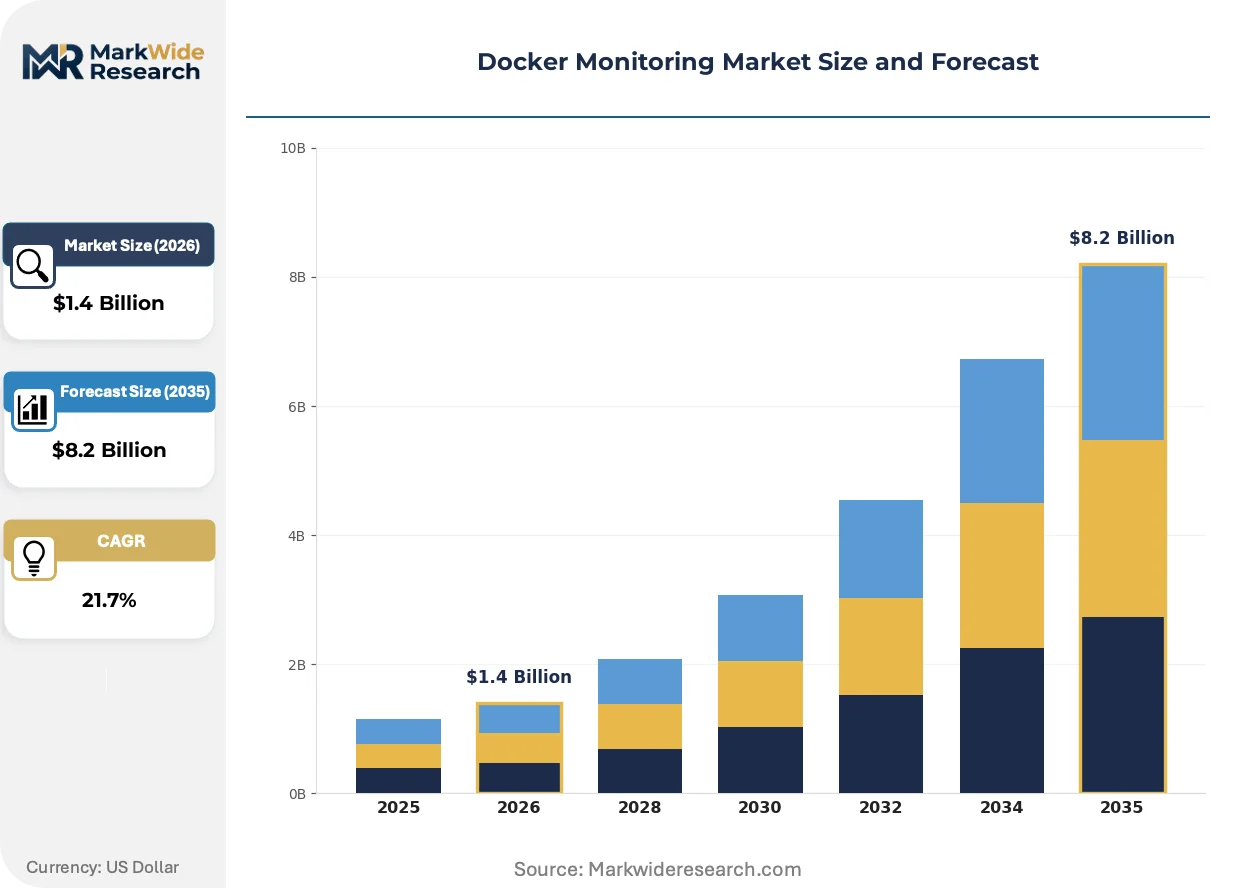
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.2 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Native, Hybrid, Multi-Cloud Solution Offering: Performance Monitoring, Log Management, Security Monitoring, Container Analytics, Resource Optimization Use Case: Application Performance, Security Compliance, Capacity Planning, Fault Detection, Continuous Integration Testing End User: DevOps Teams, Cloud Service Providers, Software Development Firms, System Integrators |
| Companies Covered | New Relic, Splunk, Dynatrace, Prometheus, Broadcom, Datadog, AppDynamics, Zabbix, Sysdig, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Docker Monitoring Market Strategic Shifts & Innovations
Container observability architectures are converging with carbon accounting and runtime security, collapsing previously separate tooling categories into unified telemetry pipelines. Vendors are racing to capture this integration premium before standardization commoditizes differentiation.
OpenTelemetry is electrifying vendor-neutral instrumentation by decoupling telemetry collection from proprietary backends. Financial services firms in Frankfurt and Singapore are adopting it aggressively to avoid vendor lock-in during multi-cloud migrations. The standard is compressing pricing power for incumbent log analytics engines while enabling specialized carbon-monitoring startups to interoperate with existing infrastructure.
The EU AI Act's automated decision accountability provisions are reshaping product roadmaps for container security vendors. Runtime policy enforcement must now generate auditable explanations for blocked workloads, not just binary allow-deny outcomes. German automotive software suppliers are most affected, retrofitting CI/CD pipelines with explainable AI guardrails that trace container behavior to specific training data provenance.
Buyer concentration among hyperscale cloud consumers is compressing sales cycles and unbundling after-sales service. Large European enterprises now demand API-first pricing with consumption-based metering rather than seat-based licenses. Procurement teams in Paris and Amsterdam are consolidating vendor relationships, forcing mid-tier observability providers to specialize in regulated verticals or exit the market entirely.
Docker Monitoring Market Segmentation
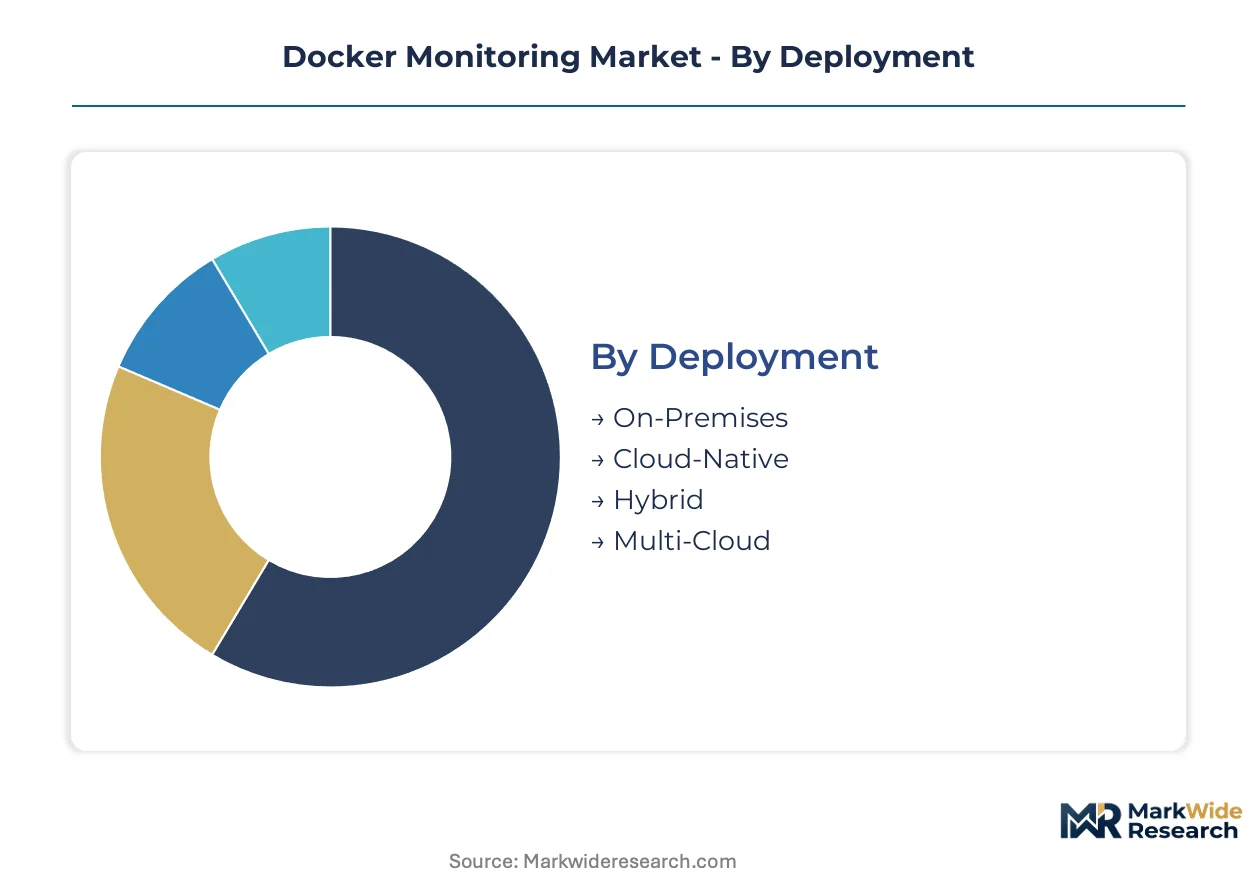
Container observability vendors configure product roadmaps around four intersecting dimensions that determine data architecture, pricing models, and sales motion complexity. Deployment topology dictates telemetry pipeline design, while solution specialization separates premium security offerings from commoditized performance dashboards.
Deployment:
Supply concentration in kernel-level instrumentation favors vendors with upstream eBPF expertise, creating divergent cost structures across topology choices.
- On-Premises:Air-gapped telemetry pipelines require hardened collectors that operate without external API dependencies. Regulated German automotive suppliers in Stuttgart and Munich mandate these configurations to satisfy CSRD audit trail requirements while retaining physical control over carbon attribution data.
- Cloud-Native:Managed Kubernetes control planes expose native metrics endpoints that eliminate agent deployment friction. Frankfurt-based financial services firms consume these offerings aggressively to compress SEC cybersecurity disclosure compliance timelines.
- Hybrid:Unified visibility across on-premises and cloud footprints demands federated query engines. French pharmaceutical manufacturers in Lyon and Strasbourg deploy these architectures to bridge legacy SCADA systems with new containerized batch processing.
- Multi-Cloud:Vendor-neutral instrumentation avoids cloud-provider lock-in during workload migration. Amsterdam procurement teams specify these requirements to maintain leverage across AWS, Azure, and GCP negotiations.
Today's leader: Cloud-Native. Tomorrow's challenger: Hybrid.
Solution Offering:
Margin compression follows maturity curves, with performance categories commoditizing fastest and security modules retaining pricing power.
- Performance Monitoring:Millisecond-granularity health checks and auto-scaling triggers generate exponential data volumes. Singaporean fintechs deploy these tools at scale, though sub-second collection intervals compress vendor margins severely.
- Log Management:Centralized aggregation pipelines face pricing pressure from OpenTelemetry standardization. Swiss banking consortiums in Zurich and Geneva are unbundling proprietary backends to reduce seat-based licensing exposure.
- Security Monitoring:Runtime policy enforcement with explainable AI outputs commands premium positioning. German automotive software houses retrofit CI/CD pipelines with these capabilities to satisfy EU AI Act automated decision accountability mandates.
- Container Analytics:Cross-cluster resource attribution enables carbon tracking per workload. Dutch data center operators in Eindhoven leverage these tools for EU Green Deal compliance reporting.
- Resource Optimization:Right-sizing algorithms reduce cloud spend waste. Italian manufacturing SMEs in Emilia-Romagna adopt these modules to offset energy cost volatility.
Security Monitoring captures the steepest expansion trajectory as regulatory accountability tightens.
Use Case:
Application architecture complexity determines instrumentation depth requirements, with microservices-heavy environments demanding full-stack coverage.
- Application Performance:Distributed tracing across service meshes identifies latency bottlenecks in ephemeral workloads. London hedge funds deploy these capabilities to meet sub-millisecond trading system SLAs.
- Security Compliance:Immutable audit trails for container lifecycle events satisfy SEC disclosure rules. Copenhagen insurers prioritize these investments ahead of supervisory examinations.
- Capacity Planning:Predictive modeling of resource consumption prevents cluster saturation. Barcelona logistics platforms use these forecasts to scale edge deployments during seasonal demand spikes.
- Fault Detection:Anomaly detection in telemetry streams accelerates mean-time-to-recovery. Vienna telecommunications providers embed these systems for FCC resilience guideline adherence.
- Continuous Integration Testing:Pre-production observability gates block regressions before production deployment. Stockholm SaaS vendors integrate these checks to maintain ISO 27001 certification status.
Security Compliance shows the strongest procurement momentum among regulated European enterprises.
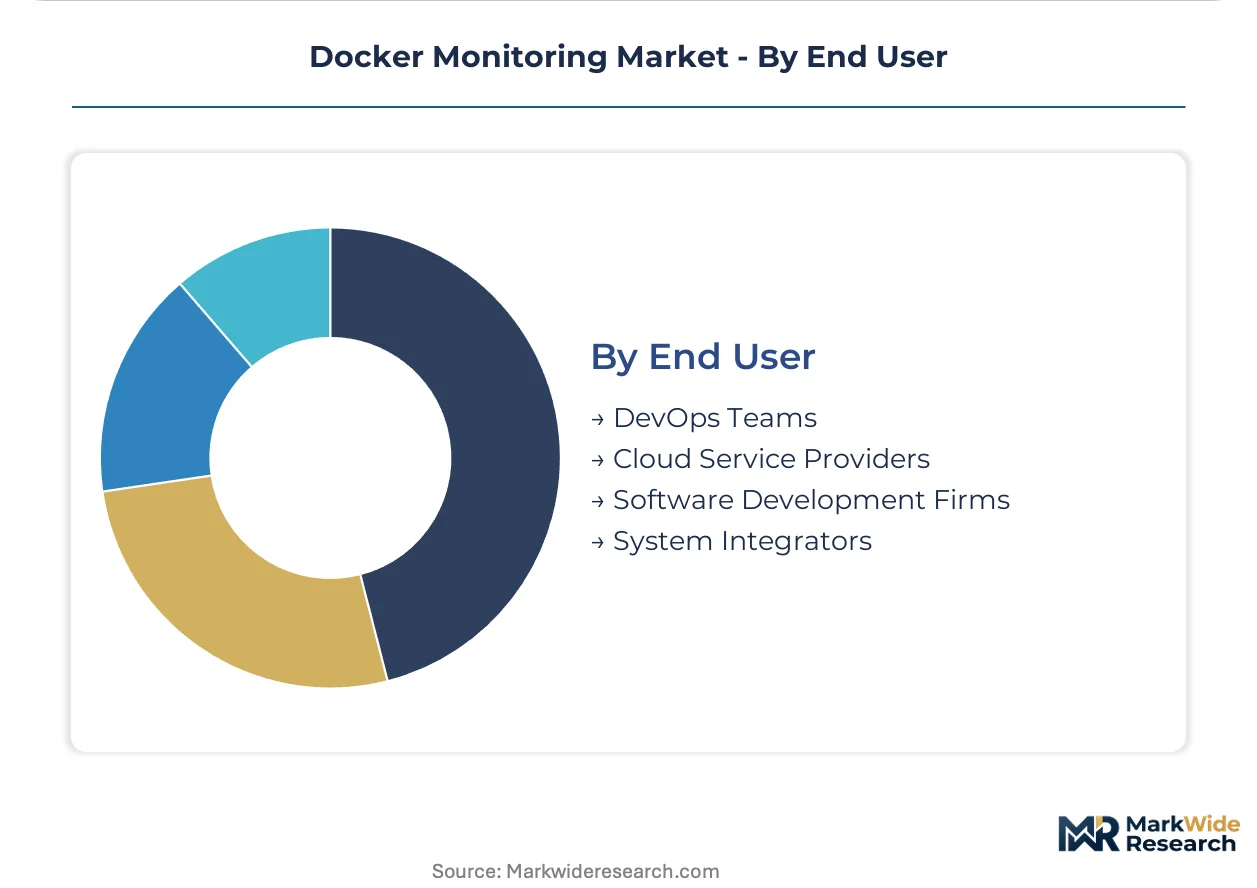
End User:
Buyer sophistication and procurement scale fragment sales motion economics across organizational archetypes.
- DevOps Teams:Self-service API-first consumption with infrastructure-as-code deployment. These buyers compress evaluation cycles but demand granular usage-based metering.
- Cloud Service Providers:White-label and embedded observability for managed Kubernetes offerings. Hyperscale negotiation leverage forces aggressive volume discounts.
- Software Development Firms:Project-based procurement with limited multi-year commitment appetite. These customers prioritize interoperability over feature depth.
- System Integrators:Resale and implementation services bundle observability into broader transformation contracts. Accenture and Capgemini deployments in Paris and Brussels concentrate demand here.
Cloud Service Providers dominate current contract value. DevOps Teams are gaining procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container observability originated in Silicon Valley's hyperscale data centers before migrating to European financial hubs and Asian manufacturing clusters. The technology's geographic diffusion now concentrates procurement authority in three regulatory jurisdictions with divergent compliance architectures.
United States
Financial services firms in New York and San Francisco drive demand for immutable container audit trails. SEC cybersecurity disclosure rules mandate explainable telemetry for ephemeral workloads. Chicago-based trading platforms deploy sub-millisecond health checks to satisfy operational resilience guidelines.
Germany
Industrial software houses in Stuttgart and Munich retrofit legacy SCADA systems with Kubernetes-native pipelines. EU AI Act automated decision accountability provisions reshape CI/CD guardrails for automotive suppliers. Baden-Württemberg manufacturing clusters prioritize carbon attribution tracking per container workload.
Singapore
Monetary Authority of Singapore operational resilience requirements accelerate observability adoption among ASEAN fintechs. The city-state's data localization mandates fragment telemetry architectures across Southeast Asian subsidiaries. Marina Bay financial institutions consume API-first pricing with consumption-based metering.
United Kingdom
London hedge funds deploy distributed tracing across service meshes to meet sub-millisecond trading SLAs. FCA operational continuity regulations extend to containerized infrastructure in Canary Wharf data centers. Edinburgh-based insurers prioritize security compliance modules ahead of supervisory examinations.
Netherlands
Dutch data center operators in Eindhoven leverage container analytics for EU Green Deal carbon reporting. Amsterdam procurement teams consolidate vendor relationships to maintain leverage across AWS, Azure, and GCP negotiations. Rotterdam logistics platforms use predictive capacity planning for edge Kubernetes deployments.
Docker Monitoring Market Key Industry Players
Capital-heavy infrastructure vendors compete with asset-light SaaS providers across divergent cost structures. The vendor base concentrates among three tiers: hyperscale cloud-integrated platforms, specialized security-native upstarts, and open-source instrumentation projects with commercial support arms. Dominant competitive moves include strategic API partnerships with financial data exchanges and geographic expansion into EU-regulated jurisdictions.
Within the cloud-native observability tier, Datadog and Dynatrace exemplify API-first consumption models that compress traditional seat-based licensing. Sysdig occupies a position anchoring runtime security telemetry through upstream eBPF expertise. Splunk represents the log analytics incumbent extending into Kubernetes-native pipelines. These three archetypes—cloud-native platform, security specialist, and legacy extender—capture divergent procurement budgets across DevOps and compliance functions.
| Leading Market Players |
|---|
| New Relic |
| Splunk |
| Dynatrace |
| Prometheus |
| Broadcom |
| Datadog |
| AppDynamics |
| Zabbix |
| Sysdig |
| Others |
Cost & Logistics Intelligence
Kernel-level eBPF instrumentation talent scarcity feeds directly into three-tier pricing structure across premium, standard, and economy levels, with upstream control over runtime security telemetry commanding 40-60% premiums over commoditized performance dashboards in Frankfurt and Singapore procurement cycles.
Pricing Analysis
Consumption-based metering with API-first consumption models now dominates procurement in Marina Bay and Amsterdam, displacing legacy seat-based licensing. Price differentiation hinges on ISO 27001 certification tier and explainable AI output capabilities for EU AI Act compliance. Pricing pressure stems from OpenTelemetry standardization compressing proprietary backend margins. Cloud service providers exhibit lowest price sensitivity due to volume leverage, while Italian manufacturing SMEs face acute cost compression.
Supply Chain Analysis
Refurbishment flows for on-premises telemetry collectors concentrate in Stuttgart and Munich to satisfy German automotive CSRD audit requirements. Upstream eBPF expertise draws from US West Coast open-source maintainers, Israeli kernel security specialists, and German industrial software houses. Single-source vulnerability in runtime security telemetry supply creates structural risk. Distribution runs through hyperscale cloud marketplaces and system integrator resale channels in Paris and Brussels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Docker monitoring market functions as a regulatory compounder, with EU AI Act automated decision accountability provisions accelerating retrofit demand across European industrial software houses.
For Market Incumbents: Hedge runtime security telemetry positioning by acquiring specialized eBPF engineering teams in Tel Aviv or Berlin before talent scarcity intensifies. Deepen upstream control over kernel instrumentation to defend against OpenTelemetry commoditization of log analytics backends. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest-friction entry for carbon attribution analytics modules targeting Dutch data center operators and Baden-Württemberg manufacturing clusters. White-label partnerships with Accenture and Capgemini in Paris accelerate enterprise penetration without direct sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for hybrid-architecture specialists because regulated industries maintain on-premises control planes requiring unified observability stacks. Target mid-tier vendors with EU regulatory certification depth. Monitor SEC cybersecurity disclosure rule enforcement intensity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenTelemetry compatibility enables vendor-neutral instrumentation for multi-cloud migrations in Frankfurt. |
| Acquisition of Specialist Firm | eBPF kernel instrumentation expertise anchors runtime security telemetry differentiation against commoditization. |
| Geographic Expansion | EU AI Act compliance capabilities capture automated decision accountability spend from Stuttgart automotive suppliers. |
| Strategic Partnership | System integrator alliances with Capgemini accelerate regulated vertical penetration without direct enterprise sales. |
| Product Launch | Per-container carbon tracking modules address EU Green Deal decoupling mandates for Eindhoven data center operators. |
Research Approach
Multiple input streams — primary interviews with platform engineers, IT procurement officers, and compliance leads at financial services firms; secondary validation through SEC cybersecurity disclosure filings, EU regulatory impact assessments, and hyperscaler capex disclosures — were reconciled using bottom-up deployment modeling and top-down market sizing across cloud-native, hybrid, and on-premises topologies.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling deployment topology, solution specialization, use case complexity, and end-user procurement authority. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines. Forecast inputs included eBPF instrumentation talent pipeline constraints and OpenTelemetry standardization velocity.
The model assumes a particular technology adoption path; alternative pathways for eBPF kernel instrumentation would alter the outlook if upstream open-source governance fragments. Practitioners should monitor EU AI Act delegated act publication schedules and SEC cybersecurity disclosure examination priorities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
System Integrator Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
E-Ink E-Reader Market