
 Decision Management Applications Market | 2026-2036
Decision Management Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Decision Management Applications Market Outlook
Modular bundling of decision engines with embedded compliance layers is realigning how enterprises evaluate procurement options. FICO leverages its scoring heritage to anchor risk-assessment workflows for banking clients. SAS Institute competes through deep specialization in predictive analytics modules that integrate with legacy data warehouses. IBM Corporation extends its position via hybrid-cloud deployment architectures that appeal to regulated industries.
Decision management applications combine business rules engines, machine learning models, and workflow orchestration to automate and optimize operational choices across customer onboarding, pricing, and risk evaluation. These systems process structured and unstructured data through configurable rule sets and self-learning algorithms, executing decisions at sub-second latency for high-volume transactional environments. Cloud-based deployment models are capturing the fastest expansion as financial services firms migrate off legacy mainframes, while on-premises installations retain margin concentration in defense and government segments where data sovereignty requirements dominate procurement criteria. Workflow automation applications lead current revenue contribution, though artificial intelligence–enabled decisioning is accelerating as organizations seek adaptive systems that reduce manual rule maintenance.
The EU AI Act, GDPR automated decision-making provisions, and US fair-lending regulations enforced by the CFPB are collectively tightening accountability standards for algorithmic outcomes, forcing vendors to embed explainability features and audit trails as standard product components. Financial institutions in the United States face overlapping scrutiny from the SEC on model risk management and from state insurance regulators on automated underwriting transparency, creating layered compliance obligations that favor established vendors with pre-certified governance frameworks. Stakeholders must monitor how rapidly evolving algorithmic accountability standards in the European Union and United States reshape product roadmaps and customer retention dynamics.
Market Dynamics
Financial institutions face intensifying pressure from the EU AI Act and overlapping US fair-lending rules to embed explainability and audit trails directly into automated decisioning workflows, fundamentally restructuring vendor procurement criteria and product architecture requirements.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision systems in credit and insurance now require algorithmic transparency documentation, forcing enterprises to upgrade legacy rule engines with governance-ready platforms.
- Cloud migration acceleration:Banking and insurance carriers are abandoning mainframe infrastructure for scalable decision engines that process high-volume transactions at sub-second latency.
- Machine learning model operationalization:Self-learning algorithms reduce manual rule maintenance burdens while enabling real-time adaptive pricing and risk evaluation across customer touchpoints.
Market Restraints
- Data sovereignty requirements:Defense and government segments mandate on-premises deployment, fragmenting vendor R&D resources across incompatible infrastructure stacks.
- Specialized talent scarcity:Shortages of professionals combining domain expertise in risk modeling with MLOps capabilities inflate implementation timelines and consulting costs.
- Legacy system entrenchment:Decades-old core banking platforms resist API-based integration, constraining decision engine deployment to greenfield workflows rather than full-stack replacement.
Strategic Opportunities
- Mid-market banking penetration:Regional and community banks in the United States remain underserved by enterprise-grade governance tools, creating whitespace for modular compliance-layer bundling.
- Embedded finance convergence:Decision engines integrated directly into e-commerce checkout flows and BNPL platforms expand addressable market beyond traditional financial services.
- State-level insurance transparency rules:Regulators in California and New York are mandating automated underwriting documentation standards that favor vendors with pre-certified audit frameworks.
Industry Challenges
- Model risk management certification:SEC scrutiny of algorithmic trading and lending decisions requires documented validation protocols that extend sales cycles by 6-12 months.
- Interoperability complexity:Synchronizing business rules engines with existing data warehouses demands custom mapping layers that inflate professional services revenue dependence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decision Management Applications Market |
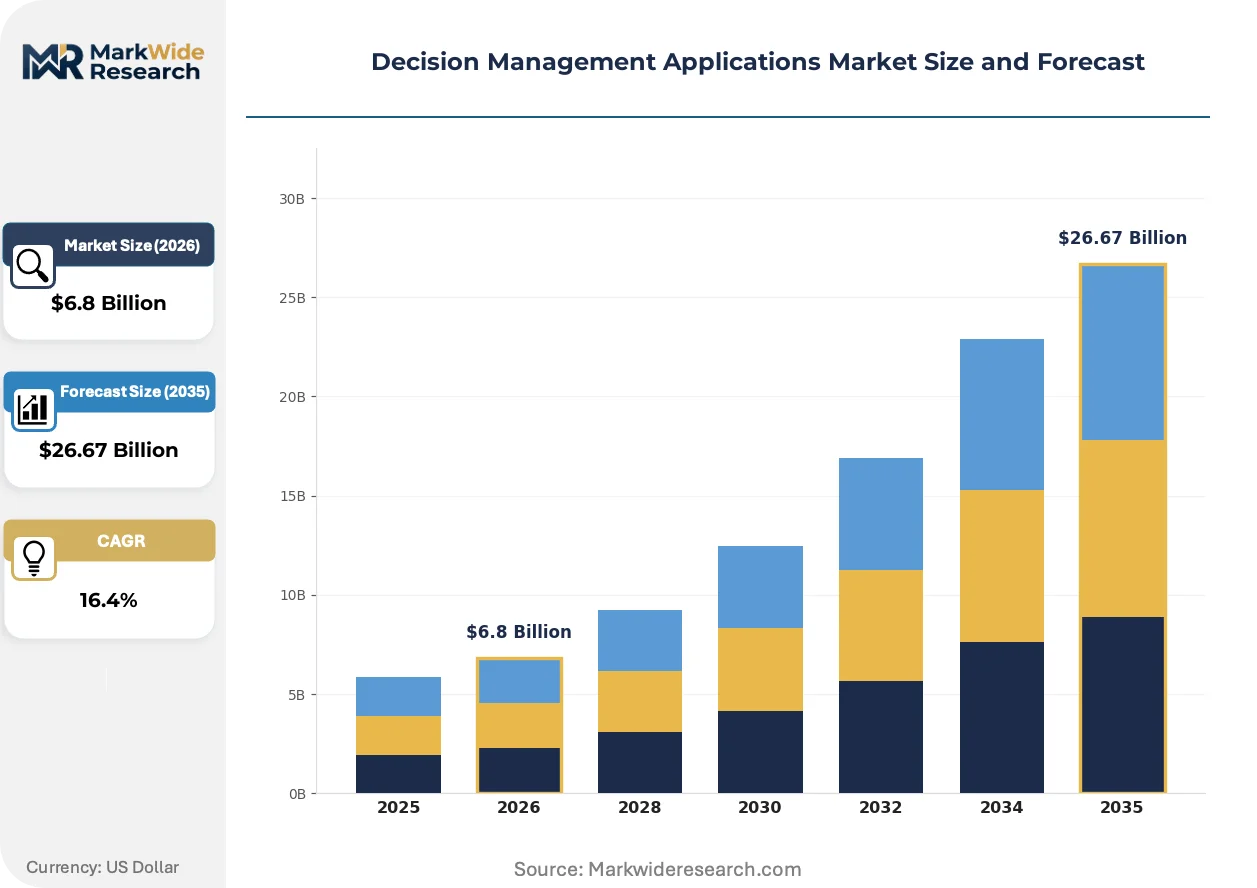
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Workflow Automation, Predictive Analytics, Risk Assessment, Performance Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Financial Services, Retail, Manufacturing, Telecommunications Technology: Machine Learning, Business Rules Engine, Data Mining, Artificial Intelligence |
| Companies Covered | IBM Corporation, SAS Institute Inc., FICO, Oracle Corporation, Pegasystems, Inc., TIBCO Software Inc., Salesforce.com, Inc., Experian PLC, Equifax, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decision Management Applications Market Strategic Shifts
Decision management architectures are pivoting from static rule repositories to adaptive systems that autonomously refine decision logic based on outcome feedback, compressing the gap between model deployment and production performance optimization.
Retrieval-augmented generation is rewriting how financial institutions handle unstructured documentation in credit decisions. Large language models extract and validate income verification, contract terms, and risk indicators from scanned documents and email threads. Commercial lenders in the United States and United Kingdom are piloting these systems for small-business underwriting, collapsing document processing from days to minutes while preserving audit trails required by prudential regulators.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk automated decision systems used in credit scoring and insurance pricing. Vendors must now provide technical documentation, human oversight protocols, and accuracy metrics as standard deliverables. European banking supervisors are conducting targeted reviews of algorithmic credit models, accelerating demand for pre-certified governance modules that embed compliance by design.
Enterprise buyers are unbundling decision engine procurement from monolithic platform commitments, favoring API-first components that integrate with existing cloud data infrastructure. Procurement teams now evaluate vendors on interoperability certifications and time-to-production metrics rather than feature breadth alone. This pattern is most pronounced among asset managers and specialty insurers in the United States, where CTOs prioritize composable architectures that avoid vendor lock-in.
Decision Management Applications Market Segmentation
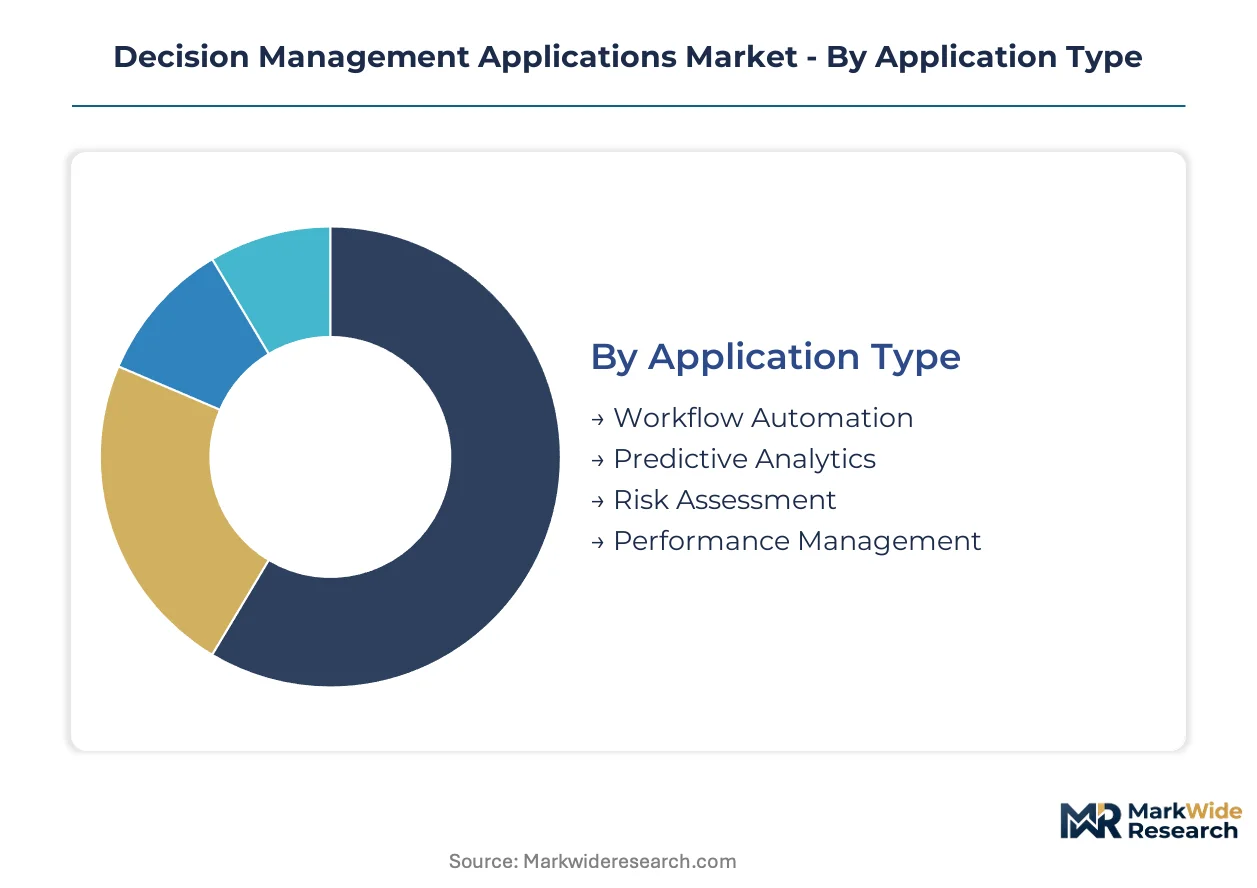
Segmentation in decision management applications reveals how procurement criteria diverge across buyer archetypes. Financial institutions prioritize compliance-ready governance layers, while retail and manufacturing segments emphasize speed-to-deployment and total cost of ownership over regulatory certification depth.
Application Type:
Buyers in this category differentiate primarily by operational maturity and regulatory exposure rather than firm size.
- Workflow Automation:Orchestrates multi-step approval chains and exception handling across customer onboarding and claims processing. Banking carriers in the United States concentrate procurement here as CFPB fair-lending scrutiny intensifies audit trail requirements for manual handoffs.
- Predictive Analytics:Statistical models forecast customer churn, default probability, and lifetime value from historical behavioral data. Asset managers and specialty insurers favor these modules for portfolio stress testing where SEC model risk management rules mandate documented validation protocols.
- Risk Assessment:Real-time scoring engines evaluate creditworthiness and operational exposure at transaction velocity.
- Performance Management:Dashboards and KPI trackers monitor decision engine accuracy and business outcome alignment.
Workflow Automation leads volumes today; Predictive Analytics is gaining share fastest.
Deployment Model:
Infrastructure choices here map directly to data sovereignty obligations and legacy system entrenchment.
- Cloud-Based:Scalable compute resources process high-volume transactional decisions without capital-intensive hardware procurement. Regional banks across the United States are abandoning mainframe dependencies for these architectures as core banking modernization budgets expand.
- On-Premises:Dedicated hardware installations satisfy defense and government segments where classified data handling prohibits third-party infrastructure access. The segment retains margin concentration despite slower growth trajectories.
- Hybrid:Sensitive decision logic runs locally while model training leverages elastic cloud capacity.
- SaaS:Subscription pricing lowers barrier to entry for mid-market buyers lacking dedicated IT operations.
Cloud-Based deployments dominate new procurement; Hybrid architectures show the steepest expansion trajectory among regulated enterprises.
End User:
Vertical specialization requirements create procurement fragmentation that favors vendors with pre-built industry accelerators.
- Financial Services:Credit scoring, fraud detection, and automated underwriting workflows process millions of daily transactions. EU AI Act conformity assessments and overlapping US state insurance transparency rules compel these buyers toward governance-embedded platforms.
- Retail:Dynamic pricing engines and inventory optimization algorithms respond to demand signals in near-real-time. E-commerce platforms and BNPL providers integrate decision engines directly into checkout flows.
- Manufacturing:Supply chain risk scoring and predictive maintenance decisions reduce operational downtime.
- Telecommunications:Churn prediction and network capacity allocation models manage subscriber retention and infrastructure investment.
Financial Services anchors current revenue contribution; Retail is climbing the fastest as embedded finance convergence accelerates.
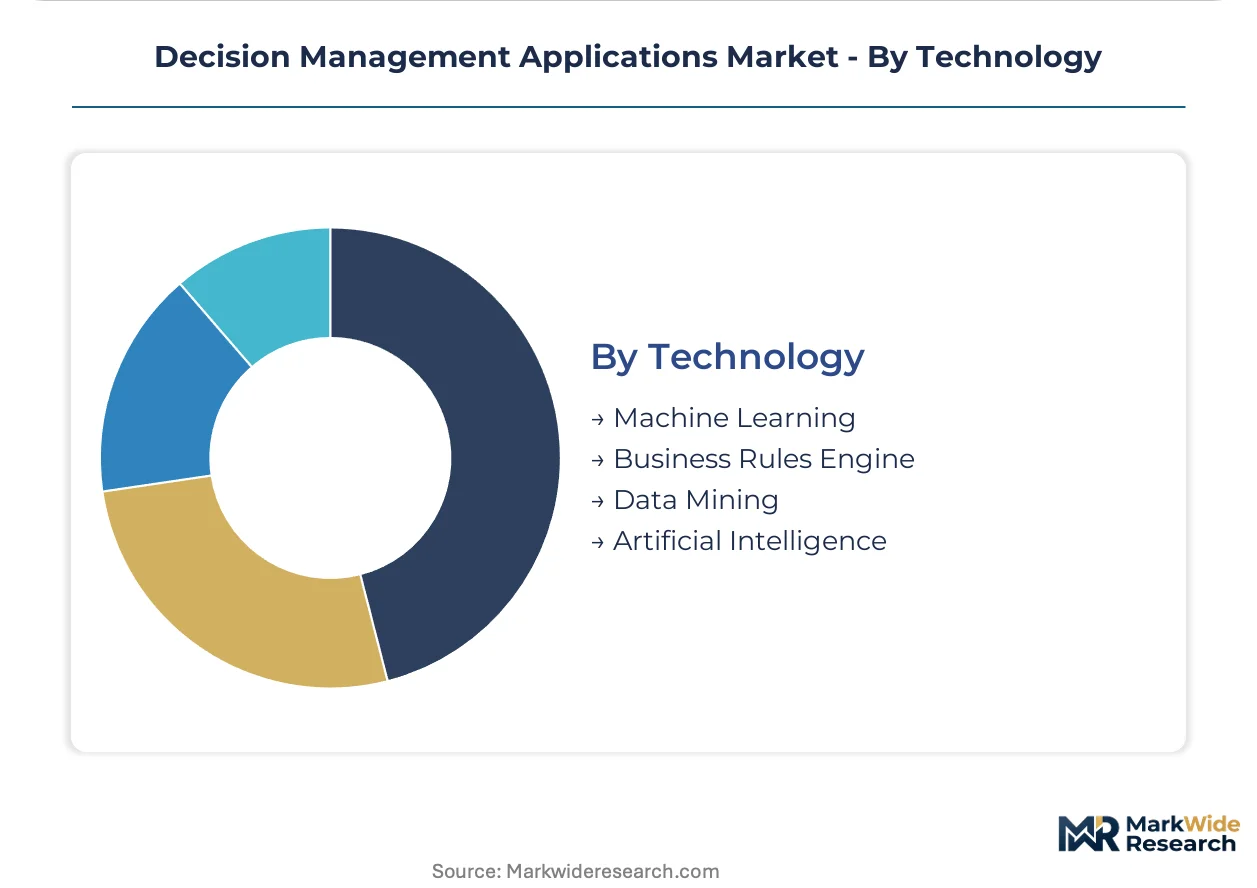
Technology:
Technical architecture choices determine maintenance burden, explainability depth, and integration complexity with existing data infrastructure.
- Machine Learning:Self-learning algorithms autonomously refine decision boundaries from outcome feedback without explicit rule recoding. Commercial lenders in the United States and United Kingdom deploy these systems for small-business underwriting where document volume overwhelms manual review capacity.
- Business Rules Engine:Explicit if-then logic provides deterministic, auditable decision paths that satisfy prudential regulator demands for transparency. Insurance carriers facing California and New York automated underwriting documentation mandates favor these for their inherent explainability.
- Data Mining:Pattern discovery techniques identify hidden correlations in historical transaction records.
- Artificial Intelligence:Large language models and retrieval-augmented generation extract structured data from unstructured documentation sources.
Business Rules Engine retains the largest installed base; Machine Learning is expanding most quickly as MLOps tooling matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decision management applications originated in United States banking centers during the 1990s credit scoring revolution, then diffused through London and Frankfurt as Basel II compliance requirements standardized risk quantification practices across OECD markets.
United States
Large financial institutions in New York and Chicago drive procurement of compliance-ready AI governance tools as CFPB fair-lending scrutiny intensifies. The SEC enforces model risk management documentation standards that extend vendor sales cycles. Silicon Valley technology clusters incubate retrieval-augmented generation pilots for commercial lending document processing.
United Kingdom
London-based asset managers and specialty insurers favor predictive analytics modules for portfolio stress testing under Prudential Regulation Authority oversight. The Financial Conduct Authority mandates algorithmic transparency for automated credit decisions. Edinburgh and Manchester banking hubs accelerate cloud migration off legacy mainframe infrastructure.
Germany
Frankfurt's concentration of systemically important banks demands embedded explainability features for EU AI Act conformity assessments. BaFin reviews algorithmic credit models with heightened scrutiny for high-risk automated decision systems. Munich insurance clusters pilot hybrid deployment architectures balancing data sovereignty with elastic compute capacity.
Japan
Tokyo megabanks operationalize machine learning models for real-time fraud detection at transaction velocity. METI guidelines encourage AI adoption while preserving deterministic audit trails for Financial Services Agency examinations. Osaka regional banks represent underserved whitespace for modular compliance-layer bundling.
Singapore
Wealth management and private banking centers deploy decision engines for customer onboarding automation under Monetary Authority of Singapore technology risk management guidelines. The city-state's regulatory sandbox accommodates pilot programs for BNPL-integrated decisioning. Fintech clusters in One-North district attract vendors targeting Southeast Asian expansion.
Decision Management Applications Market Competitive Environment
Premium-margin players sit above commodity-margin players across compliance certification depth, with governance-embedded platforms commanding pricing power against generic workflow automation tools. The vendor base stratifies into three tiers: established enterprise platforms with pre-certified audit frameworks, mid-market specialists offering modular API-first components, and emerging challengers targeting embedded finance convergence. Dominant competitive moves include strategic partnerships with cloud hyperscalers and geographic expansion through regulatory sandbox participation.
Within the established enterprise tier, IBM Corporation and SAS Institute exemplify divergent architectural philosophies, with the former emphasizing hybrid-cloud deployment models and the latter anchoring position through deep predictive analytics specialization. FICO occupies a distinctive niche leveraging scoring heritage to anchor risk-assessment workflows. These three vendors collectively represent how compliance-ready governance layers have become the primary procurement differentiator as EU AI Act and overlapping US regulatory mandates reshape customer retention dynamics.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| FICO |
| Oracle Corporation |
| Pegasystems, Inc. |
| TIBCO Software Inc. |
| Salesforce.com, Inc. |
| Experian PLC |
| Equifax, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in the decision management applications space concentrate development capacity across cloud-native architectures while enforcing pricing discipline through recurring revenue models that lock in multi-year enterprise commitments.
Pricing Analysis
Subscription-based tiering across enterprise, professional, and entry levels anchors vendor revenue models, with price differentiation hinging on governance certification depth and API call volume thresholds. Pricing pressure stems from mid-market banking buyers demanding modular unbundling without full-platform commitments. Regional and community banks exhibit the highest price sensitivity, while systemically important financial institutions prioritize compliance-ready audit frameworks over cost minimization.
Supply Chain Analysis
Regional distribution centers in the United States, United Kingdom, and Germany coordinate software delivery through cloud marketplace integrations and direct enterprise licensing channels. Development draws from specialized talent pools in Bangalore, Warsaw, and Singapore for MLOps engineering and regulatory documentation. Single-source vulnerability concentrates in hyperscaler compute dependencies for model training workloads. Distribution runs through AWS Marketplace, Azure Marketplace, and direct vendor sales organizations serving tier-one financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decision management applications market functions as a stable compounder, with regulatory compliance mandates across the United States and European Union generating durable demand for governance-embedded platforms regardless of macroeconomic cycles.
For Market Incumbents: Deepen vertical integration into MLOps tooling and model validation services to capture professional services revenue that emerging API-first competitors cannot replicate. Expand certification investment for EU AI Act conformity assessments and SEC model risk management frameworks to extend sales cycle advantages. Prioritize hybrid-cloud deployment architectures that satisfy data sovereignty requirements in defense and government segments where challenger vendors lack clearance credentials. For New Entrants and Emerging Players: The price-point gap between enterprise-grade governance platforms and generic workflow automation tools creates entry whitespace for modular compliance-layer bundling. Target mid-market banking in the United States, particularly regional institutions in the Southeast and Midwest lacking dedicated AI governance teams. Pursue embedded finance convergence through BNPL-integrated decision engines for e-commerce platforms seeking sub-second credit decisions at checkout. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market specialists with pre-certified audit frameworks but limited geographic footprint, offering platform consolidation upside. Long-term viability centers on vendors embedding explainability features as standard product components rather than add-on modules. Monitor California and New York insurance transparency rule enforcement as an inflection indicator for governance-embedded platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU AI Act conformity assessments and SEC model risk frameworks extend incumbent sales cycle advantages against challengers. |
| Hybrid-Cloud Architecture Expansion | Data sovereignty compliance in defense segments captures margin concentration unavailable to pure-cloud competitors. |
| Mid-Market Banking Penetration | Regional institutions in the United States represent underserved whitespace for modular compliance-layer bundling. |
| Embedded Finance Integration | BNPL and e-commerce checkout flows expand addressable market beyond traditional financial services procurement. |
| Retrieval-Augmented Generation Deployment | Large language model document processing collapses commercial lending underwriting timelines from days to minutes. |
Study Parameters
Direct dialogue with CTOs at asset managers, model risk officers at systemically important banks, insurance regulator examination staff, and MLOps engineering directors grounded qualitative findings in operational reality. Secondary validation drew from SEC enforcement actions, EU AI Act technical documentation requirements, CFPB fair-lending examination manuals, and cloud hyperscaler partnership disclosure filings. Bottom-up segment sizing triangulated against top-down regulatory mandate coverage estimates across financial services procurement budgets.
Market value and volume trajectories emerged from segment-level modeling across deployment model, organization size tier, vertical specialization, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act implementation timelines and US state insurance transparency rule phase-ins. Forecast inputs included cloud migration budget allocations at regional banks and professional services revenue dependence ratios across vendor tiers.
The model assumes a particular technology adoption path; alternative pathways for retrieval-augmented generation in commercial lending would alter the outlook for document-processing automation modules. Forecasts reflect assumptions about regulatory enforcement intensity and hyperscaler partnership exclusivity terms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Control Room Solutions Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Graph Technology Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Global Photo Management Software Market