
 Global E-Visa Market | 2026-2036
Global E-Visa Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Visa Market Foresight
Buyer concentration among government immigration agencies is expanding as sovereign nations consolidate vendor relationships for integrated border management systems. Thales Group leverages its biometric document portfolio to anchor large-scale e-visa platform deployments across multiple continents. IDEMIA competes through deep specialization in identity verification workflows that reduce processing friction at consular checkpoints. VFS Global sustains its position by controlling physical-digital hybrid service channels that bridge online applications with biometric enrollment centers.
An e-visa constitutes a digitally issued travel authorization stored in electronic immigration databases rather than as a physical visa label, typically incorporating machine-readable data fields, biometric identifiers, and cryptographic verification protocols to authenticate traveler identity at port-of-entry systems. Tourist visa processing through web portals occupies the largest transaction volume, while mobile app platforms represent the fastest-growing application channel as smartphone penetration deepens across emerging economies. Corporate client segments increasingly demand premium processing service models that compress turnaround timelines through dedicated account management and pre-cleared traveler databases.
The EU Entry/Exit System under EASA oversight, ICAO Doc 9303 biometric standards, and India's Bureau of Immigration digital mandates collectively shape product specifications and market access requirements for platform providers. EES compliance deadlines are forcing Schengen-area governments to replace legacy stamp-based systems with automated e-visa and e-gate integrations. Stakeholders must monitor which regulatory frameworks achieve cross-border harmonization versus fragmentation, as interoperability standards will determine vendor scalability and contract renewal cycles.
Market Dynamics
The EU Entry/Exit System mandate is compressing procurement timelines for biometric border infrastructure, forcing sovereign immigration agencies to consolidate vendor relationships around integrated platform providers capable of delivering document verification, biometric enrollment, and backend database interoperability within compressed deployment windows.
Growth Catalysts
- Biometric Standardization:ICAO Doc 9303 compliance requirements are mandating machine-readable travel documents with embedded chips, creating upgrade cycles for legacy visa issuance systems across consular networks.
- India:The Bureau of Immigration's digital mandate for visa-on-arrival digitization is driving transaction volume expansion through mobile-first application portals and automated port-of-entry verification gates.
- Corporate Travel Programs:Multinational enterprises are demanding API-integrated visa management platforms that embed directly into corporate travel booking workflows, compressing turnaround timelines for frequent business travelers.
Market Restraints
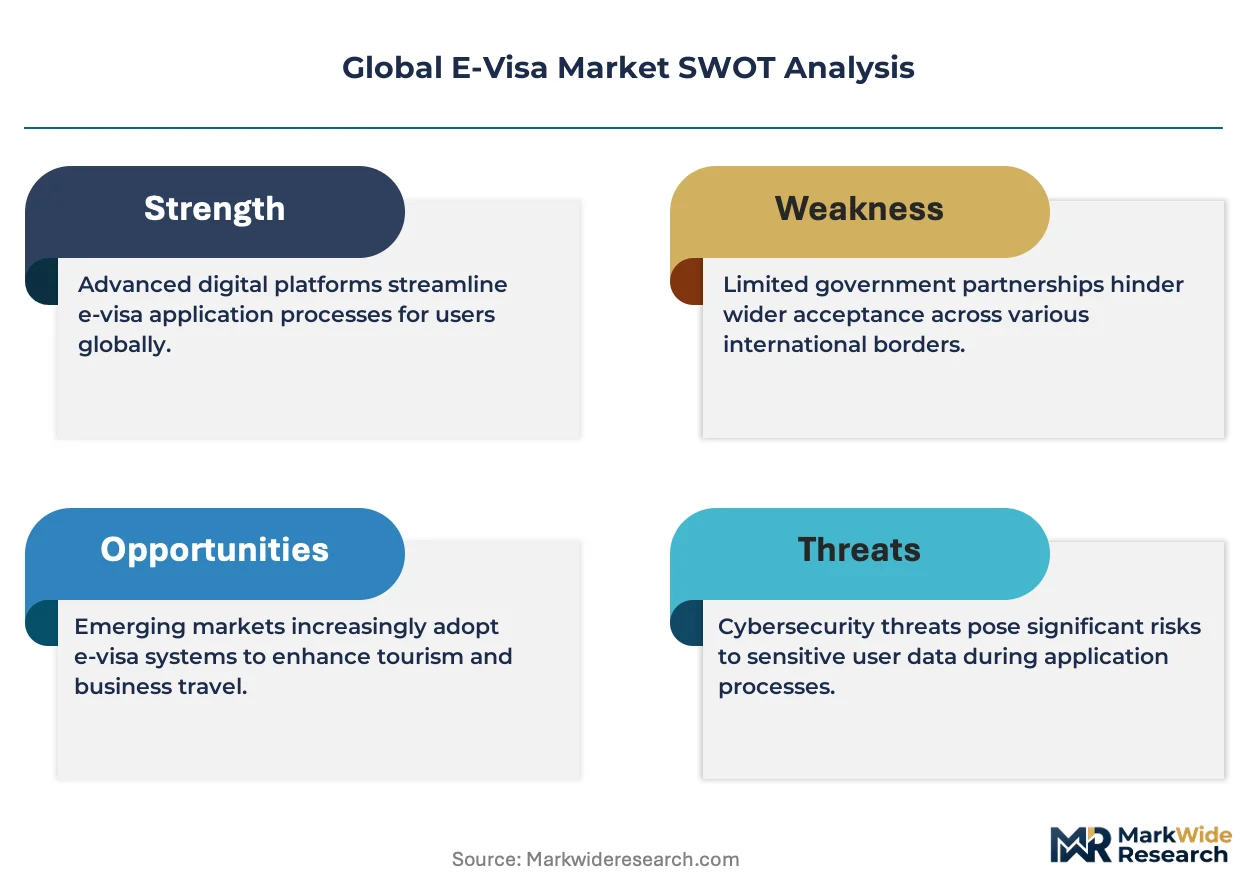
- Semiconductor Supply Concentration:Secure element chip shortages concentrated in Taiwan and South Korea are extending lead times for smart visa document production, delaying large-scale e-visa card deployments.
- Data Localization Mandates:Russia, China, and Indonesia require biometric traveler data to reside on sovereign servers, fragmenting platform architectures and inflating infrastructure duplication costs for global vendors.
- Legacy System Interoperability:Stamp-based entry protocols in older Schengen consular posts create technical debt that complicates EES-compliant middleware integration, extending deployment timelines.
Strategic Opportunities
- Sub-Saharan Africa:Kenya, Nigeria, and Ghana are piloting visa-free regional mobility protocols that require shared biometric verification infrastructure, opening greenfield platform deployment contracts.
- Mobile Wallet Convergence:Integration of e-visa tokens into Apple Wallet and Google Pay ecosystems is creating new distribution channels that bypass traditional consular web portals for eligible traveler segments.
- UAE Golden Visa Expansion:Long-term residency programs targeting remote workers and investors are generating demand for premium-tier processing services with dedicated biometric enrollment centers and concierge support.
Industry Challenges
- Biometric Algorithm Bias:Facial recognition systems exhibit elevated false rejection rates for certain demographic cohorts, triggering operational delays at automated border gates and requiring human adjudication fallback protocols.
- Cybersecurity Certification Lag:Common Criteria EAL4+ evaluation timelines for border management software extend 18-24 months, compressing vendor revenue recognition cycles and inflating pre-contract engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Visa Market |
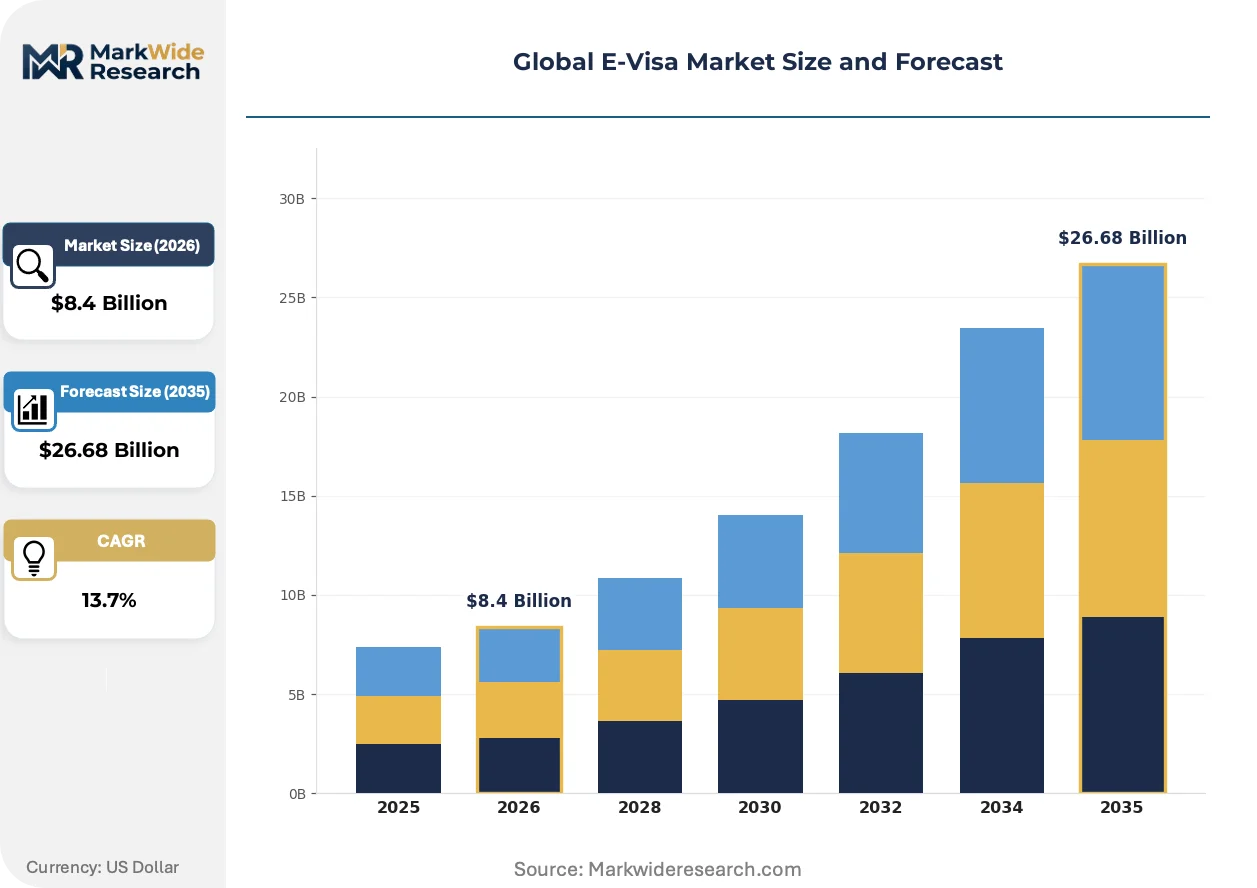
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Visa Type: Tourist, Business, Student, Transit, Medical, Crew Application Platform: Web Portal, Mobile App, Kiosk, Call Center, Email, Travel Agency End User Type: Individual Travelers, Corporate Clients, Educational Institutions, Government Agencies, Non-Governmental Organizations Service Model: Self-Service, Assisted Service, Third-Party Processing, Premium Processing |
| Companies Covered | Thales Group, Mühlbauer Group, IDEMIA, VFS Global, BLS International Services Ltd., 4G Identity Solutions, Entrust Corporation, Securiport, Canadian Bank Note Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Visa Market Shifts & Advancements
Artificial intelligence is penetrating document authentication workflows, compressing the gap between application submission and biometric enrollment while raising new questions about algorithmic transparency in visa adjudication decisions.
Computer vision systems trained on ICAO-compliant document templates are automating optical character recognition and security feature verification at consular checkpoints, reducing manual document review headcount requirements by immigration officers. Schengen-area governments are deploying these systems at scale ahead of EES deadlines, with France and Germany leading procurement volumes for automated visa processing kiosks. The technology is automating routine eligibility screening, enabling human reviewers to concentrate on complex cases requiring discretionary judgment.
REACH chemical restrictions on persistent organic pollutants are reshaping substrate specifications for visa document laminates and security inks, forcing secure printing vendors to reformulate product lines around biodegradable polymer alternatives. The regulation's industrial consequence extends to document durability testing protocols, as new materials must demonstrate equivalent resistance to tampering and environmental degradation. EU member states are responding through coordinated procurement specifications that harmonize environmental compliance with security performance benchmarks.
Travelers are abandoning consular web portals in favor of mobile-native application experiences that embed passport scanning, selfie capture, and payment processing within single-session workflows. This behavioral shift is disrupting the traditional physical-digital hybrid model controlled by legacy service providers, with airline and online travel agency apps emerging as preferred distribution channels. Singapore and the United Arab Emirates exhibit the most pronounced migration patterns, where government-developed mobile platforms now capture majority transaction share for eligible visa categories.
Global E-Visa Market Segmentation
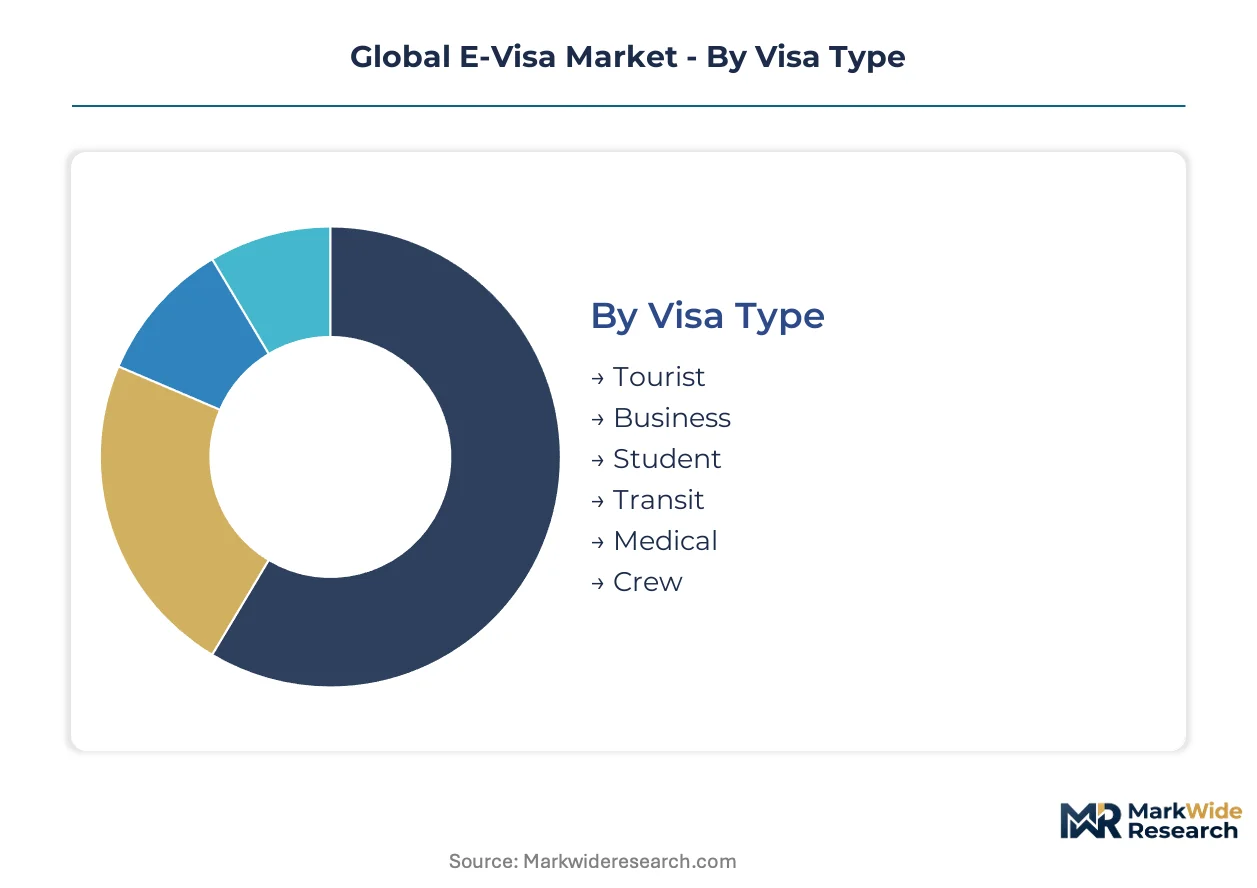
E-visa market segmentation reveals how platform providers must architect differentiated service tiers across visa categories, application channels, and client relationships. Procurement patterns diverge sharply between sovereign immigration agencies seeking integrated border management systems and individual travelers demanding frictionless mobile experiences.
Visa Type:
Platform engineering resources concentrate disproportionately around high-volume visa categories that drive biometric database scaling requirements and consular workflow automation.
- Tourist:Machine-readable travel authorizations incorporating ICAO Doc 9303 biometric standards dominate transaction volumes across India's Bureau of Immigration portals and UAE visa-on-arrival systems. India's mobile-first digitization mandate for tourist arrivals is compressing turnaround timelines to under 72 hours.
- Business:API-integrated processing pipelines enable corporate travel management platforms to embed visa procurement directly into booking workflows. Multinational enterprises in Singapore and Germany are negotiating dedicated account structures with compressed adjudication windows.
- Student:Long-stay authorization workflows requiring educational institution sponsorship verification.
- Transit:Short-duration permits for airport transfer corridors.
- Medical:Specialized channels linking to hospital admission documentation.
- Crew:Maritime and aviation personnel authorizations with recurring validity cycles.
Tourist visa processing absorbs the bulk of installed platform capacity; Business visa digitization is expanding most quickly as corporate travel programs consolidate vendor relationships.
Application Platform:
Distribution channel strategies diverge between legacy consular web infrastructure and emerging mobile-native experiences that bypass traditional enrollment centers.
- Web Portal:Browser-based submission systems remain the default for first-time applicants and complex visa categories requiring document upload protocols. Schengen-area governments are retrofitting these portals for EES compliance ahead of biometric border mandate deadlines.
- Mobile App:Single-session workflows embedding passport OCR, selfie capture, and payment processing are capturing majority transaction share in Singapore and UAE government-developed platforms. Smartphone penetration across emerging economies is accelerating channel migration.
- Kiosk:Automated enrollment terminals at airports and consular posts.
- Call Center:Voice-assisted application support for digital literacy gaps.
- Email:Legacy submission channels for diplomatic and exceptional cases.
- Travel Agency:Intermediary-led processing for package tour operators.
Web Portal infrastructure carries the heaviest maintenance burden; Mobile App deployment is climbing the fastest as traveler behavior shifts toward native application experiences.
End User Type:
Customer acquisition economics vary dramatically between high-frequency corporate accounts and sporadic individual applicants with divergent support requirements.
- Individual Travelers:Mass-market applicants seeking lowest-cost processing channels with standard turnaround timelines. India's digitization push has redirected millions of individual applications from paper-based consular submissions to automated portals.
- Corporate Clients:Enterprise accounts demanding pre-cleared traveler databases, dedicated relationship management, and API connectivity into expense management systems. Premium pricing tolerances support accelerated biometric enrollment scheduling.
- Educational Institutions:Bulk sponsorship workflows for international student cohorts.
- Government Agencies:Inter-governmental visa facilitation and diplomatic protocols.
- Non-Governmental Organizations:Humanitarian and mission-specific authorization channels.
Individual Travelers generate the highest absolute transaction volumes; Corporate Clients are gaining share fastest as enterprise travel programs consolidate around integrated visa management platforms.
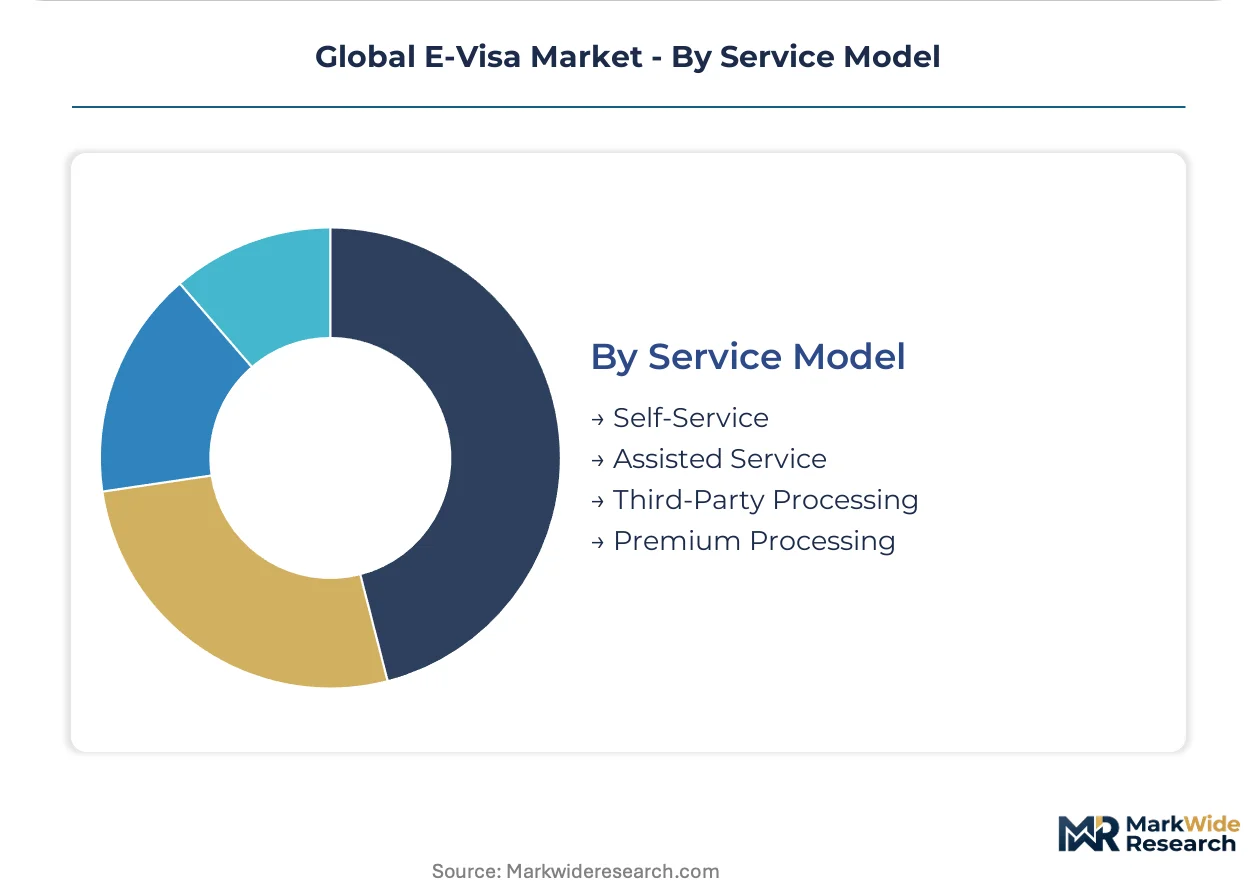
Service Model:
Margin structures stratify sharply between zero-touch automation and high-touch assisted services requiring human adjudication intervention.
- Self-Service:Fully automated eligibility screening, document verification, and biometric scheduling without consular officer review. France and Germany are deploying these models at scale for standardized tourist visa categories.
- Premium Processing:Concierge-tier services with dedicated enrollment center access, expedited adjudication, and relationship manager assignment. UAE Golden Visa expansion is driving demand for long-term residency premium tiers targeting remote workers and investors.
- Assisted Service:Hybrid models combining digital submission with human guidance.
- Third-Party Processing:Outsourced application handling through visa facilitation contractors.
Self-Service platforms handle the greatest application throughput; Premium Processing is expanding most rapidly as high-net-worth individual programs proliferate across Gulf Cooperation Council member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India, the United Arab Emirates, and Singapore concentrate the heaviest transaction volumes as sovereign governments accelerate consular digitization mandates. Each jurisdiction deploys distinct regulatory frameworks that reshape vendor procurement patterns and platform specifications.
India
The Bureau of Immigration's digital mandate drives tourist visa-on-arrival digitization through mobile-first portals. India's PLI scheme for electronics manufacturing indirectly supports domestic biometric document production capacity expansion. Bangalore and Hyderabad host the primary technology development clusters for consular automation platforms.
United Arab Emirates
Golden Visa expansion for remote workers and investors generates premium-tier processing demand with dedicated enrollment centers. MOHAP oversees health-integrated visa workflows linking medical tourism authorizations to hospital admission systems. Dubai's smart city infrastructure anchors the Gulf's most advanced biometric border gate deployments.
Singapore
Government-developed mobile platforms now capture majority transaction share for eligible visa categories as smartphone penetration deepens. The Immigration and Checkpoints Authority mandates API-integrated corporate travel workflows for multinational enterprise accounts. The city-state's fintech corridor enables real-time payment processing embedded within single-session visa applications.
Germany
EES compliance deadlines force replacement of legacy stamp-based systems with automated e-visa and e-gate integrations ahead of biometric border mandates. KBA consultation on secure document standards influences procurement specifications across Schengen-area consular networks. Berlin and Munich concentrate the largest deployment contracts for automated visa processing kiosks.
United States
Customs and Border Protection accelerates ESTA platform modernization to incorporate enhanced biometric verification protocols for visa-waiver travelers. FAA coordination on crew visa digitization supports aviation sector-specific authorization workflows. Washington DC and Atlanta host the primary system integration hubs for federal immigration technology procurement.
Global E-Visa Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-native distribution channels and AI-augmented document verification. The vendor base stratifies between integrated border management platform providers and specialized biometric enrollment service operators. Three archetypes dominate: aerospace-defense conglomerates leveraging document security portfolios, pure-play identity technology specialists, and physical-digital hybrid service intermediaries. Consolidation pressure intensifies through strategic partnerships between hardware manufacturers and software platform developers, while geographic expansion into African and Southeast Asian greenfield markets accelerates contract competition.
Within the integrated platform tier, Thales Group and IDEMIA exemplify contrasting strategic positions. Thales anchors large-scale deployments across multiple continents through its biometric document portfolio and established government relationships. IDEMIA occupies a specialist position in identity verification workflows that reduce processing friction at consular checkpoints. VFS Global represents the hybrid service archetype, bridging online applications with physical biometric enrollment center networks to sustain intermediary control over traveler touchpoints.
| Leading Market Players |
|---|
| Thales Group |
| Mühlbauer Group |
| IDEMIA |
| VFS Global |
| BLS International Services Ltd. |
| 4G Identity Solutions |
| Entrust Corporation |
| Securiport |
| Canadian Bank Note Company |
| Others |
Supply & Pricing Matrix
Sovereign immigration agencies consolidating vendor relationships for integrated border management systems anchor pricing power toward platform providers capable of delivering end-to-end biometric infrastructure. Government procurement programs favor multi-year service contracts with embedded hardware refresh cycles, compressing margins for pure-play software vendors unable to capture document production revenue streams.
Pricing Analysis
High-volume tourist visa processing through automated portals generates thin per-transaction margins offset by biometric database scaling efficiencies, while premium corporate service tiers capture outsized returns through dedicated account management and API integration fees. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by processing speed, human adjudication access, and enrollment center convenience. Pricing pressure stems from mobile-native platform entrants disrupting traditional physical-digital hybrid intermediaries. Individual travelers exhibit highest price sensitivity, whereas multinational enterprises tolerate premium tiers for compressed turnaround timelines.
Supply Chain Analysis
Reverse-logistics flows for expired biometric documents and decommissioned enrollment hardware create secondary material recovery channels, particularly for secure element chips and specialized polymer substrates. Secure element chip fabrication concentrates in Taiwan and South Korea, with document laminate production anchored in Germany and India. The supply chain draws from semiconductor foundries, cryptographic module suppliers, and biometric sensor manufacturers. Single-source vulnerability in advanced chip fabrication represents the dominant structural risk. Distribution runs through government procurement frameworks and direct vendor contracts with immigration agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-visa market is becoming a vertical-integration race as platform providers pursue backward integration into secure document manufacturing to capture hardware margins and accelerate deployment timelines.
For Market Incumbents: Hedge against mobile-native disruption by acquiring specialized biometric enrollment software firms and securing exclusive chip supply agreements with Taiwanese foundries. Consolidate around integrated platform architectures that bundle document production, identity verification workflows, and backend database interoperability to defend against pure-play SaaS entrants. Prioritize certification investment in Common Criteria EAL4+ evaluation to extend contract renewal cycles. For New Entrants and Emerging Players: Begin with white-space targeting of Sub-Saharan African greenfield deployments in Kenya, Nigeria, and Ghana, where shared biometric verification infrastructure for regional mobility protocols lacks established vendor relationships. Pursue mobile wallet convergence opportunities embedding e-visa tokens into Apple Wallet and Google Pay ecosystems, bypassing traditional consular web portals. Anchor go-to-market strategy through airline and online travel agency distribution partnerships rather than direct government procurement. For Investors and Strategic Acquirers: The window for entry favors identity verification workflow specialists with ICAO Doc 9303 compliance expertise and established government relationships. Long-term viability hinges on platform scalability across multiple sovereign jurisdictions rather than single-market dependency. Monitor EES implementation deadlines and biometric border mandate compliance progress as inflection indicators for contract acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Document Manufacturing Integration | Captures hardware margins and accelerates deployment timelines for large-scale e-visa platforms. |
| Mobile Wallet Convergence Partnership | Creates distribution channels that bypass traditional consular web portals for eligible traveler segments. |
| Common Criteria EAL4+ Certification Investment | Compresses vendor revenue recognition cycles and reduces pre-contract engineering cost inflation. |
| Sub-Saharan African Market Entry | Opens greenfield platform deployment contracts for regional mobility protocol infrastructure. |
| API-Integrated Corporate Travel Workflow | Embeds visa procurement directly into multinational enterprise booking systems for premium pricing capture. |
Research Methodology
Multi-period observation of biometric border infrastructure procurement timelines, mobile application transaction share migration, and sovereign data localization mandate adoption anchored the trend analysis, supplemented by interviews with immigration technology procurement officers, biometric system integration specialists, consular operations directors, and secure document manufacturing executives. Secondary validation drew from ICAO implementation reports, EU EASO technical specifications, Indian Bureau of Immigration digitization disclosures, and customs trade data on secure element chip flows. Bottom-up transaction volume modeling and top-down market sizing triangulation reconciled segment-level estimates.
Input-output matrix framing connected visa category transaction volumes to platform capacity requirements, application channel mix shifts to infrastructure investment patterns, and regulatory compliance deadlines to procurement acceleration indicators across the projection horizon. Segmentation dimensions modeled include visa type, application platform, end user category, and service tier. CAGRs derived from regression analysis against smartphone penetration curves, biometric database scaling rates, and government digitization mandate implementation schedules.
EES deadline delays, semiconductor supply disruptions, and biometric algorithm bias litigation are the dominant revision risks that could compress forecasted transaction volumes or extend platform deployment timelines. Practitioners should monitor Schengen-area implementation progress, secure element chip lead time indicators, and regulatory enforcement actions on algorithmic transparency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Europe API Management Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Digital BSS Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Digital Evidence Management System Market