
 Digital Check Scanning Solutions Market | 2026-2036
Digital Check Scanning Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Check Scanning Solutions Market Analysis
Market Context
High-speed image capture specifications above 200 documents per minute is bifurcating vendor tiers across the competitive landscape. NCR Corporation leverages its installed base of teller automation systems to sustain recurring service revenue across North American banking networks. Digital Check Corporation specializes in compact desktop units designed for community bank branches and credit union operations. Panini S.p.A. dominates European markets with hardware optimized for multi-currency and multilingual check environments.
Technical Definition and Segment Structure
Digital check scanning solutions encompass electromechanical devices and software platforms that capture high-resolution images of paper checks, read magnetic ink character recognition lines, and transmit digitized data to clearing networks for settlement. These systems typically operate at 150-300 dots per inch optical resolution with dual-sided scanning capability to meet ANSI X9.100-181 image quality standards for interchange and truncation. Multi-feed scanners command the largest installed base among product categories due to throughput requirements at high-volume bank branches and centralized operations centers. Cloud-based solutions represent the fastest-expanding technology segment as financial institutions depreciate on-premise capture servers in favor of software-as-a-service architectures with embedded artificial intelligence for fraud pattern recognition. Remote deposit capture applications generate substantial recurring software licensing revenue while mobile check deposit functionality drives incremental peripheral sales to small business banking clients.
Regulatory Framework and Outlook
The Federal Reserve Board governs check collection and return processes under Regulation CC in the United States, while the European Banking Authority coordinates digital payment infrastructure standards including image format interoperability across EU member states. The Monetary Authority of Singapore and the Reserve Bank of India have issued comparable truncation mandates that accelerate replacement cycles for legacy magnetic reader equipment. Financial institutions must evaluate vendor roadmaps for real-time payment integration capabilities as check volumes decline and instant settlement protocols gain regulatory endorsement across multiple jurisdictions.
Market Dynamics
Cloud-based capture architectures are displacing on-premise server installations across financial institutions, compressing hardware refresh cycles and redirecting capital toward software-as-a-service licensing models with embedded fraud detection capabilities.
Growth Catalysts
- Check 21 Act truncation mandates:US financial institutions must maintain image-quality standards for exchange, forcing replacement of legacy magnetic readers with dual-sided scanners.
- Community bank branch modernization:Credit unions and regional banks deploy compact multi-feed units to reduce teller transaction times and eliminate courier-based clearing.
- Artificial intelligence integration:Machine learning algorithms for signature verification and anomaly detection drive incremental software attach rates to hardware contracts.
Market Restraints
- Semiconductor supply concentration:Image sensor and processor fabrication concentrates in East Asian foundries, exposing scanner OEMs to allocation volatility.
- Declining check transaction volumes:Real-time payment networks displace paper instruments in consumer and commercial segments, compressing addressable hardware demand.
- ANSI X9.100-181 compliance costs:Certification testing for image quality standards adds fixed development overhead for new product introductions.
Strategic Opportunities
- India truncation acceleration:Reserve Bank of India mandates for digital clearing create replacement demand among cooperative banks and regional rural banks.
- Mobile RDC peripheral expansion:Small business banking clients require compact Bluetooth-enabled scanners for remote deposit capture beyond smartphone camera limits.
- API-first platform architectures:Open banking standards enable third-party fintech integration with capture-as-a-service offerings.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for high-speed image pipelines competes with automotive and medical device sectors for specialized engineers.
- Legacy core banking integration:Decades-old host systems require custom middleware development for cloud-native capture platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Check Scanning Solutions Market |
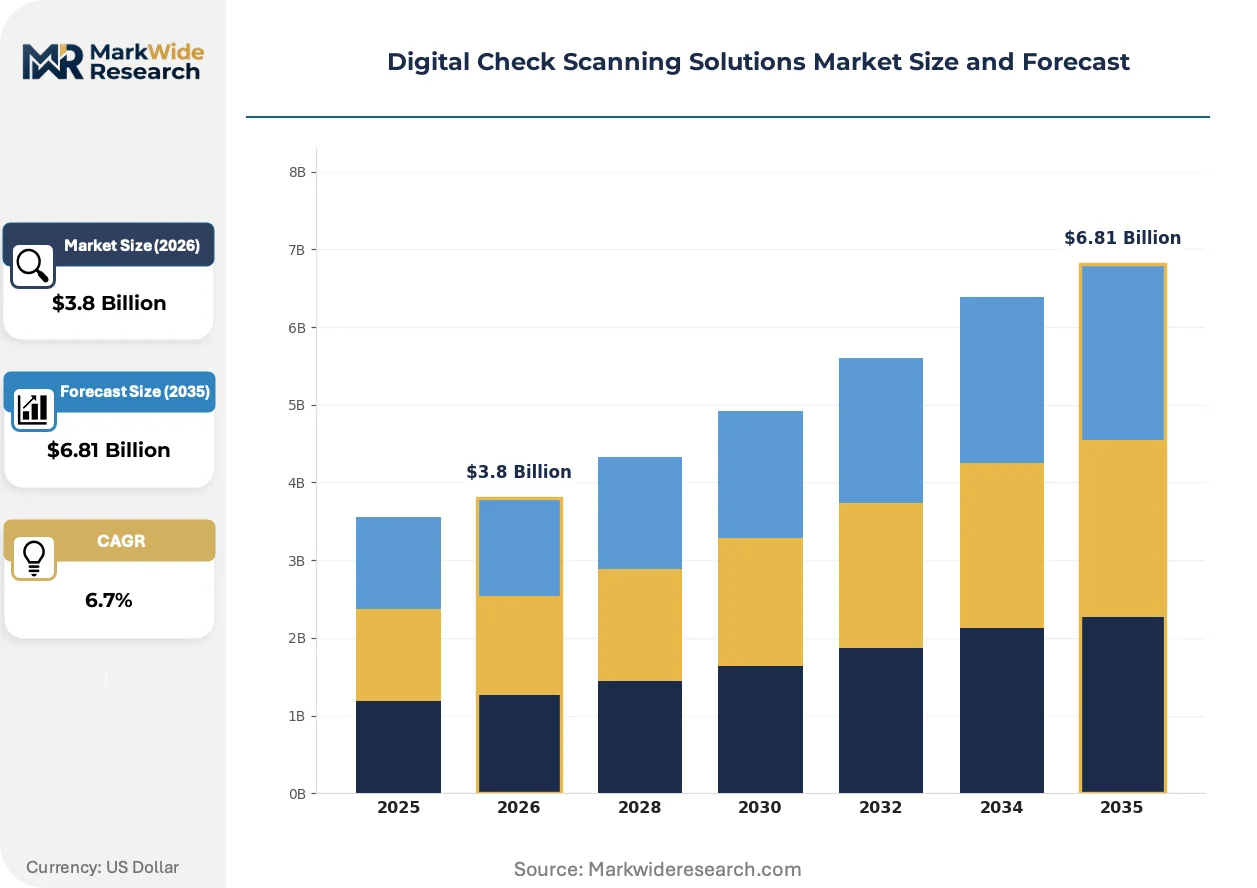
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Feed Scanners, Multi-Feed Scanners, Check Imaging Solutions, Teller Scanners End User: Banks, Credit Unions, Retailers, Payment Processors Technology: Magnetic Ink Character Recognition, Optical Character Recognition, Image Processing, Cloud-Based Solutions Application: Remote Deposit Capture, In-Branch Deposits, Mobile Check Deposit, Fraud Detection |
| Companies Covered | NCR Corporation, Digital Check Corporation, Panini S.p.A., Epson America, Inc., Canon U.S.A., Inc., ARCA Tech Systems, RDM, MagTek Inc., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Check Scanning Solutions Market Emerging Trajectories
Real-time payment adoption is compressing check clearing timelines and forcing scanner vendors to reposition hardware as multi-channel capture nodes rather than single-purpose instruments.
Dual-sided scanning at 240 dots per inch is bifurcating vendor tiers between premium units for high-volume operations centers and compact desktop models for branch deployment. Tier-one banks consolidate procurement around 300-document-per-minute specifications while community institutions accept 75-document-per-minute throughput. This specification divergence is compressing mid-range product viability and forcing OEMs to choose volume or margin positioning.
The European Banking Authority's image format interoperability standards are mandating JPEG 2000 compression and XML metadata packaging for cross-border clearing. Scanner firmware must embed codec licenses and schema validation engines. Hardware vendors serving EU member states face accelerated obsolescence for pre-2020 installed bases lacking these capabilities.
Small business banking clients now demand scanner-as-a-service subscriptions bundling hardware, maintenance, and software updates under per-transaction pricing. Traditional capital equipment purchasing contracts lose share to operational expenditure models. This preference shift concentrates among US credit unions and UK building societies seeking to reduce upfront technology commitments.
Digital Check Scanning Solutions Market Segmentation
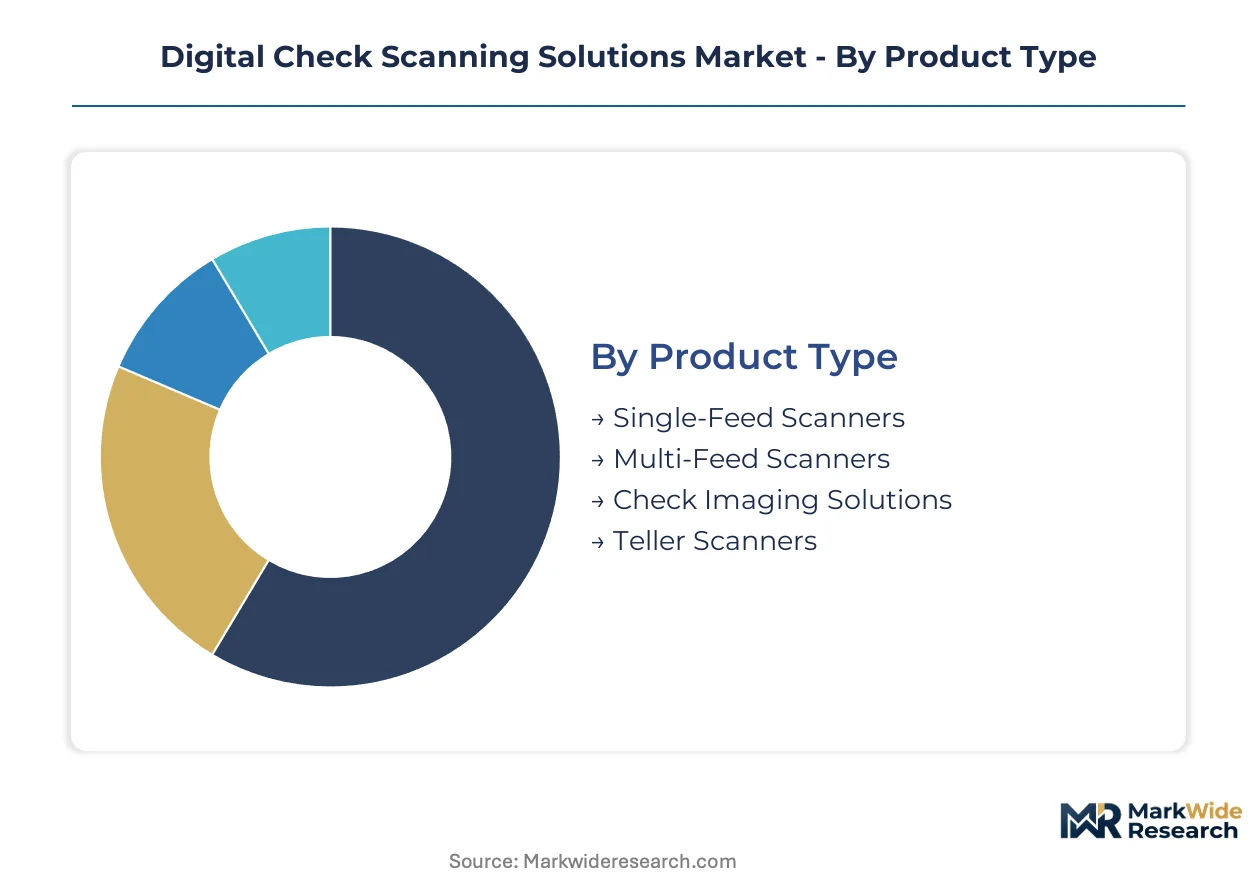
Segmentation reveals how substitution pressures from real-time payments and mobile banking reshape demand across hardware categories and software platforms. Understanding these fault lines helps vendors allocate R&D resources between legacy capture infrastructure and emerging cloud-native architectures.
Product Type:
Multi-feed scanners face the strongest substitution threat as centralized operations centers consolidate toward fewer, higher-capacity units while branches downsize to compact alternatives.
- Multi-Feed Scanners:Electromechanical devices process 150-300 documents per minute with dual-sided image capture at 240 dots per inch resolution. Demand concentrates at US money center banks and Canadian chartered banks modernizing high-volume operations centers under Check 21 Act and similar truncation mandates.
- Single-Feed Scanners:Desktop units designed for low-volume environments with manual document feeding and reduced throughput specifications. Credit union branches and small business banking operations in the United Kingdom favor these units for cost-containment during branch footprint reduction.
- Check Imaging Solutions:Software platforms managing image quality validation, compression, and clearing network transmission.
- Teller Scanners:Integrated peripherals embedded within branch automation workstations for real-time transaction processing.
Multi-feed scanners anchor the volume base while cloud-enabled imaging solutions gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich institutions pursuing full-stack modernization from budget-constrained players seeking incremental upgrades.
- Banks:Tier-one institutions deploy enterprise-scale capture infrastructure with embedded artificial intelligence for fraud pattern recognition. JPMorgan Chase and Bank of America drive specifications above 300 documents per minute for centralized operations centers.
- Payment Processors:Fiserv and Fidelity National Information Services operate multi-tenant platforms serving thousands of financial institutions.
- Credit Unions:Member-owned cooperatives prioritize compact desktop units and scanner-as-a-service subscriptions to reduce upfront capital commitments.
- Retailers:Big-box merchants and grocery chains deploy check capture for cash management and vendor payment processing.
Banks dominate absolute spending while payment processors expand most quickly through platform consolidation.
Technology:
Application requirements determine whether legacy magnetic reading or modern optical pipelines prove sufficient for compliance and fraud detection workloads.
- Cloud-Based Solutions:Software-as-a-service architectures replace on-premise capture servers with API-first platforms enabling third-party fintech integration. US regional banks and UK building societies lead migration to reduce data center overhead.
- Image Processing:High-resolution pipelines with JPEG 2000 compression and XML metadata packaging meet European Banking Authority interoperability standards.
- Magnetic Ink Character Recognition:Legacy line-reading technology for routing number and account identification extraction.
- Optical Character Recognition:Character recognition for amount verification and payee field extraction.
Image processing underpins current installed bases while cloud-based solutions climb the fastest toward majority share.
Application:
Volume concentration varies sharply between high-frequency branch transactions and episodic remote capture events.
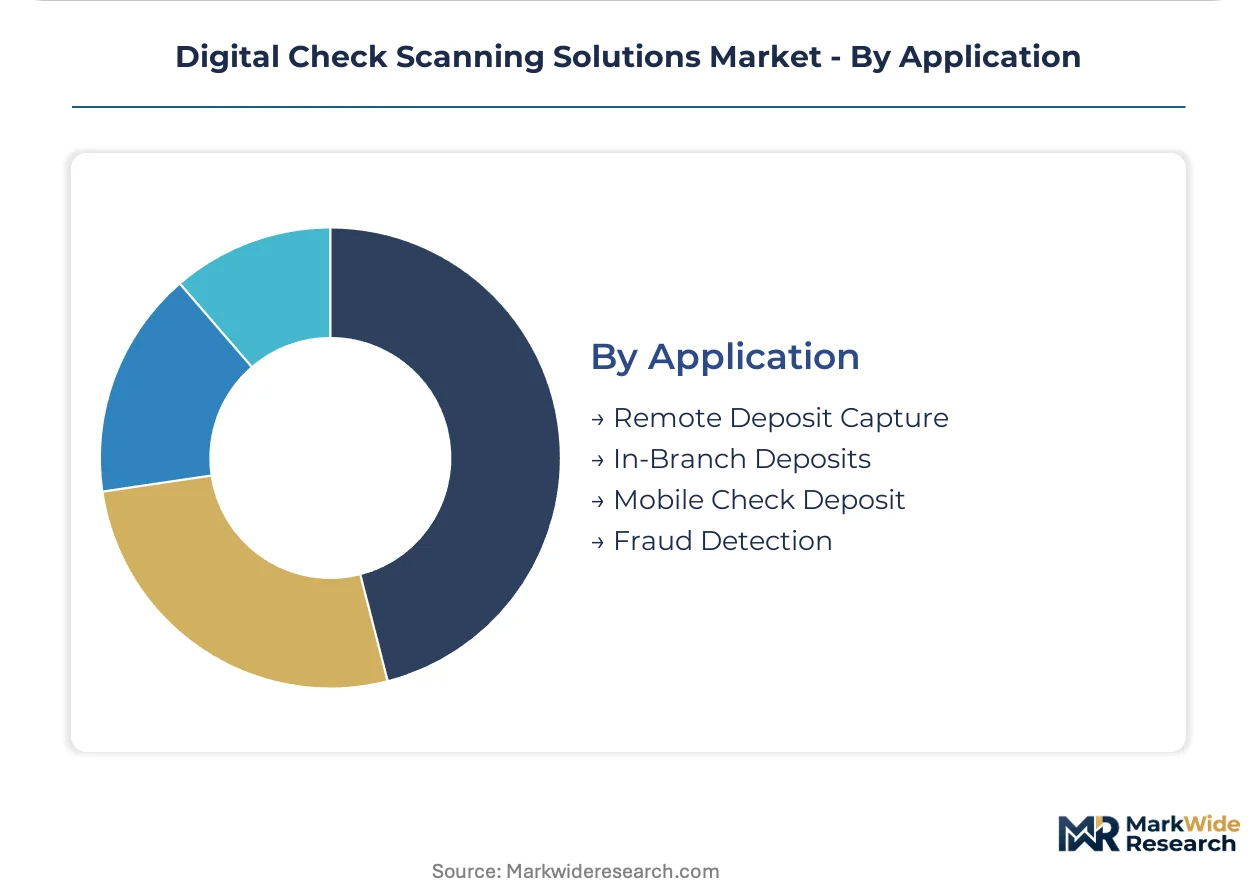
- Remote Deposit Capture:Desktop and mobile-enabled capture for small business clients depositing checks without branch visits. US community banks bundle Bluetooth-enabled peripherals with treasury management services.
- Fraud Detection:Machine learning algorithms analyze signature patterns, check stock authenticity, and transaction anomalies in real time.
- In-Branch Deposits:Teller-assisted and self-service kiosk capture for retail and commercial clients.
- Mobile Check Deposit:Smartphone camera-based capture with software-only processing for consumer banking applications.
In-branch deposits retain the largest transaction volume while fraud detection commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for image sensor components concentrates procurement risk in East Asian supply chains, while finished scanner exports flow predominantly toward North American and European financial centers. The United States maintains the largest trade surplus in check imaging software and cloud platforms. Regional regulatory divergence around truncation timelines and image quality standards fragments vendor certification requirements across jurisdictions.
United States
Community banks and credit unions drive hardware refresh cycles as legacy magnetic reader infrastructure ages past twenty-year service lives. The Federal Reserve Board's Regulation CC governs check collection timeframes and return processes, mandating interoperability standards that shape vendor development roadmaps. Chicago and Charlotte banking clusters concentrate procurement decision-making for tier-one institutions consolidating high-volume operations centers.
Canada
Chartered banks modernize branch capture infrastructure under federal truncation mandates accelerating paper displacement. Payments Canada coordinates image exchange standards and clearing network protocols across domestic financial institutions. Toronto's financial district anchors vendor sales activity, with regional banks in Vancouver and Montreal following procurement patterns set by headquarters operations.
United Kingdom
Building societies and challenger banks favor scanner-as-a-service subscriptions to minimize upfront capital commitments during branch network rationalization. The Financial Conduct Authority supervises payment system compliance, including image clearing standards administered through the Cheque and Credit Clearing Company. London's Square Mile concentrates fintech integration demand, while regional hubs in Manchester and Birmingham lag adoption timelines by eighteen to twenty-four months.
India
Cooperative banks and regional rural banks face replacement pressure from Reserve Bank of India mandates for digital clearing infrastructure. The central bank's phased truncation deadlines force hardware procurement decisions among historically underinvested institutions. Mumbai's financial district and Bangalore's technology corridor concentrate vendor implementation resources, with secondary demand emerging from Pune and Hyderabad banking clusters.
Germany
Savings banks and cooperative credit institutions pursue incremental modernization rather than wholesale infrastructure replacement. BaFin supervises payment system compliance, while the Deutsche Bundesbank coordinates image exchange standards within European Banking Authority frameworks. Frankfurt's banking quarter anchors procurement for large commercial banks, with Stuttgart and Munich clusters driving mid-market demand for compact desktop units.
Digital Check Scanning Solutions Market Vendor Landscape
Concentration sits with diversified technology conglomerates and specialized financial hardware vendors rather than pure-play scanner manufacturers. Tier-one procurement gravitates toward vendors offering integrated branch automation ecosystems, while mid-market institutions prioritize cost-optimized single-function devices. Two strategic archetypes dominate: full-stack platform providers bundling hardware with software and maintenance contracts, and component specialists supplying image capture modules to OEM integrators. Competitive moves center on cloud platform partnerships and API-first architecture development to capture recurring revenue streams.
Within the full-stack tier, NCR Corporation and Fujitsu Limited represent integrated platform vendors with established teller automation footprints, while Panini S.p.A. exemplifies regional specialists commanding European market segments through multi-currency optimization. Digital Check Corporation occupies a position as a focused community banking specialist. These three anchors demonstrate how vendor archetypes align with institutional tier and geographic concentration rather than pursuing undifferentiated global scale.
| Leading Market Players |
|---|
| NCR Corporation |
| Digital Check Corporation |
| Panini S.p.A. |
| Epson America, Inc. |
| Canon U.S.A., Inc. |
| ARCA Tech Systems |
| RDM |
| MagTek Inc. |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
ANSI X9.100-181 certification gates both vendor qualification and price stratification across scanner tiers, forcing OEMs to absorb fixed testing overhead while tier-one banks extract volume discounts that compress mid-range margins.
Pricing Analysis
Tier-one banks anchor pricing leverage through consolidated procurement of 300-document-per-minute specifications, while credit unions and regional institutions face premium markups on sub-scale orders. Pricing stratifies across enterprise, mid-market, and compact desktop tiers based on throughput certification and embedded AI fraud-detection bundling. Cost compression in the mid-market tier is intensifying because specification divergence eliminates viable positioning between high-volume and branch-optimized units. Credit unions demonstrate the highest price sensitivity due to capital constraints, whereas money-center banks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Trans-Pacific container availability constraints and port congestion at Los Angeles-Long Beach elevate inbound logistics costs for image sensor modules sourced from East Asian foundries. Scanner OEMs draw from Taiwan, South Korea, and Japan for CMOS sensors, processors, and precision optical components. Single-source vulnerability concentrates in advanced image pipeline semiconductors where automotive and medical device sectors compete for allocation. Distribution runs through authorized reseller networks serving North American banking clusters, with direct OEM relationships dominating tier-one procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scanner-as-a-service subscriptions and fraud-detection software attach rates are expanding faster than hardware shipments, reframing vendor economics around recurring revenue capture rather than capital equipment sales.
For Market Incumbents: Consolidate service contract portfolios through multi-year scanner-as-a-service offerings that embed predictive maintenance and AI-powered anomaly detection, locking out fintech challengers attempting API-first disintermediation. Deepen backward integration into image processing firmware to reduce licensing exposure for JPEG 2000 codecs mandated by European Banking Authority standards. For New Entrants and Emerging Players: Anchor in India's cooperative bank segment where Reserve Bank of India truncation deadlines force hardware procurement decisions among historically underinvested regional rural banks lacking legacy vendor relationships. Pursue Bluetooth-enabled mobile RDC peripherals for US small business banking clients, bundling hardware with treasury management software through credit union channel partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native capture platforms as software-as-a-service architectures displace on-premise server installations and compress hardware refresh cycles. Target acquisition candidates with established API-first platforms and embedded machine learning fraud detection capabilities. Monitor real-time payment network adoption rates as the critical signal for check volume trajectory and hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Software-as-a-service architectures reduce data center overhead for US regional banks and UK building societies. |
| AI Fraud Detection Integration | Machine learning algorithms for signature verification drive incremental software attach rates to hardware contracts. |
| Mobile RDC Peripheral Expansion | Bluetooth-enabled scanners capture small business banking clients beyond smartphone camera deposit limits. |
| India Market Penetration | Reserve Bank of India truncation mandates create replacement demand among cooperative and rural banks. |
| API-First Architecture Development | Open banking standards enable third-party fintech integration with capture-as-a-service offerings. |
Methodological Framework
A standing panel of bank operations executives, credit union technology officers, payment processor platform architects, and scanner OEM product managers provided ongoing calibration against primary interview findings validated through secondary sources including Federal Reserve regulatory filings, Payments Canada clearing statistics, European Banking Authority technical standards, and SEC 10-K disclosures from listed financial technology vendors. Bottom-up unit shipment estimates triangulated against top-down spending data from financial institution IT budget surveys.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with segmentation modeling across product type, end-user tier, deployment technology, and application use case. CAGRs derived from logistic adoption curves fitted to check volume decline trajectories and real-time payment substitution rates, incorporating hardware refresh cycle assumptions and cloud migration timelines specific to regional regulatory environments.
Decision-makers should treat outputs as directional under base assumptions of sustained truncation mandate enforcement and gradual real-time payment adoption; material deviation in check volume decline rates or regulatory timeline acceleration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Social Networking App Market
Digital Solutions
Latin America IT Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Construction Design App Market
Digital Solutions
Digital Signature Market
Digital Solutions
Web Content Management Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Workflow Management System Market
Digital Solutions
United Kingdom ICT Market