
 Application Lifecycle Management (ALM) Market | 2026-2036
Application Lifecycle Management (ALM) Market Size, Share, and Industry Trends Forecast 2026-2036
Application Lifecycle Management (ALM) Market Analysis
Aerospace and defense software procurement is hardening as a dominant demand vertical for ALM platforms. Siemens AG leverages its Polarion acquisition to anchor defense-aerospace workflows with traceability mandates. IBM Corporation sustains relevance through DO-178C and ARP4754A compliance tooling for avionics suppliers. Broadcom differentiates via mainframe-integrated ALM suites that dominate legacy defense IT estates.
Application Lifecycle Management encompasses the integrated governance of software requirements, design, coding, testing, and maintenance through unified toolchain orchestration, typically employing artifact traceability matrices and automated pipeline validation. Its primary commercial purpose is eliminating defect propagation across development stages while enforcing audit-ready documentation for safety-critical industries. Cloud-based deployment now leads growth trajectory as enterprises retire on-premises server farms, though hybrid configurations retain margin concentration among regulated buyers. The DevOps application area is expanding fastest, absorbing continuous integration pipelines into formal ALM governance structures previously reserved for waterfall methodologies.
FAA airworthiness directives and DoD cybersecurity mandates from NIST SP 800-171 shape procurement specifications for defense-sector ALM deployments, while FDA software-as-medical-device guidance extends traceability requirements into healthcare tooling selections. ISO 26262 functional safety standards for automotive software are migrating into ALM vendor roadmaps as OEMs demand ASIL-D qualified toolchain evidence. Stakeholders must monitor how EU AI Act conformity requirements absorb ALM workflows for machine-learning component governance in embedded systems.
Market Dynamics
Defense primes and federal systems integrators in the United States are consolidating procurement around cloud-native ALM suites that embed continuous compliance validation, compressing vendor selection cycles from eighteen months to under six months.
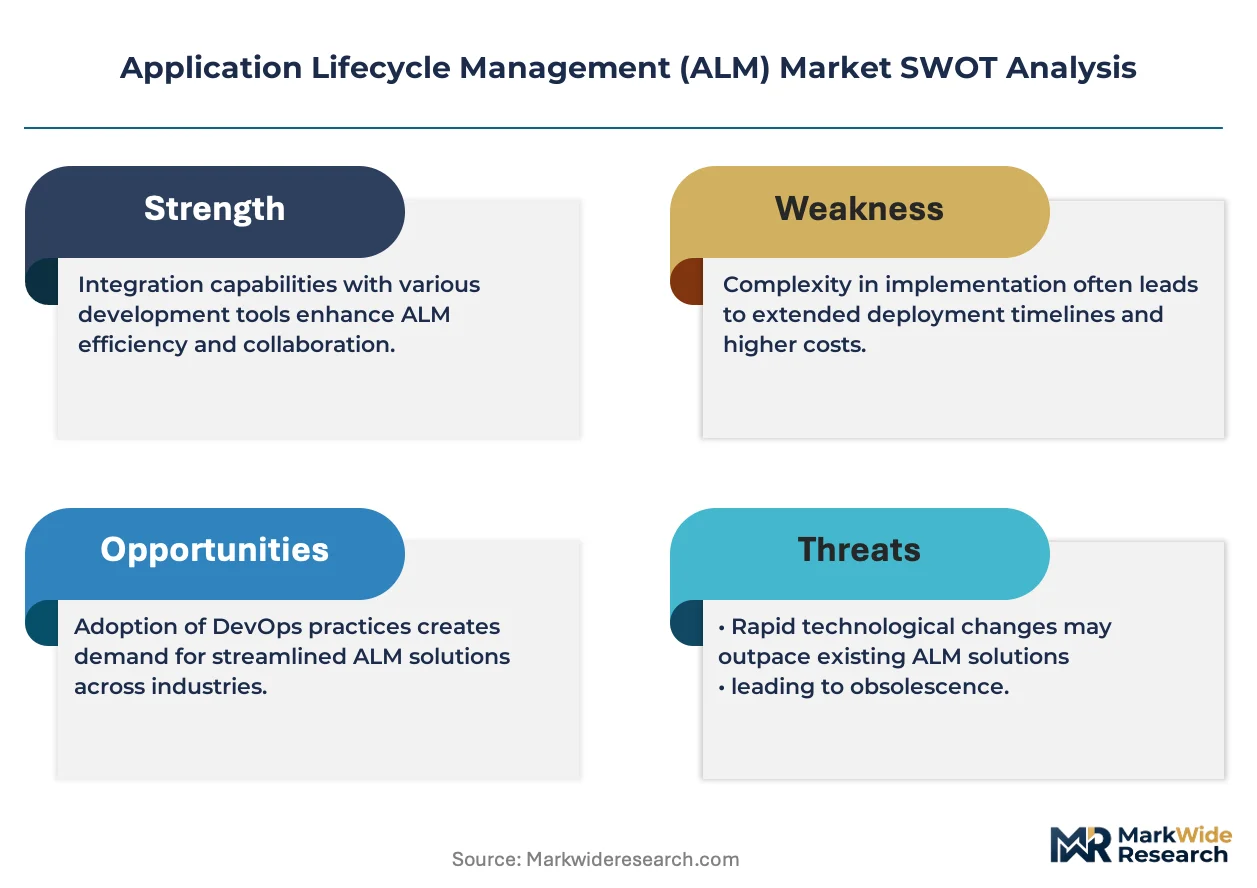
Growth Catalysts
- DO-178C Mandates:FAA airworthiness directives for avionics software traceability are forcing commercial aerospace suppliers to replace document-based workflows with automated ALM pipelines.
- DevOps Convergence:Continuous integration tooling is absorbing formal governance structures previously reserved for waterfall methodologies, expanding ALM addressable scope into enterprise IT modernization.
- NIST SP 800-171:DoD cybersecurity mandates are disqualifying non-compliant ALM vendors from defense contractor shortlists, concentrating demand among qualified toolchain providers.
Market Restraints
- Cloud Migration Friction:Regulated buyers in aerospace and healthcare face eighteen-to-twenty-four-month validation timelines for cloud-native ALM deployments, delaying revenue recognition for vendors.
- Specialized Talent Scarcity:Engineers qualified in both safety-critical standards and modern CI/CD pipelines command compensation premiums that inflate implementation costs.
- Legacy Lock-in:Mainframe-integrated ALM estates at defense primes create switching costs that protect incumbent vendors and slow competitive displacement.
Strategic Opportunities
- EU AI Act Alignment:Machine-learning component governance requirements are creating demand for ALM extensions that trace training data lineage through deployment artifacts.
- ISO 26262 Automotive:ASIL-D qualified toolchain evidence requirements from OEMs are opening adjacent revenue streams for vendors with avionics safety credentials.
- Healthcare Expansion:FDA software-as-medical-device guidance is extending traceability mandates into diagnostic equipment and digital therapeutics tooling selections.
Industry Challenges
- Multi-standard Certification Burden:Vendors must maintain parallel compliance evidence for DO-178C, ARP4754A, ISO 26262, and FDA QSR, fragmenting R&D resources across qualification workflows.
- Hybrid Integration Complexity:Enterprises demand seamless artifact flow between cloud-native pipelines and on-premises legacy systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Lifecycle Management (ALM) Market |
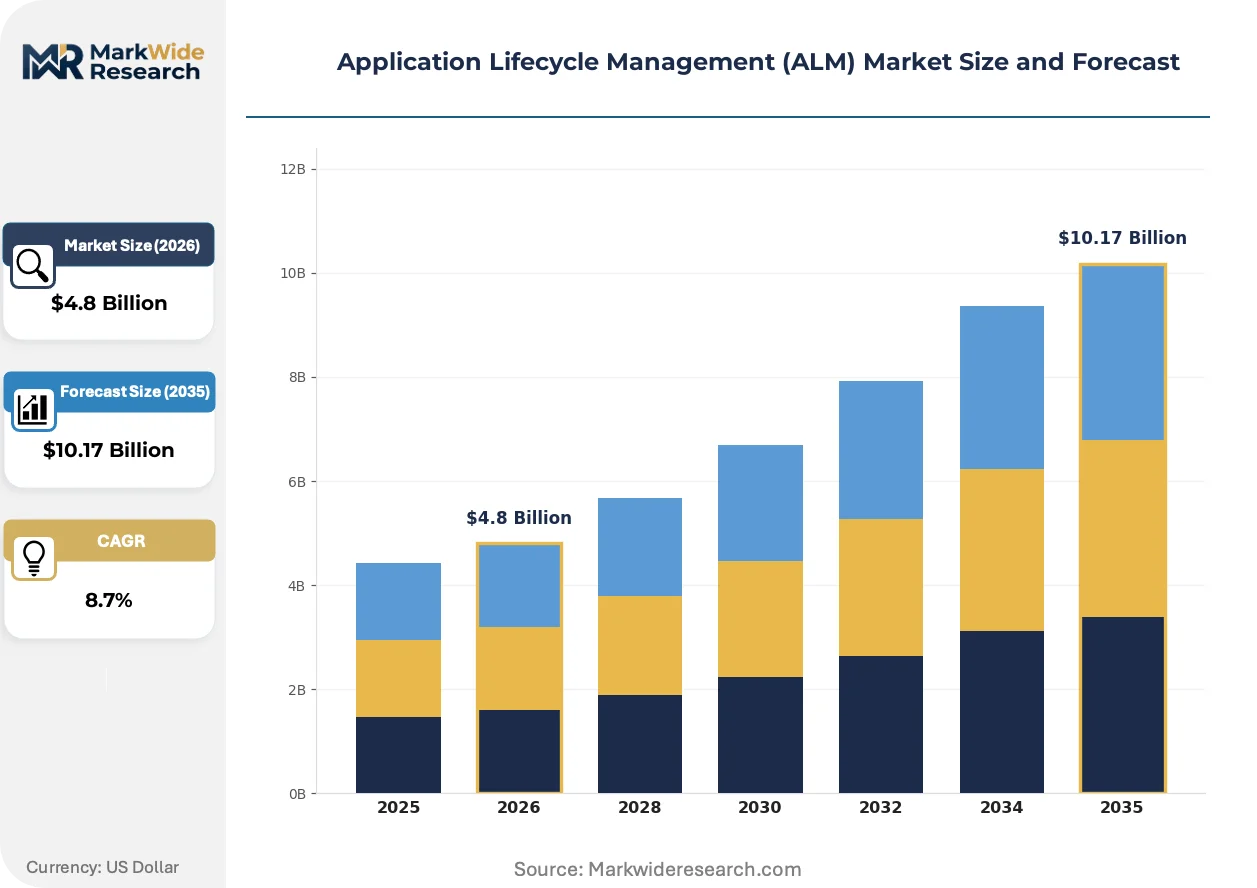
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Dedicated Server End User Type: Enterprise, SMBs, Government, Educational Institutions Service Type: Consulting, Licensing, Technical Support, Managed Services Application Area: Software Development, Project Management, Testing, DevOps |
| Companies Covered | Broadcom, Siemens AG, Microsoft Corporation, PTC Inc., Perforce Software, IBM Corporation, SAP SE, HP Development Company, Atlassian Corporation Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Lifecycle Management (ALM) Market Emerging Trajectories
Software bill of materials (SBOM) automation and machine-learning operations (MLOps) governance are merging into unified ALM workflows, eliminating the historical separation between application development and compliance documentation.
Model-based systems engineering (MBSE) tooling is unifying requirements, architecture, and verification artifacts into live digital threads that auto-generate audit evidence. Defense primes in the United States are piloting these integrations for next-generation combat aircraft programs. This convergence is compressing the systems engineering workforce headcount required for major platform developments.
The EU AI Act conformity assessment framework is mandating traceability for high-risk AI systems through their full lifecycle, extending ALM scope into training data governance and model versioning. Medical device manufacturers in Germany and France are restructuring quality management systems to absorb these requirements. Vendors with existing safety-critical tooling foundations are capturing early specification influence.
Subscription pricing for ALM platforms is displacing perpetual license models among mid-tier aerospace suppliers seeking to convert capital expenditure to operational expenditure. European tier-two avionics contractors are leading this transition to preserve cash for hardware certification programs. Vendor revenue predictability is improving while customer switching friction is declining.
Application Lifecycle Management (ALM) Market Segmentation
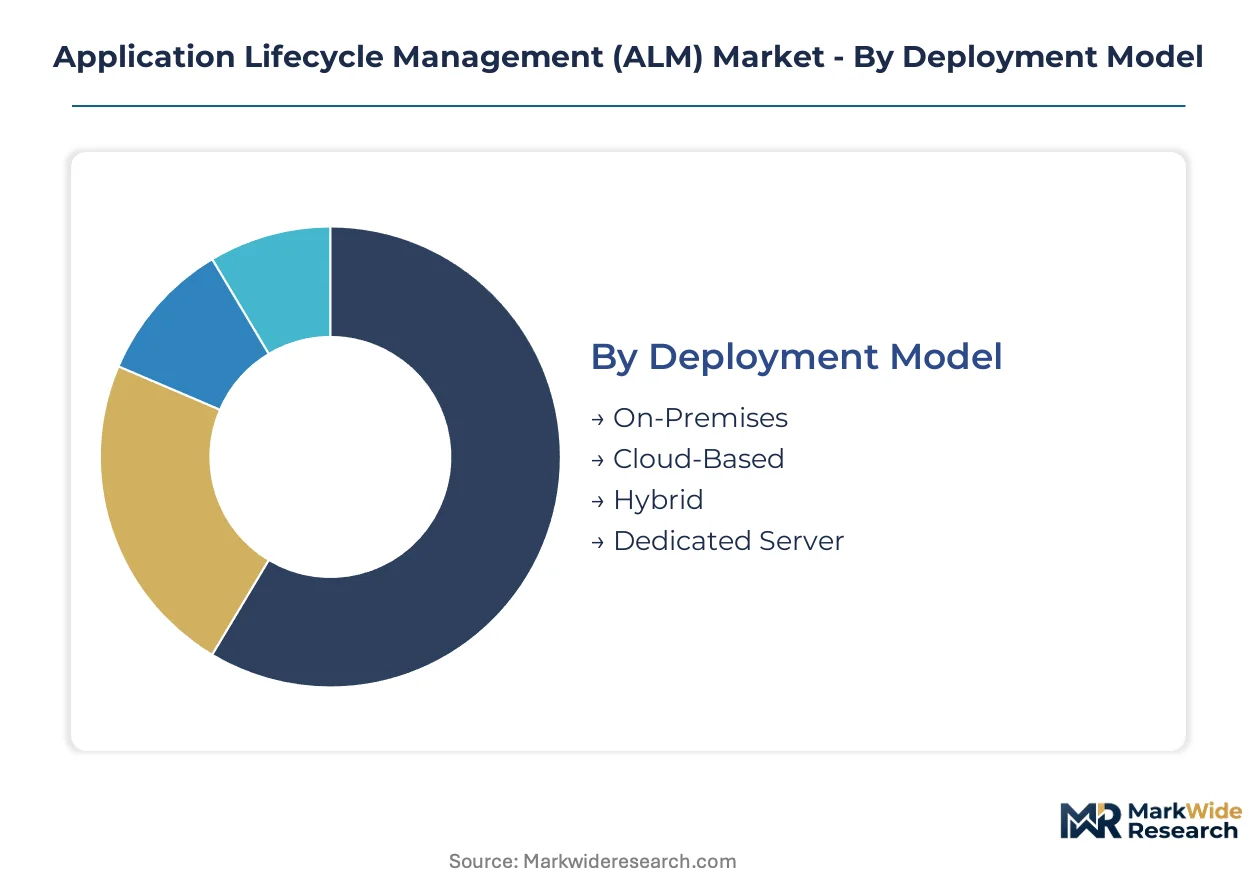
ALM procurement patterns diverge sharply across deployment architectures and buyer categories, with compliance requirements dictating viable configurations for safety-critical verticals. Segmentation clarity enables vendors to align certification investments with addressable revenue pools.
Deployment Model:
Cloud-native configurations face elongated validation cycles for DO-178C and NIST SP 800-171 compliance, while hybrid architectures absorb the bulk of defense contractor procurement.
- On-Premises:Air-gapped installations dominate classified program environments at defense primes, where FAA and DoD auditors mandate physical infrastructure control. Lockheed Martin and Northrop Grumman sustain large on-premises estates for airworthiness certification workflows.
- Cloud-Based:Multi-tenant SaaS platforms are capturing mid-tier aerospace suppliers seeking to convert capital expenditure to operational expenditure. European tier-two avionics contractors in Germany and France lead this transition to preserve cash for hardware certification programs.
- Hybrid:Split architectures separate classified artifact storage from collaborative development pipelines. Federal systems integrators consolidate procurement around these configurations to satisfy NIST SP 800-171 boundary controls while enabling contractor collaboration.
- Dedicated Server:Single-tenant cloud deployments serve healthcare device manufacturers requiring FDA software-as-medical-device traceability without multi-tenant risk exposure.
On-Premises sits at the top of the volume ranking, with Cloud-Based climbing the fastest.
End User Type:
Procurement authority and compliance sophistication vary dramatically across organizational scale, with government buyers imposing the most stringent qualification requirements.
- Enterprise:Fortune 500 manufacturers demand unified toolchain orchestration spanning requirements, design, coding, testing, and maintenance. Automotive OEMs in Germany and Japan are migrating ISO 26262 functional safety standards into vendor selection criteria.
- Government:Defense primes and federal systems integrators in the United States consolidate procurement around cloud-native suites that embed continuous compliance validation. DoD cybersecurity mandates from NIST SP 800-171 disqualify non-compliant vendors from contractor shortlists.
- SMBs:Subscription pricing models are displacing perpetual licenses among mid-tier suppliers seeking operational expenditure flexibility. Cash preservation for hardware certification programs drives this shift.
- Educational Institutions:Research universities with defense research contracts require export-controlled ALM environments for International Traffic in Arms Regulations compliance.
Government captures the largest contract values, with Enterprise expanding most quickly.
Service Type:
Revenue mix is shifting toward recurring service streams as implementation complexity drives demand for specialized expertise.
- Managed Services:Outsourced ALM administration absorbs continuous compliance validation burdens for resource-constrained aerospace suppliers. FAA airworthiness directive updates require dedicated regulatory monitoring.
- Consulting:Safety-critical standards expertise commands compensation premiums as engineers qualified in both DO-178C and modern CI/CD pipelines remain scarce. Implementation timelines stretch eighteen-to-twenty-four months for regulated buyers.
- Licensing:Perpetual license models retain foothold among defense primes with capital expenditure flexibility and long platform lifecycles. Mainframe-integrated estates create switching costs that protect incumbent vendors.
- Technical Support:Tiered support structures align with certification audit schedules, with premium tiers guaranteeing response times synchronized with regulatory submission deadlines.
Licensing remains the revenue foundation, with Managed Services gaining share fastest.
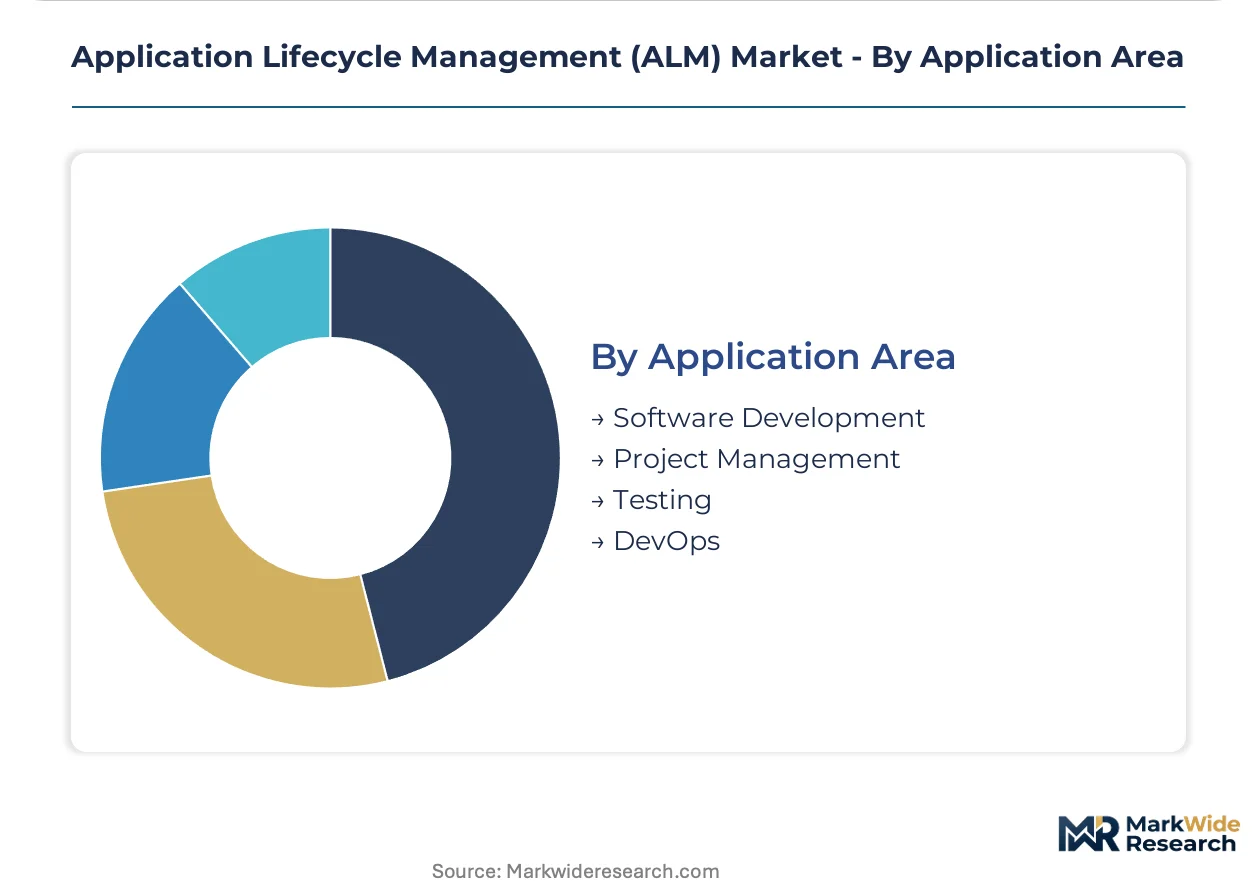
Application Area:
DevOps convergence is expanding ALM addressable scope beyond traditional waterfall governance into continuous integration pipelines.
- DevOps:Continuous integration tooling is absorbing formal governance structures previously reserved for waterfall methodologies. Software bill of materials automation and machine-learning operations governance are merging into unified workflows.
- Software Development:Requirements traceability matrices and automated pipeline validation eliminate defect propagation across development stages. Model-based systems engineering tooling unifies requirements, architecture, and verification artifacts into live digital threads.
- Testing:Automated validation pipelines generate audit-ready documentation for safety-critical industries. FDA software-as-medical-device guidance extends traceability requirements into diagnostic equipment tooling.
- Project Management:Artifact traceability extends into program schedule and resource allocation, compressing systems engineering workforce headcount for major platform developments.
Software Development holds the installed base lead, with DevOps showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping ALM procurement geography as defense contractors migrate compliance workloads toward jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between air-gapped sovereign clouds and multi-tenant SaaS platforms are accelerating vendor selection cycles in lower-friction markets.
United States
Defense primes and federal systems integrators concentrate procurement around NIST SP 800-171 compliant suites, with DoD cybersecurity mandates disqualifying non-qualified vendors from contractor shortlists. FAA airworthiness directives for DO-178C traceability force commercial aerospace suppliers toward automated pipelines. The Washington DC-Baltimore corridor hosts dense systems engineering talent pools serving Northrop Grumman and Lockheed Martin legacy estates.
Germany
Automotive OEMs embed ISO 26262 ASIL-D toolchain evidence into vendor selection criteria, extending ALM scope into functional safety verification. ECHA REACH compliance documentation requirements intersect with software traceability mandates for embedded systems. Stuttgart and Munich anchor tier-one supplier clusters where Siemens AG maintains dominant specification influence through Polarion deployments.
France
EU AI Act conformity assessment frameworks mandate traceability for high-risk AI systems, extending ALM workflows into training data governance. ANSM medical device oversight converges with FDA-recognized quality system requirements for diagnostic equipment exports. The Paris-Saclay cluster concentrates AI safety research contracts restructuring quality management systems for machine-learning component governance.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance burdens for aerospace suppliers serving both EASA and FAA jurisdictions. UK Ministry of Defence procurement specifications increasingly mirror NIST cybersecurity frameworks for contractor qualification. Bristol and Cambridge host avionics engineering centers where MBSE tooling unification is compressing systems engineering headcount for combat aircraft programs.
Japan
METI industrial standards harmonization efforts align JIS software quality frameworks with ISO 26262 and DO-178C for automotive-avionics convergence. PMDA software-as-medical-device guidance extends traceability requirements into diagnostic robotics and digital therapeutics. The Nagoya-Tokyo corridor concentrates automotive embedded systems development where tier-one suppliers pilot unified ALM-MLOps workflows.
Application Lifecycle Management (ALM) Market Vendor Landscape
Strategic acquisitions dominate the current landscape as incumbent enterprise software vendors absorb specialized compliance-tooling providers to anchor defense-aerospace workflows. Market structure concentrates around three tiers: diversified industrial conglomerates with safety-critical credentials, pure-play DevOps platforms extending into governance, and legacy mainframe-integrated estates protected by switching costs. Two archetypes define competitive positioning: compliance-first vendors embedding continuous validation into cloud-native suites, and toolchain consolidators unifying fragmented artifact repositories. M&A activity and hybrid cloud middleware development represent the dominant competitive moves.
Within the compliance-first tier, Siemens AG and IBM Corporation exemplify archetypes anchored by safety-critical certification foundations. Siemens leverages its Polarion acquisition to dominate traceability-mandate workflows in European aerospace and automotive verticals. IBM sustains relevance through DO-178C and ARP4754A tooling for avionics suppliers requiring audit-ready documentation. Broadcom occupies a distinct position via mainframe-integrated ALM suites that dominate legacy defense IT estates at US primes, where air-gapped infrastructure requirements protect incumbent positions.
| Leading Market Players |
|---|
| Broadcom |
| Siemens AG |
| Microsoft Corporation |
| PTC Inc. |
| Perforce Software |
| IBM Corporation |
| SAP SE |
| HP Development Company |
| Atlassian Corporation Plc |
| Others |
Supply Flow & Price Mechanics
Defense contractor consolidation around NIST SP 800-171 compliant suites is compressing vendor selection cycles from eighteen months to under six months, forcing suppliers to absorb certification costs upfront while cloud-native deployment models shift revenue recognition toward recurring streams.
Pricing Analysis
Distributor margins for ALM platforms compress as direct-to-OEM channels capture hyperscale defense prime procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—DO-178C and ISO 26262 qualified toolkits command substantial premiums over baseline DevOps modules. Pricing pressure stems from mid-tier aerospace suppliers converting capital expenditure to operational expenditure through SaaS subscriptions. SMBs exhibit highest price sensitivity, while government buyers prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from defense primes and federal systems integrators, bypassing traditional distribution layers for classified program environments. Software development concentrates in the United States, Germany, and India, with compliance validation and safety-critical certification anchored in the United States and European aerospace clusters. Cloud infrastructure and cybersecurity tooling draw from specialized technology vendors concentrated in the United States and Israel. Single-source vulnerability around FedRAMP-authorized cloud environments creates procurement bottlenecks for defense contractors. Distribution runs through value-added resellers with security clearance credentials for classified artifact handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ALM market functions as a stable compounder, with regulatory mandates for safety-critical software traceability creating durable demand visibility across aerospace, automotive, and healthcare verticals.
For Market Incumbents: Acquire specialized compliance-tooling providers with existing DO-178C or ISO 26262 certification foundations to anchor defense-aerospace workflows. Siemens AG's Polarion integration demonstrates how traceability-mandate expertise creates specification lock-in. Counter pure-play DevOps platforms extending into governance by embedding continuous validation into hybrid cloud architectures that satisfy air-gapped requirements at legacy defense primes. For New Entrants and Emerging Players: Enter via MLOps governance extensions for EU AI Act conformity assessment, where training data lineage traceability lacks established tooling incumbents. Target mid-tier European automotive suppliers seeking ASIL-D qualified toolchain evidence without legacy mainframe integration burdens. Lead with API-first architectures that splice into existing CI/CD pipelines rather than displacing entrenched ALM estates. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-first vendors possessing parallel certification evidence for multiple safety-critical standards. Long-term viability hinges on sustained defense procurement concentration and automotive functional safety migration. Monitor EU AI Act implementation timelines as inflection indicator for machine-learning component governance demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Polarion's integration into Siemens anchors defense-aerospace traceability mandates. |
| Platform Integration | MBSE tooling unification compresses systems engineering headcount for combat aircraft programs. |
| Strategic Partnership | Federal systems integrators consolidate procurement around hybrid cloud middleware developers. |
| Geographic Expansion | ISO 26262 credential extension opens adjacent revenue streams in Stuttgart and Munich automotive clusters. |
| Product Launch | SBOM automation modules merge compliance documentation into continuous integration pipelines. |
Methodological Framework
Bottom-up defense contractor and automotive OEM modeling reconciled against top-down cloud infrastructure and DevOps tooling tracking forms the analytical core of this study. Primary interviews with ALM platform engineering directors, defense procurement officers, automotive functional safety leads, and federal systems integrators were validated against secondary sources including FAA airworthiness directive filings, DoD cybersecurity framework updates, EMA medical device guidance, and SEC 10-K disclosures from diversified industrial software vendors. Triangulation between demand-side procurement patterns and supply-side certification roadmaps ensures segmentation accuracy.
Historical trendline analysis of defense prime ALM expenditure patterns and commercial aerospace software certification timelines informs the projection framework. Segmentation dimensions span deployment architecture, end-user organizational scale, service type mix, and application area complexity, with regional regulatory cluster variations modeled separately. CAGRs were derived from elasticity-adjusted adoption curves across safety-critical verticals, incorporating DevOps convergence rates and cloud migration friction factors specific to regulated buyers.
Inputs from defense contractor procurement databases and automotive OEM supplier qualification records were available through the study window; gaps in classified program ALM expenditure disclosure introduce uncertainty bands around government segment estimates. Forecasts reflect assumptions regarding sustained FAA and DoD mandate enforcement, EU AI Act implementation pacing, and ISO 26262 automotive adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Audit Management Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Cricket Analysis Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Fitness App Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Global Recipe Apps Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Nosql Database Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Payroll and HR Software Market