
 Healthcare Video Conferencing Solutions Market | 2026-2036
Healthcare Video Conferencing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Video Conferencing Solutions Market Intelligence
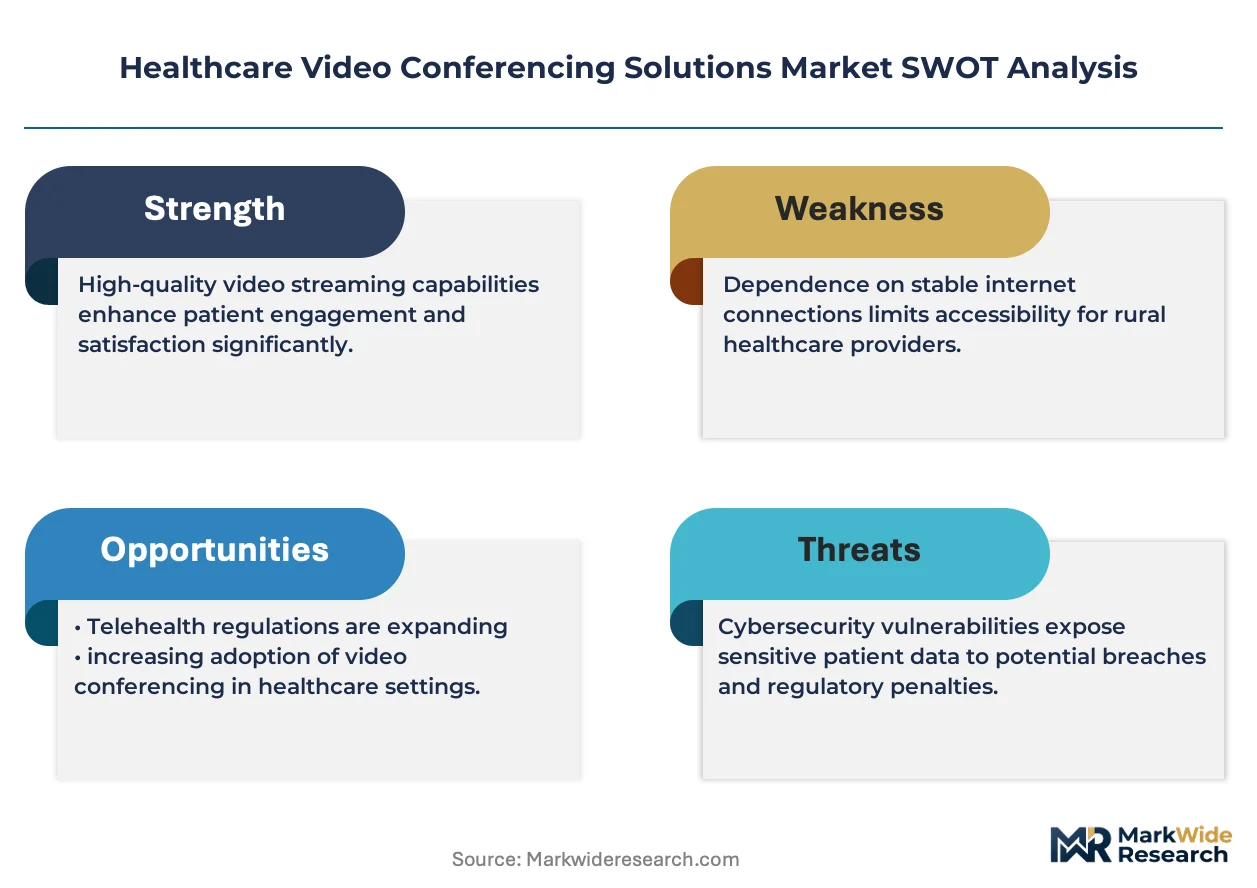
Rural health networks and federally qualified health centers are bifurcating demand away from large academic medical centers as the primary growth vector. Zoom Video Communications leverages its consumer-to-enterprise channel crossover to capture ambulatory clinic expansions. Cisco Systems anchors its position through hardened security architectures that sustain long-term contracts with Veterans Health Administration facilities. Teladoc Health differentiates via vertical integration into care delivery workflows rather than standalone conferencing tools.
Healthcare video conferencing solutions encompass real-time audiovisual communication platforms engineered for clinical environments, typically integrating 256-bit AES encryption, HL7 FHIR interoperability protocols, and sub-150 millisecond latency thresholds to support diagnostic-grade interactions. These systems enable synchronous remote care delivery, specialist access expansion, and multidisciplinary care coordination across distributed provider networks. Software deployments currently command the dominant margin pool as recurring SaaS models displace capital-intensive hardware refresh cycles, while cloud-based architectures represent the fastest-expanding technology dimension due to elastic scalability and reduced IT overhead. Remote consultation applications lead volume adoption, though patient monitoring integrations are deepening as platforms embed biometric data streams from connected devices.
The FDA oversees software-as-a-medical-device classifications for diagnostic video encounters, while HIPAA mandates encryption and access control standards that shape vendor product roadmaps and procurement eligibility. State-level telehealth parity laws and DEA flexibility for controlled substance prescribing via video further fragment compliance requirements across jurisdictions. Stakeholders must monitor evolving reimbursement codes and interstate licensure compacts that determine platform monetization potential and addressable market boundaries.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for HIPAA-compliant platforms while interoperability mandates from the ONC force legacy system overhauls across integrated health networks.
Growth Catalysts
- Federally qualified health centers:Rural health networks in the United States are expanding specialist access through subsidized telehealth infrastructure grants from HRSA.
- HL7 FHIR R4 mandates:The ONC's information blocking rules require standardized data exchange, compelling EHR vendors to embed video APIs into clinical workflows.
- Edge computing deployment:Sub-50 millisecond latency at the network edge enables diagnostic-grade video encounters for stroke assessment and teledermatology.
Market Restraints
- State licensure fragmentation:Interstate medical practice regulations create compliance friction for platforms serving multi-state health systems.
- Specialized engineering talent scarcity:Dual expertise in clinical informatics and real-time video infrastructure commands premium compensation, constraining vendor scaling.
- Hardware refresh cycle compression:Endpoint camera and codec obsolescence accelerates as 4K diagnostic imaging standards displace 1080p configurations.
Strategic Opportunities
- Chronic care management integration:Biometric data streams from connected glucometers and blood pressure cuffs deepen platform stickiness in value-based contracts.
- DEA flexibility for controlled substances:Ryan Haight Act waivers for video prescribing of Schedule II-V medications expand addressable markets for addiction medicine platforms.
- API-first distribution models:White-label video modules embedded into EHR interfaces capture procurement budgets previously allocated to standalone conferencing licenses.
Industry Challenges
- FDA software-as-a-medical-device classification:Diagnostic video encounters trigger 510(k) pathways, extending product launch timelines by 12-18 months.
- Legacy PBX integration complexity:Health systems with Cisco and Avaya voice infrastructure face circuitous migration paths to cloud-native video stacks.
- Biometric data governance:State-level privacy laws in California and Illinois impose consent workflows that complicate automated vital sign capture during video visits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Video Conferencing Solutions Market |
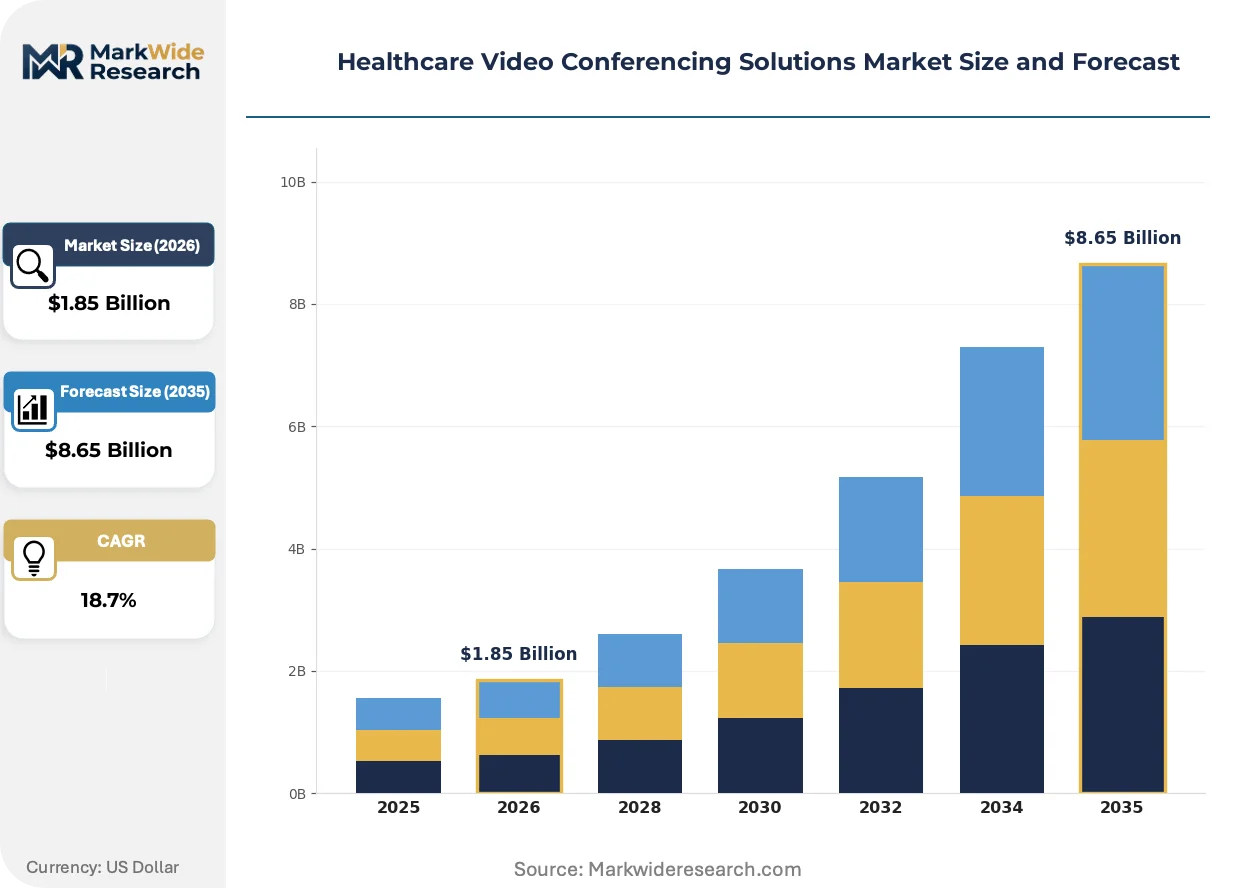
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Systems, Accessories End User: Hospitals, Clinics, Telehealth Providers, Homecare Services Technology: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Applications Application: Remote Consultation, Patient Monitoring, Staff Training, Emergency Services |
| Companies Covered | Zoom Video Communications, Cisco Systems, Teladoc Health, Doxy.me, Amwell, Caregility, Pexip, Vidyo, Logitech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Video Conferencing Solutions Market Strategic Shifts & Innovations
Real-time video infrastructure is fragmenting into composable microservices while regulatory pressure forces security architecture redesigns and procurement patterns favor outcome-contingent vendor relationships.
Containerized video infrastructure is decomposing monolithic conferencing stacks into Kubernetes-orchestrated components. Health systems with dedicated DevOps functions are adopting this modular approach to customize latency, encryption, and storage policies per clinical use case. The shift is compressing vendor lock-in durations and enabling multi-cloud failover configurations for critical care consultations.
The EU AI Act's risk classification framework for biometric identification is forcing vendors to segregate facial analysis features from core video transport. European health systems must document conformity assessments for emotion detection or gaze-tracking algorithms embedded in patient monitoring applications. German university hospitals are piloting anonymized video routing to preempt GDPR enforcement actions.
Subscription fatigue among ambulatory clinic administrators is accelerating preference for consumption-based pricing tied to completed encounters rather than licensed seats. This model disrupts traditional enterprise SaaS procurement and concentrates vendor risk on patient volume volatility. The pattern is most visible in United States multi-specialty groups with seasonal demand fluctuations.
Healthcare Video Conferencing Solutions Market Segmentation
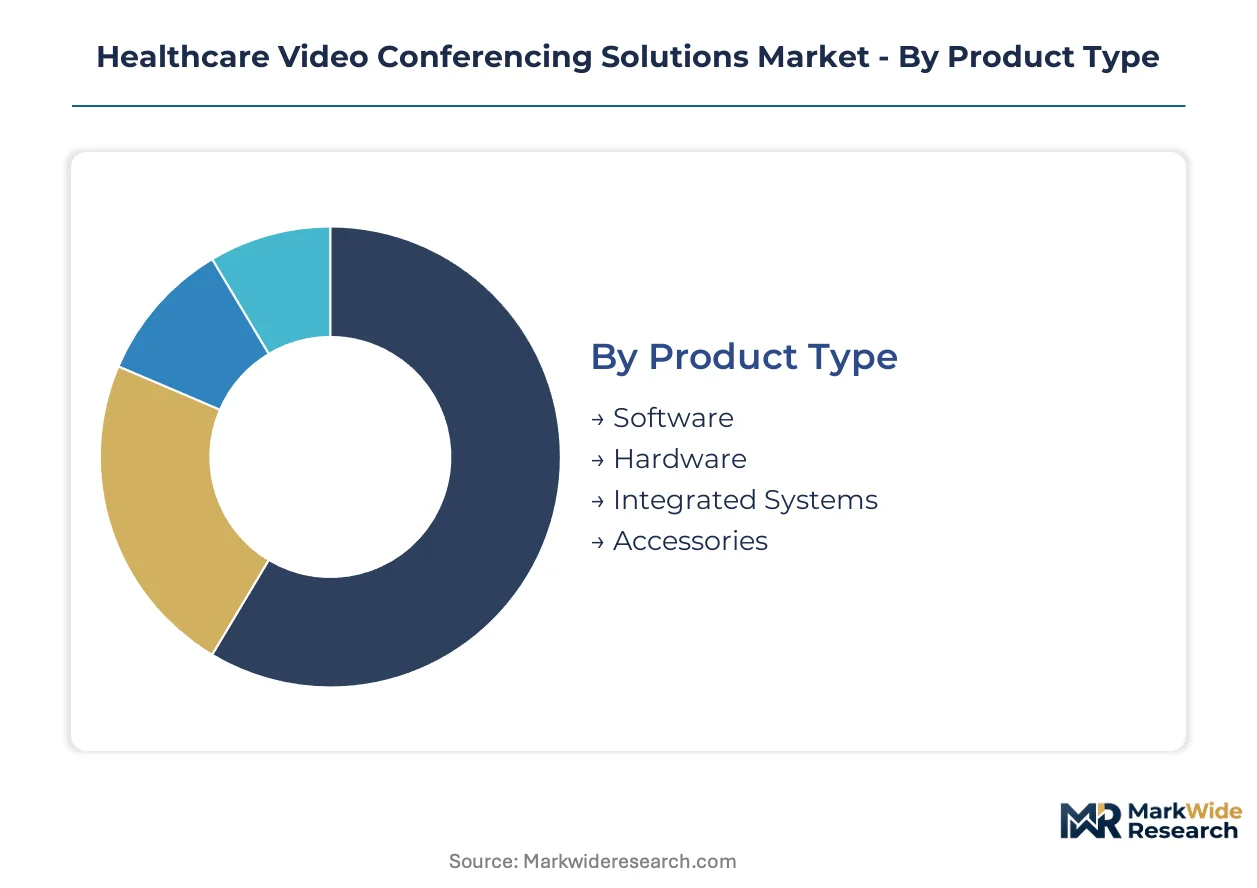
Segmentation in healthcare video conferencing reveals how procurement budgets flow through distinct channels. Software subscriptions dominate recurring revenue streams while hardware refresh cycles concentrate capital expenditure. Understanding these pathways clarifies where vendors must embed their offerings to capture enterprise health system contracts.
Product Type:
Channel mix varies sharply across product categories. Software licenses flow through SaaS marketplaces and direct vendor relationships. Hardware moves through medical device distributors and systems integrators. Integrated systems and accessories follow divergent procurement paths tied to capital budgets versus operational spending.
- Software:Cloud-native platforms with 256-bit AES encryption and HL7 FHIR APIs command premium recurring margins. Demand concentrates among United States ambulatory clinic networks modernizing EHR-embedded workflows under ONC interoperability mandates. SaaS models displace perpetual licenses as health systems prioritize elastic scalability over capital deployment.
- Hardware:Diagnostic-grade endpoints with 4K imaging sensors and sub-150 millisecond latency thresholds anchor Veterans Health Administration deployments. Cisco Systems sustains long-term contracts through hardened security architectures. Refresh cycles compress as 1080p configurations obsolesce rapidly.
- Integrated Systems:Bundled software-hardware packages reduce IT integration burden for rural health networks with limited technical staff.
- Accessories:Peripheral cameras, microphones, and mounting hardware represent low-margin attach sales to primary platform vendors.
By volume, Software leads. By growth pace, Integrated Systems is climbing the fastest as federally qualified health centers seek turnkey solutions.
End User:
Customer type determines pricing tolerance and contract structure. Enterprise health systems negotiate multi-year agreements with outcome contingencies. Smaller providers accept standardized terms with faster deployment timelines.
- Hospitals:Academic medical centers demand diagnostic-grade latency for stroke assessment and surgical consultations. These institutions drive enterprise-scale deployments with rigorous security audits.
- Clinics:Multi-specialty groups in United States metropolitan corridors favor consumption-based pricing tied to completed encounters rather than licensed seats. Zoom Video Communications captures this segment through consumer-to-enterprise channel crossover.
- Telehealth Providers:Pure-play virtual care platforms require API-first architectures for white-label embedding into payer portals.
- Homecare Services:Post-acute and hospice providers integrate biometric data streams from connected devices to deepen platform stickiness.
Telehealth Providers generate the highest contract velocity. Homecare Services shows the steepest expansion trajectory as value-based reimbursement extends into post-acute settings.
Technology:
Deployment architecture shapes total cost of ownership and compliance posture. Cloud-native stacks reduce IT overhead but introduce data sovereignty considerations. On-premise installations satisfy stringent security requirements at higher capital cost.
- Cloud-Based:Kubernetes-orchestrated microservices enable elastic scaling for seasonal demand fluctuations. United States health systems with dedicated DevOps functions adopt modular configurations to customize encryption and storage policies per clinical use case.
- On-Premise:Air-gapped installations serve Department of Defense medical facilities and intelligence community health clinics with classified data requirements.
- Hybrid Solutions:Split architectures route routine traffic through cloud infrastructure while retaining sensitive consultations on local infrastructure.
- Mobile Applications:Native iOS and Android clients with offline synchronization support home health aides in connectivity-constrained environments.
Cloud-Based deployments dominate new installations. Hybrid Solutions is gaining share fastest as organizations balance scalability against control.
Application:
Use case specificity determines feature prioritization and integration depth. Diagnostic encounters demand sub-50 millisecond edge computing latency. Administrative applications tolerate higher latency in exchange for broader accessibility.
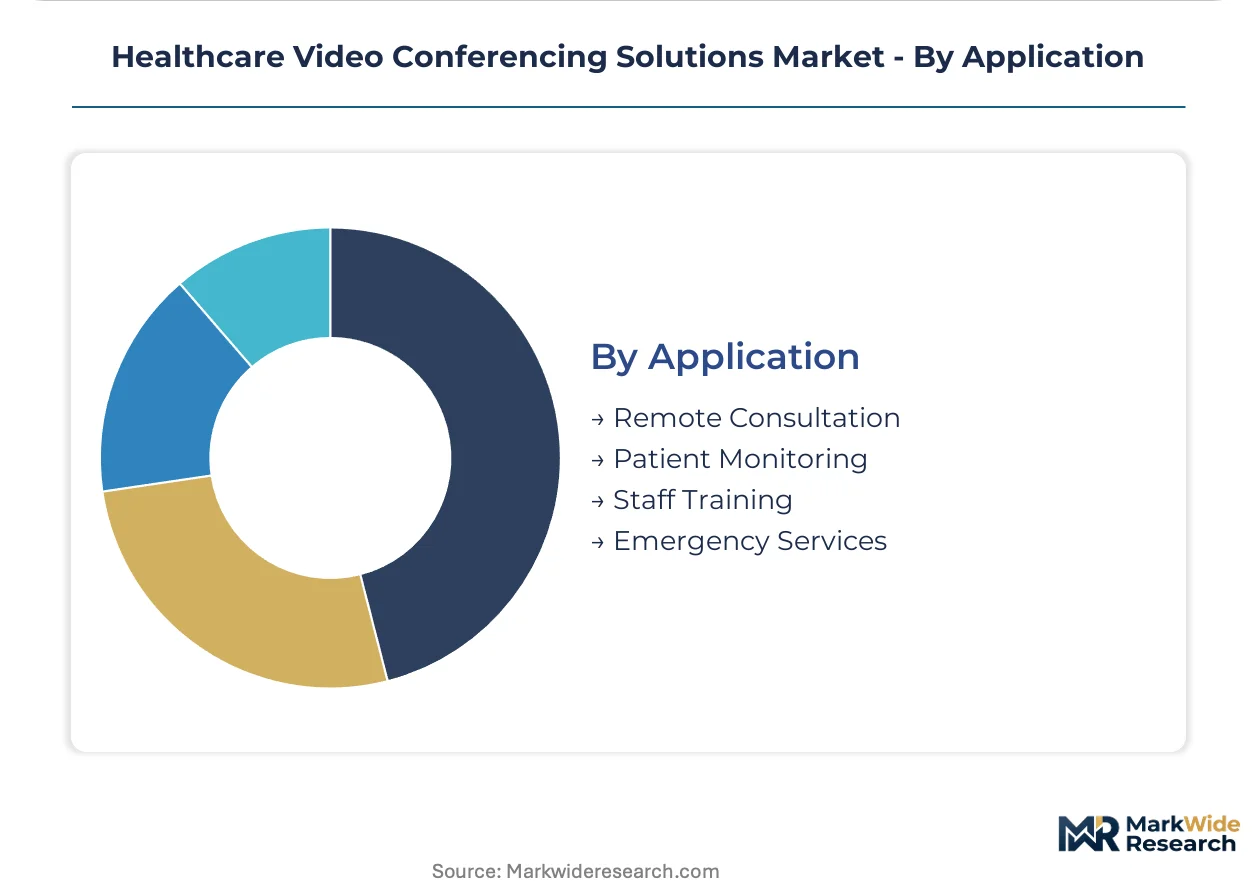
- Remote Consultation:Synchronous audiovisual encounters with specialist access expansion represent the volume adoption leader. Federally qualified health centers leverage HRSA infrastructure grants to deploy these capabilities.
- Patient Monitoring:Continuous biometric data streams from connected glucometers and blood pressure cuffs embed video platforms into chronic care management workflows. Teladoc Health differentiates through care delivery integration rather than standalone conferencing.
- Staff Training:Asynchronous recorded sessions and live procedural demonstrations reduce travel costs for dispersed clinical workforces.
- Emergency Services:Pre-hospital stroke assessment and trauma consultation require guaranteed bandwidth prioritization through network slicing.
Remote Consultation leads by encounter volume. Patient Monitoring is expanding most quickly as value-based contracts incentivize longitudinal engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment concentrates heavily in the United States, where federal telehealth subsidies and interoperability mandates generate outsized procurement volumes. Germany and the United Kingdom follow with regulatory-driven modernization programs, while Japan and Australia represent mature Asia-Pacific markets with distinct compliance frameworks shaping vendor entry strategies.
United States
Rural health networks and federally qualified health centers drive demand through HRSA infrastructure grants that subsidize HIPAA-compliant platform deployment. FDA oversight of software-as-a-medical-device classifications extends product launch timelines for diagnostic video applications. The Veterans Health Administration anchors enterprise-scale procurement in the Washington DC corridor and major metropolitan hospital systems.
Germany
University hospitals pilot anonymized video routing to preempt GDPR enforcement actions under the EU AI Act's biometric identification risk framework. The country's national digital health regulator enforces conformity assessments for emotion detection algorithms embedded in patient monitoring applications. Berlin and Munich clusters concentrate vendor development activity for edge computing latency optimization.
United Kingdom
NHS England's digital transformation programs mandate HL7 FHIR interoperability for specialist access expansion in rural and coastal communities. The Medicines and Healthcare products Regulatory Agency oversees diagnostic-grade video encounter classifications that align with FDA pathways. London's health tech corridor hosts concentrated vendor partnerships with integrated care systems.
Japan
Metropolitan hospital networks adopt sub-50 millisecond edge computing configurations for stroke assessment and teledermatology consultations. The Pharmaceuticals and Medical Devices Agency classifies diagnostic video platforms under medical device regulations that require local clinical validation. Tokyo and Osaka clusters concentrate telehealth provider headquarters and EHR integration partnerships.
Australia
Post-acute and homecare providers integrate biometric data streams from connected devices under value-based reimbursement expansion programs. The Therapeutic Goods Administration regulates software-based medical devices with risk classification frameworks similar to FDA and EMA approaches. Sydney and Melbourne health tech corridors concentrate platform development for aged care and chronic disease management applications.
Healthcare Video Conferencing Solutions Market Key Industry Players
Concentration sits with diversified technology conglomerates and pure-play telehealth platforms that anchor procurement decisions across distinct customer tiers. The market structure exhibits moderate consolidation at the enterprise level alongside fragmentation in specialized clinical applications. Three archetypes dominate: consumer-to-enterprise crossover platforms, hardened security infrastructure providers, and vertically integrated care delivery systems. Competitive moves center on API-first distribution models and outcome-contingent pricing structures that displace traditional seat-based licensing.
Within the diversified technology tier, Zoom Video Communications and Cisco Systems occupy positions that exemplify contrasting security and accessibility trade-offs. Teladoc Health anchors the care delivery integration archetype through workflow embedding rather than standalone conferencing tools. These three companies represent the dominant strategic vectors that shape procurement patterns across United States health systems and influence compliance roadmap priorities for mid-tier competitors.
| Leading Market Players |
|---|
| Zoom Video Communications |
| Cisco Systems |
| Teladoc Health |
| Doxy.me |
| Amwell |
| Caregility |
| Pexip |
| Vidyo |
| Logitech |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day procurement cycles for HIPAA-compliant video infrastructure compress vendor pricing power while cloud-native deployment models shift cost structures from capital expenditure to operational spending. Federally qualified health centers with constrained budgets drive aggregate demand toward consumption-based models that erode traditional enterprise seat-licensing premiums.
Pricing Analysis
HIPAA encryption mandates dictate the pricing tier structure across healthcare video conferencing deployments. Three-tier pricing structure across premium, standard, and economy levels separates diagnostic-grade platforms with FDA 510(k) clearance from administrative conferencing tools and basic telehealth modules. Price differentiation rests on certification depth and latency performance guarantees. Cost compression in the standard tier intensifies because Zoom Video Communications and Cisco Systems compete aggressively for ambulatory clinic contracts. Federally qualified health centers exhibit the highest price sensitivity, while Veterans Health Administration facilities tolerate premium pricing for air-gapped security architectures.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for video encoding chipsets that enable sub-50 millisecond latency thresholds. The hardware tier draws from Chinese camera sensor manufacturers and Mexican assembly operations for endpoint devices. Supply chain risk centers on single-source vulnerability for specialized encryption processors subject to export control restrictions. Distribution runs through medical device distributors and systems integrators that bundle software-hardware packages for rural health networks with limited technical staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among United States integrated health systems consolidating vendor relationships under enterprise-wide telehealth contracts, compressing margins for standalone platform providers.
For Market Incumbents: Consolidate API-first distribution partnerships with Epic Systems and Cerner to embed video modules directly into EHR workflows before interoperability mandates harden procurement specifications. Defensive positioning requires backward integration into edge computing infrastructure to guarantee latency performance for diagnostic encounters. Threat substitution emerges from Amazon Web Services and Microsoft Azure launching healthcare-compliant video services as loss-leader cloud attachments. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for software-as-a-medical-device classifications create entry ramps for diagnostic video platforms targeting teledermatology and stroke assessment. White-space concentration sits in homecare services integrating biometric data streams from connected glucometers and blood pressure cuffs. Go-to-market execution should target post-acute providers under value-based reimbursement contracts with consumption-based pricing tied to patient engagement metrics. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates divesting non-core healthcare video assets amid portfolio rationalization. Long-term viability favors vendors with care delivery integration rather than standalone conferencing tools, as Teladoc Health's workflow embedding demonstrates sustainable competitive positioning. Monitor DEA regulatory shifts on Ryan Haight Act waivers as inflection indicators for addiction medicine platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR API Integration | ONC interoperability mandates force EHR vendors to embed video modules into clinical workflows. |
| Edge Computing Deployment | Sub-50 millisecond latency enables diagnostic-grade stroke assessment and teledermatology consultations. |
| FDA 510(k) Clearance Pathway | Software-as-a-medical-device classification extends product launch timelines for diagnostic video platforms. |
| Hospital System Partnership | Veterans Health Administration contracts anchor enterprise-scale procurement with multi-year security requirements. |
| Reimbursement Strategy | CMS telehealth parity codes determine platform monetization potential across state Medicaid programs. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with telehealth platform executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, ONC interoperability certification databases, CMS Medicare telehealth utilization data, and HRSA infrastructure grant disbursements. Bottom-up encounter volume modeling triangulated against top-down health system IT budget allocations.
Across the projection horizon, the analytical framework segmented by deployment architecture, end-user scale, application specificity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating reimbursement code expansion and interstate licensure compact ratification. Forecast inputs included edge computing infrastructure capex trajectories and EHR vendor API roadmap disclosures.
Underlying assumptions cover sustained HRSA funding for rural telehealth infrastructure and stable DEA flexibility for controlled substance video prescribing, with deviation risk concentrated in state-level privacy law fragmentation and FDA enforcement intensity on diagnostic video classifications. Recalibration cycles align with material shifts in ONC information blocking rule implementation and Medicare telehealth reimbursement parity legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Data Broker Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Turkey ICT Market