
 Farm Management Software Market | 2026-2036
Farm Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Management Software Market Intelligence
The EU Green Deal is rebalancing the cost-of-entry calculus for farm management software vendors serving European agribusinesses. Trimble Ag Software leverages its precision agriculture heritage to sustain channel dominance across North American row-crop operations. Climate Corporation anchors its position through proprietary weather and soil data layers that differentiate its subscription model from commodity platform providers.
Farm management software denotes integrated digital platforms that collect, process, and visualize agronomic, operational, and financial data through cloud architectures, IoT sensor integrations, and mobile interfaces to optimize decision-making across the crop and livestock production cycle. Cloud-based deployment leads the market as connectivity infrastructure improves across rural geographies, while crop monitoring solutions capture disproportionate R&D investment due to their direct linkage to yield optimization outcomes. Smallholders represent the fastest-growing end-user category as subsidized mobile-based tools lower adoption barriers, though agribusinesses still command the deepest per-seat revenue pools.
The EPA enforces water quality reporting that shapes irrigation management module requirements, while the EU AI Act imposes algorithmic transparency obligations on automated harvest forecasting tools. The USDA distributes conservation incentives that require documented farm planning, directly stimulating software procurement among compliance-oriented operators. Stakeholders must weigh whether to build predictive analytics capabilities in-house or partner with specialized AI vendors as regulatory scrutiny of automated agricultural recommendations intensifies.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for farm management platforms while EU regulatory mandates force compliance module standardization across vendor portfolios.
Growth Catalysts
- EU Green Deal reporting mandates:Environmental disclosure requirements for agricultural operators create mandatory software procurement triggers across European member states.
- USDA conservation incentives:Documented farm planning requirements under conservation programs directly stimulate platform adoption among compliance-oriented growers.
- IoT sensor proliferation:Soil moisture and weather station networks generate data volumes that demand centralized management platforms for actionable agronomic insights.
Market Restraints
- Rural connectivity gaps:Broadband infrastructure deficits in agricultural regions limit real-time cloud synchronization capabilities for field-based applications.
- Data interoperability barriers:Proprietary data formats across equipment manufacturers create integration friction that inflates total cost of ownership.
- Smallholder price sensitivity:Per-acre economics for operations under fifty hectares compress willingness-to-pay for subscription-based software tiers.
Strategic Opportunities
- India smallholder penetration:Subsidized mobile-first tools targeting the country's fragmented agricultural base represent substantial untapped addressable demand.
- Carbon credit verification modules:Emerging soil carbon sequestration protocols create new revenue streams for platforms that integrate measurement and reporting functionality.
- Livestock-digital convergence:Integration of herd management, feed optimization, and veterinary records into unified platforms addresses underpenetrated animal agriculture segments.
Industry Challenges
- Agronomic data science talent scarcity:Shortage of professionals combining crop science expertise with machine learning implementation creates hiring bottlenecks for platform vendors.
- Legacy equipment integration complexity:Retrofitting connectivity to decades-old machinery requires custom hardware development that strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Management Software Market |
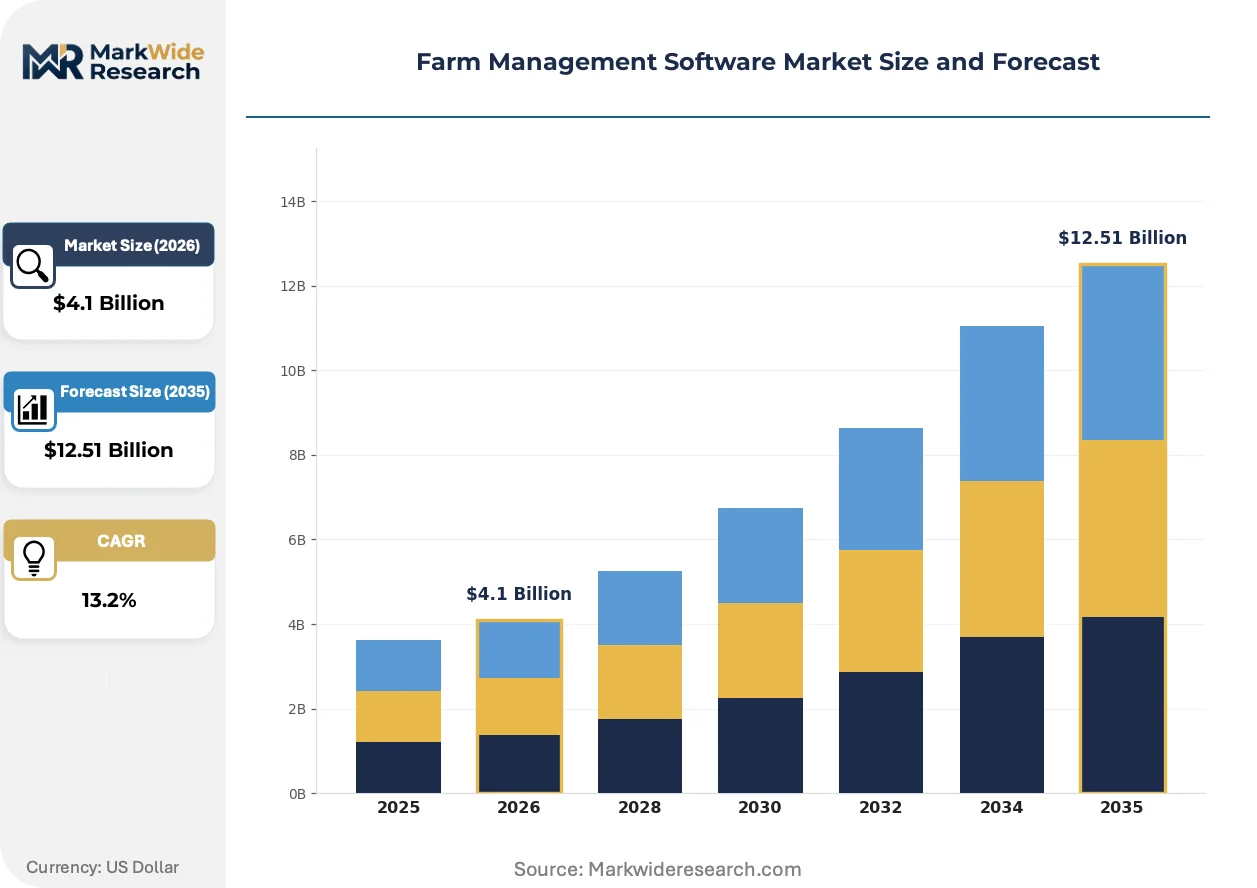
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $12.51 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, Web-Based, Mobile-Based, On-Premise Solution Offering: Crop Monitoring, Livestock Management, Supply Chain Management, Finance Management, Equipment Tracking Application: Precision Farming, Farm Planning, Irrigation Management, Harvest Forecasting, Soil Analysis End User: Smallholders, Agribusinesses, Government Agencies, Cooperatives, Agricultural Consultants |
| Companies Covered | xFarm, Cropio, Trimble Ag Software, FarmBrite, Farmers Business Network, Climate Corporation, FarmLogs, AGRONET, Agrivi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Management Software Market Strategic Shifts & Innovations
Artificial intelligence is compressing decision cycles from seasonal to real-time while regulatory mandates force transparency into algorithmic recommendations.
Computer vision-based crop health monitoring is overtaking manual scouting methods for pest and disease detection. Large-scale row-crop operations in the United States and Brazil are deploying drone-mounted multispectral sensors at accelerating rates. This capability compression is reducing agronomist labor requirements while expanding the addressable market for automated intervention recommendations.
The EU AI Act imposes algorithmic transparency obligations on automated harvest forecasting and input recommendation tools. Vendors must now document training data provenance and decision logic for tools classified as high-risk AI systems. European agribusinesses are responding by demanding audit trails and explainability features that exceed current North American platform specifications.
Subscription unbundling is fragmenting traditional all-in-one platform offerings into specialized modules. Mid-scale operators in Australia and Canada are selectively procuring crop monitoring, financial management, and compliance tools from different vendors rather than accepting bundled suites. This procurement pattern shift rewards vendors with superior API architectures and penalizes closed-ecosystem approaches.
Farm Management Software Market Segmentation
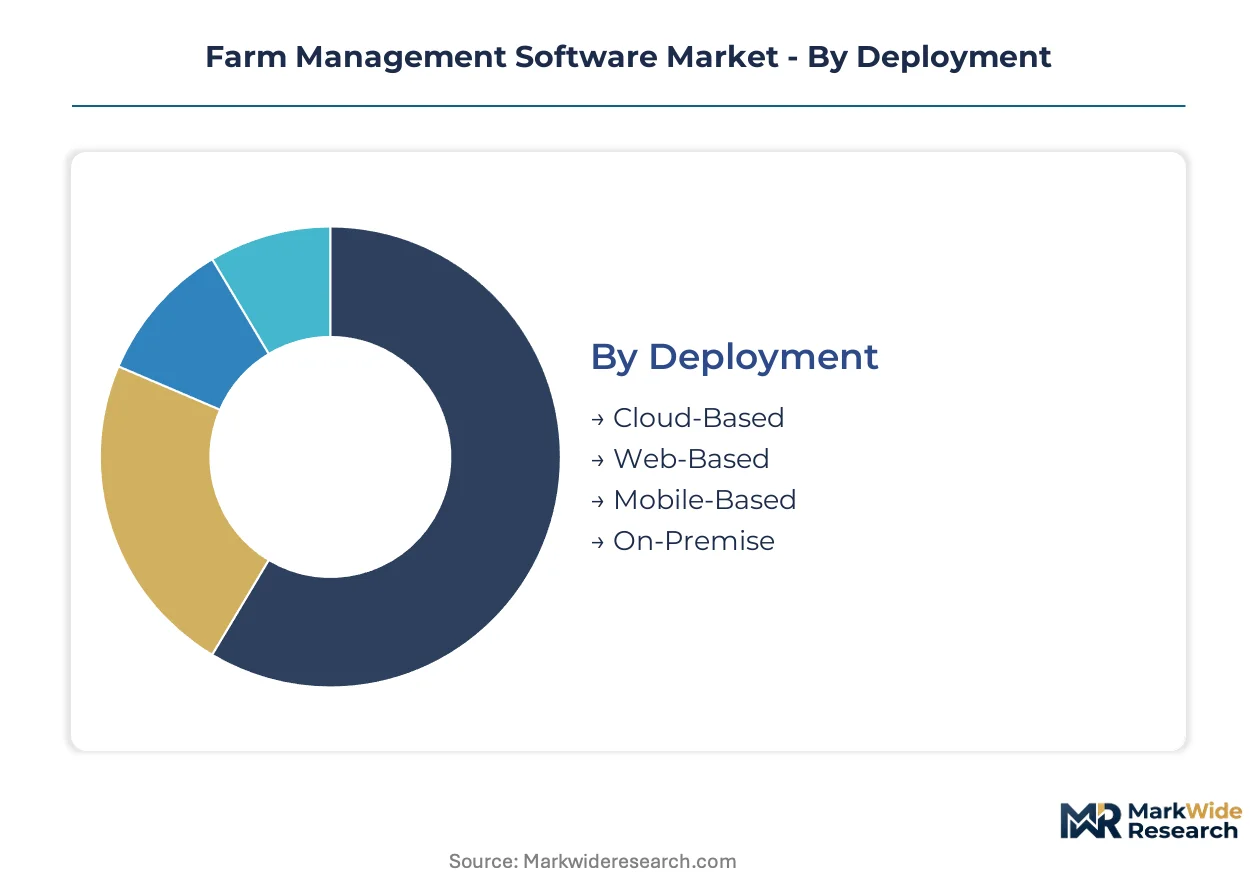
Deployment architecture determines total cost of ownership and synchronization capabilities for farm management platforms. Solution specialization shapes vendor competitive moats and recurring revenue durability across agronomic workflows.
Deployment:
Cloud infrastructure concentration among hyperscale providers compresses hosting economics for software vendors serving dispersed agricultural operations.
- Cloud-Based:Centralized server architectures enable real-time data synchronization across multiple field locations and equipment fleets. Large-scale row-crop operations in the United States and Brazil drive enterprise procurement of cloud-native platforms for their distributed acreage portfolios.
- Mobile-Based:Smartphone-optimized interfaces leverage cellular connectivity to deliver field-level decision support without dedicated hardware investments. India's fragmented smallholder base absorbs the bulk of mobile-first deployments as subsidized data plans lower adoption barriers for sub-fifty-hectare operations.
- Web-Based:Browser-accessible dashboards serve administrative users requiring complex financial and compliance reporting without native app dependencies.
- On-Premise:Local server installations address operators in regions with unreliable broadband infrastructure or stringent data sovereignty requirements.
Cloud-Based deployments absorb the bulk of installed capacity; Mobile-Based is expanding most quickly.
Solution Offering:
Module specialization creates pricing tier differentiation and integration complexity trade-offs for multi-functional platform procurement.
- Crop Monitoring:Satellite imagery and sensor fusion platforms track vegetative health indices, pest pressure, and nutrient deficiencies across growing seasons. North American commodity crop producers concentrate demand for these tools due to their direct linkage to yield optimization and input cost reduction.
- Livestock Management:Herd tracking, feed optimization, and veterinary record systems address underpenetrated animal agriculture segments with distinct workflow requirements from crop operations.
- Supply Chain Management:Traceability and logistics coordination modules enable compliance with EU Green Deal documentation requirements for agricultural product provenance.
- Finance Management:Integrated accounting, crop insurance, and loan servicing tools streamline working capital management for capital-intensive farming operations.
- Equipment Tracking:Fleet utilization and maintenance scheduling systems reduce machinery downtime across large-scale mechanized operations.
Crop Monitoring captures the deepest per-seat revenue pools; Livestock Management demonstrates the steepest expansion trajectory as animal agriculture digitization accelerates.
Application:
Use-case specificity determines sensor integration requirements and algorithmic model training data needs for agronomic decision support.
- Precision Farming:Variable-rate input application and automated steering systems optimize seed, fertilizer, and chemical placement at sub-field resolution. Commercial farms in the United States and Germany anchor demand for these high-investment precision agriculture workflows.
- Irrigation Management:Soil moisture monitoring and evapotranspiration modeling tools enable water stress mitigation under EPA water quality reporting constraints.
- Farm Planning:Seasonal crop rotation and input budgeting modules satisfy USDA conservation incentive documentation requirements for compliance-oriented growers.
- Harvest Forecasting:Yield prediction algorithms face EU AI Act transparency obligations for training data provenance and decision logic documentation.
- Soil Analysis:Nutrient mapping and carbon sequestration measurement tools support emerging carbon credit verification protocols.
Precision Farming commands the largest installed base; Soil Analysis is climbing the fastest as carbon market participation expands.
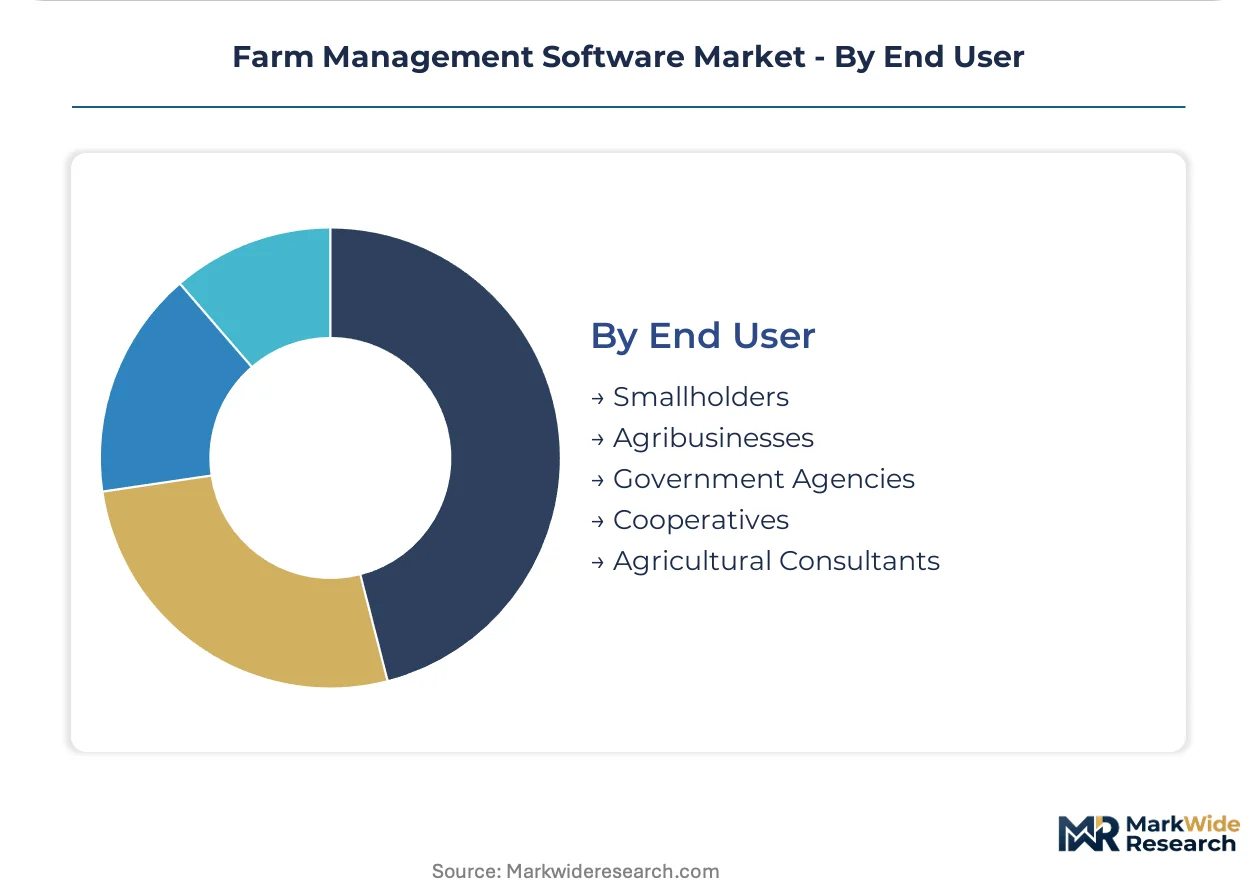
End User:
Customer scale and sophistication stratify pricing tolerance and feature complexity requirements across platform tiers.
- Agribusinesses:Enterprise-scale operators with thousand-plus hectare portfolios demand multi-user collaboration, ERP integration, and dedicated account management. These organizations generate the highest lifetime value through deep module penetration and multi-year contract structures.
- Smallholders:Sub-fifty-hectare operations prioritize affordability and mobile accessibility over advanced analytics capabilities. India's agricultural base represents the largest addressable population for subsidized entry-tier tools.
- Cooperatives:Member-owned aggregation entities procure shared platforms to standardize record-keeping across diverse producer operations.
- Agricultural Consultants:Independent agronomists require multi-tenant architectures to manage client portfolios with segregated data access.
- Government Agencies:Extension services and regulatory bodies deploy platforms for program administration and compliance monitoring.
Agribusinesses dominate current revenue concentration; Smallholders are gaining share fastest as mobile penetration erodes historical adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for agricultural technology in Karnataka and Telangana concentrate software development capacity. These zones channel public-private partnerships toward precision farming platforms serving domestic smallholders and export markets.
United States
Large-scale commercial farms in Iowa and Illinois drive enterprise software deployments through thousand-plus-hectare operations requiring multi-user collaboration tools. The USDA distributes conservation incentives mandating documented farm planning, directly stimulating platform procurement among compliance-oriented growers. The Corn Belt corridor anchors North American demand for cloud-native crop monitoring and variable-rate input applications.
Germany
Commercial farms in Lower Saxony and Bavaria anchor European demand for precision agriculture workflows integrating ERP systems with field-level sensors. The EU Green Deal imposes environmental reporting obligations that force compliance module standardization across vendor portfolios. The Munich-Stuttgart industrial corridor hosts development clusters for algorithmic transparency tools addressing EU AI Act requirements.
Brazil
Large-scale soybean and sugarcane operations in Mato Grosso and São Paulo states absorb mobile-first platforms for distributed acreage management. Federal agricultural credit programs require documented production planning, creating procurement triggers for farm management software among subsidized operators. The Campinas technology cluster concentrates localization development for Portuguese-language agronomic decision support.
India
Subsidized mobile-based tools penetrate Maharashtra and Gujarat's fragmented smallholder base as subsidized data plans erode historical adoption barriers. The PLI scheme for agricultural technology channels public investment toward domestic software development capacity. The Hyderabad-Bangalore corridor anchors R&D centers for low-bandwidth-optimized platforms serving sub-fifty-hectare operations.
Australia
Mid-scale mixed farming operations in New South Wales and Victoria selectively procure unbundled modules rather than bundled suites. The country's national agricultural regulator enforces traceability documentation requirements that stimulate supply chain management platform adoption. The Wagga Wagga-Griffith corridor concentrates deployment of irrigation management tools under water quality monitoring obligations.
Farm Management Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base stratifies between precision agriculture heritage players, weather data aggregators, and mobile-first platform developers. Three archetypes dominate: equipment-integrated incumbents leveraging manufacturer relationships, cloud-native challengers unbundling functionality into specialized modules, and regional specialists optimizing for local regulatory and linguistic requirements. Competitive moves concentrate on API architecture investments enabling interoperability and carbon credit verification module development.
Within the precision agriculture tier, Trimble Ag Software and Climate Corporation exemplify divergent defensive strategies. Trimble leverages its positioning across North American row-crop operations through channel relationships with equipment dealers. Climate Corporation anchors its model through proprietary data layers differentiating subscription offerings from commodity platform providers. Among mobile-first specialists, xFarm occupies a position representing European smallholder penetration strategies.
| Leading Market Players |
|---|
| xFarm |
| Cropio |
| Trimble Ag Software |
| FarmBrite |
| Farmers Business Network |
| Climate Corporation |
| FarmLogs |
| AGRONET |
| Agrivi |
| Others |
Cost & Logistics Intelligence
Premium-mid-economy pricing differentiation separates enterprise cloud deployments from subsidized mobile-first tools across deployment tiers, with supply chain configurations tracking this bifurcation through hyperscale infrastructure concentration versus low-bandwidth optimization for emerging markets. The divergence concentrates vendor R&D allocation between API-rich modular architectures and stripped-down cellular interfaces.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement decisions, with premium tiers commanding higher rates for real-time synchronization capabilities and immediate implementation support. Subscription models stratify across premium, standard, and economy levels based on module depth and integration complexity. Price differentiation stems from ERP integration requirements and after-sales service bundling. Cost compression in the economy tier intensifies because subsidized smallholder tools compress willingness-to-pay. Smallholders demonstrate acute price sensitivity; agribusinesses exhibit the least.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure providers concentrated in the United States, Ireland, and Singapore, where server capacity constraints prop pricing for real-time agricultural data processing. Software development draws from Indian engineering talent pools, U.S.-based agronomic data science expertise, and European regulatory compliance specialists. Supply chain risk centers on broadband infrastructure deficits limiting last-mile connectivity for field-based applications. Distribution runs through equipment dealer networks in North America, mobile carrier partnerships in India, and direct SaaS sales in Australia and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through agronomic data science talent scarcity, where the bottleneck in professionals combining crop science with machine learning implementation props pricing for advanced analytics modules.
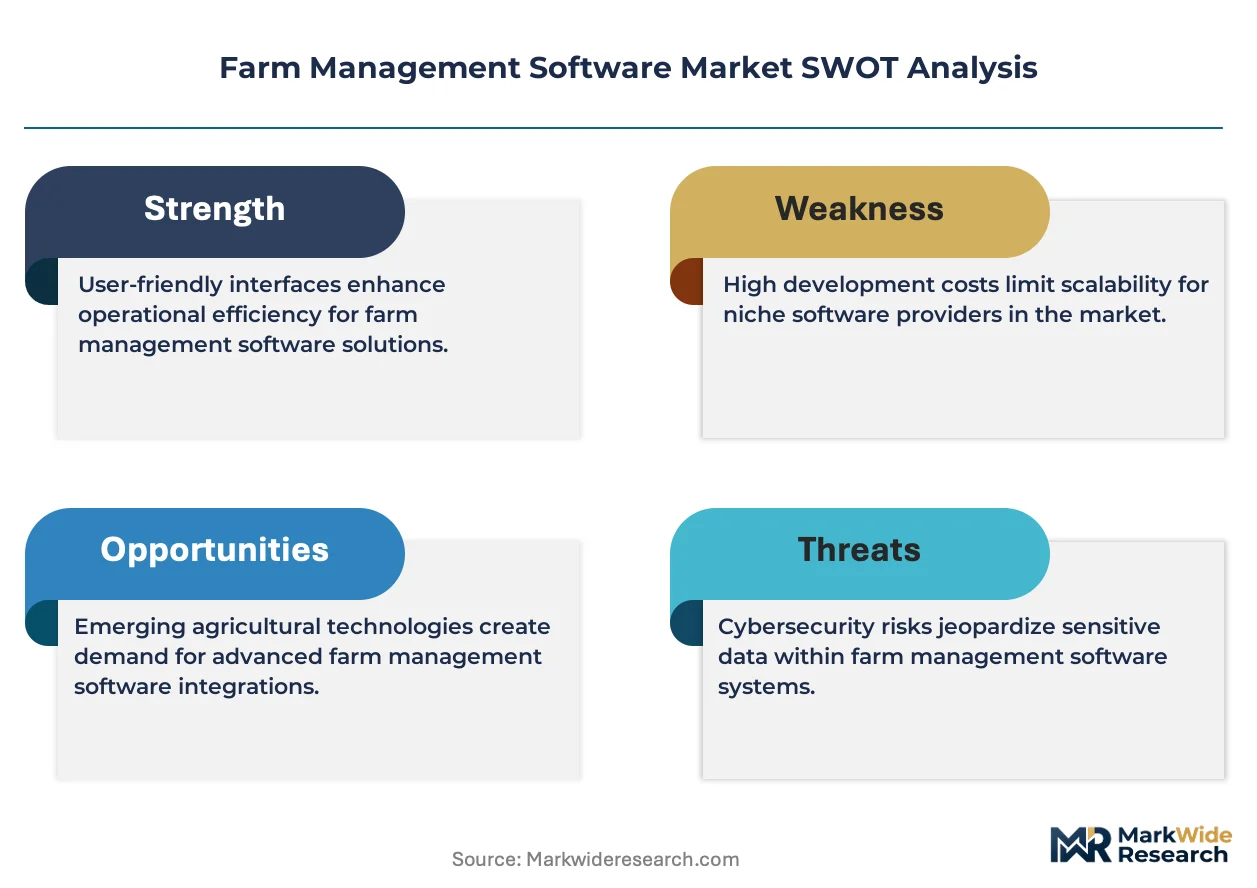
For Market Incumbents: Hedge against API-first challengers by accelerating carbon credit verification module development before soil sequestration protocols mature. Acquire specialized livestock management developers to address underpenetrated animal agriculture segments. Channel control through equipment dealer relationships remains the priority lever for North American row-crop dominance. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for algorithmic transparency tools that exceed current North American platform specifications. White-space targets include mid-scale Australian operators selectively procuring unbundled modules and Indian smallholders absorbing subsidized mobile-first deployments. A regulatory compliance-first go-to-market angle penetrates European agribusinesses facing mandatory environmental disclosure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with mobile-first platform developers given India's PLI scheme for agricultural technology channeling public investment toward domestic capacity. Long-term viability favors vendors with demonstrated API architectures enabling interoperability across fragmented procurement patterns. Watch carbon market participation expansion as the signal indicating inflection toward soil analysis module demand.| Strategic Initiative | Industry Significance |
|---|---|
| API Architecture Investment | Enables module unbundling for Australian and Canadian selective procurement patterns. |
| Carbon Credit Verification Module Launch | Captures emerging soil sequestration protocol revenue streams before standardization. |
| Livestock-Digital Convergence Platform | Addresses underpenetrated herd management and feed optimization segments. |
| EU AI Act Compliance Certification | Unlocks European agribusiness procurement requiring algorithmic audit trails. |
| Low-Bandwidth Platform Localization | Penetrates India's sub-fifty-hectare operations through subsidized data plans. |
Research Approach
Document review covered regulatory filings from the EPA and USDA, EU Green Deal implementation guidance, and EU AI Act technical standards, complemented by interviews with platform engineering leads at cloud-native vendors, agronomic data scientists at precision agriculture specialists, and procurement officers at large-scale row-crop operations. Secondary validation drew from SEC filings of publicly traded agribusinesses, hyperscaler capex disclosures, and agricultural extension service program documentation. Bottom-up deployment modeling and top-down regulatory impact assessment were triangulated against primary field intelligence.
Historical adoption curves were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include deployment architecture, solution specialization, application workflow, and end-user scale stratification. CAGRs were derived from curve-fitting approaches calibrated to documented procurement triggers and technology diffusion patterns. Forecast inputs incorporated broadband infrastructure rollout timelines and carbon market protocol development trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-driven harvest forecasting would alter the outlook if regulatory transparency requirements accelerate or relax. Forecasts reflect assumptions about smallholder subsidy continuity and hyperscale infrastructure expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Video Management System Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Online Voting System Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Global Application Container Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Spain Digital Twin Market
Digital Solutions
China Cloud OSS BSS Market