
 Digital Signage Systems Market | 2026-2036
Digital Signage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signage Systems Market Analytics
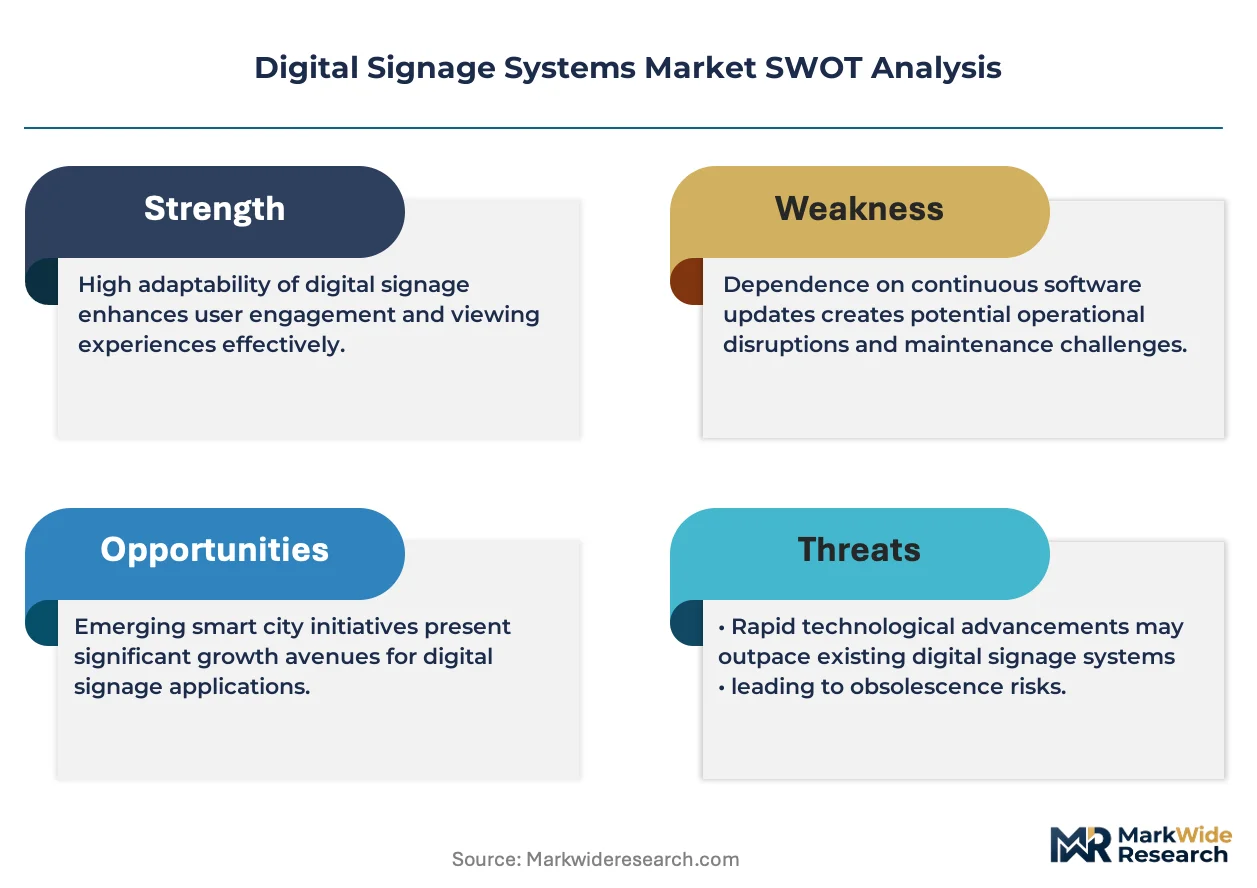
Subscription-based content management is restructuring how digital signage vendors monetize hardware deployments. Samsung Electronics leverages its vertical display manufacturing to control panel supply for large-format LED video walls. LG Electronics anchors its position in OLED signage through specialized thin-film transistor backplane technology. BrightSign LLC competes with purpose-built media players that sustain reliable playback in 24/7 commercial environments.
Digital signage systems encompass networked display hardware, media players, and software platforms that deliver dynamic visual content to targeted audiences, typically operating at resolutions from 1080p to 8K with brightness ratings between 500 and 4,000 nits for varying ambient light conditions. LED product types dominate high-visibility outdoor installations where luminosity and durability requirements exceed liquid crystal capabilities. Cloud-based technology deployments are expanding fastest among multi-location retail operators seeking centralized content orchestration across distributed screen estates. Indoor installation configurations retain the largest addressable base in corporate and education settings where environmental control reduces enclosure costs.
The Federal Communications Commission governs wireless connectivity modules embedded in networked signage, while the EU Green Deal's ecodesign requirements are pressing manufacturers toward lower standby power consumption. Underwriters Laboratories and CE marking standards shape product access across North American and European commercial construction channels. Stakeholders must weigh interoperability investments against proprietary ecosystem lock-in as hybrid technology architectures gain preference among enterprise buyers.
Market Dynamics
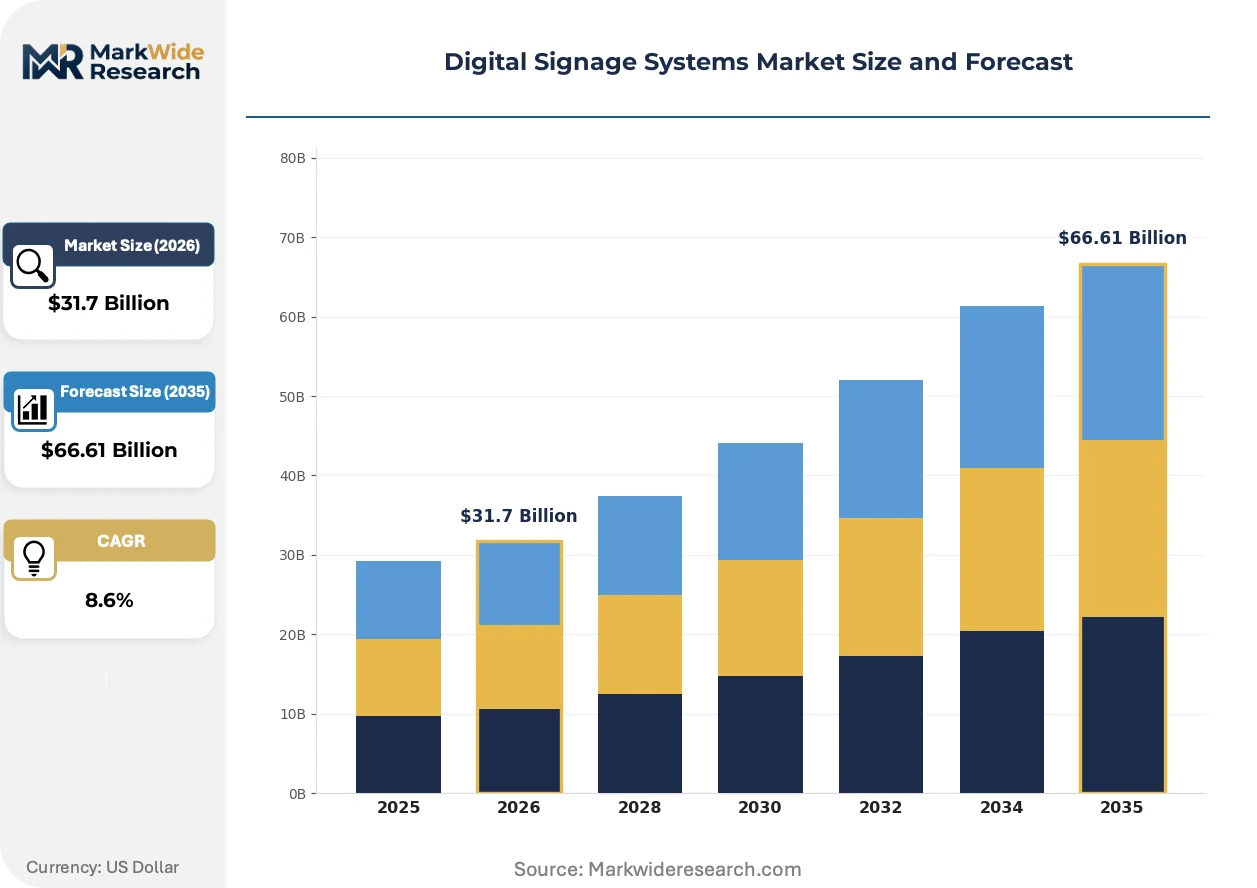
Cloud-based content management platforms are restructuring how digital signage systems are deployed, monetized, and maintained, shifting value capture from hardware margins toward recurring software revenue streams and centralized operational control.
Growth Catalysts
- Smart City Infrastructure Mandates:Municipal governments in Germany, Japan, and the United States are funding networked display installations for real-time transit information and emergency broadcasting, creating anchored demand for outdoor-rated LED systems.
- EU Green Deal Ecodesign Requirements:Standby power consumption regulations are accelerating replacement cycles for legacy signage, compelling facility managers to upgrade to energy-efficient display technologies.
- Dynamic Pricing Algorithms:Retail chains are deploying sensor-integrated screen networks that adjust promotional content based on foot traffic patterns and inventory levels, expanding the addressable use case beyond static advertising.
Market Restraints
- Semiconductor Supply Concentration:Thin-film transistor backplane manufacturing for OLED panels concentrates in South Korea and Taiwan, exposing signage OEMs to single-source risk for premium display components.
- Installation Cost Structure:High-brightness outdoor LED deployments require specialized thermal management enclosures and structural engineering, adding 40-60% to total project costs versus indoor liquid crystal alternatives.
- Wireless Spectrum Licensing:FCC Part 15 regulations constrain transmission power for embedded connectivity modules in dense urban deployments, limiting real-time content synchronization capabilities.
Strategic Opportunities
- Healthcare Wayfinding Applications:Hospital systems in the United States are piloting interactive directory networks that integrate with electronic health record systems, opening a vertical with stringent 24/7 reliability requirements.
- AI-Driven Content Personalization:Computer vision analytics converging with edge computing hardware enable demographic-targeted messaging without cloud latency, creating differentiation for premium deployment tiers.
- India Smart City Mission:Federal funding for urban digital infrastructure is accelerating municipal procurement of outdoor information displays, presenting a geography with low current penetration and policy-backed capital allocation.
Industry Challenges
- Embedded Systems Engineering Talent:Firmware development for purpose-built media players requires specialized expertise in real-time operating systems, creating recruitment bottlenecks for hardware vendors.
- CE Marking Certification Timelines:Electromagnetic compatibility testing for networked signage products routinely extends 8-14 months, compressing product launch windows and freezing engineering resources.
- Legacy Content Migration:Enterprises with decade-old on-premises content management systems face integration complexity when transitioning to cloud-native platforms, delaying contract renewals and expansion orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signage Systems Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $66.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, Projector, OLED Technology: Cloud-Based, On-Premises, Hybrid, Networked End User: Retail, Transportation, Hospitality, Education Installation: Indoor, Outdoor, Wall-Mounted, Freestanding |
| Companies Covered | Samsung Electronics, LG Electronics, Sharp Corporation, Panasonic Corporation, Sony Group Corporation, Leyard, BrightSign LLC, Cisco Systems, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signage Systems Market Evolving Landscape
MicroLED packaging technology is advancing from premium niche toward commercial viability, while regulatory pressure on energy consumption and data privacy reshapes product roadmaps across all display categories.
MicroLED displays are absorbing the high-brightness outdoor segment previously dominated by conventional LED video walls. Stadium operators and transportation authorities are specifying microLED for 10,000+ nit applications where thermal efficiency and color consistency outweigh cost premiums. This technology is absorbing margin pressure from commoditized liquid crystal alternatives by establishing a performance tier without direct competition.
The EU AI Act's risk classification framework is imposing documentation and transparency requirements on signage systems with embedded computer vision. Manufacturers must now maintain algorithmic audit trails for audience analytics features, increasing compliance overhead for European deployments. Outdoor retail and smart city applications face the steepest compliance burden, with several vendors pre-emptively disabling facial analysis capabilities.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software platforms rather than assembling components from separate suppliers. Multi-location retailers in North America are favoring single-source contracts that bundle displays, media players, and content management under unified service-level agreements. This preference shift is most pronounced among quick-service restaurant chains and pharmacy networks with standardized national footprints.
Digital Signage Systems Market Segmentation
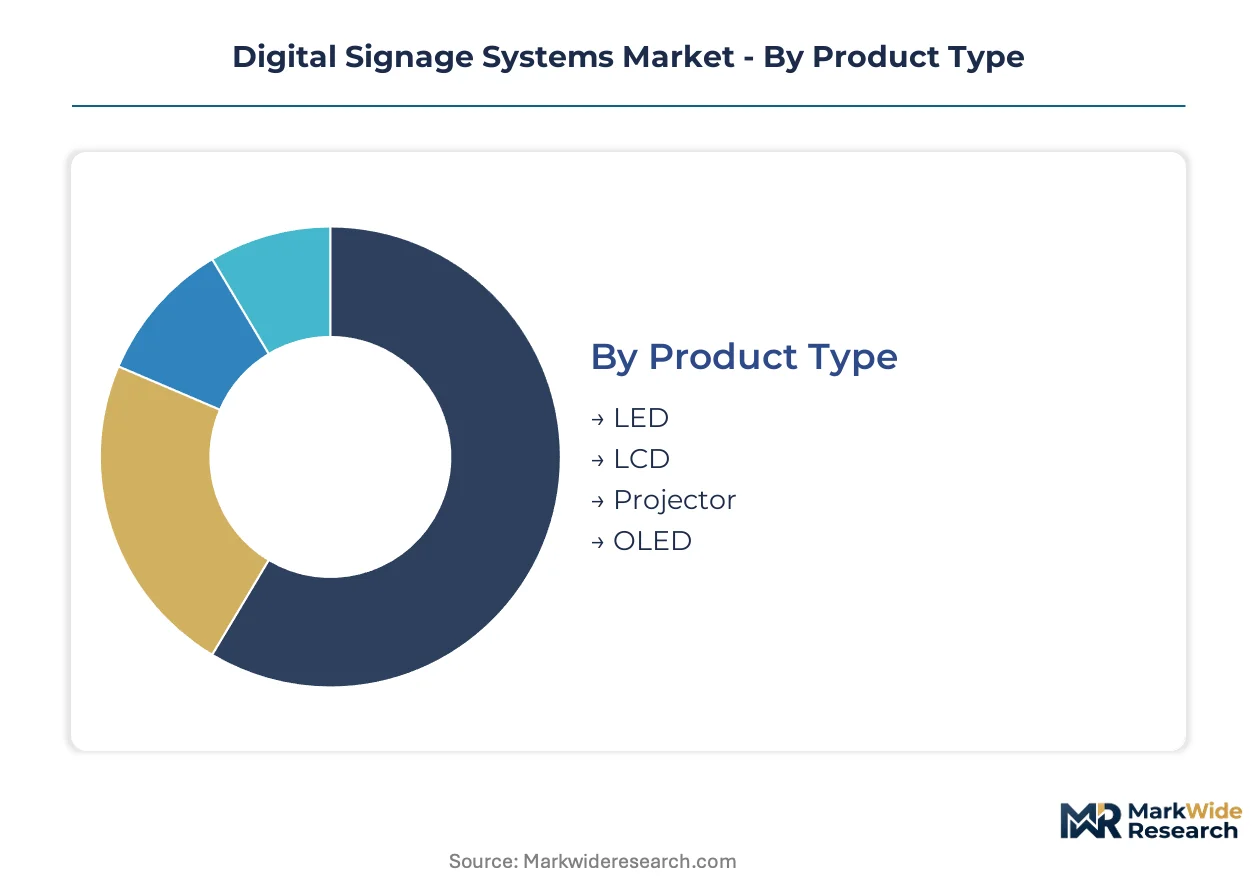
Digital signage procurement decisions hinge on environmental durability, content orchestration architecture, and vertical-specific compliance requirements. Segment boundaries increasingly blur as cloud-native platforms absorb hardware differentiation and embedded AI capabilities reshape total cost calculations.
Product Type:
LED and LCD systems anchor standalone deployments where display performance determines procurement, while OLED and projector technologies embed into integrated architectural solutions demanding deeper systems integration.
- LED:Direct-view LED modules achieve 4,000–10,000 nits brightness through chip-on-board packaging, sustaining visibility in direct sunlight. Demand concentrates in Germany, Japan, and the United States where municipal transit authorities specify outdoor-rated cabinets for wayfinding and emergency alerts. Thermal management engineering adds substantial project cost but extends operational lifespan beyond liquid crystal alternatives.
- LCD:Liquid crystal panels with edge-lit LED backlights dominate indoor corporate and education settings where ambient light stays controlled. Procurement volumes cluster in North American retail chains and Japanese office complexes seeking 1080p to 4K resolution at sub-1,000 nit specifications. Panel supply concentrates among Korean and Taiwanese manufacturers, creating lead time vulnerability for large-format orders.
- Projector:Laser phosphor projectors serve temporary installations and heritage buildings where permanent display mounting faces structural restrictions.
- OLED:Organic light-emitting diode signage delivers infinite contrast ratios through self-emissive pixels, finding niche adoption in premium retail and museum applications.
Volume placements concentrate in LCD; the faster expansion belongs to LED.
Technology:
Deployment architecture determines operational control depth, with cloud-based platforms enabling centralized management while hybrid configurations preserve on-premises security for sensitive content.
- Cloud-Based:Browser-accessible content management platforms synchronize thousands of endpoints through API-driven workflows. Multi-location retailers in the United States and Germany favor this model for dynamic pricing updates across distributed estates. Subscription revenue restructuring shifts vendor economics from hardware margins toward recurring software fees.
- On-Premises:Local server installations maintain content libraries behind corporate firewalls, satisfying healthcare and financial sector data residency requirements. Japanese enterprise buyers particularly favor this architecture for internal communications networks where cloud connectivity faces IT security review.
- Hybrid:Edge-cached content with cloud orchestration balances real-time responsiveness with offline resilience.
- Networked:IP-connected displays without full CMS integration serve basic digital poster applications.
Networked systems retain the largest installed base; cloud-based deployments are climbing the fastest.
End User:
Vertical specialization drives feature prioritization, with retail demanding dynamic content agility while transportation prioritizes 24/7 reliability certification.
- Retail:Sensor-integrated screen networks adjust promotional content based on foot traffic and inventory levels. North American quick-service restaurant chains and pharmacy networks deploy these systems for queue management and upsell optimization. FCC Part 15 regulations constrain wireless transmission power in dense urban mall environments.
- Transportation:Airport and railway operators in Germany and Japan specify MIL-STD-810G shock resistance and wide-temperature operation for passenger information displays. EU Green Deal standby power requirements are accelerating replacement of legacy cathode-ray tube installations.
- Hospitality:Hotels and conference centers deploy wayfinding and event signage with centralized brand control.
- Education:K-12 and university campuses prioritize interactive whiteboard integration and emergency broadcast capabilities.
Education holds the broadest deployment footprint; retail is gaining share fastest.
Installation:
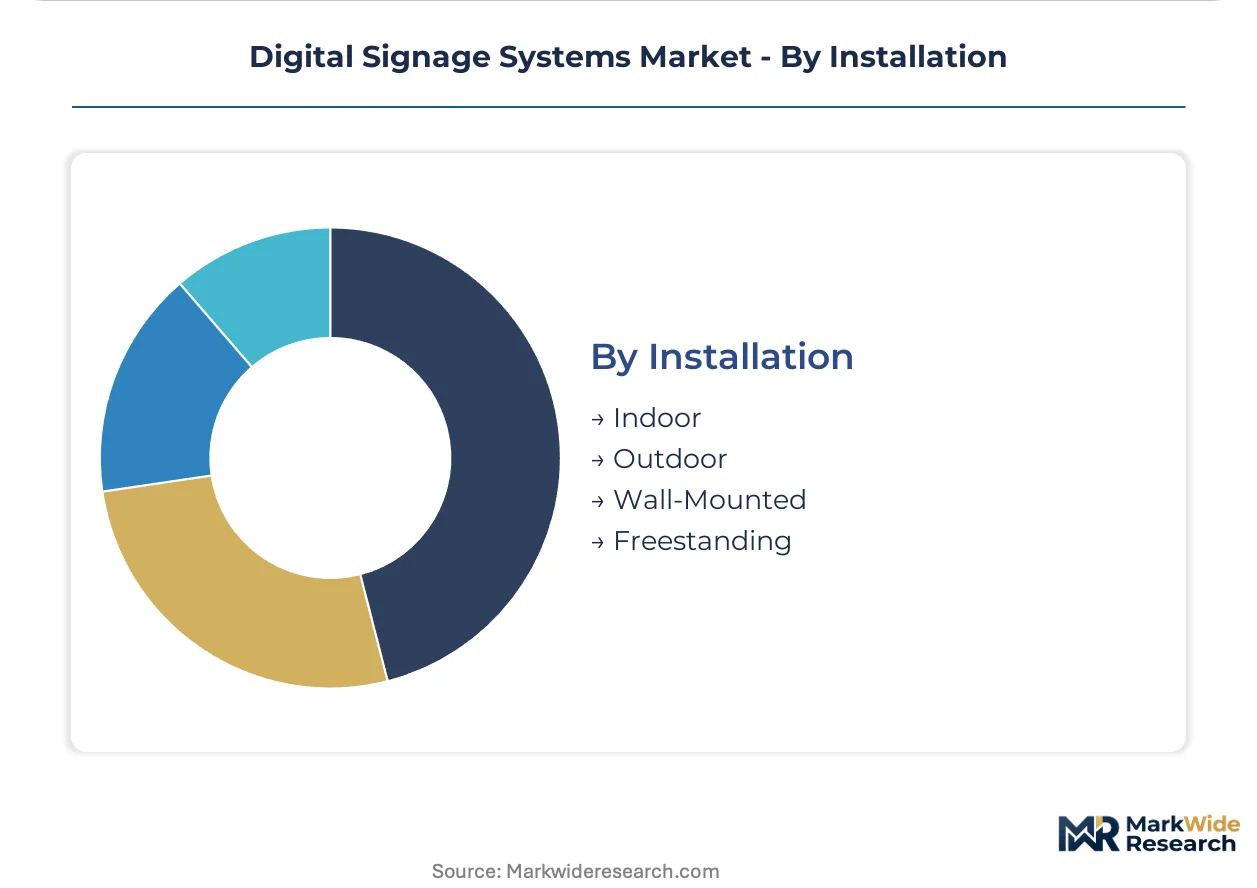
Environmental exposure determines enclosure engineering investment, with outdoor specifications demanding IP65 sealing and active thermal management absent from climate-controlled indoor alternatives.
- Indoor:Climate-controlled environments reduce enclosure costs and enable thinner bezel designs for video wall tiling. Corporate headquarters and university campuses in the United States and Japan represent concentrated demand for 55-inch and 65-inch landscape formats.
- Outdoor:High-brightness LED installations require structural engineering for wind load and vandal resistance. Smart city infrastructure investments in Germany and the United States are expanding municipal procurement for transit shelter and street furniture integration.
- Wall-Mounted:Flush architectural integration suits permanent corporate and healthcare directory applications.
- Freestanding:Kiosk and totem formats enable repositioning for seasonal retail layouts and temporary event deployments.
Wall-mounted configurations dominate current volumes; outdoor installations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel manufacturing concentrates in South Korea and Taiwan, while deployment demand clusters in Germany, Japan, and the United States where smart city infrastructure investments drive procurement volumes.
Germany
Municipal transit authorities in Berlin and Munich are procuring outdoor-rated LED systems for real-time passenger information displays. The EU Green Deal's ecodesign requirements are accelerating replacement of legacy cathode-ray tube installations in railway stations. Industrial demand centers on Bavaria and Baden-Württemberg where automotive headquarters deploy corporate communication networks.
Japan
Tokyo's metropolitan government is funding networked screen installations for emergency broadcasting and disaster alert systems. METI efficiency standards are pressing facility managers toward lower standby power consumption in commercial displays. Osaka and Nagoya clusters anchor enterprise demand for 24/7 reliability-certified indoor installations in corporate and retail settings.
United States
Quick-service restaurant chains and pharmacy networks are deploying sensor-integrated screen networks for dynamic pricing and queue management. FCC Part 15 regulations constrain wireless transmission power for embedded connectivity modules in dense urban mall environments. Procurement concentrates in Texas, California, and the Northeast Corridor where multi-location retail operators seek centralized content orchestration.
India
The Smart City Mission is channeling federal funding toward urban digital infrastructure including outdoor information displays in transit hubs. BIS certification requirements are shaping product access for commercial construction channels. Demand clusters in Maharashtra and Karnataka where municipal corporations in Mumbai and Bangalore are piloting networked signage for public service delivery.
South Korea
Seoul's metropolitan government is specifying high-brightness LED installations for street furniture integration and smart transit shelters. Domestic panel supply from Korean manufacturers reduces lead time vulnerability for large-format orders. The Seoul Capital Area and Busan-Ulsan region concentrate corporate headquarters procurement for indoor video wall deployments.
Digital Signage Systems Market Competitive Landscape
Top-tier vendors anchor integrated hardware-software platforms, while specialized component suppliers occupy niche positions in media players and connectivity modules. The vendor base stratifies across three archetypes: diversified electronics conglomerates with captive display manufacturing, purpose-built signage specialists, and enterprise networking vendors extending into visual communication systems. Consolidation pressures favor single-source contracts bundling displays, software, and service-level agreements. Competitive moves center on vertical integration into panel supply and cloud-native platform development.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics exemplify the integrated-manufacturer archetype through vertical control over display panel production. BrightSign LLC occupies a specialist position in purpose-built media players designed for commercial reliability requirements. These three companies represent distinct strategic postures: captive supply chain integration, display technology leadership, and embedded systems specialization respectively.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sharp Corporation |
| Panasonic Corporation |
| Sony Group Corporation |
| Leyard |
| BrightSign LLC |
| Cisco Systems |
| Daktronics |
| Others |
Value Network & Pricing Analysis
Performance divergence between microLED premium tiers and commoditized LCD alternatives splits procurement budgets and supplier portfolios across fundamentally different manufacturing footprints. Cloud-native software subscriptions now capture recurring revenue streams that offset hardware margin compression, while panel supply concentration in East Asian fabrication clusters constrains pricing flexibility for buyers seeking large-format LED deployments.
Pricing Analysis
Margin tightening in outdoor LED systems reflects thermal management enclosure costs that add substantial project overhead versus indoor alternatives. Three-tier pricing structure across premium, standard, and economy levels separates microLED stadium installations from conventional LED transit displays and entry-level LCD corporate networks. Certification grade under UL and CE marking standards drives price differentiation alongside volume scale for multi-location retail rollouts. Cost-down pressure on indoor LCD accelerates because Korean and Taiwanese panel manufacturers face lead time vulnerability for large-format orders. Quick-service restaurant chains exhibit highest price sensitivity due to standardized national footprint requirements, while transportation authorities prioritize 24/7 reliability certification over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's Smart City Mission are reshaping sourcing patterns for municipal procurement of outdoor information displays. Thin-film transistor backplane manufacturing concentrates in South Korea and Taiwan, exposing signage OEMs to single-source risk for premium OLED components. Raw material dependencies span gallium nitride for LED chips, rare earth phosphors for laser projectors, and specialized aluminum enclosures for thermal management. Single-source vulnerability in display panel supply creates structural risk for vendors without captive fabrication capacity. Distribution runs through systems integrators and direct enterprise contracts rather than traditional electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film transistor backplane fabrication capacity constraints in South Korea and Taiwan prop pricing power for integrated display manufacturers, creating a supply-constrained market structure favoring vendors with captive panel supply.
For Market Incumbents: Lock in long-term supply agreements with Korean and Taiwanese backplane manufacturers to secure allocation priority as microLED capacity expands. Invest in backward integration into LED chip packaging to defend against commoditization pressure from Chinese competitors. Prioritize cloud-native platform development to capture recurring software revenue that offsets hardware margin erosion. For New Entrants and Emerging Players: Enter via healthcare wayfinding applications in the United States where stringent 24/7 reliability requirements and EHR integration complexity deter established consumer electronics vendors. Target India's Smart City Mission municipalities where BIS certification requirements create regulatory moats against unqualified competitors. Pursue partnership-based go-to-market models with systems integrators possessing existing hospital or municipal relationships. For Investors and Strategic Acquirers: Re-rating potential sits with purpose-built media player specialists given enterprise consolidation around integrated hardware-software platforms. Long-term viability favors vendors with software recurring revenue exceeding hardware dependency. Monitor cloud-native content management platform adoption rates as the inflection signal for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Fabrication | Samsung Electronics and LG Electronics control critical gallium nitride supply for high-brightness outdoor installations. |
| Cloud-Native Platform Development | BrightSign LLC competes through API-driven content orchestration that displaces legacy on-premises server architectures. |
| Healthcare Vertical Specialization | Hospital systems in the United States pilot interactive directory networks integrating with electronic health record infrastructure. |
| India Smart City Mission Alignment | Federal funding for urban digital infrastructure accelerates municipal procurement in Maharashtra and Karnataka states. |
| EU Green Deal Compliance Investment | Energy-efficient display technologies capture replacement demand as standby power regulations force legacy system upgrades. |
Research Methodology
Multi-period observation of municipal procurement cycles, retail deployment timelines, and semiconductor fabrication capacity utilization anchored the trend analysis, supplemented by interviews with digital signage systems executives, municipal IT procurement officers, cloud platform engineers, and systems integration specialists. Secondary validation drew from FCC equipment authorization databases, EU ecodesign regulatory filings, BIS certification records, SEC 10-K disclosures from diversified electronics conglomerates, and smart city infrastructure investment announcements. Bottom-up triangulation of vendor shipment data converged with top-down spending estimates from enterprise technology budgets.
Segment-weighting across product type, deployment technology, end-use vertical, and installation environment shaped the analytical framework. Cloud-based versus on-premises technology splits, retail versus transportation end-use concentration, and indoor versus outdoor installation ratios informed volume allocation. CAGRs were derived from fitted growth curves calibrated against historical replacement cycle patterns and policy-backed capital allocation timelines. Panel supply lead times and content management platform subscription renewal rates served as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated EU AI Act enforcement on computer vision analytics. Forecasts reflect assumptions regarding smart city infrastructure commitment continuity, retail capital expenditure recovery, and wireless spectrum licensing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Utility Cases Market
Digital Solutions
Australia ICT Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
South Africa ICT Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Canada ICT Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Database Management Platform Market