
 Backup-As-A-Service (Baas) Market | 2026-2036
Backup-As-A-Service (Baas) Market Size, Share, and Industry Trends Forecast 2026-2036
Backup-As-A-Service (Baas) Market Insights
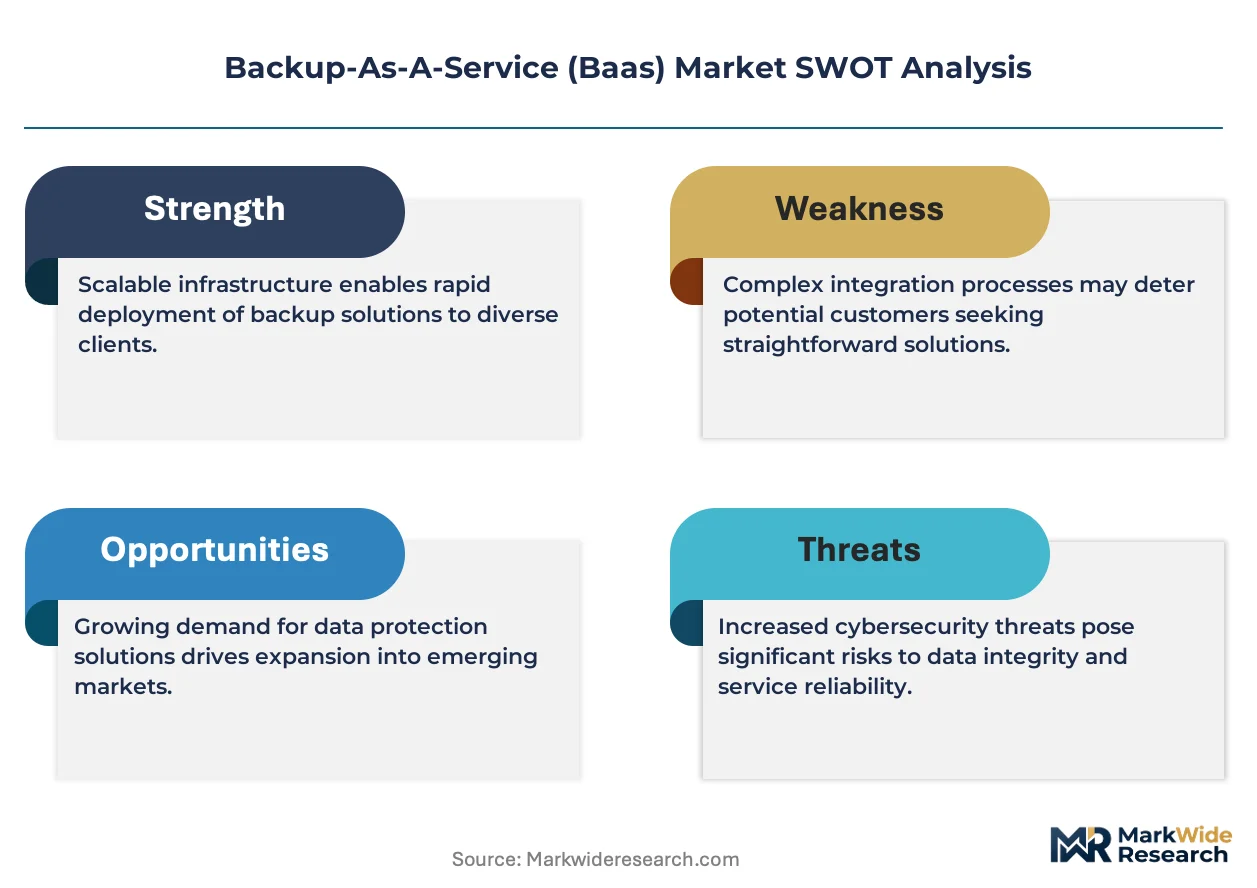
ISO 27001 certification is bifurcating the competitive landscape into qualified providers and excluded aspirants. Amazon Web Services leverages its global infrastructure footprint to anchor multi-region redundancy offerings. Microsoft competes through deep integration with enterprise productivity suites. Veeam Software specializes in virtual-machine-centric backup architectures for hybrid environments.
Backup-as-a-Service denotes a managed cloud delivery model where third-party providers host, operate, and restore customer data through subscription-based platforms, typically employing immutable object storage, AES-256 encryption, and point-in-time recovery with sub-hour RPO targets to ensure business continuity against ransomware, hardware failure, or natural disaster. Cloud backup services now capture the dominant margin pool as enterprises abandon tape-based rotation, while hybrid backup deployments represent the fastest-growing structural segment as regulated industries seek to balance cloud elasticity with on-premises control. Disaster recovery services command premium pricing due to stringent SLA requirements around RTO guarantees.
FDA 21 CFR Part 11 imposes audit-trail and data-integrity requirements on life-science backup systems, while HIPAA mandates encrypted off-site retention for protected health information, and EU GDPR Articles 32 and 17 shape erasure and breach-notification protocols that providers must embed architecturally. Stakeholders should monitor evolving SEC cybersecurity disclosure rules for material incident reporting, as these will redefine liability allocation between BaaS vendors and their enterprise clients.
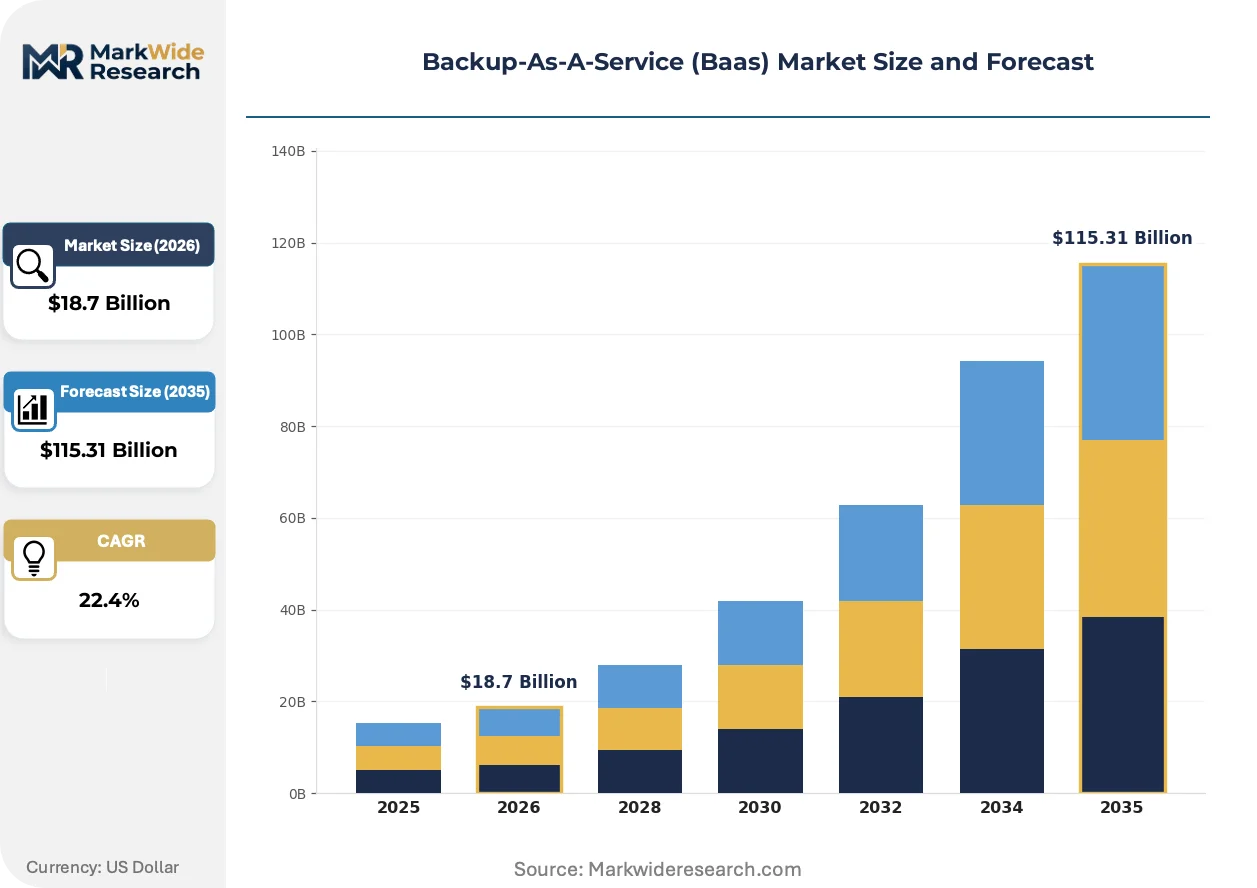
Market Dynamics
Immutable object storage architectures are displacing tape-based rotation as the default enterprise standard, compressing recovery point objectives from days to minutes and forcing vendors to re-engineer pricing models around sub-hour SLA guarantees.
Growth Catalysts
- Ransomware resilience mandates:HIPAA requires encrypted off-site retention for protected health information, compelling US healthcare systems to abandon on-premises tape libraries.
- EU AI Act data-localization:Article 5 obligations are forcing enterprises to re-architect storage strategies with in-region redundancy.
- Industrial SME compliance pressure:German federal data-residency requirements are concentrating demand among Mittelstand manufacturers seeking ISO 27001-certified providers.
Market Restraints
- Encryption key management complexity:AES-256 key lifecycle costs consume 15-22% of total contract value, creating procurement friction in mid-market segments.
- Cross-border latency penalties:GDPR Article 44 transfer mechanism uncertainties restrict multi-region orchestration for EU-headquartered enterprises.
- Skilled architect scarcity:Certified disaster recovery engineers command 40% salary premiums, constraining provider scaling velocity.
Strategic Opportunities
- Hybrid deployment white space:Regulated industries in Switzerland and Singapore seek to balance cloud elasticity with on-premises control for audit-trail sovereignty.
- Disaster recovery unbundling:Premium RTO guarantees are commanding separate pricing tiers from base backup subscriptions.
- API-native channel expansion:DevOps-oriented buyers are purchasing through infrastructure-as-code marketplaces rather than traditional enterprise sales cycles.
Industry Challenges
- FDA 21 CFR Part 11 validation timelines:Life-science customers require 6-18 month qualification periods for electronic record systems, extending sales cycles.
- Legacy mainframe integration:Financial services institutions maintain decades-old IBM z/OS environments that resist cloud-native backup protocols without costly middleware layers.
- SEC cybersecurity disclosure readiness:Material incident reporting rules are redefining liability allocation between BaaS vendors and enterprise clients, requiring contract renegotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backup-As-A-Service (Baas) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Backup, Local Backup, Hybrid Backup, Disaster Recovery Deployment Model: Public Cloud, Private Cloud, On-Premises, Managed Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Data Type: Structured Data, Unstructured Data, Virtual Machines, Applications |
| Companies Covered | Amazon Web Services, Microsoft, IBM, Veeam Software, Commvault, Acronis, Dell Technologies, Cohesity, Rubrik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backup-As-A-Service (Baas) Market Trends and Innovations
Agentless backup architectures are compressing deployment timelines from weeks to hours, eliminating the traditional endpoint software footprint that previously blocked cloud-native adoption in regulated sectors.
Container-native data protection is miniaturizing recovery granularity from virtual machines to individual Kubernetes pods. DevOps teams at SaaS providers are adopting this capability to meet internal SLOs without provisioning full VM restores. The technology is miniaturizing backup windows from hours to seconds for microservices architectures.
EU GDPR Article 32 security-of-processing requirements are mandating encryption-by-default for all personal data backups. Cloud providers must now demonstrate technical and organizational measures through third-party attestation. Healthcare and financial services verticals in Germany and France are driving the strictest interpretation, rejecting providers without ISO 27701 privacy certification.
Subscription fatigue is fragmenting procurement authority from central IT to line-of-business units. Department heads in manufacturing and retail are purchasing departmental backup solutions through credit-card self-service rather than enterprise-wide RFP processes. This pattern is most pronounced in North American mid-market enterprises with distributed operational technology environments.
Backup-As-A-Service (Baas) Market Segmentation
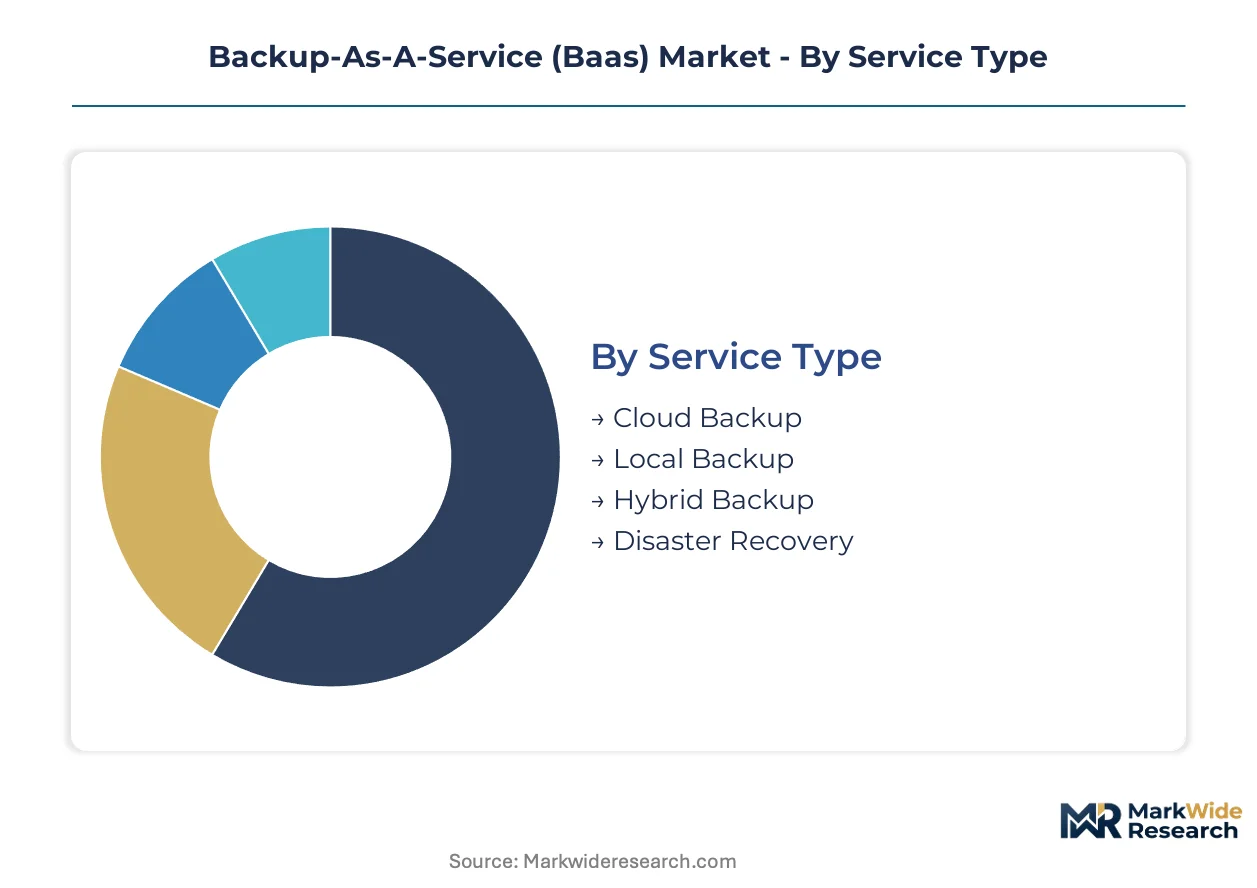
BaaS procurement patterns diverge sharply across service tiers and deployment architectures. Margin capture depends on matching immutable storage guarantees to specific regulatory exposure profiles.
Service Type:
Cloud backup services command the dominant margin pool as enterprises abandon tape-based rotation. Disaster recovery offerings capture premium pricing through stringent RTO guarantees.
- Cloud Backup:Subscription platforms host customer data through immutable object storage with AES-256 encryption and sub-hour RPO targets. Healthcare providers in the US are expanding adoption for HIPAA-mandated encrypted off-site retention of patient records.
- Disaster Recovery:Managed services guarantee specific recovery time objectives through dedicated infrastructure orchestration. German industrial SMEs facing strict federal data-residency requirements are concentrating demand for ISO 27001-certified disaster recovery tiers.
- Hybrid Backup:Combines cloud elasticity with on-premises control for audit-trail sovereignty. Regulated industries in Switzerland and Singapore are balancing these requirements.
- Local Backup:On-site retention for low-latency recovery scenarios. Financial services maintain these for trading floor continuity.
Cloud backup holds installed capacity. Disaster recovery is rotating up the share rankings.
Deployment Model:
Public cloud deployments scale fastest among DevOps-oriented buyers purchasing through infrastructure-as-code marketplaces. Private cloud architectures retain pricing power in life-science verticals requiring FDA 21 CFR Part 11 validation.
- Public Cloud:Multi-tenant infrastructure delivers subscription economics with rapid provisioning. API-native channel expansion is accelerating procurement through credit-card self-service rather than traditional enterprise sales cycles.
- Private Cloud:Single-tenant environments satisfy data-localization mandates under EU AI Act Article 5 obligations. EU-headquartered enterprises are re-architecting storage strategies with in-region redundancy.
- Managed Services:Providers assume operational responsibility for backup lifecycle management. Mid-market segments face procurement friction from AES-256 key lifecycle costs consuming 15-22% of total contract value.
- On-Premises:Customer-operated infrastructure for complete control over encryption key custody. Legacy mainframe integration challenges persist in IBM z/OS environments.
Public cloud deployments dominate volume. Private cloud is climbing the fastest among regulated verticals.
End User:
Large enterprises generate the highest contract values through multi-year agreements with custom SLA architectures. SME procurement is fragmenting from central IT to line-of-business units with distributed operational technology environments.
- Large Enterprises:Global organizations require multi-region redundancy with centralized governance. SEC cybersecurity disclosure rules are redefining liability allocation between BaaS vendors and enterprise clients.
- SMEs:Mid-market manufacturers seek departmental solutions without enterprise-wide RFP overhead. Subscription fatigue is driving credit-card self-service procurement in North American distributed environments.
- Government Agencies:Sovereign cloud requirements with domestic data residency. Federal procurement cycles extend qualification timelines.
- Educational Institutions:Research data protection with grant-funded budget constraints. Seasonal enrollment drives backup window variability.
Large enterprises anchor revenue concentration. SME segment is gaining share fastest through unbundled procurement.
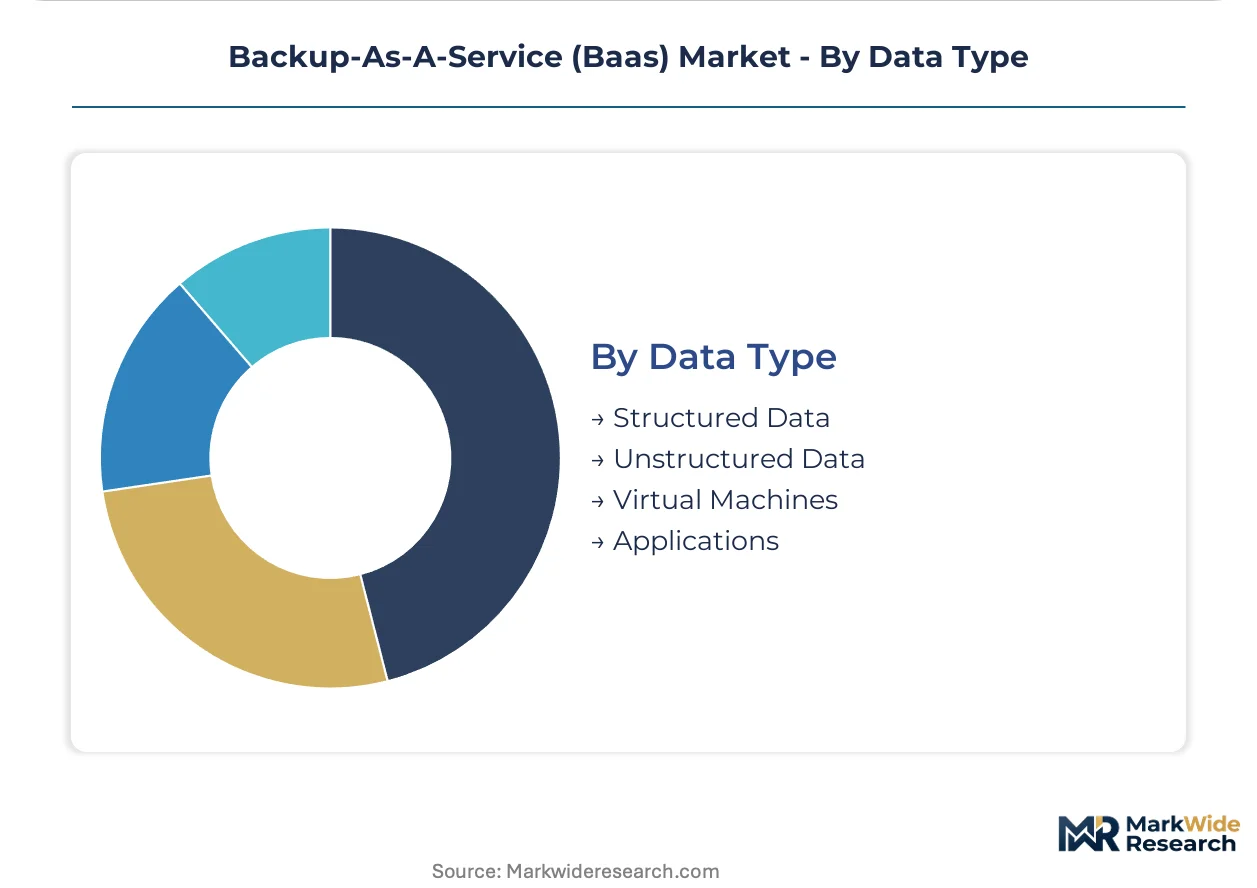
Data Type:
Virtual machine protection captures the largest addressable spend as enterprises consolidate server footprints. Container-native data protection is miniaturizing recovery granularity for microservices architectures.
- Virtual Machines:Hypervisor-consistent snapshots with application-aware quiescing. Veeam Software specializes in VM-centric backup architectures for hybrid environments.
- Applications:Database-consistent protection with log shipping and point-in-time recovery. DevOps teams at SaaS providers are adopting container-native capabilities to meet internal SLOs.
- Unstructured Data:File system and object storage protection with deduplication. GDPR Article 32 encryption-by-default mandates apply to all personal data backups.
- Structured Data:Relational database protection with schema-aware recovery. Life-science customers require 6-18 month qualification periods under FDA 21 CFR Part 11.
Virtual machine protection holds installed base. Application-level backup is expanding most quickly through microservices adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act Article 5 obligations and GDPR data-localization mandates are compelling enterprises across multiple jurisdictions to re-architect storage strategies with in-region redundancy. Healthcare systems and industrial manufacturers face the strictest compliance pressures.
Germany
Mittelstand manufacturers and automotive suppliers drive demand for ISO 27001-certified disaster recovery tiers. The Federal Data Protection Act and GDPR Articles 32 and 17 shape erasure and breach-notification protocols that providers must embed architecturally. Industrial clusters in Bavaria and Baden-Württemberg concentrate procurement among SMEs seeking encrypted off-site retention with sovereign cloud guarantees.
United States
Healthcare providers expand cloud backup adoption for HIPAA-mandated encrypted off-site retention of patient records. FDA 21 CFR Part 11 imposes audit-trail and data-integrity requirements on life-science backup systems. The Research Triangle in North Carolina and Boston-Cambridge biotech corridor generate concentrated demand for validated electronic record systems with 6-18 month qualification timelines.
Switzerland
Pharmaceutical headquarters and private banking institutions seek hybrid deployments balancing cloud elasticity with on-premises control for audit-trail sovereignty. Swissmedic guidance on data integrity for clinical trials reinforces strict interpretation of GDPR-equivalent protections. Zurich and Basel clusters reject providers without ISO 27701 privacy certification.
France
CNIL enforcement of GDPR Article 32 security-of-processing requirements mandates encryption-by-default for all personal data backups. Healthcare and financial services verticals in Île-de-France drive the strictest provider qualification standards. Paris-based enterprises re-architect storage strategies to satisfy ANSM pharmaceutical data residency expectations.
Singapore
Financial services institutions and sovereign wealth funds demand hybrid backup architectures combining cloud scalability with domestic data custody. The Monetary Authority of Singapore's technology risk management guidelines prescribe business continuity arrangements with sub-hour RPO targets. Marina Bay and Raffles Place financial districts concentrate procurement among providers offering dedicated infrastructure orchestration.
Backup-As-A-Service (Baas) Market Competitive Landscape
Player mix skews toward hyperscale cloud platforms with global infrastructure footprints. Market structure concentrates around three strategic tiers: infrastructure-native providers leveraging multi-region redundancy, enterprise software vendors integrating backup with productivity suites, and specialists in virtual-machine-centric architectures for hybrid environments. Dominant competitive moves include API-native channel expansion through infrastructure-as-code marketplaces and unbundled disaster recovery pricing with premium RTO guarantees.
Within the infrastructure-native tier, Amazon Web Services and Microsoft exemplify scale-driven positioning through global footprint and enterprise productivity integration respectively. Veeam Software occupies a specialist position representing virtual-machine-centric backup architectures for hybrid environments. These three anchors illustrate the competitive spectrum from hyperscale platform dominance to focused technical specialization.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Veeam Software |
| Commvault |
| Acronis |
| Dell Technologies |
| Cohesity |
| Rubrik |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with ISO 27001-certified providers lock in both supply access and price visibility for German Mittelstand manufacturers facing federal data-residency mandates. These multi-year agreements bundle encryption key lifecycle management with guaranteed sub-hour RPO targets, creating procurement friction for mid-market buyers while securing margin pools for qualified vendors.
Pricing Analysis
Certification level creates the primary spread between qualified providers and excluded aspirants in this market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance exposure, with ISO 27701 privacy certification commanding substantial premiums in Swiss and French healthcare verticals. Price erosion runs through the unmanaged public cloud tier as hyperscalers compete on infrastructure scale. Mid-market SMEs with distributed operational technology environments exhibit the highest price sensitivity, while life-science customers with FDA 21 CFR Part 11 requirements demonstrate inelastic demand for validated tiers.
Supply Chain Analysis
Inventory compression from agentless backup architectures has collapsed deployment timelines from weeks to hours across the provisioning layer. Infrastructure supply concentrates in the United States, Ireland, and Germany where hyperscale cloud regions satisfy EU AI Act data-localization requirements. The supply chain draws from specialized semiconductor components for encryption accelerators, enterprise storage arrays for hybrid deployments, and certified engineering talent for disaster recovery orchestration. Single-source vulnerability in skilled architect availability constrains provider scaling velocity. Distribution runs through API-native infrastructure-as-code marketplaces for DevOps-oriented buyers and traditional enterprise sales cycles for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified disaster recovery engineers command 40% salary premiums, constraining how quickly providers can scale operations to meet concentrated demand in Germany and Switzerland. This capability scarcity rewards early investments in workforce development and automated orchestration tooling.
For Market Incumbents: Compound defensive positioning through backward integration into encryption key lifecycle services and capacity expansion in Frankfurt and Zurich cloud regions. The unbundling of disaster recovery pricing from base subscriptions threatens margin pools for providers without dedicated infrastructure orchestration capabilities. Prioritize ISO 27701 certification investment to maintain access to Swiss and French healthcare verticals rejecting uncertified vendors. For New Entrants and Emerging Players: Container-native data protection for Kubernetes environments represents a service-layer gap where incumbents under-serve DevOps teams at SaaS providers. Target this microservices backup segment through infrastructure-as-code marketplace listings rather than traditional enterprise sales cycles. The fastest penetrable geography is Singapore, where MAS guidelines prescribe sub-hour RPO targets but local provider presence remains limited. For Investors and Strategic Acquirers: Agentless backup architecture specialists with established API-native channel partnerships represent the most attractive acquisition target archetype. Long-term viability in this market hinges on automation capabilities that reduce dependency on scarce certified engineers. Watch for inflection signals in SEC cybersecurity disclosure rule enforcement, which will redefine liability allocation and trigger contract renegotiation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27701 Privacy Certification | Swissmedic and ANSM pharmaceutical guidance now rejects providers without this attestation. |
| API-Native Marketplace Expansion | DevOps-oriented buyers at SaaS providers purchase through infrastructure-as-code channels bypassing enterprise sales. |
| Hybrid Deployment Architecture | Singapore MAS guidelines and Swiss banking requirements mandate domestic data custody with cloud elasticity. |
| Container-Native Data Protection | Kubernetes pod-level recovery granularity meets internal SLOs without full VM restore provisioning. |
| Disaster Recovery Unbundling | Premium RTO guarantees now command separate pricing tiers from base backup subscriptions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief information security officers, enterprise IT procurement managers, disaster recovery architects, and compliance officers at healthcare and financial services institutions. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act regulatory texts, HIPAA enforcement actions, and hyperscaler infrastructure expansion announcements. Bottom-up sizing of subscription contract values triangulated against top-down market aggregation across deployment models and service tiers.
Across the projection horizon, the analytical framework modeled segmentation dimensions including service type, deployment architecture, organization size tier, data protection granularity, and regional regulatory cluster. CAGRs were synthesized from adoption curve analysis and replacement cycle dynamics. Forecast inputs incorporated ransomware incident frequency trends and qualification timeline compression for FDA 21 CFR Part 11 validation.
Underlying assumptions cover sustained regulatory enforcement of GDPR Article 32 encryption mandates and EU AI Act data-localization requirements, with deviation risk concentrated in SEC cybersecurity disclosure rule implementation timing and skilled architect supply elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Business Information Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Australia Cloud OSS BSS Market