
 Fuel Management Software Market | 2026-2036
Fuel Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Management Software Market Foresight
Cloud infrastructure is decoupling fuel management software from legacy on-premise hardware economics, collapsing deployment costs for mid-size fleet operators. Samsara leverages its IoT-native architecture to anchor real-time telematics across North American logistics corridors. Geotab competes through open-platform APIs that sustain third-party integration density. Fleetio specializes in mobile-first maintenance workflows that differentiate its offering for smaller fleet segments.
Fuel management software encompasses platforms that monitor, control, and optimize fuel procurement, storage, and consumption across vehicle fleets and stationary assets, typically integrating GPS telemetry, tank-level sensors, and ERP connectors through standardized API protocols. Cloud-based deployment leads in new customer acquisition due to lower capital barriers and automatic feature updates, while on-premise installations retain margin concentration among defense and critical infrastructure buyers with air-gapped security requirements. Fleet management application segments dominate revenue contribution as diesel cost volatility forces operators toward predictive consumption analytics.
The EPA enforces emissions reporting thresholds that shape product requirements for commercial vehicle fleets exceeding defined weight classes, while the DOT's electronic logging device mandates create compliance-driven software attach rates. Fleet operators must weigh subscription pricing flexibility against perpetual license total-cost-of-ownership as fuel price hedging becomes a core procurement criterion.
Market Dynamics
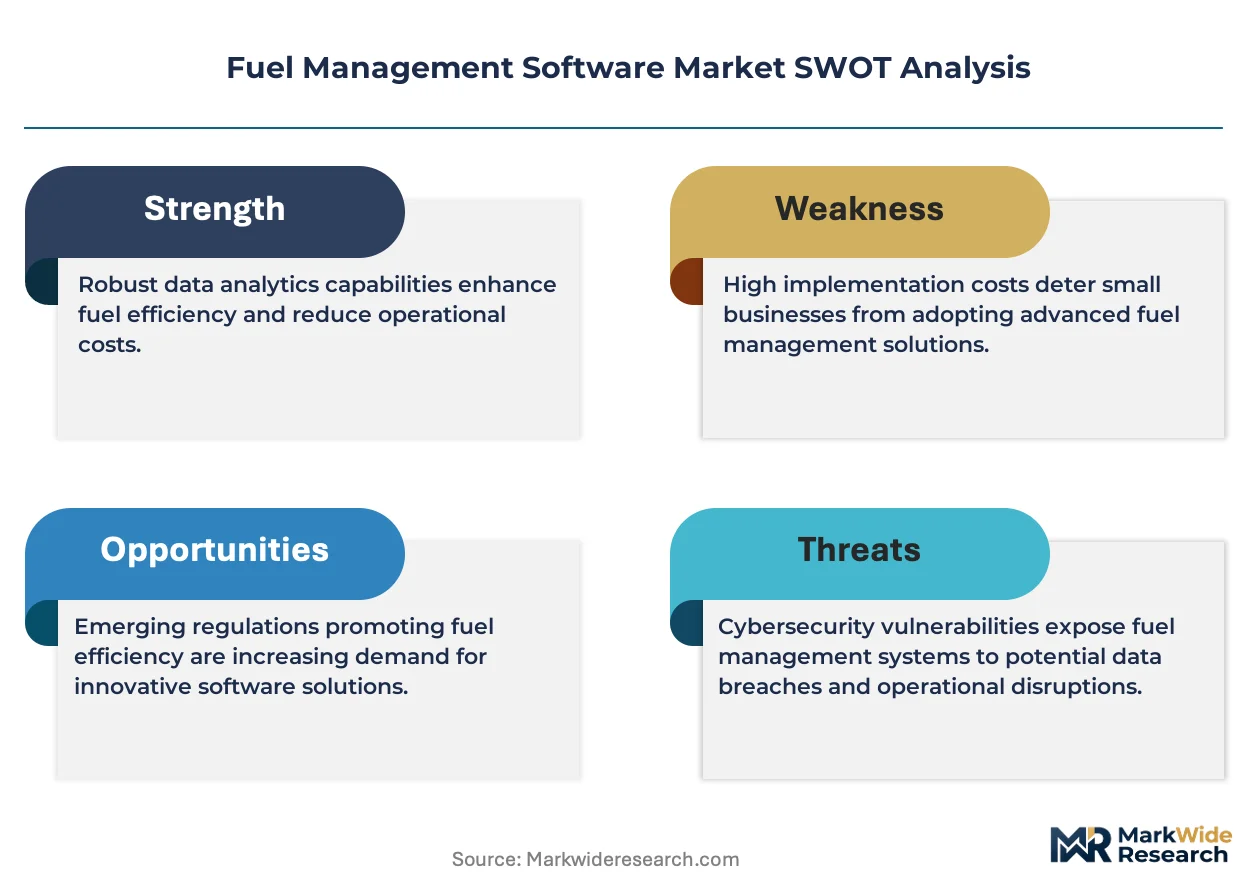
Cloud infrastructure economics are collapsing deployment barriers for mid-size fleet operators while EPA emissions enforcement tightens compliance requirements for commercial vehicle software procurement.
Growth Catalysts
- Telematics Integration:IoT sensor networks now feed real-time fuel consumption data into predictive analytics engines, enabling logistics operators to optimize route efficiency and idle-time reduction.
- EPA Emissions Mandates:The EPA's evolving standards for commercial vehicle fleets exceeding defined weight classes compel operators to deploy automated monitoring systems for regulatory reporting.
- Diesel Price Volatility:Fleet managers in the United States are prioritizing fuel hedging capabilities within software procurement criteria to manage operational cost exposure.
Market Restraints
- Legacy System Integration Costs:Air-gapped defense and critical infrastructure buyers face prohibitive capital requirements to bridge on-premise hardware with cloud-native platforms.
- Data Standardization Gaps:Incompatible API protocols between tank-level sensor manufacturers and ERP systems create persistent interoperability friction.
- Cybersecurity Liability Exposure:Real-time fuel monitoring systems introduce attack surfaces that municipal transport agencies struggle to insure against.
Strategic Opportunities
- Small Fleet Mobile-First Adoption:Maintenance workflow platforms targeting sub-100 vehicle operators remain underpenetrated relative to enterprise logistics corridors.
- AI-Driven Predictive Maintenance:Convergence of machine learning with GPS telemetry enables anticipatory fuel system diagnostics before component failure.
- DOT ELD Mandate Attach Rates:Electronic logging device compliance requirements create natural software bundling opportunities for fuel management modules.
Industry Challenges
- Embedded Systems Talent Scarcity:Fleet operators compete with automotive OEMs for firmware engineers capable of integrating heterogeneous sensor networks.
- Multi-Vendor Certification Timelines:Third-party API integrations require sequential security audits that extend deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Management Software Market |
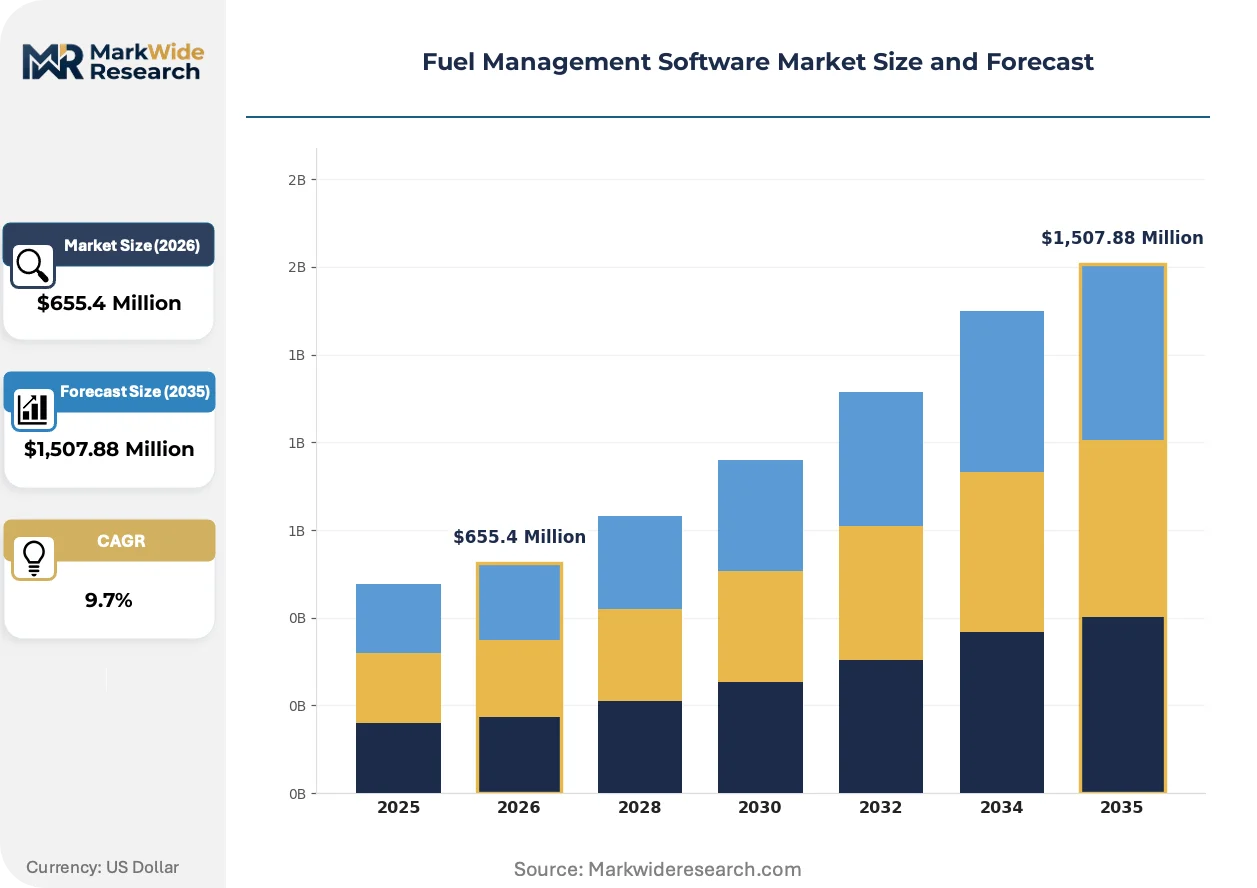
| Market Size in 2026 | $655.4 Million |
| Market Size in 2035 | $1,507.88 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Application: Fleet Management, Asset Tracking, Consumption Monitoring, Maintenance Scheduling End User Industry: Logistics, Construction, Mining, Agriculture License Model: Subscription, Perpetual, Freemium, Pay-Per-Use |
| Companies Covered | Fleetio, Masternaut, Samsara, Ampcontrol, Omnitracs, Geotab, Verizon Connect, Driivz, Motive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Management Software Market Shifts & Advancements
Edge computing architectures are redistributing data processing loads across distributed fleet assets, compressing latency for real-time fuel optimization decisions.
Containerized software delivery is modularizing fuel management platforms into interoperable microservices. Mid-size logistics operators now adopt discrete modules for route optimization, tank monitoring, and emissions reporting rather than monolithic suites. This architecture collapses integration timelines and permits selective capability upgrades without platform replacement.
The EPA's evolving emissions reporting thresholds for commercial vehicles are reshaping product requirement specifications. Software vendors must embed automated audit trails and tamper-evident data logging to satisfy enforcement documentation standards. Heavy-duty trucking fleets in the United States face the steepest compliance burden and are accelerating procurement of integrated fuel-emissions platforms.
Subscription pricing models are displacing perpetual licenses across fleet procurement departments. Operators prioritize predictable operational expenditure over capital-intensive on-premise deployments, particularly in municipal transport agencies with constrained IT infrastructure budgets. This preference shift concentrates most visibly in United States metropolitan transit authorities seeking automatic feature updates and cloud-resident data security.
Fuel Management Software Market Segmentation
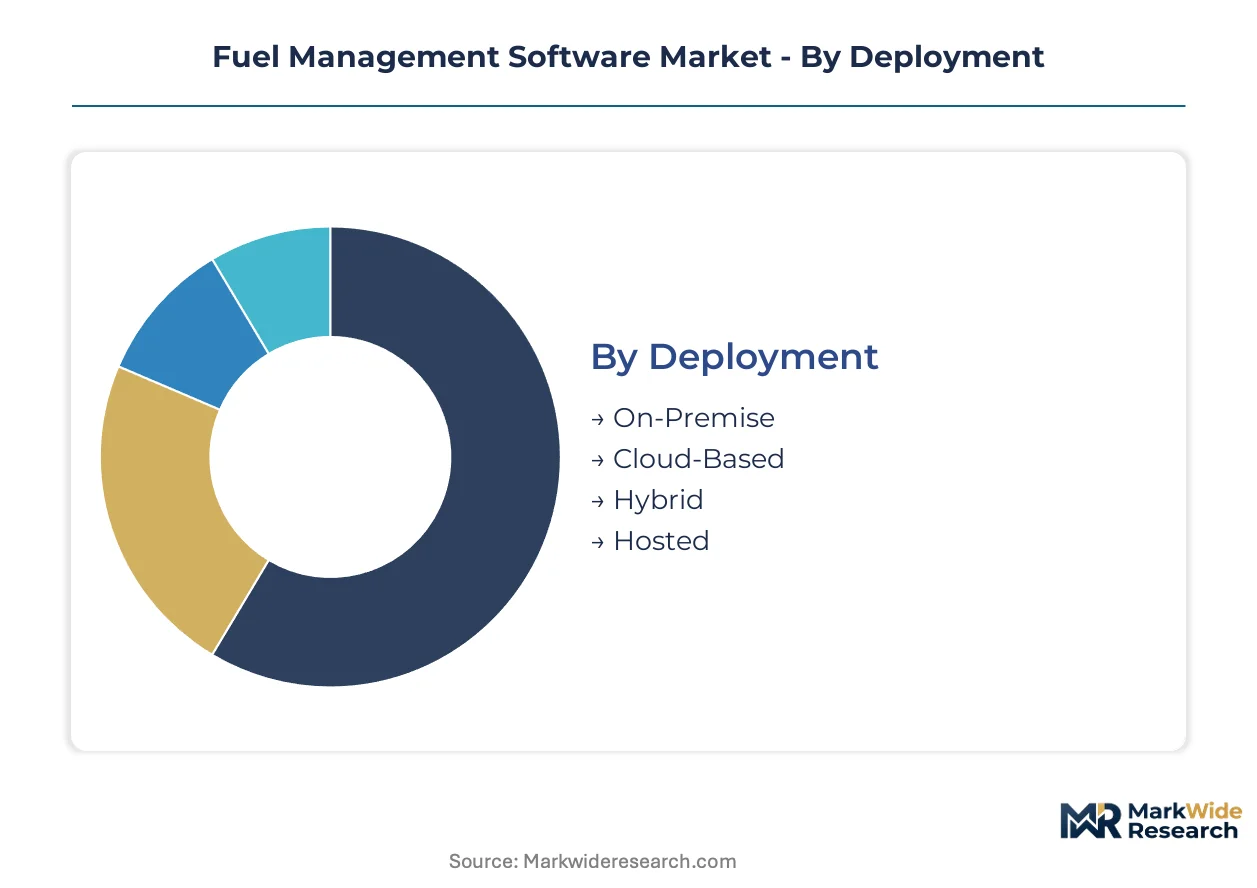
Fuel management software vendors architect pricing and capability tiers around deployment complexity and fleet scale. Segmentation reveals where cloud-native platforms displace legacy systems and which compliance burdens shape procurement priorities.
Deployment:
Volume deployments favor low-touch cloud delivery, while premium revenue concentrates in air-gapped installations for regulated infrastructure.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead for mid-size logistics operators. Municipal transit agencies across the United States prioritize automatic security patches and API extensibility over customization depth.
- On-Premise:Dedicated hardware installations serve defense contractors and critical energy infrastructure with strict data sovereignty requirements. Perpetual license economics appeal to capital-rich buyers insulating operations from subscription cost escalation.
- Hybrid:Split architectures process sensitive telemetry locally while pushing analytics workloads to cloud instances. Mining operators in remote geographies with intermittent connectivity deploy this model to maintain operational continuity.
- Hosted:Single-tenant managed services deliver dedicated virtual environments without customer-side infrastructure management. Construction fleet managers seeking compliance documentation without IT staffing burdens gravitate toward this intermediate option.
Mature deployment sits with On-Premise installations in defense and energy sectors. Newer deployment is concentrated in Cloud-Based platforms among sub-500 vehicle fleets.
Application:
Functional modules map directly to operational cost centers, with route efficiency and fuel theft prevention commanding the steepest pricing premiums.
- Fleet Management:Integrated platforms combining GPS telemetry, driver behavior scoring, and fuel consumption baselining dominate enterprise procurement. Long-haul trucking operators in the United States deploy these systems to satisfy DOT electronic logging mandates while optimizing diesel procurement timing.
- Consumption Monitoring:Real-time tank-level sensing and automated variance detection target fuel theft and leakage in distributed asset networks. Agricultural cooperatives with dispersed equipment fleets use these tools to reconcile bulk fuel deliveries against actual field consumption.
- Asset Tracking:Geofencing and utilization analytics prevent unauthorized equipment movement and idle-time waste. Construction rental yards deploy these capabilities to bill customers accurately for engine hours and fuel burn.
- Maintenance Scheduling:Predictive algorithms trigger service intervals based on fuel system performance degradation rather than fixed calendars. Smaller fleet operators lacking dedicated maintenance departments adopt these modules to prevent catastrophic fuel injection failures.
Procurement concentrates on Fleet Management for regulatory compliance integration. Consumption Monitoring is climbing fastest as fuel price volatility intensifies theft prevention priorities.
End User Industry:
Industry verticals exhibit divergent sensor density requirements and regulatory exposure profiles that reshape platform configuration priorities.
- Logistics:High-frequency telematics integration across interstate corridors demands millisecond-latency data pipelines. EPA emissions reporting requirements for Class 8 vehicles drive software procurement at the largest trucking fleets.
- Mining:Harsh-environment sensor durability and offline operation capability dominate technical specifications. Open-pit operators in remote locations prioritize fuel reconciliation accuracy over real-time cloud connectivity.
- Construction:Project-based equipment utilization and fragmented fleet ownership complicate centralized fuel accounting. Rental fleet managers seek modular deployments that scale with contract duration rather than enterprise commitments.
- Agriculture:Seasonal demand spikes and rural connectivity constraints favor lightweight mobile interfaces over desktop-heavy analytics. Cooperative fuel purchasing agreements require software capable of allocating bulk deliveries across member farms.
Revenue concentration aligns with Logistics procurement scale. Agricultural adoption represents the most underpenetrated vertical relative to total diesel consumption.
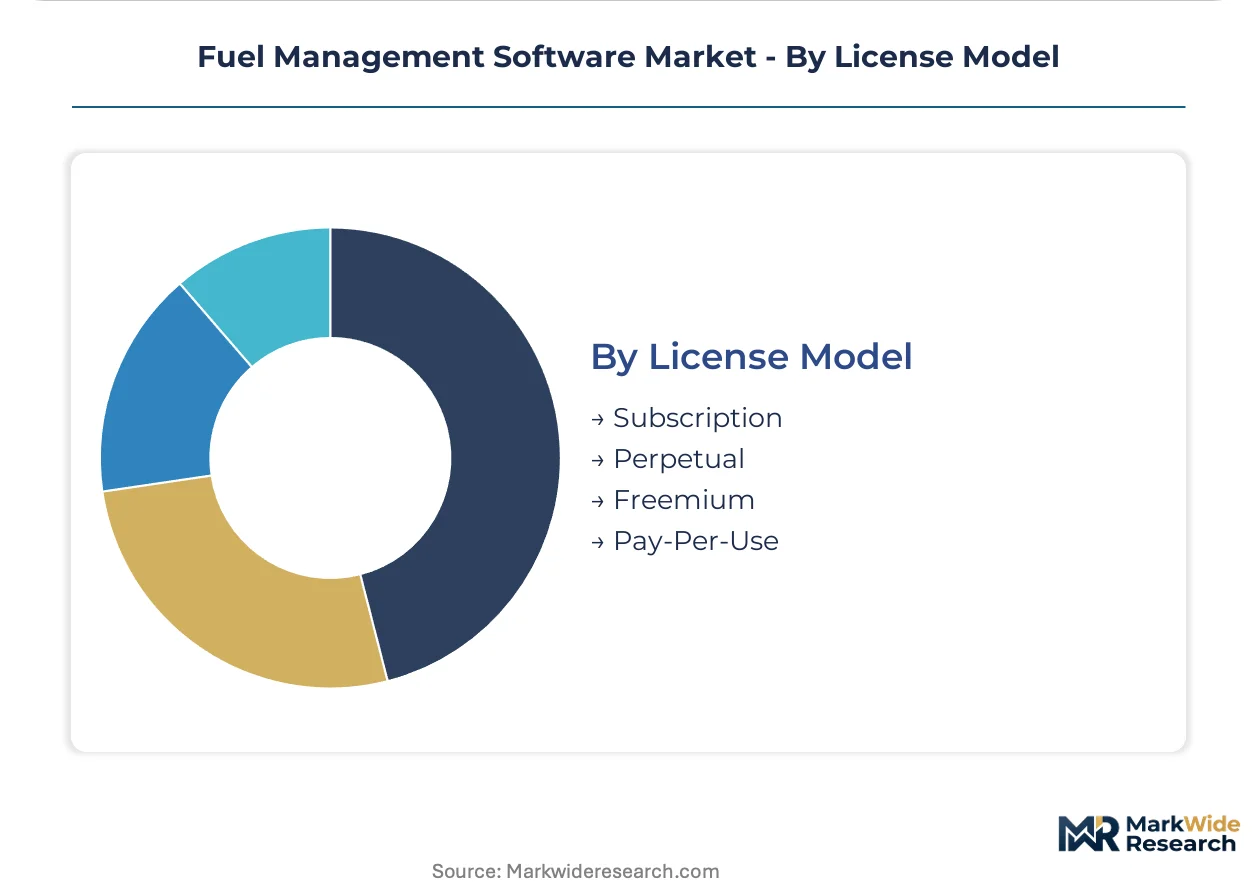
License Model:
Payment structure preferences split along capital availability and procurement flexibility requirements, with municipal buyers exhibiting distinct constraints.
- Subscription:Predictable monthly or annual fees convert capital expenditure to operational budgets, accelerating approval cycles. United States metropolitan transit authorities favor this model to circumvent municipal bond issuance delays for IT infrastructure.
- Perpetual:One-time license purchases with separate maintenance contracts appeal to buyers with depreciation-focused accounting practices. Defense procurement frameworks often mandate this structure for multi-year program stability.
- Freemium:Core functionality at no cost with tiered upgrades for advanced analytics or additional vehicle seats. Independent owner-operators with single-digit fleet sizes represent the primary adoption cohort.
- Pay-Per-Use:Consumption-based pricing tied to actual fuel volume managed or transactions processed. Seasonal agricultural operators and project-based construction firms minimize fixed cost exposure through this structure.
Subscription terms dominate new customer acquisition. Pay-Per-Use experimentation is expanding most quickly among asset-light fleet operators seeking variable cost alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale trucking fleets and municipal transport agencies in the United States drive the majority of software procurement volume. Cloud-native deployment concentrates in logistics corridors with dense telematics infrastructure. Regulatory enforcement varies significantly by jurisdiction, shaping local compliance technology requirements.
United States
Class 8 vehicle operators across interstate corridors generate sustained demand for integrated fuel-emissions platforms. The EPA enforces evolving emissions reporting thresholds that mandate automated audit trails and tamper-evident data logging. Metropolitan transit authorities in Chicago, Los Angeles, and New York accelerate cloud procurement to circumvent municipal bond delays.
Germany
Commercial vehicle fleets exceeding defined weight classes face intensifying pressure to optimize diesel consumption amid price volatility. The KBA enforces type-approval standards that shape telematics integration requirements for cross-border logistics operators. Industrial clusters in North Rhine-Westphalia and Bavaria anchor procurement of predictive analytics engines for route efficiency.
United Kingdom
Logistics operators prioritize fuel hedging capabilities within software procurement criteria to manage operational cost exposure. The Driver and Vehicle Standards Agency maintains compliance frameworks that influence electronic logging device specifications. Fleet managers in the Midlands and Greater London concentrate adoption of mobile-first maintenance workflows for sub-100 vehicle operations.
China
Remote mining operators in harsh-environment geographies demand fuel reconciliation accuracy over real-time cloud connectivity. The Ministry of Ecology and Environment enforces dual carbon goals that reshape emissions monitoring requirements for commercial transport. Yangtze River Delta logistics hubs drive edge computing adoption to compress latency for distributed fleet assets.
India
Agricultural cooperatives with dispersed equipment fleets seek lightweight mobile interfaces to reconcile bulk fuel deliveries against field consumption. The Central Electricity Authority influences standards for IoT sensor networks in rural connectivity-constrained environments. Fleet operators in Maharashtra and Gujarat experiment with pay-per-use pricing to align software costs with seasonal demand spikes.
Fuel Management Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge API interoperability gaps and accelerate third-party integration density. The vendor base organizes around three distinct tiers: IoT-native platforms with real-time telematics architectures, open-platform specialists sustaining integration ecosystems, and mobile-first workflow providers targeting underserved small-fleet segments. Competitive positioning depends on cloud infrastructure economics collapsing deployment barriers for mid-size operators. M&A activity concentrates on sensor network capabilities and predictive analytics engines.
Within the IoT-native tier, Samsara and Geotab exemplify divergent approaches to platform architecture. Samsara anchors real-time telemetry deployment across North American logistics corridors through vertically integrated hardware-software stacks. Geotab occupies a position emphasizing open-platform APIs that sustain third-party integration density. Fleetio represents the mobile-first archetype, targeting maintenance workflow automation for smaller fleet segments with constrained IT infrastructure.
| Leading Market Players |
|---|
| Fleetio |
| Masternaut |
| Samsara |
| Ampcontrol |
| Omnitracs |
| Geotab |
| Verizon Connect |
| Driivz |
| Motive |
| Others |
Supply & Pricing Matrix
Embedded systems firmware engineers concentrated in Silicon Valley and Austin command compensation premiums that compress margins for mid-tier SaaS vendors while widening the spread between premium IoT-native platforms and economy-tier maintenance modules. Labor-cost differentials between North American development hubs and Eastern European engineering centers directly shape three-tier pricing stratification across cloud-native deployments.
Pricing Analysis
Volume deployments favor subscription SaaS tiers with per-vehicle monthly fees, while margin concentration sits with perpetual-license on-premise installations for defense buyers. Price differentiation rests on API integration density and tamper-evident compliance certification grade. Pricing pressure stems from municipal transit agencies demanding predictable operational expenditure conversion. Small-fleet owner-operators exhibit highest price sensitivity; critical infrastructure buyers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries producing GPS telemetry chipsets. Hardware component sourcing draws from China, Mexico, and Germany for sensor assembly. Raw material dependencies include lithium-ion battery cells, RF transceivers, and industrial-grade enclosure polymers. Tariff exposure on Chinese electronics components poses structural risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EPA emissions enforcement raises compliance barriers beyond bootstrap-capable development teams. Smaller vendors lacking automated audit-trail capabilities face forced exit or acquisition.
For Market Incumbents: Deploy API ecosystem expansion to lock in third-party integration density. Samsara and Geotab demonstrate defensive moat construction through open-platform architectures that increase customer switching costs. Counter emerging mobile-first entrants by acquiring predictive analytics engines. Channel control through direct sales investment in municipal transit corridors anchors enterprise retention.
For New Entrants and Emerging Players: Launch via freemium mobile-first workflows targeting agricultural cooperatives with sub-100 vehicle fleets. White-space concentration sits with seasonal operators in India and Brazil seeking pay-per-use pricing alignment. Underpenetrated maintenance scheduling modules for construction rental yards offer lowest competitive density. Go-to-market leverage through cooperative fuel-purchasing consortiums bypasses direct enterprise sales friction.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing embedded sensor firmware capabilities given IoT-talent scarcity. Long-term viability favors platforms with DOT ELD mandate bundling attach rates. Acquisition target archetype: predictive maintenance engines with machine-learning telemetry convergence. Watch EPA enforcement threshold expansion as inflection signal for compliance-module demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API density locks in logistics operators across North American interstate corridors. |
| Acquisition of Specialist Firm | Predictive analytics engines compress maintenance cost exposure for fleet managers. |
| Strategic Partnership | Tank-level sensor manufacturers bridge data standardization gaps through co-development. |
| Geographic Expansion | Edge computing deployment targets Yangtze River Delta logistics latency requirements. |
| Product Launch | AI-driven fuel theft detection addresses agricultural cooperative reconciliation pain points. |
Research Methodology
Multi-period observation of EPA regulatory threshold evolution and diesel price volatility anchored the trend analysis, supplemented by interviews with fleet operations directors, municipal transit procurement officers, IoT platform engineers, and fuel systems maintenance managers. Secondary validation drew from EPA enforcement documentation, DOT ELD mandate compliance filings, SEC 10-K disclosures from logistics operators, and hyperscaler cloud infrastructure capex reports. Bottom-up triangulation across deployment model adoption curves converged with top-down macroeconomic scenario weighting.
Segment-weighting applied deployment complexity tiers, fleet scale brackets, and vertical regulatory exposure profiles across the projection horizon. Modeled dimensions included cloud-native versus on-premise architecture, vehicle count strata, end-use industry sensor density requirements, and regional compliance framework stringency. CAGRs derived from logistic growth curve fitting with technology adoption S-curve inflection points. Forecast inputs incorporated telematics infrastructure penetration rates and municipal IT budget cycle timing.
EPA enforcement acceleration, diesel price shock magnitude, and embedded systems talent availability are the dominant revision risks warranting scenario-band expansion. Forecasts reflect documented assumptions about regulatory timeline adherence and cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Hiking Apps Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Poland ICT Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Load Balancer Market