
 Digital Fitness Apps Market | 2026-2036
Digital Fitness Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fitness Apps Market Outlook
The divergence between premium subscription tiers and freemium commodity offerings is repositioning how developers allocate engineering resources and user acquisition spending. Apple Inc. leverages its wearable ecosystem to anchor premium health data integration across hardware-software boundaries. Nike Inc. competes through brand-driven content exclusivity rather than utility-first feature expansion. Under Armour, Inc. navigates a narrower position by specializing in performance analytics for competitive athletes.
Digital fitness apps are software platforms that capture biometric signals, motion data, and nutritional inputs through smartphone sensors, wearable peripherals, or manual entry, then apply algorithmic processing to generate personalized training prescriptions and progress visualizations. The platform dimension spans iOS, Android, Web, and Wearable Devices, with wearable-native architectures commanding superior engagement metrics due to continuous passive monitoring capabilities. Within application types, Live Classes and Virtual Coaching concentrate margin pools through instructor-led network effects, while Workout Tracking remains the highest-volume entry point. The monetization model landscape shows Subscription-Based revenue dominating sustainable cash flows, though Freemium conversion efficiency varies sharply by geography and age cohort.
FDA oversight of software-as-medical-device classifications in the United States, HIPAA privacy rule enforcement, and GDPR health data provisions in Europe collectively raise compliance costs while creating barriers against low-integrity entrants. The EU AI Act introduces additional algorithmic transparency obligations for automated coaching recommendations that process sensitive health categories. Stakeholders must monitor whether emerging interoperability mandates from national health systems will force open data architectures or reinforce proprietary walled gardens.
Market Dynamics
Algorithmic coaching engines are restructuring competitive advantage around proprietary biometric datasets rather than content libraries, forcing developers to choose between hardware-integrated data moats and platform-agnostic distribution scale.
Growth Catalysts
- Employer-Sponsored Wellness Mandates:Corporate health initiatives in the United States are embedding fitness apps into benefits packages, creating captive user bases with subsidized subscription models.
- Wearable-Native Architectures:Continuous passive monitoring through Apple Watch and Android Wear devices is generating higher engagement metrics than smartphone-only experiences.
- GDPR and HIPAA Compliance Frameworks:European and American data protection rules are filtering out low-integrity competitors while elevating platforms with certified privacy infrastructure.
Market Restraints
- Input Cost Volatility:Cloud compute and API access fees for real-time biometric processing are compressing margins for mid-tier subscription providers.
- Regulatory Friction:The EU AI Act's algorithmic transparency obligations for automated health recommendations are extending product development timelines by months.
- Technical Limitation:Optical heart rate sensors in consumer wearables lack clinical-grade precision, limiting expansion into medical-adjacent coaching claims.
Strategic Opportunities
- Underpenetrated Geography:Germany's statutory health insurance reimbursement experiments are opening B2B2C channels unavailable in purely private-pay markets.
- Technology Convergence:Integration of generative AI with motion-capture cameras is enabling real-time form correction without human instructors.
- Regulatory Tailwind:China's dual carbon goals are accelerating government-backed fitness initiatives that favor domestic app platforms with localized data storage.
Industry Challenges
- Certification Timeline Compression:FDA software-as-medical-device classifications require clinical validation studies that delay feature releases by quarters.
- Integration Complexity:Legacy electronic health record systems in hospital networks resist API interoperability, fragmenting user data across disconnected platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fitness Apps Market |
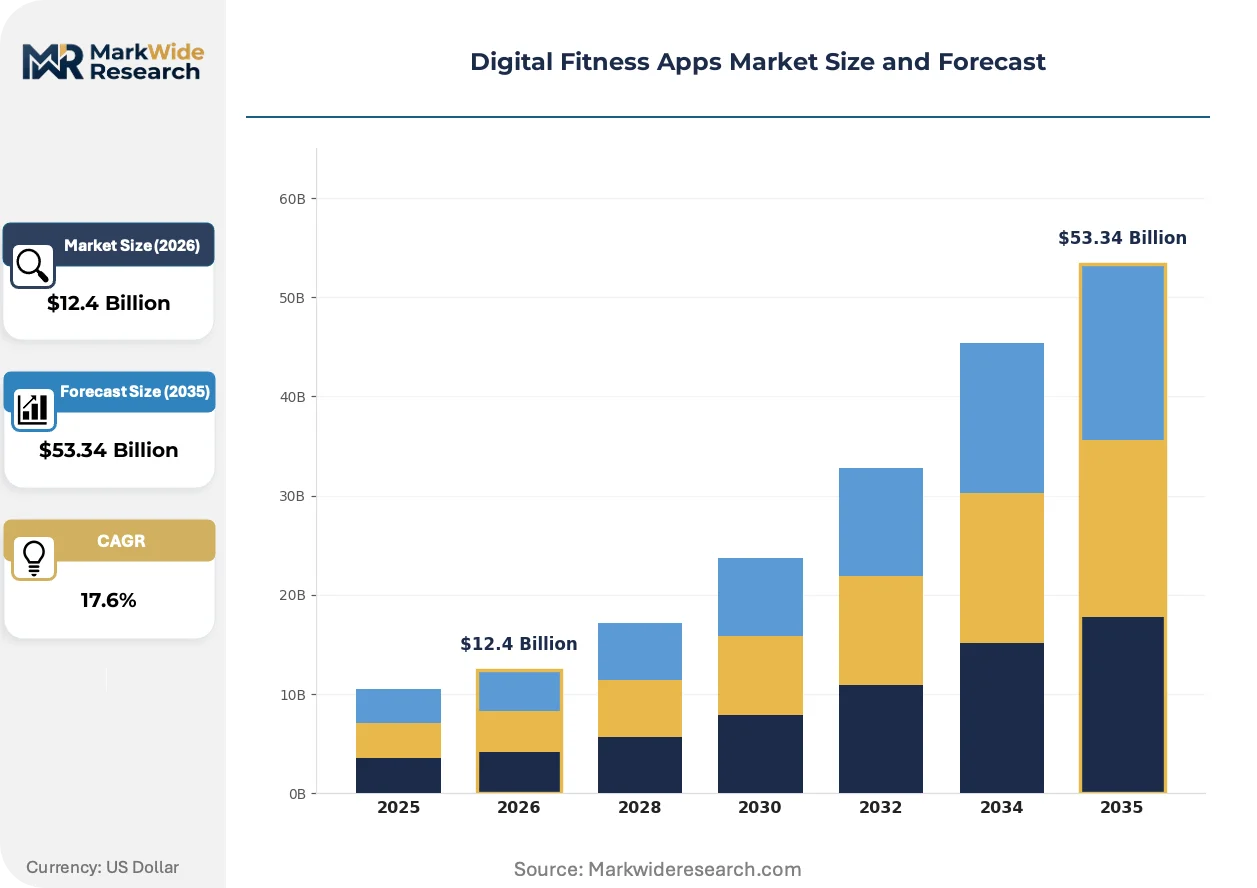
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $53.34 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Workout Tracking, Nutrition Guidance, Live Classes, Virtual Coaching Platform: iOS, Android, Web, Wearable Devices End User: Fitness Enthusiasts, Weight Loss Seekers, Athletes, Senior Citizens Monetization Model: Subscription-Based, Freemium, One-Time Purchase, Advertising |
| Companies Covered | Apple Inc., Alphabet Inc., Fitbit LLC, Nike Inc., Adidas AG, Samsung Electronics Co., Ltd., Under Armour, Inc., MyFitnessPal, Inc., Peloton Interactive, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fitness Apps Market Strategic Shifts
Passive biometric monitoring is displacing active manual logging as the primary data capture method, while regulatory pressure on algorithmic decision-making is forcing transparency into previously opaque coaching engines.
Generative AI is overtaking scripted workout libraries as the dominant content production method. Fitness platforms are deploying large language models to synthesize personalized training blocks from real-time recovery metrics. Boutique studio chains and elite athlete coaching services are adopting these tools fastest. The technology is overtaking the economics of human instructor networks that previously anchored premium pricing tiers.
The EU AI Act's risk classification system for health-related algorithmic recommendations is forcing developers to document training data provenance and decision logic. This industrial consequence is elevating compliance costs for automated coaching features. Live class platforms with human instructors face lighter algorithmic scrutiny and are responding by emphasizing instructor-led network effects over AI-generated personalization.
Subscription bundling through telecom and insurance channels is displacing direct-to-consumer acquisition as the dominant growth engine. Fitness apps are integrating into Verizon and UnitedHealthcare benefit portals, capturing users at enrollment moments rather than through app store discovery. This channel shift is most visible in the United States, where employer-sponsored health initiatives dominate B2B distribution.
Digital Fitness Apps Market Segmentation
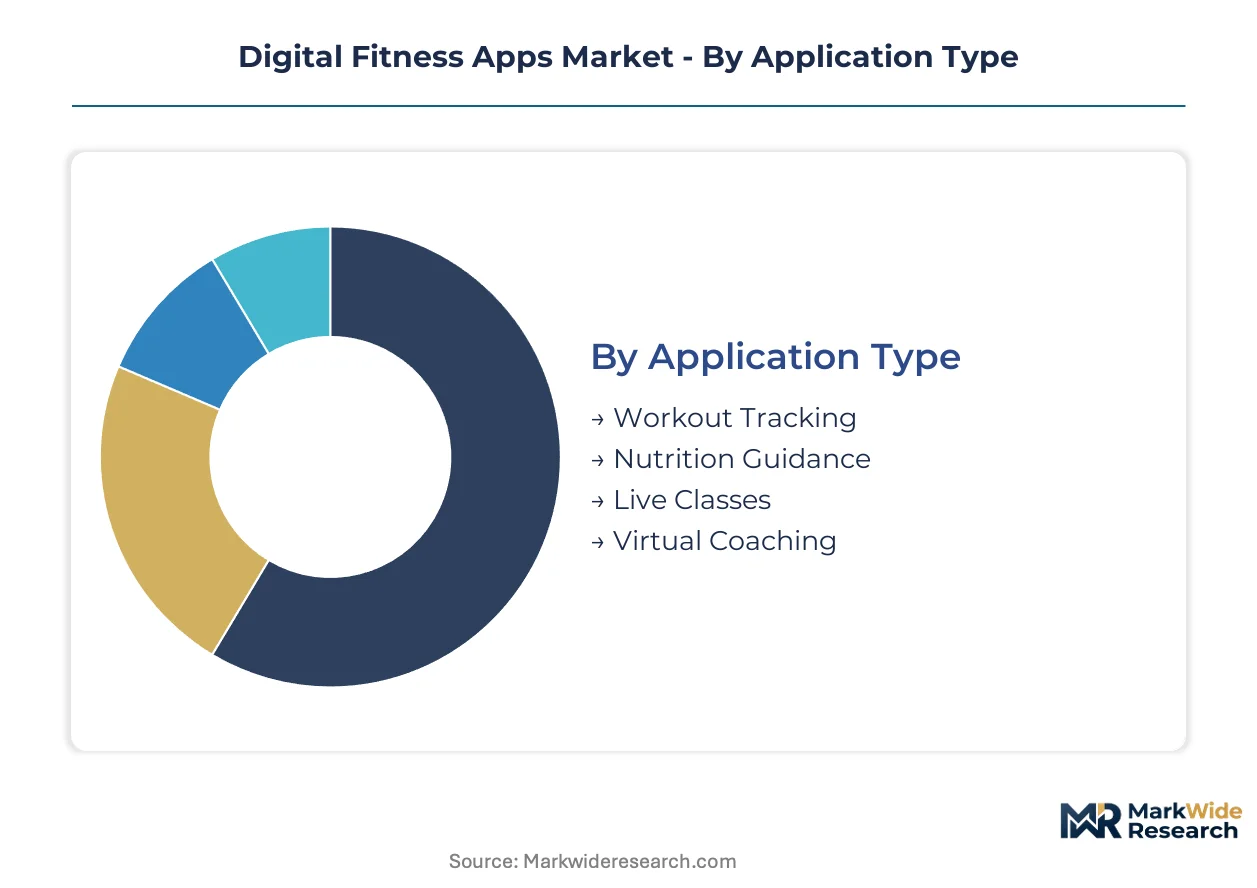
Segmentation in digital fitness apps determines which compliance frameworks apply and where engineering investments yield differential returns. Application architecture and platform choice dictate FDA software-as-medical-device exposure, while monetization models shape data handling obligations under HIPAA and GDPR.
Application Type:
Certification burden varies sharply: Virtual Coaching triggers FDA oversight when algorithms generate personalized health recommendations, while Workout Tracking faces lighter scrutiny as passive data logging.
- Workout Tracking:Captures motion data, heart rate variability, and GPS routes through smartphone sensors or wearables, then visualizes progress through dashboards and trend analytics. Demand concentrates among recreational runners and cyclists in the United States, where Strava and Apple Fitness integrations dominate, though optical sensor limitations constrain medical-adjacent claims. Growing fastest: expanding into recovery metrics and sleep staging.
- Live Classes:Streams instructor-led sessions with real-time biometric feedback, generating network effects through scheduled community participation. Boutique studio chains in Germany and the United Kingdom anchor demand, with employer-sponsored wellness programs subsidizing corporate subscriptions. Leading the category by volume.
- Nutrition Guidance:Logs caloric intake and macronutrient balance through barcode scanning or manual entry, applying algorithmic meal planning. Weight loss seekers in China drive adoption, with SAMR data localization requirements adding compliance overhead.
- Virtual Coaching:Deploys generative AI to synthesize adaptive training blocks from recovery biomarkers and performance history. Athletes and competitive amateurs in the United States pay premium subscriptions, though EU AI Act algorithmic transparency obligations extend development timelines.
Leading the category by volume: Workout Tracking. Growing fastest: Virtual Coaching.
Platform:
Cost tier stratification follows hardware integration depth: Wearable Devices command premium engineering spend for continuous passive monitoring, while Web platforms compete on lowest acquisition cost.
- Wearable Devices:Apple Watch and Android Wear architectures enable continuous heart rate, blood oxygen, and temperature monitoring without user initiation. Engagement metrics exceed smartphone-only experiences by multiples, with FDA 510(k) pathways required for clinical-grade feature claims. Leading the category by volume.
- iOS:Leverages Apple's HealthKit ecosystem for standardized biometric data exchange and premium subscriber demographics. Developers face App Store commission structures but gain access to affluent user bases concentrated in the United States, Japan, and Australia. Climbing the fastest in revenue per user.
- Android:Offers broader geographic distribution and hardware diversity, though fragmentation across device manufacturers complicates sensor calibration. India's price-sensitive market and China's domestic OEM ecosystem anchor volume.
- Web:Delivers browser-based access without app store dependencies, minimizing platform fees but sacrificing push notification engagement and sensor-native features. Corporate wellness dashboards and employer administrative portals represent primary use cases.
Dominant by installed base: Android. Premium revenue concentration: iOS and Wearable Devices.
End User:
Customer maturity determines feature complexity tolerance and subscription lifetime value, with Athletes accepting steeper learning curves for performance analytics.
- Fitness Enthusiasts:Regular exercisers seeking structured progression and community features, representing the broadest addressable base. United States and German markets show highest subscription conversion rates.
- Weight Loss Seekers:Users prioritizing caloric deficit tracking and behavioral nudges, with high churn risk after initial goal achievement. Nutrition Guidance bundling improves retention.
- Athletes:Competitive and elite amateurs demanding periodization, load management, and recovery optimization. Performance analytics integration with TrainingPeaks and WHOOP ecosystems commands premium pricing. Steepest expansion trajectory.
- Senior Citizens:Growing segment requiring simplified interfaces, fall detection, and medication adherence features. Medicare Advantage plans in the United States are piloting reimbursement for clinically validated apps.
Largest subscriber base: Fitness Enthusiasts. Fastest-growing demographic: Senior Citizens.
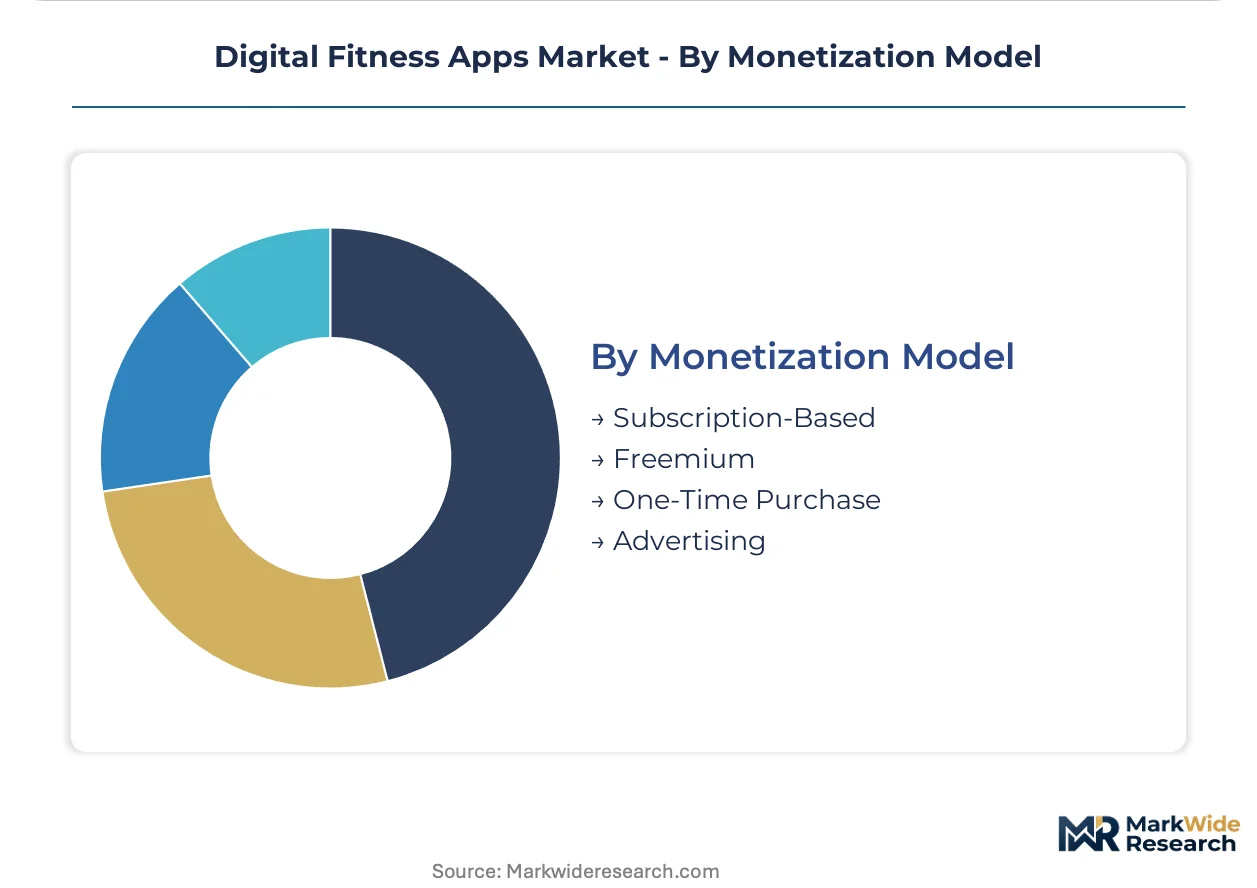
Monetization Model:
Margin structure separates sustainable cash flow generators from acquisition-dependent experiments, with Subscription-Based models funding compliance infrastructure that Freemium competitors cannot afford.
- Subscription-Based:Recurring monthly or annual fees unlock full feature sets, generating predictable revenue for biometric processing infrastructure and content licensing. Employer-sponsored wellness mandates in the United States and statutory insurance experiments in Germany expand B2B2C distribution. Dominant revenue model.
- Freemium:Basic functionality at no cost with premium tiers for advanced analytics or live classes. Conversion efficiency varies sharply by geography and age cohort, with younger users in India and Southeast Asia showing resistance to paid upgrades.
- One-Time Purchase:Perpetual licenses for standalone workout programs or equipment-integrated software. Boutique studio chains and specialty hardware vendors favor this model to avoid ongoing platform dependencies.
- Advertising:Data-monetization through targeted placement, increasingly constrained by GDPR and CCPA consent requirements. Health data sensitivity limits advertiser appetite relative to general lifestyle apps.
Highest revenue concentration: Subscription-Based. Most challenged by privacy regulation: Advertising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the global digital fitness app ecosystem, hosting the densest concentration of venture-backed health technology startups and wearable-native platform developers. Employer-sponsored wellness mandates and FDA software-as-medical-device pathways concentrate engineering talent along the US West Coast.
United States
Corporate benefits packages subsidize fitness app subscriptions through UnitedHealthcare and Verizon distribution channels. FDA 510(k) clearance requirements for clinical-grade features extend development timelines for biometric coaching algorithms. Medicare Advantage pilots in Florida and Arizona are testing reimbursement for fall-detection and medication-adherence apps targeting senior citizens.
Germany
Statutory health insurance experiments in Bavaria and North Rhine-Westphalia are opening B2B2C reimbursement channels unavailable in private-pay markets. GDPR health data provisions and EU AI Act algorithmic transparency obligations elevate compliance costs for automated coaching features. Berlin's startup cluster specializes in live-class platforms with human instructors to avoid heavier algorithmic scrutiny.
China
Government-backed fitness initiatives under dual carbon goals favor domestic platforms with localized data storage compliant with SAMR requirements. Shenzhen and Hangzhou hardware ecosystems supply optical sensors and motion-capture components for wearable-native architectures. Nutrition guidance apps face heightened data localization overhead for caloric logging and biometric processing.
United Kingdom
Boutique studio chains in London anchor demand for live-class subscriptions with real-time biometric feedback. NHS interoperability mandates are forcing API standardization that could fragment user data across hospital networks and consumer fitness platforms. Manchester and Birmingham corporate wellness programs are expanding employer-sponsored app adoption.
Japan
Aging demographics drive demand for simplified interfaces and fall-detection features among senior citizens in Tokyo and Osaka metropolitan areas. METI guidelines on health data portability are pressuring proprietary walled gardens toward open architectures. Corporate wellness mandates remain underdeveloped compared to US and German markets, limiting B2B channel penetration.
Digital Fitness Apps Market Competitive Environment
Premium-margin players sit above commodity-margin players across data integration depth and hardware-software ecosystem control. The market structure consolidates around wearable-native architectures that command superior engagement metrics through continuous passive monitoring. Three archetypes dominate: technology conglomerates with captive hardware ecosystems, sportswear brands leveraging content exclusivity, and specialized analytics platforms for competitive athletes. Dominant competitive moves include strategic partnerships with telecom and insurance channels for subscription bundling, and backward integration into sensor hardware to secure biometric data moats.
Within the technology conglomerate tier, Apple Inc. and Alphabet Inc. occupy positions defined by wearable-native platform control and health data ecosystem integration. Samsung Electronics Co., Ltd. anchors the hardware-integrated archetype through Android Wear distribution scale. Among sportswear specialists, Nike Inc. and Adidas AG exemplify brand-driven content strategies that compete through exclusivity rather than utility-first feature expansion. Under Armour, Inc. sits within the performance analytics niche, serving competitive athletes with periodization and load management tools.
| Leading Market Players |
|---|
| Apple Inc. |
| Alphabet Inc. |
| Fitbit LLC |
| Nike Inc. |
| Adidas AG |
| Samsung Electronics Co., Ltd. |
| Under Armour, Inc. |
| MyFitnessPal, Inc. |
| Peloton Interactive, Inc. |
| Others |
Value Chain & Pricing Dynamics
Venture-backed platform developers concentrated in San Francisco and Shenzhen anchor pricing discipline through recurring subscription architectures that amortize cloud infrastructure costs across captive user bases. Their ownership structure prioritizes lifetime value metrics over transactional margin extraction, compressing price points for mid-tier entrants while sustaining premium tiers through hardware-integrated data moats.
Pricing Analysis
Outcome-based pricing anchored to engagement metrics and biometric-derived health outcomes dominates sustainable revenue models. Three-tier pricing structure across premium, standard, and economy levels separates wearable-native platforms with FDA 510(k) pathways from smartphone-only utilities and freemium commodity offerings. Cost compression in the mid-tier subscription band is intensifying because cloud compute and API access fees for real-time biometric processing are eroding margins. Fitness enthusiasts in the United States and Germany show lowest price sensitivity, while weight loss seekers in India and Southeast Asia resist paid upgrades most acutely.
Supply Chain Analysis
China's SAMR data localization mandates and India's domestic-content preferences for government-backed fitness initiatives are reshaping sourcing toward localized server infrastructure and regional cloud providers. Hardware component supply draws from Shenzhen and Hangzhou for optical sensors, Taiwan for semiconductor fabrication, and South Korea for display panels. Single-source vulnerability concentrates in advanced biometric sensor modules where Apple and Samsung maintain captive supply arrangements. Distribution runs through telecom and insurance bundling channels that capture users at employer enrollment moments rather than app store discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Fitness Apps Market operates as a cost-of-compliance story where GDPR health data provisions and EU AI Act algorithmic transparency obligations erect barrier-to-entry moats that filter out low-integrity competitors and elevate platforms with certified privacy infrastructure.
For Market Incumbents: Cement hardware-integrated data moats through backward integration into sensor calibration and proprietary biometric algorithm development. Expand certification investment for FDA 510(k) and EU MDR software-as-medical-device pathways to delay feature releases by competitors lacking clinical validation infrastructure. Priority lever rests on channel control through exclusive telecom and insurance bundling agreements that lock in employer-sponsored wellness mandates. For New Entrants and Emerging Players: Begin with underpenetrated B2B2C reimbursement channels in Germany's statutory health insurance experiments, where statutory frameworks subsidize subscription costs unavailable in private-pay markets. Target senior citizens in United States Medicare Advantage pilot regions as the most penetrable demographic, deploying simplified interfaces and fall-detection features. Go-to-market angle centers on clinical validation partnerships with hospital networks seeking API interoperability for fragmented electronic health record systems. For Investors and Strategic Acquirers: FDA 510(k) clearance announcements for algorithmic coaching features are the leading indicator that a platform has crossed the compliance threshold toward sustainable competitive positioning. Long-term viability frames around five-to-ten year windows where regulatory friction accelerates consolidation toward vertically integrated hardware-software ecosystems. Acquisition target archetype includes specialized analytics platforms for competitive athletes with periodization tools and TrainingPeaks integration capabilities. Signal to watch: employer-sponsored wellness mandates expanding beyond United States into European statutory reimbursement experiments.| Strategic Initiative | Industry Significance |
|---|---|
| Wearable-Native Platform Integration | Apple Watch and Android Wear ecosystems command superior engagement through continuous passive monitoring capabilities. |
| Regulatory Certification Investment | FDA 510(k) and EU MDR pathways for software-as-medical-device classifications filter out low-integrity competitors. |
| Telecom and Insurance Bundling Partnership | UnitedHealthcare and Verizon distribution channels capture users at enrollment moments rather than app store discovery. |
| Generative AI Content Development | Large language models synthesize personalized training blocks from recovery biomarkers, displacing human instructor networks. |
| Geographic Expansion into Reimbursement Markets | Germany's statutory health insurance experiments open B2B2C channels unavailable in purely private-pay markets. |
Study Parameters
Independent corroboration across app store intelligence platforms, wearable device shipment disclosures, and employer benefits administration data underwrites the qualitative findings in this study. Primary interviews with fitness app product managers, wearable platform engineers, corporate wellness benefits directors, and health insurance channel partners combined with secondary validation from SEC filings, App Annie/Sensor Tower metrics, hyperscaler capex disclosures, and FDA 510(k) clearance databases. Bottom-up and top-down triangulation reconciles user acquisition costs with subscription revenue projections across monetization models.
Comparable-period anchoring to historical engagement metric baselines and biometric data processing cost trajectories structured the forecast window across the analysis window. Segmentation dimensions modeled include application type, platform architecture, end user maturity, and monetization model, with additional weighting for regulatory compliance tier and hardware integration depth. CAGRs derived from fitted growth curves incorporating wearable device adoption rates, employer-sponsored wellness mandate expansion, and cloud infrastructure cost deflation assumptions.
Underlying measurement precision varies by segment; subscription-based revenue models carry tighter precision than advertising-dependent freemium conversion estimates. Forecasts reflect assumptions around regulatory timeline compression for EU AI Act compliance and FDA software-as-medical-device classification pathways, with biometric sensor accuracy limitations and data localization mandate evolution representing specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Digital Clothing Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
API Management Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Data Classification Tool Market