
 Customer Experience As a Service (Cxaas) Market | 2026-2036
Customer Experience As a Service (Cxaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Experience As a Service (Cxaas) Market Analysis
The capital-intensity divergence between hyperscale cloud infrastructure and lightweight API-first platforms is bifurcating competitive dynamics in CXaaS delivery. Oracle Corporation leverages its database-to-application stack to sustain integrated customer data environments across enterprise clients. NICE anchors its position through specialized workforce optimization tools that dominate compliance-sensitive verticals. Zendesk competes by extending modular ticketing architectures that occupy the mid-market segment with rapid deployment cycles.
Customer Experience As a Service (CXaaS) denotes the outsourced delivery of end-to-end customer engagement capabilities through subscription-based cloud platforms, encompassing real-time sentiment analysis, omnichannel routing engines, and predictive next-best-action algorithms that process interaction data at sub-second latency. Its primary commercial purpose is to replace fragmented in-house support stacks with unified, scalable service layers that reduce cost-to-serve while improving resolution rates and lifetime value metrics. Cloud-based deployment leads structural momentum as enterprises abandon on-premises contact center hardware for elastic consumption models with faster iteration cycles. AI-Powered Chatbots within the technology dimension represent the fastest-growing capability segment, though margin pools remain concentrated in managed services bundles that bundle implementation, training, and ongoing optimization. Multichannel support maintains mature, high-volume status but faces compression as analytics-driven personalization layers command premium pricing.
The EU AI Act and GDPR jointly constrain automated profiling and cross-border data flows in European CXaaS implementations, compelling providers to engineer transparent algorithmic audit trails and region-locked processing nodes. In the United States, HIPAA and state-level biometric privacy laws impose sector-specific guardrails on healthcare and voice-data applications, fragmenting compliance requirements across deployments. China's SAMR and GB standards around algorithmic recommendation systems add a third regulatory vector that shapes product architecture for multinational vendors. Stakeholders must monitor evolving algorithmic accountability frameworks and decide whether to architect modular compliance engines or pursue geography-specific product forks.
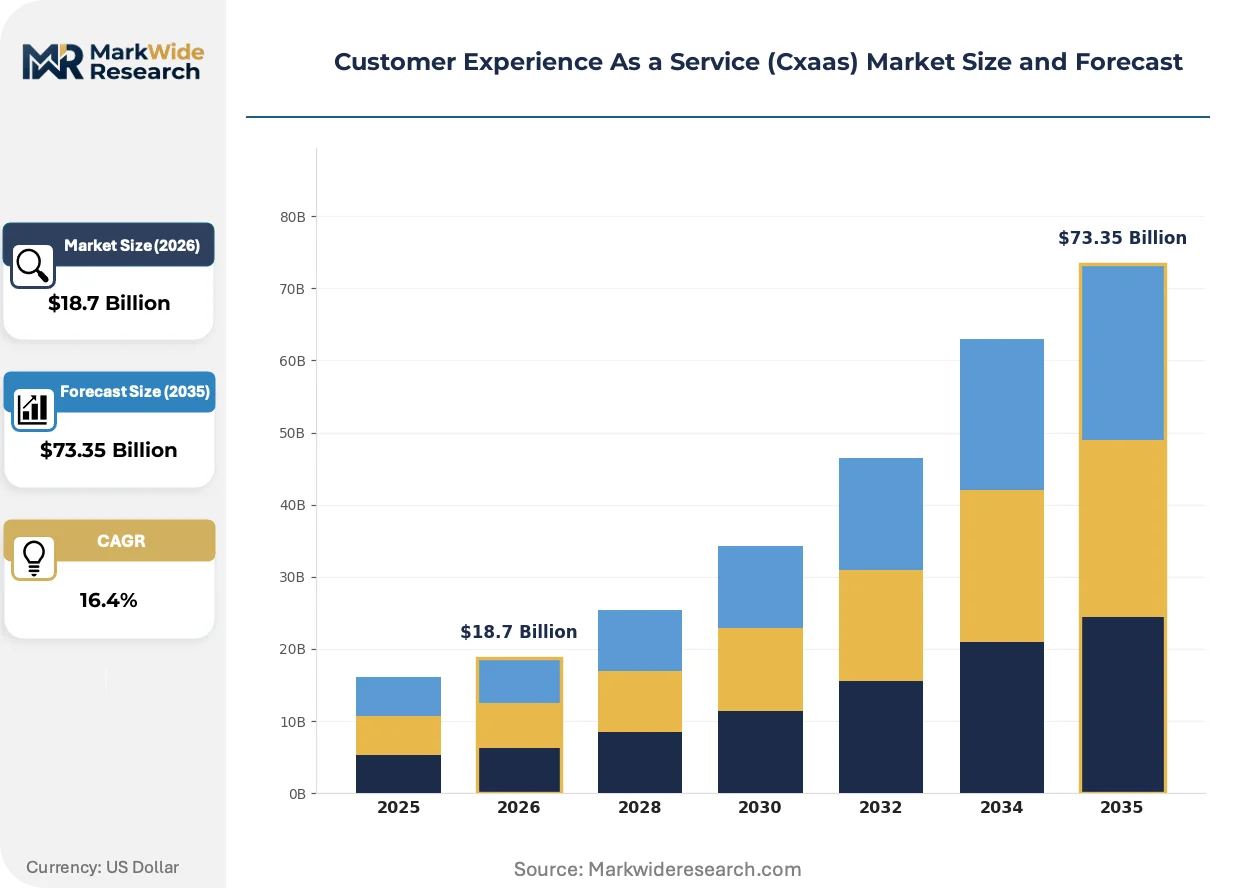
Market Dynamics
Cloud-native orchestration platforms are displacing legacy contact center infrastructure as enterprises prioritize elastic consumption models over fixed hardware investments. The shift compresses deployment cycles from quarters to weeks while fragmenting vendor relationships across specialized API providers.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making tools require transparent audit trails before deployment, creating pull for CXaaS vendors with pre-certified algorithmic stacks.
- German industrial retrofit wave:Manufacturing conglomerates are replacing fragmented service infrastructure with managed CXaaS bundles that unify B2B and B2C touchpoints.
- Real-time sentiment analysis:Sub-second latency processing of voice and text interactions enables predictive next-best-action engines that reduce cost-to-serve metrics.
Market Restraints
- Cross-border data localization:GDPR and China's GB standards force region-locked processing nodes, raising infrastructure duplication costs for multinational deployments.
- Hyperscale cloud concentration:Three infrastructure providers control elastic compute pricing, squeezing margins for CXaaS platforms without captive data center capacity.
- Biometric voice authentication:State-level privacy laws in Illinois, Texas, and Washington fragment compliance requirements for voice-data applications.
Strategic Opportunities
- India's PLI scheme for IT services:Export-linked incentives for software development centers create cost arbitrage for CXaaS implementation and training operations.
- Convergence of edge AI and 5G:Low-latency inference at network edge enables real-time personalization without central cloud round-trips for latency-sensitive use cases.
- Healthcare unbundling:HIPAA-covered entities are separating patient engagement from EHR systems, creating attach opportunities for compliant CXaaS layers.
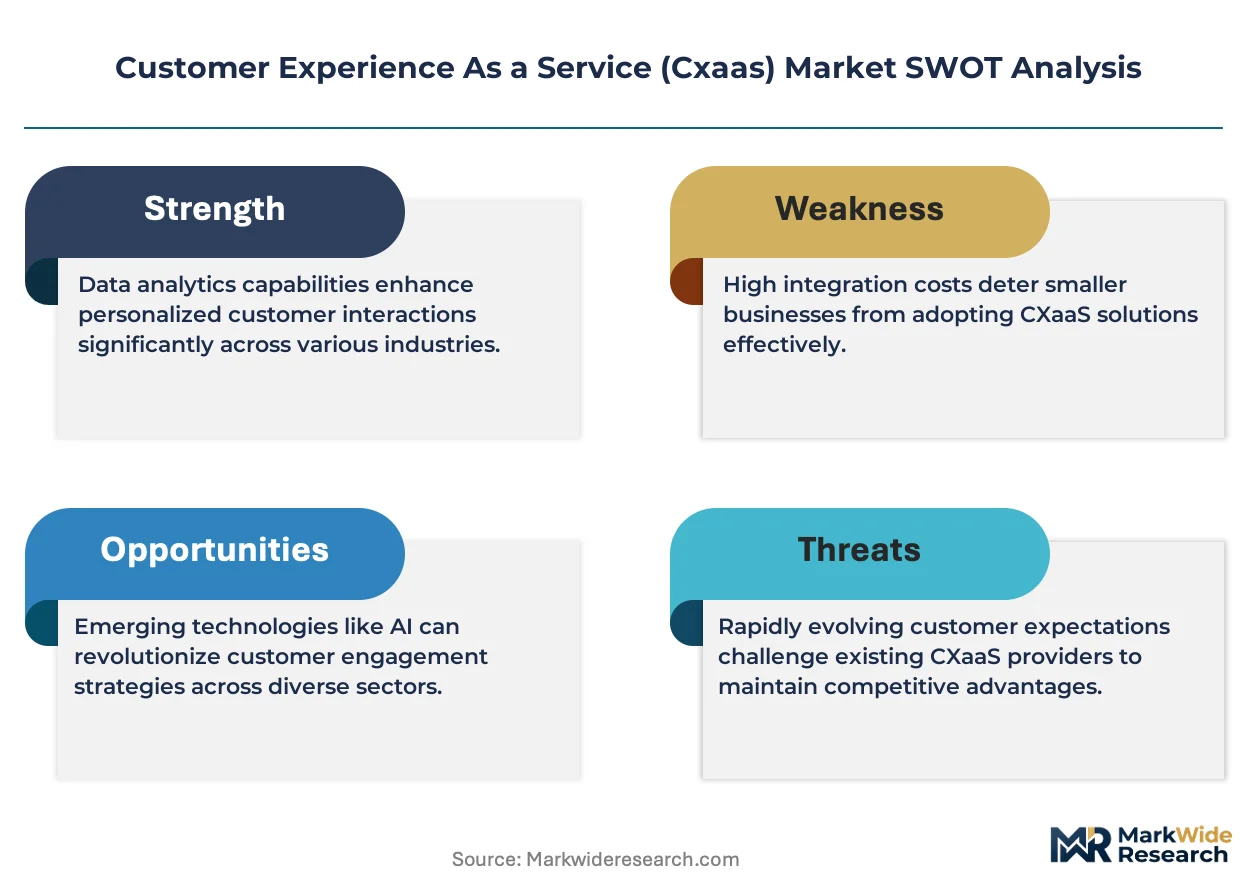
Industry Challenges
- Conversational AI talent scarcity:Shortage of prompt engineers and LLM fine-tuning specialists delays deployment timelines for advanced chatbot implementations.
- Legacy CRM integration friction:Enterprises with decades-old customer databases face data schema mismatches that extend implementation cycles and raise professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Experience As a Service (Cxaas) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Multichannel Support, Customer Analytics, Feedback Management, Knowledge Management End User: Retail, Financial Services, Healthcare, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: AI-Powered Chatbots, CRM Integration, Voice Recognition, Data Analytics |
| Companies Covered | Oracle Corporation, TTEC Holdings, Inc., Genesys, Salesforce, Adobe, Zendesk, NICE, Talkdesk, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Experience As a Service (Cxaas) Market Emerging Trajectories
Generative AI capabilities are restructuring competitive advantage around proprietary training data and fine-tuning expertise rather than traditional feature differentiation. Vendors race to embed LLM-powered assistants without ceding margin to foundation model providers.
API-first microservices architectures are fragmenting the CXaaS stack into composable components. Mid-market enterprises in retail and hospitality adopt best-of-breed routing, analytics, and automation modules rather than monolithic suites. This modularity compresses vendor switching costs and enables rapid experimentation with emerging capabilities.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes automated decision systems. Financial services deployments face mandatory conformity assessments before production release. German automotive lenders and Dutch insurers are front-loading compliance engineering to secure competitive clearance timelines.
Subscription fatigue among enterprise buyers is compressing contract renewal cycles and elevating proof-of-value requirements. Procurement teams demand consumption-based pricing with explicit ROI linkages to resolution rates and customer lifetime value. This pattern is most pronounced in US healthcare and UK telecommunications verticals where CFO scrutiny of SaaS spend has intensified.
Customer Experience As a Service (Cxaas) Market Segmentation
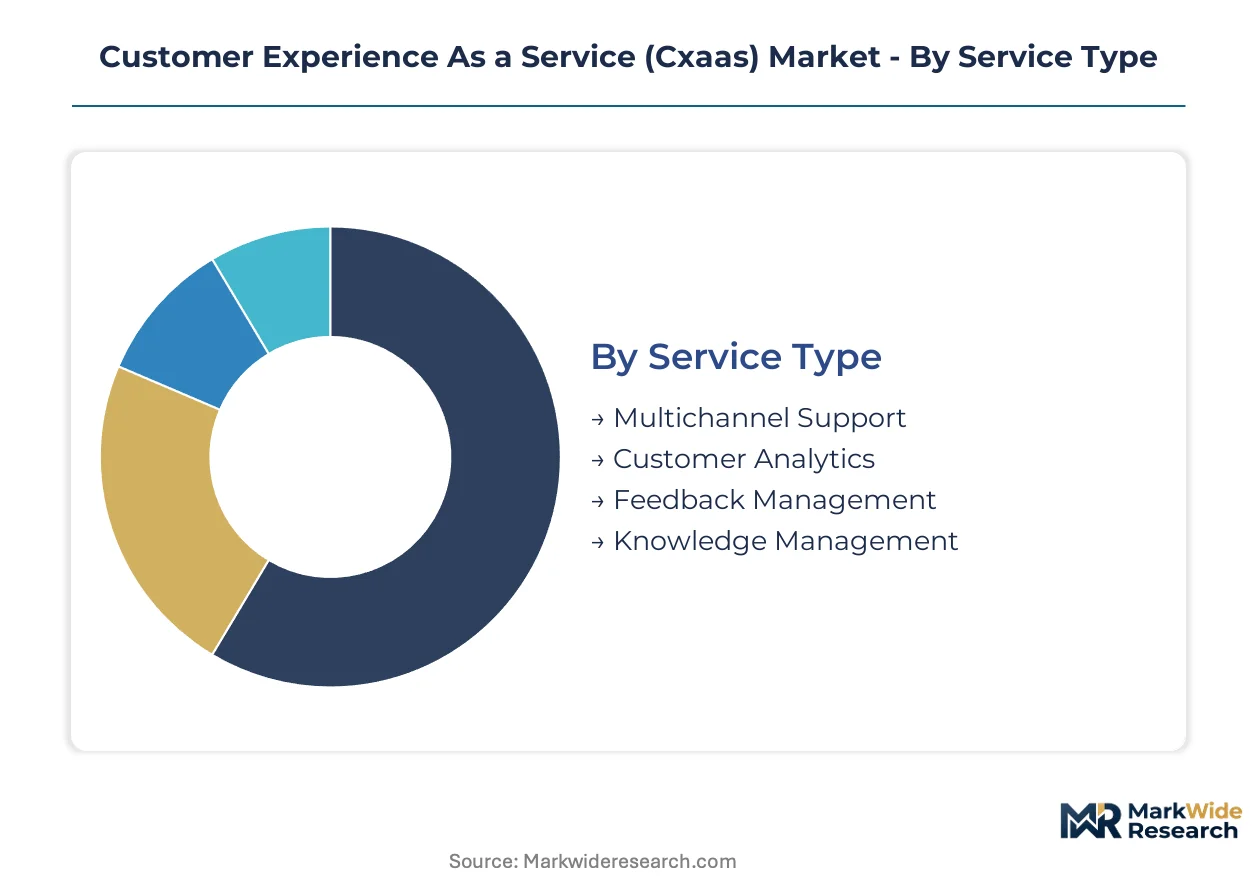
CXaaS procurement patterns diverge sharply across deployment models and vertical applications, with substitution pressure coming from adjacent enterprise software categories rather than direct competitors. Understanding segment boundaries clarifies where vendors defend margin pools versus where buyers force commoditization.
Service Type:
Multichannel Support faces the strongest substitution threat from unified communications platforms expanding into customer engagement, while specialized analytics layers remain defensible through proprietary data pipelines.
- Multichannel Support:Orchestrates voice, email, chat, and social touchpoints through unified agent desktops with real-time queue management. German automotive suppliers and Dutch insurers drive demand as they consolidate fragmented B2B and B2C service operations under single vendor relationships.
- Customer Analytics:Processes interaction data through predictive models that surface churn risk and lifetime value propensities. Financial services firms in Frankfurt and Amsterdam front-load investment here to satisfy EU AI Act documentation requirements for automated decision systems.
- Feedback Management:Captures and routes survey responses, reviews, and social sentiment into closed-loop improvement workflows.
- Knowledge Management:Maintains self-service repositories and agent-facing answer databases with semantic search and automated content suggestions.
Multichannel Support retains volume leadership; Customer Analytics holds the steepest expansion curve.
End User:
Margin concentration varies by vertical regulatory burden, with HIPAA and GDPR compliance requirements creating pricing power for certified implementations.
- Financial Services:Demands pre-certified algorithmic audit trails and real-time fraud detection integration. German automotive lenders and Dutch insurers prioritize conformity assessments under EU AI Act risk-based classifications.
- Healthcare:Requires HIPAA-compliant patient engagement layers with biometric voice authentication safeguards. US providers unbundle EHR-native support functions to attach specialized CXaaS modules with explicit ROI linkages.
- Retail:Prioritizes rapid-deployment ticketing for seasonal volume spikes and returns processing.
- Telecommunications:Consumes high-volume routing infrastructure with 5G-enabled edge personalization for latency-sensitive subscriber interactions.
Financial Services commands premium pricing; Healthcare is expanding most quickly as unbundling accelerates.
Deployment:
Cost tier stratification separates capital-intensive infrastructure plays from lightweight subscription models, with hybrid architectures capturing mid-market ambivalence.
- Cloud-Based:Delivers elastic consumption with sub-second latency orchestration and automatic feature updates. Enterprises abandon fixed hardware investments for faster iteration cycles, compressing deployment from quarters to weeks.
- Managed Services:Bundles implementation, training, and ongoing optimization with outcome-based pricing tied to resolution rates. Margin pools concentrate here as buyers demand explicit customer lifetime value linkages.
- On-Premises:Persists in highly regulated environments requiring air-gapped data processing.
- Hybrid:Combines sensitive data handling on-premises with burst capacity in public cloud infrastructure.
Cloud-Based dominates new contract value; Managed Services captures the highest margin expansion.
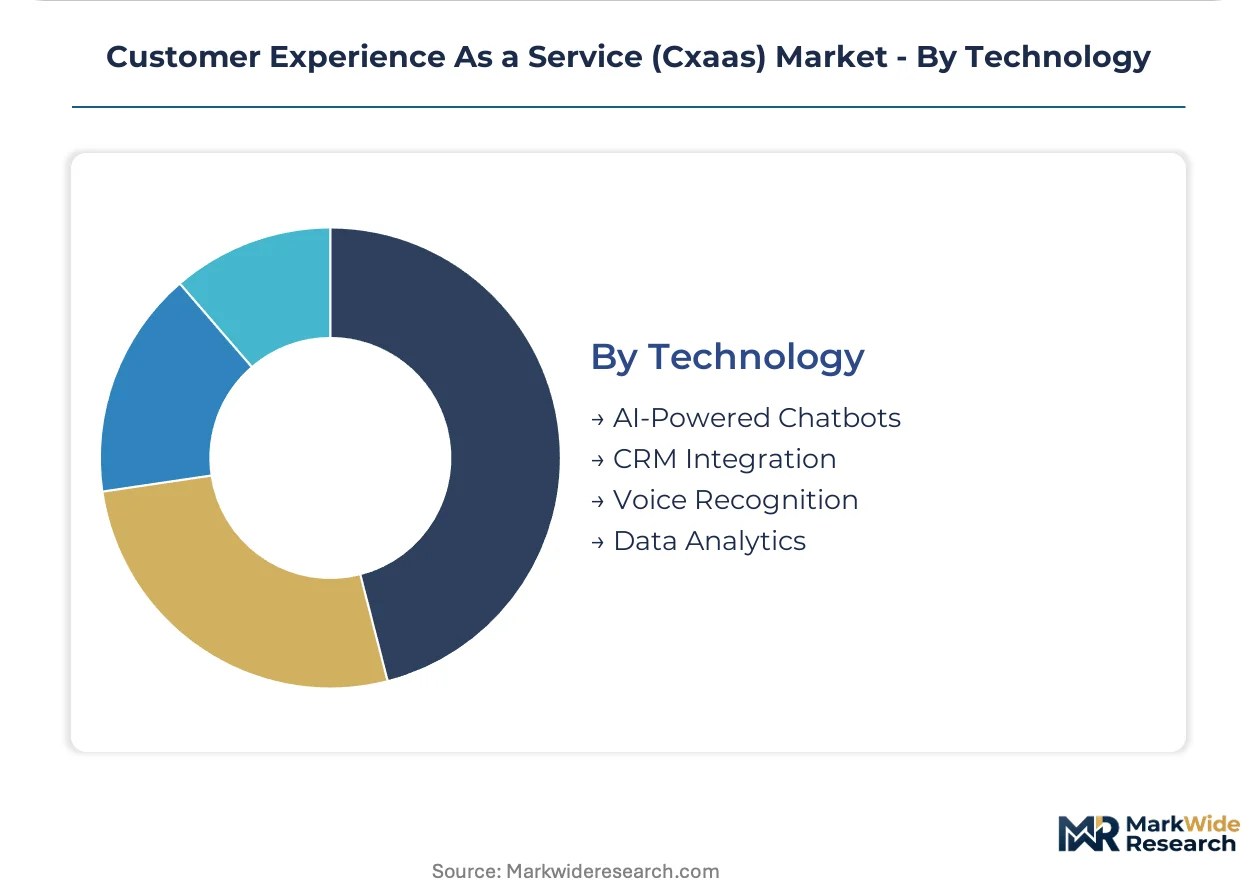
Technology:
Supply concentration in foundation model providers reshapes competitive dynamics for AI-powered capabilities, forcing differentiation through fine-tuning expertise rather than core LLM access.
- AI-Powered Chatbots:Deploys LLM-powered conversational agents with prompt engineering and domain-specific fine-tuning. Prompt engineer scarcity delays implementations for advanced use cases, extending professional services timelines.
- Data Analytics:Processes interaction streams through predictive next-best-action engines that reduce cost-to-serve metrics. Real-time sentiment analysis at sub-second latency enables proactive intervention before escalation.
- CRM Integration:Bridges CXaaS platforms with legacy customer databases, facing friction from decades-old schema mismatches.
- Voice Recognition:Powers biometric authentication and real-time transcription, fragmented by Illinois BIPA and Texas biometric privacy compliance requirements.
Data Analytics anchors platform value; AI-Powered Chatbots is climbing the fastest as generative capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where manufacturers absorb premium CXaaS bundles, while US healthcare providers negotiate consumption-based contracts with explicit ROI clauses. This asymmetry reflects divergent regulatory burdens and procurement maturity across Atlantic markets.
Germany
Automotive lenders and industrial conglomerates drive managed CXaaS adoption to unify B2B and B2C service operations. The EU AI Act mandates conformity assessments for automated decision systems before production deployment. Frankfurt and Stuttgart clusters front-load compliance engineering to secure competitive clearance timelines for algorithmic credit-scoring tools.
United States
Healthcare systems unbundle patient engagement from EHR-native functions, creating attach opportunities for compliant CXaaS layers. HIPAA and Illinois BIPA impose sector-specific guardrails on voice-data applications and biometric authentication. Chicago-based providers and Texas medical centers negotiate outcome-based pricing tied to resolution rate improvements.
Netherlands
Insurers and financial services firms prioritize customer analytics investments to satisfy EU AI Act documentation requirements. GDPR constrains cross-border data flows, compelling region-locked processing architectures. Amsterdam's fintech corridor deploys predictive next-best-action engines with transparent algorithmic audit trails for regulatory pre-certification.
India
Export-linked incentives under the PLI scheme for IT services create cost arbitrage for CXaaS implementation and training operations. The country's software development centers attract multinational vendors seeking operational efficiency. Bangalore and Hyderabad clusters specialize in conversational AI talent pools for prompt engineering and LLM fine-tuning services.
China
Domestic demand for algorithmic recommendation systems aligns with SAMR and GB standards that shape product architecture for voice recognition and sentiment analysis. Multinational vendors engineer geography-specific compliance forks to satisfy data localization mandates. Shanghai and Shenzhen technology corridors concentrate development of edge AI inference capabilities for low-latency personalization.
Customer Experience As a Service (Cxaas) Market Vendor Landscape
Concentration sits with hyperscale cloud infrastructure providers and specialized workforce optimization vendors that anchor opposite ends of the CXaaS stack. The market structure bifurcates between capital-intensive integrated suites and lightweight API-first platforms. Three strategic archetypes dominate: database-to-application stack owners, compliance-sensitive vertical specialists, and modular mid-market ticketing providers. Competitive moves center on M&A to acquire conversational AI capabilities and strategic partnerships with foundation model providers to embed generative features without margin erosion.
Within the integrated enterprise tier, Oracle Corporation and Salesforce occupy positions that leverage captive data environments across financial and healthcare clients. NICE anchors the compliance-specialist vector with workforce optimization tools targeting regulated verticals. Among modular platform providers, Zendesk exemplifies the rapid-deployment archetype that captures mid-market retail and hospitality contracts with API-first architectures.
| Leading Market Players |
|---|
| Oracle Corporation |
| TTEC Holdings, Inc. |
| Genesys |
| Salesforce |
| Adobe |
| Zendesk |
| NICE |
| Talkdesk |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Consumption-based SaaS contracts with explicit ROI linkages lock in both supply access and price visibility for enterprise buyers, compressing renewal cycles while anchoring vendor margins to resolution rate improvements. CFO scrutiny in US healthcare and UK telecommunications elevates proof-of-value requirements, forcing CXaaS providers to bundle implementation and optimization services with outcome-based pricing.
Pricing Analysis
Customization-premium spreads separate configured-to-order implementations from standard SaaS tiers, with German automotive lenders and Dutch insurers absorbing premium bundles for EU AI Act-compliant algorithmic stacks. Subscription fatigue compresses contract structures toward consumption-based models with explicit customer lifetime value linkages, while mid-market retail buyers drive standard-tier commoditization through rapid-deployment demands. Price differentiation hinges on certification grade and vertical integration depth, with HIPAA-compliant healthcare layers and GDPR-audited European deployments commanding substantial premiums. Cost compression in standard multichannel support reflects unified communications substitution, though managed services bundles retain pricing power through embedded optimization expertise.
Supply Chain Analysis
Inbound logistics costs for GPU clusters and specialized AI accelerators fluctuate with port congestion at Rotterdam and Singapore, constraining elastic compute provisioning for real-time sentiment analysis workloads. Supply concentration centers on Taiwan and South Korea for advanced semiconductors, with hyperscale cloud infrastructure drawing from captive US and European data center networks. Raw material dependencies span NVIDIA/AMD accelerators, high-bandwidth memory modules, and fiber-optic interconnects for sub-second latency orchestration. Single-source vulnerability in foundation model APIs forces CXaaS vendors to engineer multi-provider redundancy. Distribution runs through direct enterprise sales with embedded professional services, supplemented by channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification system creates a regulatory inflection that separates pre-certified vendors from compliance-lagged competitors, reshaping competitive positioning across financial services and healthcare verticals.
For Market Incumbents: Consolidate conversational AI capabilities through targeted capability acquisitions, securing prompt engineering talent pools in Bangalore and Hyderabad before scarcity intensifies deployment timelines. Deepen backward integration into proprietary training data pipelines to reduce margin erosion from foundation model provider dependencies. Anchor position in German industrial corridors through pre-certified algorithmic audit trails that accelerate EU AI Act clearance timelines for automotive lenders. For New Entrants and Emerging Players: HIPAA fast-track certification for patient engagement modules opens attach opportunities as US healthcare systems unbundle EHR-native support functions. Target mid-market retail and hospitality segments with API-first microservices architectures that compress switching costs and enable rapid experimentation. Pursue outcome-based pricing with explicit resolution rate linkages to differentiate from incumbent subscription fatigue. For Investors and Strategic Acquirers: Capital is best deployed toward workforce optimization specialists with compliance-sensitive vertical depth, particularly those serving Dutch insurers and German automotive lenders facing EU AI Act conformity assessments. Long-term viability hinges on proprietary fine-tuning expertise and region-locked processing architectures that satisfy GDPR and China's GB standards. Monitor foundation model provider pricing power as the critical inflection signal for margin compression risk across the CXaaS stack.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Frankfurt automotive lenders secure competitive clearance timelines for algorithmic credit-scoring tools. |
| Conversational AI Acquisition | Bangalore prompt engineering talent pools accelerate LLM deployment cycles for enterprise clients. |
| HIPAA-Compliant Layer Development | US healthcare unbundling creates attach opportunities with explicit ROI linkages to resolution rates. |
| Edge AI Infrastructure Partnership | 5G-enabled low-latency inference supports real-time personalization without central cloud round-trips. |
| Managed Services Bundle Expansion | Outcome-based pricing with customer lifetime value linkages captures highest margin expansion pools. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, contact center operations directors, platform engineers, and channel integration specialists. Secondary validation drew from SEC filings of hyperscale cloud providers, EU AI Act implementation guidance, HIPAA enforcement actions, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market boundary estimates from industry association data and enterprise software spending surveys.
Across the analysis window, forecasts model deployment mode, organization size, vertical regulatory burden, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs derive from trend extrapolation of cloud migration velocity, AI capability maturation curves, and compliance cost trajectories. Industry-specific inputs include EU AI Act conformity assessment timelines, foundation model API pricing trajectories, and 5G edge infrastructure deployment schedules.
Underlying assumptions cover sustained cloud migration momentum and regulatory enforcement consistency, with deviation risk concentrated in foundation model provider concentration and cross-border data localization fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
G2P Systems Market
Digital Solutions
Shipping Software Market
Digital Solutions
India PLM Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Inventory Management Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
File Sharing Market
Digital Solutions
Poland ICT Market