
 Open Source Bug Tracking Tool Market | 2026-2036
Open Source Bug Tracking Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Open Source Bug Tracking Tool Market Insights
Open-source contributor networks across Eastern Europe and South Asia are broadening the talent pool available for platform maintenance and plugin development. Atlassian leverages its dual commercial-open-source presence to sustain developer mindshare across Jira-adjacent workflows. JetBrains competes through deep IDE integration that anchors bug tracking within the code authoring environment itself.
An open source bug tracking tool is a software application distributed under licenses permitting source code modification, typically supporting ticket creation, assignment, status workflows, and version control linkage through REST APIs or webhooks, designed to record, prioritize, and resolve software defects across distributed development teams. Web-based deployments dominate current adoption due to lower infrastructure overhead and remote accessibility, while cloud and SaaS configurations represent the fastest-expanding deployment category as organizations shed on-premises server maintenance. Large enterprises command the deepest integration requirements, driving demand for API-based and plugin-compatible architectures that connect with CI/CD pipelines.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape procurement criteria by mandating audit trails, data residency controls, and security certification for software tooling used in regulated industries. HIPAA in the United States imposes comparable constraints on healthcare technology vendors selecting collaborative development infrastructure. Stakeholders must weigh self-hosted deployment against SaaS convenience as regulatory fragmentation hardens across major software-consuming jurisdictions.
Market Dynamics
GDPR and the EU AI Act are forcing software procurement teams to re-evaluate SaaS dependencies, redirecting evaluation criteria toward auditable, self-hosted alternatives that satisfy data residency mandates without surrendering collaborative functionality.
Growth Catalysts
- EU AI Act Compliance:European enterprises must maintain explainable decision logs for AI-assisted debugging workflows, elevating open-source tools with native audit trails above proprietary black-box alternatives.
- CI/CD Pipeline Integration:DevOps teams require webhook-native issue tracking that triggers automated test reruns on ticket state changes, embedding bug management directly into deployment orchestration layers.
- Germany:Industrial software vendors headquartered in Munich and Stuttgart prioritize data sovereignty certifications when selecting development infrastructure, creating concentrated demand for EU-hosted open-source platforms.
Market Restraints
- Self-Hosted Infrastructure Costs:Organizations maintaining on-premises deployments face persistent PostgreSQL and Elasticsearch scaling expenses that erode the total-cost-of-advantage against managed SaaS alternatives.
- Plugin Ecosystem Fragmentation:Contributors distribute maintenance effort across GitHub, GitLab, and Gitea plugin repositories, producing compatibility gaps that delay security patch propagation.
- HIPAA Audit Burden:US healthcare technology vendors encounter documentation requirements from HHS that extend procurement cycles for collaborative development tools by four to eight months.
Strategic Opportunities
- India:PLI scheme beneficiaries building enterprise software for domestic manufacturing clients represent an underpenetrated buyer segment with rising procurement authority for development infrastructure.
- Federated Architecture Convergence:ActivityPub protocol implementations enable cross-instance ticket synchronization between organizational boundaries, unlocking multi-tenant collaboration without centralized data aggregation.
- ISO 27001 Certification:Security-conscious buyers increasingly filter vendor shortlists by certification status, rewarding platforms that invest in formal attestation ahead of compliance-driven procurement waves.
Industry Challenges
- Rust-to-Wasm Migration:Frontend modernization demands specialized systems programming expertise that remains scarce in the volunteer contributor pools sustaining most open-source projects.
- Legacy Jira Integration:Enterprise migration projects require bidirectional synchronization with entrenched Atlassian workflows, consuming engineering resources that delay feature roadmap execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Source Bug Tracking Tool Market |
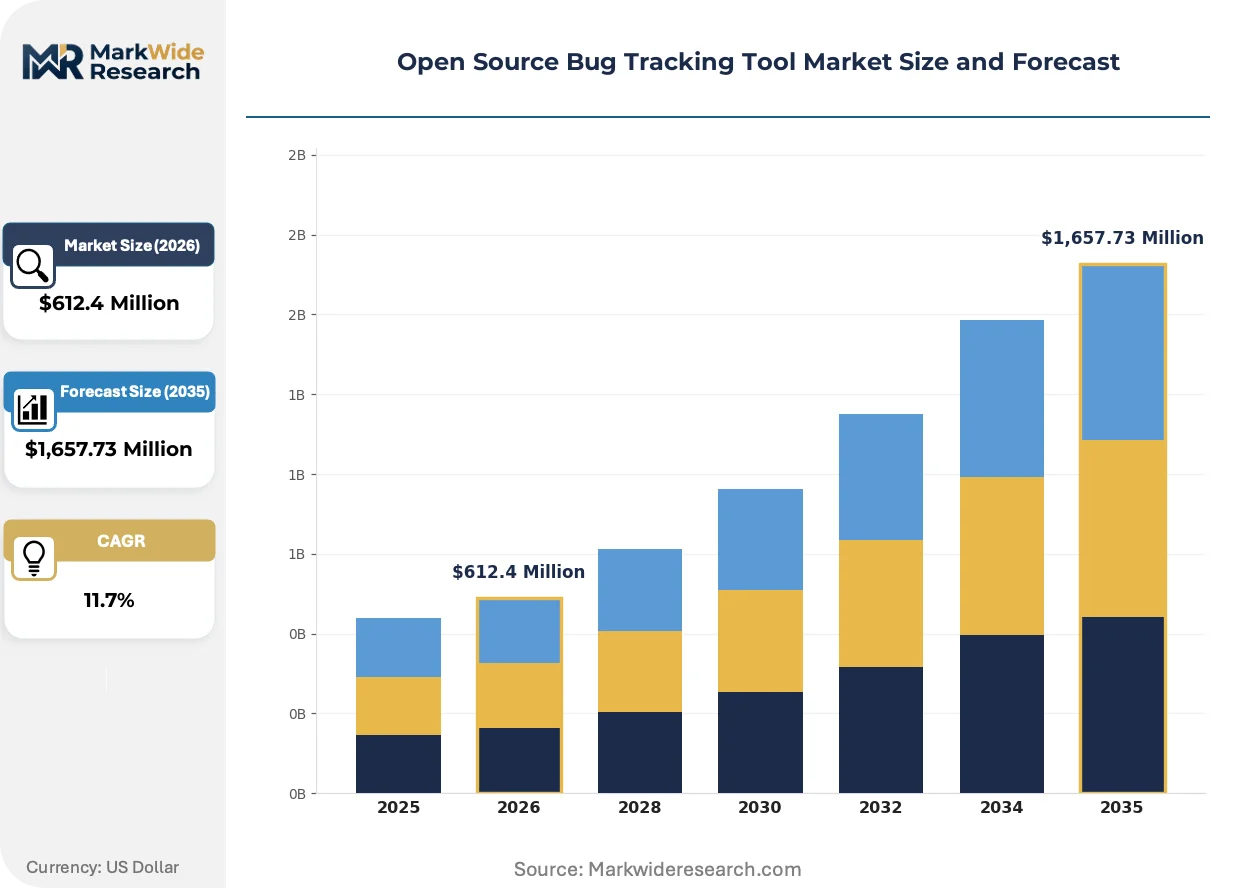
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,657.73 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Desktop, Mobile, Hybrid Deployment: On-Premises, Cloud, SaaS, Private Cloud End User: Small Enterprises, Large Enterprises, Educational Institutions, Government Agencies Integration Level: API-Based, Plugin-Compatible, Standalone, Others |
| Companies Covered | Atlassian, Sentry, MantisBT Team, JetBrains, Zoho Corporation, Rollbar, Raygun, Inflectra Corporation, Fog Creek Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Source Bug Tracking Tool Market Trends and Innovations
Real-time collaborative editing is displacing sequential ticket workflows across distributed development teams, compressing issue resolution cycles and elevating platform selection criteria toward operational latency benchmarks.
GraphQL-based query layers are unifying disparate data sources—version control, CI/CD status, and deployment telemetry—into single-pane issue views. Platform engineering teams at SaaS enterprises adopt these interfaces within eighteen-month refresh cycles. This unification collapses the context-switching overhead that previously fragmented developer attention across browser tabs.
CSRD disclosure mandates from the European Commission require software vendors to document supply chain emissions and data processing locations. Procurement departments in Frankfurt and Paris now embed these sustainability attestations into RFP scoring rubrics. German automotive software suppliers have responded by pre-certifying open-source toolchains against CSRD technical standards.
Consolidated vendor relationships are compressing the number of approved development tools per enterprise, with platform teams favoring extensible open-source cores over point solutions. Channel partners in the Netherlands and Denmark report that single-vendor procurement committees now dominate evaluations that previously involved specialized best-of-breed selections. This concentration rewards platforms with plugin marketplaces that replicate adjacent functionality without additional vendor contracts.
Open Source Bug Tracking Tool Market Segmentation
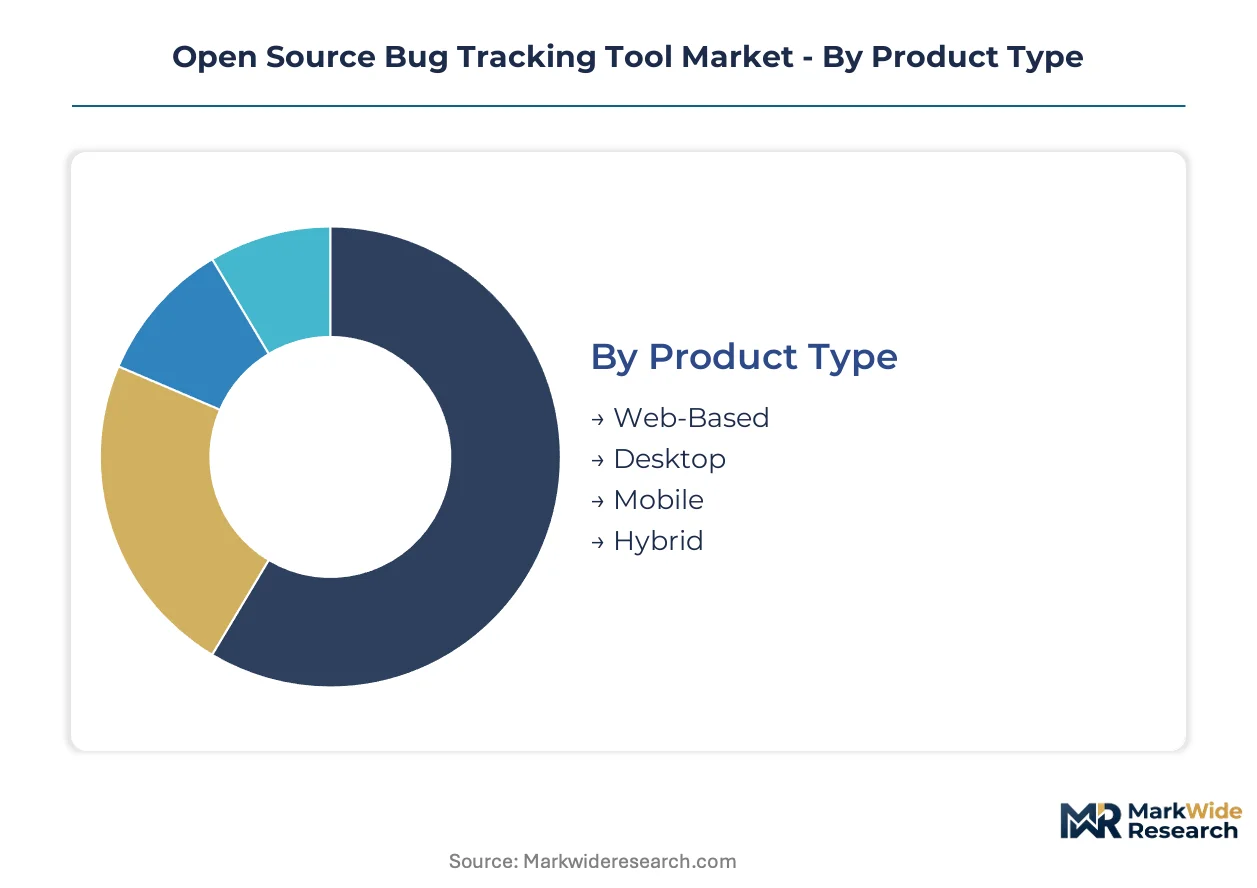
Segmentation in the open source bug tracking tool market reveals how procurement priorities diverge across infrastructure constraints, regulatory exposure, and workflow complexity. Buyers select configurations based on data residency mandates, DevOps maturity, and integration depth with existing toolchain investments.
Product Type:
Technical teams prioritize accessibility models that match their distributed workforce structures and device policies.
- Web-Based:Browser-native interfaces eliminate client installation overhead across heterogeneous device fleets. SaaS enterprises in Germany and the Netherlands standardize on these deployments to support remote engineering teams while maintaining GDPR-compliant access logging.
- Desktop:Native applications deliver offline ticket queue management and reduced latency for high-volume triage workflows. Industrial software vendors in Stuttgart and Munich favor these for air-gapped development environments where network connectivity remains intermittent.
- Mobile:Smartphone-optimized interfaces enable field engineer incident logging and on-call alert acknowledgment.
- Hybrid:Synchronized local-remote architectures bridge disconnected operations with centralized reporting requirements.
Volume sits with Web-Based deployments; growth tilts toward Hybrid configurations as edge computing expands.
Deployment:
Infrastructure ownership preferences split along audit trail requirements and capital expenditure cycles.
- On-Premises:Self-managed PostgreSQL and Elasticsearch clusters deliver complete data sovereignty for regulated industries. Healthcare technology vendors navigating HIPAA documentation mandates from HHS select these to control encryption key custody and access logging granularity.
- Cloud:Managed Kubernetes deployments reduce operational overhead while preserving customization flexibility. Platform engineering teams at European SaaS enterprises adopt these within eighteen-month infrastructure refresh cycles to satisfy CSRD disclosure requirements without自建 data center investments.
- SaaS:Fully managed subscriptions accelerate procurement for teams lacking dedicated DevOps resources.
- Private Cloud:Tenant-isolated environments replicate SaaS convenience with single-tenant security boundaries.
Cloud deployments capture the steepest expansion trajectory; On-Premises retains the largest installed base among regulated sectors.
End User:
Organizational scale dictates integration complexity and support contract expectations.
- Large Enterprises:Procurement committees mandate API-native architectures that webhook into CI/CD orchestration layers. German automotive software suppliers pre-certify open-source toolchains against ISO 27001 and CSRD technical standards before inclusion in approved vendor lists.
- Small Enterprises:Lean teams prioritize rapid deployment over customization depth, selecting containerized distributions with minimal configuration surfaces. Indian PLI scheme beneficiaries building enterprise software for domestic manufacturing clients represent rising procurement authority in this tier.
- Educational Institutions:Budget-constrained environments favor community-supported distributions with extensive documentation.
- Government Agencies:Public sector procurement cycles emphasize security certification and domestic hosting requirements.
Large Enterprises dominate current revenue; Small Enterprises are gaining share fastest as cloud-native adoption lowers entry barriers.
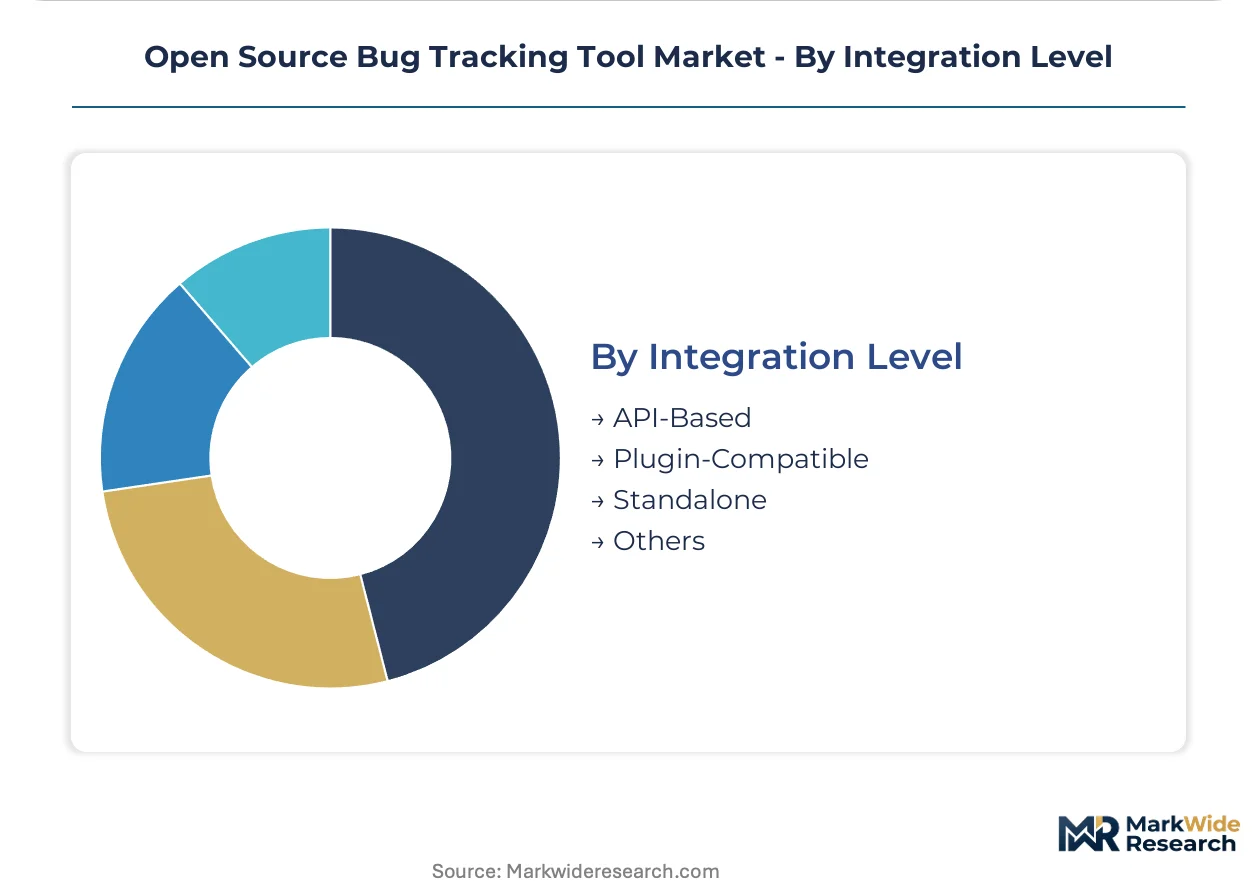
Integration Level:
Connectivity requirements separate workflow-embedded platforms from peripheral tracking utilities.
- API-Based:REST and GraphQL endpoints enable bidirectional synchronization with version control, deployment telemetry, and test automation systems. JetBrains leverages deep IDE integration to anchor bug tracking within code authoring environments, reducing context-switching overhead.
- Plugin-Compatible:Extensible architectures replicate adjacent functionality without additional vendor contracts. Channel partners in Denmark and the Netherlands report single-vendor procurement committees favoring these platforms for consolidated toolchain approval.
- Standalone:Self-contained deployments serve teams with minimal external system dependencies.
- Others:Emerging protocol implementations including ActivityPub enable cross-instance ticket synchronization between organizational boundaries.
API-Based integrations command the deepest enterprise commitment; Plugin-Compatible architectures expand most quickly through marketplace network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PostgreSQL contributor density in Estonia and Elasticsearch engineering clusters in Amsterdam anchor European infrastructure expertise for self-hosted deployments. Talent pipelines from these localities feed development teams across multiple jurisdictions.
Germany
Industrial software vendors in Munich and Stuttgart drive concentrated demand for data-sovereign toolchains. The EU AI Act mandates explainable decision logs for AI-assisted debugging, elevating platforms with native audit trails. Bavarian automotive suppliers pre-certify open-source stacks against ISO 27001 before inclusion in approved vendor lists.
United States
Healthcare technology vendors navigate HIPAA documentation requirements from HHS that extend procurement cycles by four to eight months. FDA-regulated medical device manufacturers prioritize self-hosted deployments to control encryption key custody. Boston and San Francisco clusters host the deepest DevOps integration engineering talent.
India
PLI scheme beneficiaries building enterprise software for domestic manufacturing clients represent rising procurement authority for development infrastructure. The country's national software standards body emphasizes data localization compliance for government contracts. Bengaluru and Hyderabad engineering centers export CI/CD pipeline integration expertise to multinational SaaS enterprises.
United Kingdom
London-based fintech operators reconcile GDPR data residency requirements with post-Brexit regulatory divergence. The Information Commissioner's Office enforcement patterns shape procurement risk assessments for collaborative development tools. Cambridge and Manchester university spinouts contribute plugin development capacity to major open-source projects.
Netherlands
Platform engineering teams in Amsterdam and Eindhoven adopt cloud-native deployments within eighteen-month infrastructure refresh cycles. CSRD disclosure mandates from the European Commission embed sustainability attestations into RFP scoring rubrics. Dutch channel partners report single-vendor procurement committees now dominate evaluations that previously involved specialized best-of-breed selections.
Open Source Bug Tracking Tool Market Competitive Landscape
Global majors compete with regional champions across integration depth and deployment flexibility, producing a tiered structure where IDE-anchored platforms, webhook-native DevOps tools, and self-hosted sovereignty solutions occupy distinct competitive positions. The vendor base splits between consolidated commercial-open-source hybrids and fragmented community-maintained distributions. Three archetypes dominate: dual-license incumbents with adjacent workflow ecosystems, IDE-native specialists embedding tracking within code authoring environments, and volunteer-sustained projects with plugin-marketplace network effects. Competitive moves concentrate on strategic partnerships with CI/CD orchestration vendors and geographic expansion through channel relationships in regulated European markets.
Within the dual-license tier, Atlassian leverages its commercial-open-source presence to sustain developer mindshare across Jira-adjacent workflows, while JetBrains anchors bug tracking within IDE environments through deep integration engineering. Sentry occupies a position exemplifying the webhook-native DevOps archetype, embedding error monitoring directly into deployment telemetry streams. These three represent the dominant competitive anchors shaping procurement committee evaluations across large enterprise segments.
| Leading Market Players |
|---|
| Atlassian |
| Sentry |
| MantisBT Team |
| JetBrains |
| Zoho Corporation |
| Rollbar |
| Raygun |
| Inflectra Corporation |
| Fog Creek Software |
| Others |
Pricing and Supply Chain Analysis
PostgreSQL and Elasticsearch engineering talent concentration in Estonia and Amsterdam creates labor-cost differentials that widen pricing-tier spreads between self-managed and fully managed service bundles.
Pricing Analysis
Extended warranty and premium support bundling separates enterprise-grade subscriptions from community-supported distributions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 certification status and API integration depth as primary differentiation drivers. Pricing pressure stems from hyperscaler-managed alternatives compressing margins in the mid-market tier. Small enterprises exhibit highest price sensitivity, while regulated healthcare vendors prioritize audit-trail completeness over cost minimization.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for government software contracts are reshaping contributor sourcing toward Bengaluru and Hyderabad engineering centers. Core development draws from volunteer networks in Eastern Europe, South Asia, and the Netherlands, with plugin distribution resting on GitHub, GitLab, and Gitea repository ecosystems. Single-source vulnerability concentrates in Elasticsearch dependency for search-indexing functionality. Distribution runs through direct download channels, cloud marketplaces, and channel partners in regulated European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance burdens are forcing consolidation among smaller platforms lacking audit-trail infrastructure, winnowing the vendor base toward certified incumbents.
For Market Incumbents: Deepen CI/CD pipeline integration partnerships to anchor bug tracking within DevOps orchestration layers before JetBrains extends IDE-native coverage. Invest in ISO 27001 pre-certification against CSRD technical standards to capture German automotive procurement committees. Prioritize backward integration into Elasticsearch hosting to reduce third-party dependency exposure. For New Entrants and Emerging Players: Systems integrators in the Netherlands and Denmark represent underexploited channel capacity for white-label deployment services. Target Indian PLI scheme beneficiaries building manufacturing software with containerized distributions emphasizing rapid deployment over customization depth. Lead with ActivityPub federated architecture to differentiate against centralized SaaS incumbents in multi-tenant collaboration scenarios. For Investors and Strategic Acquirers: The window for entry favors dual-license platforms with existing Jira-adjacent workflow mindshare and established plugin marketplaces. Long-term viability hinges on API-native architecture and regulatory certification depth rather than feature velocity alone. Monitor GDPR enforcement patterns from the Information Commissioner's Office and CNIL as inflection indicators for self-hosted demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep IDE embedding by JetBrains reduces context-switching overhead for developer retention. |
| Strategic Partnership | CI/CD orchestration alliances embed ticket tracking within deployment telemetry streams. |
| Acquisition of Specialist Firm | Elasticsearch hosting capabilities eliminate third-party infrastructure dependency risks. |
| Geographic Expansion | Channel relationships in Munich and Stuttgart capture German data-sovereignty procurement. |
| Product Launch | ActivityPub federated implementations unlock cross-boundary collaboration without data aggregation. |
Research Methodology
Multi-period observation of GitHub contributor velocity, plugin marketplace growth, and CI/CD adoption rates anchored the trend analysis, supplemented by interviews with platform engineering leads, DevOps directors, IT procurement officers, and open-source maintainers. Secondary validation drew from SEC filings of adjacent workflow vendors, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement database extracts. Bottom-up deployment model estimates triangulated against top-down enterprise software spending benchmarks.
Input-output matrices mapped PostgreSQL scaling costs, Elasticsearch licensing transitions, and webhook integration complexity across deployment models, organization sizes, vertical sectors, and regional regulatory clusters. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated EU AI Act implementation timelines and PLI scheme beneficiary expansion patterns.
Caveats apply where GDPR enforcement divergence, HIPAA audit burden fluctuations, or Rust-to-Wasm migration bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions about contributor network sustainability and hyperscaler competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Vending Software Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Spain Sports Management Software Market
Software & Services
North America Workforce Management Software Market
Software & Services
Photobooth Software Market
Software & Services
Intellectual Property Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Construction Project Management Software Market
Software & Services
Subscription Management Software Market
Software & Services
Simulation Software Market
Software & Services
Global Quoting Software Market
Software & Services
Towing Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
RFP Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
App Development Software Market