
 Digital Shelf Market | 2026-2036
Digital Shelf Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Shelf Market Analysis
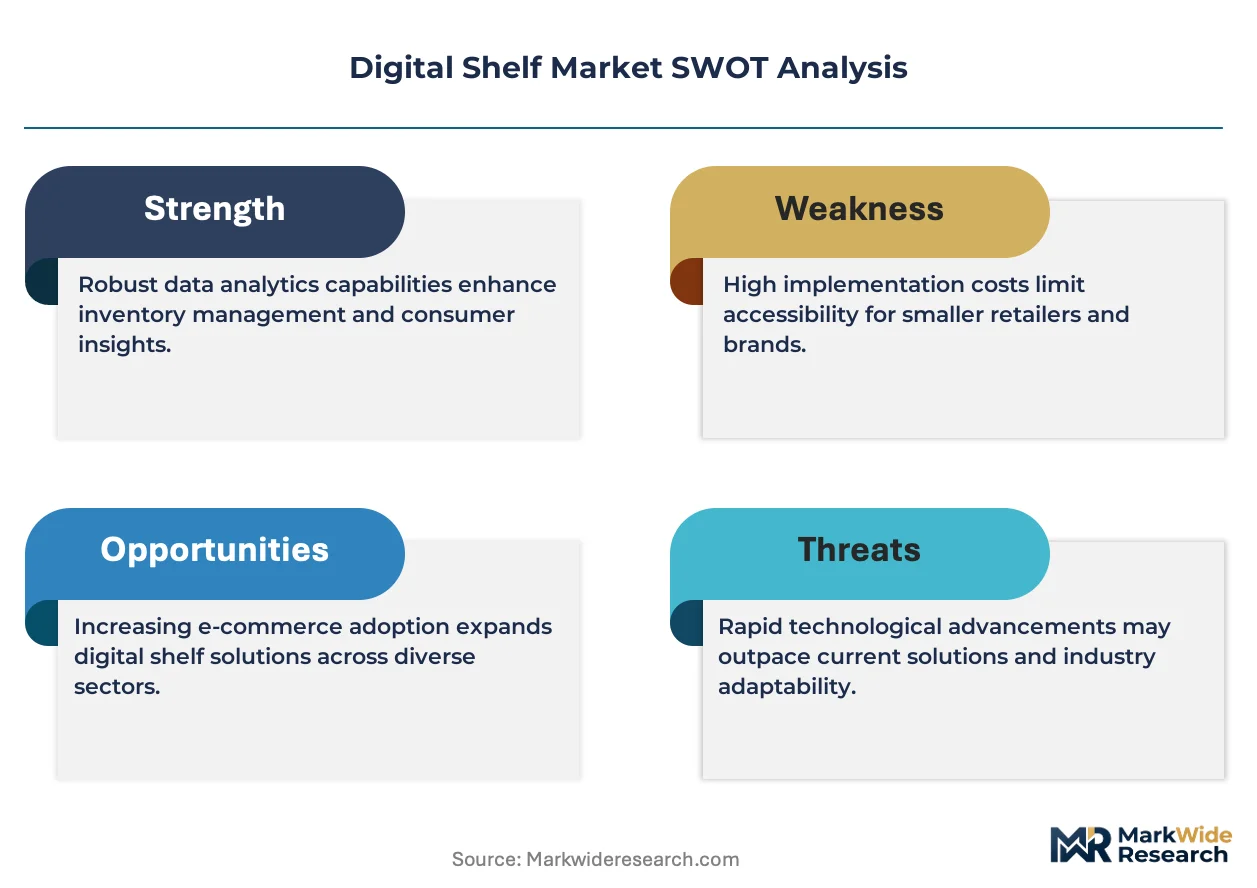
Subscription-based pricing for digital shelf analytics is shifting how vendors monetize product content syndication and performance monitoring. Intelligence Node leverages AI-powered competitive benchmarking to differentiate its offering across European retail networks. Stackline anchors its position through deep Walmart marketplace integration and first-party data partnerships. CommerceIQ sustains expansion by combining shelf health scoring with retail media optimization workflows.
The digital shelf encompasses the complete online presentation layer of products across e-commerce environments, including structured content, imagery, ratings, inventory signals, and search placement algorithms that determine discoverability. These systems ingest real-time competitive pricing, stock availability, and review sentiment to automate merchandising decisions across fragmented retailer portals. Cloud-based deployment now leads segment adoption as enterprises prioritize elastic scaling and API-native integration with existing ERP and PIM infrastructure. SaaS delivery models capture the fastest growth trajectory by reducing upfront implementation costs and accelerating time-to-value for mid-market brands. Pricing optimization software represents a concentrated margin pool where algorithmic repricing engines command premium licensing fees.
FDA regulations on health and nutrition claims directly shape how food and beverage brands structure digital shelf content for compliance. The EU Digital Services Act and GDPR impose content moderation and data governance obligations on marketplace operators managing third-party seller listings. Stakeholders must monitor evolving platform algorithm transparency mandates that could force disclosure of ranking factors currently treated as proprietary trade secrets.
Market Dynamics
Cloud-native deployment architectures are displacing legacy on-premises installations across retail operations, compressing implementation timelines and forcing vendors to restructure pricing models around consumption-based metrics rather than perpetual licenses.
Growth Catalysts
- EU Digital Services Act:Content moderation obligations on marketplace operators create mandatory investment in automated shelf monitoring tools for third-party seller compliance.
- Algorithmic search placement:Amazon and Walmart search ranking opacity drives CPG brands to purchase external analytics to reverse-engineer discoverability factors.
- API-native ERP integration:Elastic cloud scaling enables mid-market brands to deploy enterprise-grade shelf intelligence without dedicated infrastructure teams.
Market Restraints
- Data aggregation costs:Scraping fees and retailer API access charges create margin pressure for vendors serving price-sensitive mid-market accounts.
- Platform algorithm opacity:Proprietary ranking factor secrecy limits the accuracy of predictive shelf health scoring models.
- GDPR data governance:Cross-border competitive intelligence workflows face friction from EU data localization requirements and consent management overhead.
Strategic Opportunities
- Retail media convergence:Integration of shelf analytics with sponsored product campaign management creates unified workflow value for brand advertisers.
- India marketplace expansion:Flipkart and Reliance JioMart ecosystem growth generates demand for localized content syndication and vernacular search optimization.
- FDA nutrition claim automation:Structured content validation tools that pre-check health claim compliance against federal labeling standards.
Industry Challenges
- ML engineer scarcity:Shortage of talent capable of building real-time competitive pricing models that ingest multi-retailer data streams at scale.
- Legacy PIM integration:Custom middleware development requirements extend implementation timelines for enterprises with entrenched product information management systems.
- Retailer API fragmentation:Non-standardized data formats across Walmart, Amazon, Target, and Kroger portals force redundant connector maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Shelf Market |
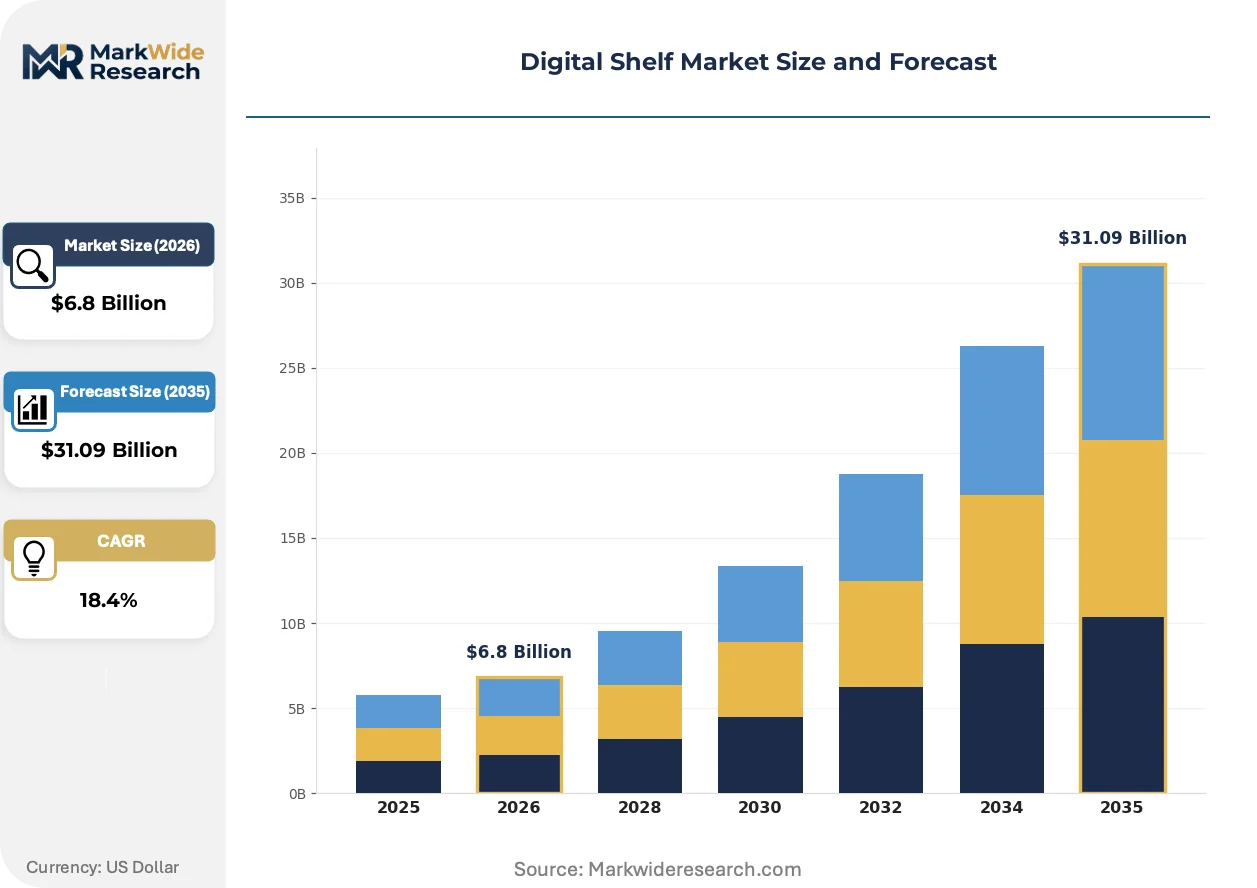
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-commerce Platforms, Digital Merchandising Tools, Inventory Management Solutions, Pricing Optimization Software End User: Retailers, Brand Manufacturers, Third-Party Sellers, Marketplaces Deployment: On-Premises, Cloud-Based, Hybrid Solutions, SaaS Sales Channel: Direct Sales, Distributors, Online Sales, Resellers |
| Companies Covered | Syndigo, Intelligence Node, MetricsCart, Triple Whale, SymphonyAI, Stackline, ChannelAdvisor, Clear Spider, CommerceIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Shelf Market Emerging Trajectories
Artificial intelligence is compressing the latency between competitive signal detection and automated merchandising response, enabling brands to treat digital shelf management as a real-time operational discipline rather than periodic reporting.
Generative AI content engines are modularizing product description and image variant production for multi-retailer syndication. Mid-market CPG brands deploy these tools to maintain content freshness across fragmented portal requirements without expanding creative headcount. The technology is modularizing the economics of long-tail SKU management, previously viable only for enterprise portfolios.
GDPR algorithmic transparency mandates are forcing disclosure of automated decision-making logic in European marketplace operations. Retailers operating in Germany, France, and the Netherlands must document how search ranking and recommendation systems process seller data. Food and beverage brands selling through these channels face expanded audit trails for content personalization workflows.
Subscription-based analytics procurement is replacing perpetual license purchases among digitally native CPG entrants. These buyers prioritize month-to-month flexibility and rapid time-to-value over enterprise feature depth. The pattern concentrates among direct-to-consumer brands scaling through Amazon and Shopify-powered retail partnerships.
Digital Shelf Market Segmentation
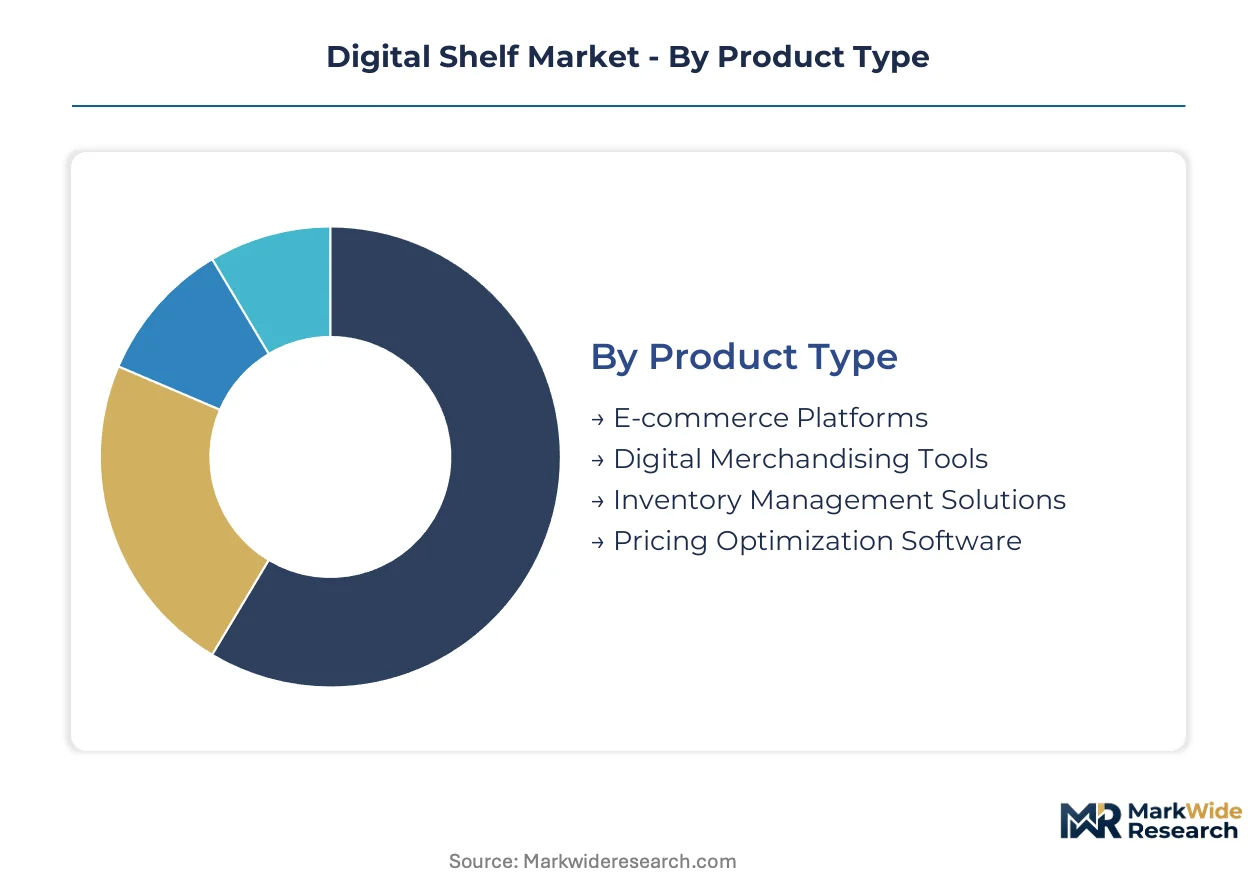
Digital shelf solutions serve heterogeneous buyer profiles with divergent technical capabilities, compliance burdens, and integration requirements. Segmentation reveals how deployment constraints and channel economics reshape vendor go-to-market strategies across fragmented retail ecosystems.
Product Type:
Buyers differentiate by the complexity of their content syndication workflows and the scale of SKU portfolios requiring automation.
- E-commerce Platforms:Unified storefront management systems that embed native analytics for search ranking and conversion funnel optimization. Demand concentrates among mid-market retailers operating multi-brand portfolios on Shopify and WooCommerce, where API-native architectures reduce dependency on specialized IT staff.
- Digital Merchandising Tools:Content optimization engines that automate image variant production, A/B testing, and structured data validation for fragmented retailer requirements. Brand manufacturers in food and beverage verticals prioritize these tools to maintain FDA-compliant health claim formatting across Walmart, Amazon, and Kroger portals.
- Inventory Management Solutions:Real-time stock synchronization systems that prevent oversell events and marketplace penalties.
- Pricing Optimization Software:Algorithmic repricing engines that ingest competitive signals and elasticity models.
Volume sits with E-commerce Platforms; growth tilts toward Digital Merchandising Tools.
End User:
Stakeholder type determines whether procurement prioritizes first-party data control or third-party seller compliance automation.
- Retailers:Multi-brand operators managing proprietary marketplace ecosystems who require shelf health scoring across thousands of third-party seller listings. Walmart and Target invest here to enforce content quality standards and algorithmic search transparency.
- Brand Manufacturers:CPG enterprises syndicating product content across fragmented retailer portals while maintaining regulatory compliance. These buyers drive demand for automated FDA nutrition claim validation and EU Digital Services Act audit trails.
- Third-Party Sellers:Marketplace-native merchants lacking dedicated merchandising teams.
- Marketplaces:Platform operators managing algorithmic ranking systems and sponsored product auctions.
Revenue concentrates with Brand Manufacturers; expansion accelerates fastest among Third-Party Sellers.
Deployment:
Technical infrastructure choices reflect trade-offs between data sovereignty, elastic scaling, and integration latency with existing ERP systems.
- Cloud-Based:Fully managed SaaS architectures with API-native connectivity to PIM and DAM systems. Mid-market CPG brands adopt these deployments to bypass dedicated infrastructure teams while achieving sub-hour competitive pricing refresh cycles.
- SaaS:Subscription-delivered analytics with consumption-based metering and rapid time-to-value. Digitally native DTC brands favor this model for month-to-month flexibility during scaling phases.
- On-Premises:Self-hosted installations retaining complete data control within enterprise firewalls.
- Hybrid Solutions:Split architectures isolating sensitive competitive intelligence on-premise while leveraging cloud elasticity for front-end syndication.
Adoption skews toward Cloud-Based; SaaS claims the steepest expansion trajectory.
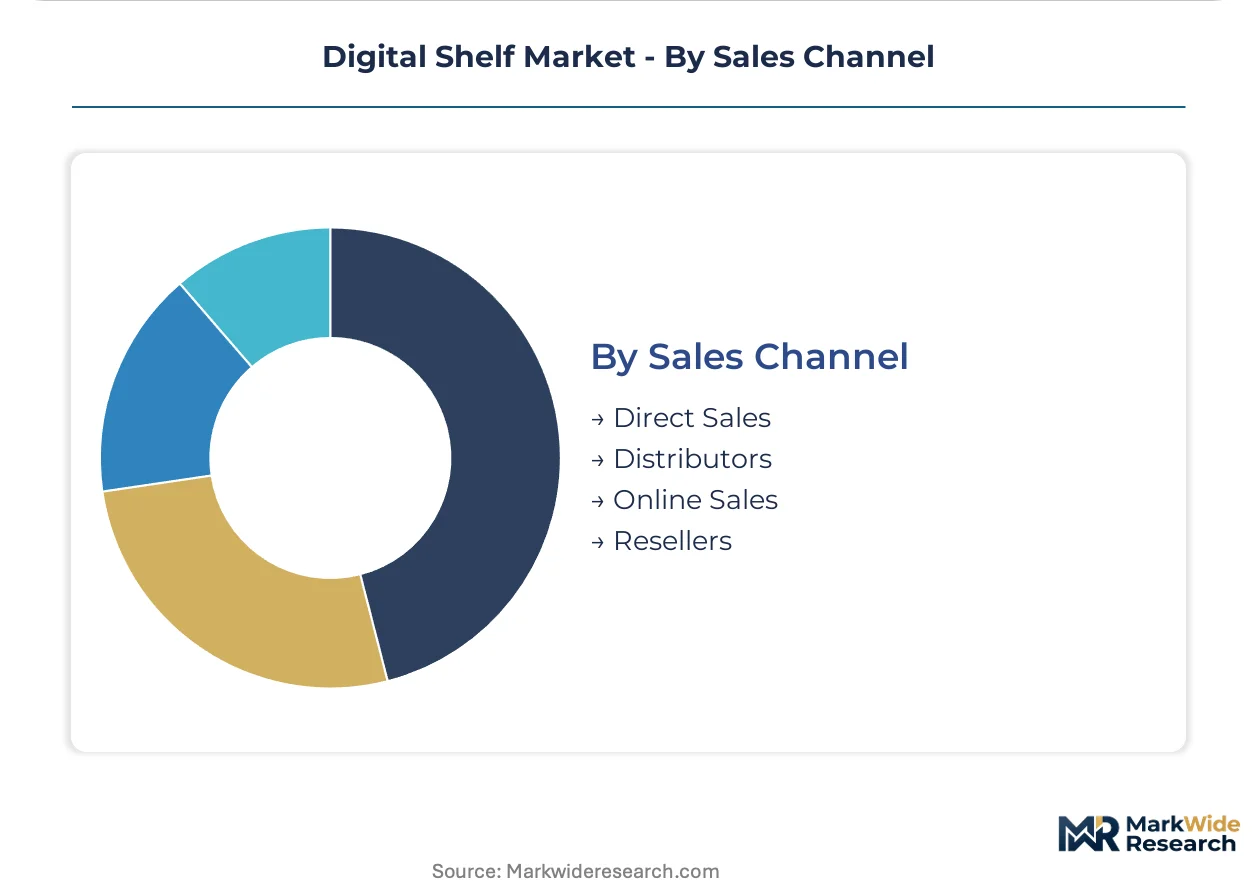
Sales Channel:
Route-to-market economics vary by buyer sophistication and the complexity of implementation services required.
- Direct Sales:Vendor-led enterprise engagements with dedicated customer success and custom integration support. Large brand manufacturers procure through this channel to negotiate SLA terms and regulatory compliance documentation.
- Distributors:Value-added resellers bundling shelf analytics with broader retail technology stacks. Regional system integrators in Europe leverage these relationships to localize GDPR-compliant deployments.
- Online Sales:Self-service procurement portals targeting low-touch mid-market accounts.
- Resellers:Specialized retail technology partners with deep marketplace integration expertise.
Transaction volume flows through Direct Sales; channel development prioritizes Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital shelf solution development concentrates in technology hubs while consumption spreads across retail-dense metropolitan corridors. Cloud infrastructure investments in Seattle, Dublin, and Singapore shape vendor capability distribution. Regulatory divergence between Washington and Brussels fragments compliance architecture design.
United States
Walmart and Amazon marketplace ecosystems drive vendor investment in shelf intelligence tooling across Bentonville and Seattle metro areas. FDA regulations on health and nutrition claims directly shape how food and beverage brands structure digital shelf content for compliance. Austin and Boston clusters host emerging SaaS entrants targeting mid-market CPG brands with API-native deployment models.
Germany
GDPR algorithmic transparency mandates force disclosure of automated decision-making logic in marketplace operations across Berlin and Munich. The EU Digital Services Act imposes content moderation obligations on marketplace operators managing third-party seller listings. Hamburg and Frankfurt retail technology consultancies localize GDPR-compliant deployment architectures for pan-European brand manufacturers.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance burdens for brands operating across UK and EU marketplaces simultaneously. The Competition and Markets Authority scrutinizes platform algorithm opacity with emerging disclosure requirements for search ranking factors. London fintech-retail convergence clusters demand real-time pricing optimization for cross-border e-commerce operations.
India
Flipkart and Reliance JioMart ecosystem growth generates demand for localized content syndication and vernacular search optimization across Bangalore and Mumbai. The FSSAI mandates structured nutritional labeling for packaged food digital listings with specific format requirements. Hyderabad and Pune technology parks host development centers building India-specific shelf analytics modules for price-sensitive market conditions.
China
SAMR oversight of platform algorithm recommendations imposes documentation requirements for search ranking systems on Alibaba and JD.com marketplaces. Dual carbon goals pressure cloud data center energy efficiency standards for shelf analytics infrastructure deployment. Shenzhen and Hangzhou e-commerce technology corridors concentrate domestic vendor development for cross-border export seller tooling.
Digital Shelf Market Vendor Landscape
Capital-heavy platform operators compete with asset-light analytics specialists across the digital shelf ecosystem. The vendor base stratifies between enterprise-grade suite providers and point-solution specialists serving narrow functional requirements. Three archetypes dominate: cloud-native SaaS platforms with API-first architectures, AI-powered competitive intelligence engines, and retail media convergence suites. M&A activity concentrates on tuck-in acquisitions of specialized pricing optimization modules. Strategic partnerships between analytics vendors and cloud hyperscalers accelerate enterprise deployment velocity.
Within the AI-powered competitive intelligence tier, Intelligence Node exemplifies European market penetration through automated benchmarking workflows. Stackline anchors the Walmart-centric integration archetype with first-party data partnerships. CommerceIQ occupies a position at the retail media convergence intersection, combining shelf health scoring with sponsored product campaign management. These three entities represent distinct strategic postures: transatlantic expansion, marketplace-specific depth, and workflow unification respectively.
| Leading Market Players |
|---|
| Syndigo |
| Intelligence Node |
| MetricsCart |
| Triple Whale |
| SymphonyAI |
| Stackline |
| ChannelAdvisor |
| Clear Spider |
| CommerceIQ |
| Others |
Supply Flow & Price Mechanics
Cloud-native SaaS architectures are displacing legacy on-premises installations across retail operations, simultaneously compressing vendor cost structures and concentrating development talent in Seattle, Dublin, and Singapore technology corridors. This infrastructure transition feeds pricing power toward vendors with elastic scaling capabilities while fragmenting supply among specialized API connector developers and hyperscaler compute providers.
Pricing Analysis
Margin tightening in the mid-market tier reflects consumption-based metering displacing perpetual licenses as the dominant pricing model. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade SLA commitments from self-service API tiers. Price differentiation hinges on integration depth with Walmart and Amazon first-party data partnerships versus basic scraping capabilities. Brand manufacturers show highest price sensitivity due to fragmented SKU portfolios, while marketplace operators absorb premium pricing for real-time competitive intelligence.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers mandate qualified API connectivity across multiple data aggregation vendors simultaneously. Development talent concentrates in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in AWS, Azure, and Google Cloud regional data centers. Raw material dependencies include GPU compute cycles for AI-powered competitive benchmarking, residential proxy networks for retailer scraping resilience, and ERP middleware licenses for PIM integration. Single-source vulnerability sits with specialized ML engineering talent pools capable of real-time pricing model construction. Distribution runs through direct enterprise sales teams and value-added resellers bundling shelf analytics with broader retail technology stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure provisioning capacity constrains vendor expansion velocity, propping pricing power for established platforms with hyperscaler allocation commitments. This supply bottleneck favors incumbents with existing elastic scaling contracts over entrants facing compute procurement queues.
For Market Incumbents: Deepen API-native integration architectures to lock in Walmart and Amazon marketplace data partnerships before emerging AI-native entrants achieve competitive latency parity. Prioritize backward integration into proprietary scraping infrastructure to reduce third-party proxy network cost exposure. Consolidate around retail media convergence workflows to capture sponsored product campaign management budgets migrating from standalone ad tech vendors. For New Entrants and Emerging Players: Generative AI content engines for vernacular search optimization represent the most penetrable wedge in India marketplace expansion, where Flipkart and Reliance JioMart ecosystem growth outpaces localized vendor supply. Target third-party seller segments with self-service pricing tiers below incumbent enterprise minimums. Pursue distributor channel partnerships with European system integrators navigating GDPR-compliant deployment requirements as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in tuck-in acquisitions of specialized pricing optimization modules by platform operators seeking workflow unification. Long-term viability favors vendors combining shelf health scoring with retail media optimization rather than point-solution specialists facing feature commoditization. Watch FDA nutrition claim automation tooling penetration as the inflection signal for regulatory compliance moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified shelf analytics and retail media workflows capture CommerceIQ's convergence model. |
| Strategic Partnership | First-party data agreements with Walmart and Amazon anchor Stackline's competitive position. |
| Acquisition of Specialist Firm | Pricing optimization module tuck-ins compress feature gaps for suite providers. |
| Geographic Expansion | India-specific development centers localize content syndication for Flipkart and JioMart ecosystems. |
| Product Launch | AI-powered competitive benchmarking tools differentiate Intelligence Node across European retail networks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with digital shelf software executives, retail technology procurement officers, CPG brand e-commerce directors, and marketplace seller operations managers. FDA guidance documents, EU Digital Services Act implementation notices, and SEC 10-K disclosures from publicly traded retail technology vendors provided regulatory and financial validation. Bottom-up SKU-level deployment estimates triangulated against top-down cloud infrastructure spend allocations across the analysis window.
Segmentation granularity modeled deployment architecture at the infrastructure tier, end-user type at the stakeholder level, and product category at the functional workflow level. CAGRs derived from elasticity-adjusted adoption curves incorporating API integration latency and retailer onboarding friction. Forecast inputs included cloud hyperscaler capex disclosure patterns and CPG brand digital transformation budget allocations across the projection horizon.
Several conditions sit outside the modeled scope, including prospective algorithm transparency mandate expansions beyond current EU Digital Services Act requirements and unilateral retailer API access policy changes. Forecasts reflect assumptions regarding sustained Walmart and Amazon marketplace competitive intensity. Deviation in cloud infrastructure cost inflation or GDPR enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Data Broker Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Global Connected Enterprise Market