
 Docketing Solution Market | 2026-2036
Docketing Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Docketing Solution Market Outlook
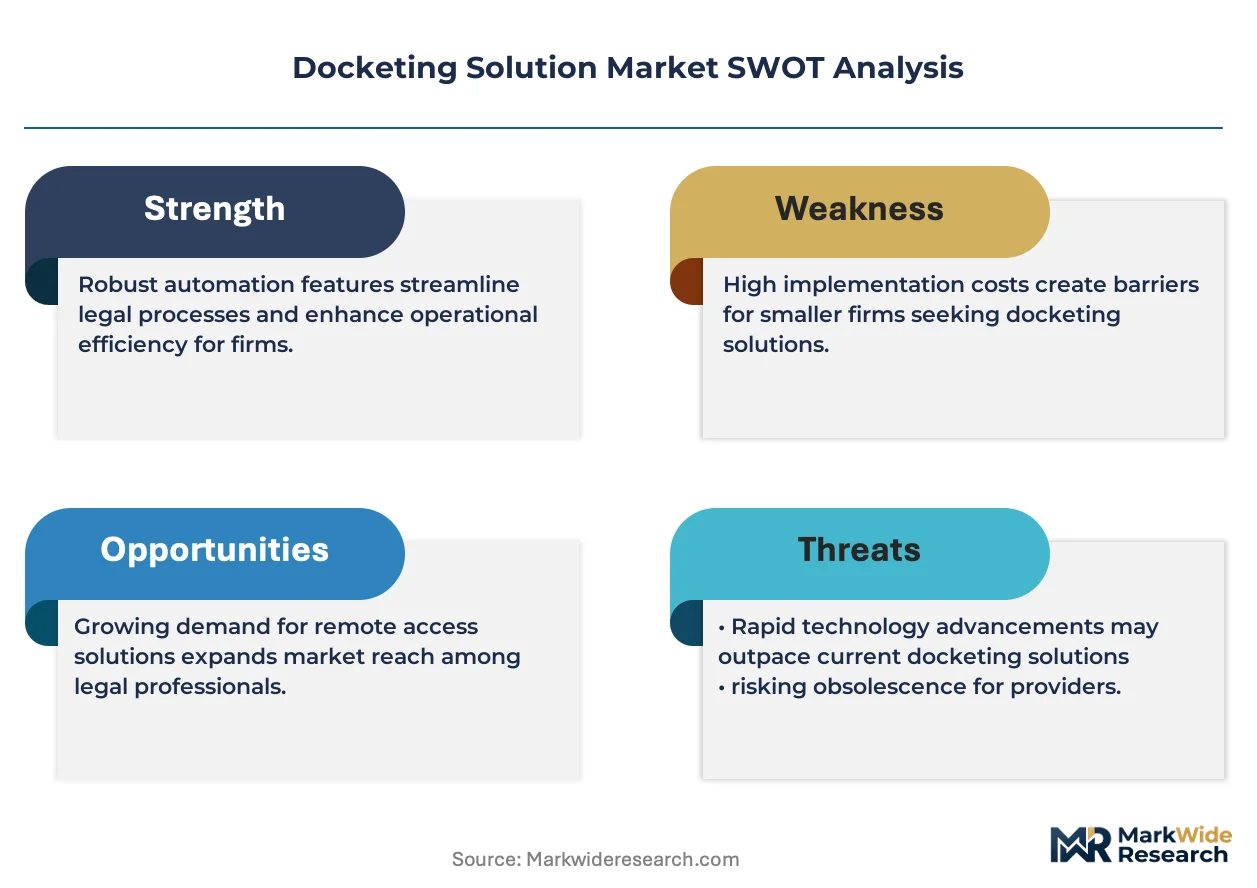
Direct-to-firm software distribution is rewriting how legal technology reaches end users, bypassing traditional value-added resellers and compressing implementation cycles. Anaqua, Inc. leverages deep integration with patent office data feeds to anchor enterprise relationships across Fortune 500 legal departments. Cardinal Intellectual Property Inc. competes through specialized prosecution workflows that sustain margins in high-volume IP practices. TM Cloud differentiates by targeting mid-market law firms with configurable SaaS deployment that reduces upfront infrastructure commitment.
A docketing solution is a specialized software system that tracks statutory deadlines, filing requirements, and procedural milestones across litigation, patent, trademark, and regulatory matters, typically integrating with patent office APIs and court electronic filing systems to automate calendaring and risk alerts. Its primary commercial purpose is to eliminate human error in deadline management, where a single missed filing can void intellectual property rights or trigger sanctions. Cloud-based deployment leads segment expansion as law firms abandon on-premise maintenance burdens, while document automation within functionality segments captures disproportionate margin pools by reducing attorney hours spent on repetitive filing preparation. Corporate legal departments represent the fastest-growing end-user category as in-house teams absorb work previously routed to outside counsel.
The USPTO's electronic filing mandates and the FDA's deadline-driven regulatory submission requirements shape product specifications for docketing vendors serving intellectual property and life sciences clients. GDPR compliance obligations in Europe and state-level data privacy laws in California impose architectural constraints on cloud-hosted solutions handling cross-border client matter. Stakeholders must monitor how patent office API rate limits and AI-assisted docketing claims reshape vendor differentiation and procurement criteria.
Market Dynamics
The USPTO's electronic filing mandate and FDA deadline tracking requirements are compressing implementation cycles and forcing vendors to rebuild core calendaring engines around real-time patent office API feeds rather than batch-processed data updates.
Growth Catalysts
- USPTO Electronic Filing Mandates:The Patent Center system requires automated deadline calculation for patent prosecution workflows, pulling law firms toward integrated docketing platforms that eliminate manual data entry errors.
- Corporate Legal Department Expansion:Fortune 500 in-house teams are absorbing IP prosecution work previously routed to outside counsel, creating direct procurement relationships with SaaS docketing vendors.
- Cloud Migration:Mid-market law firms are abandoning on-premise servers for configurable SaaS deployment models that reduce IT infrastructure overhead and accelerate user onboarding.
Market Restraints
- Patent Office API Rate Limits:USPTO data feed throttling constrains real-time synchronization capabilities for high-volume prosecution practices, forcing vendors to architect expensive caching layers.
- Data Residency Requirements:GDPR compliance obligations and California state privacy laws impose architectural constraints on cloud-hosted solutions handling cross-border client matter.
- Legacy System Integration Costs:Custom connectors for on-premise practice management systems require substantial professional services investment, extending sales cycles for enterprise accounts.
Strategic Opportunities
- Life Sciences Regulatory Expansion:FDA deadline-driven submission requirements for IND and NDA filings create adjacent market expansion beyond traditional IP docketing into pharmaceutical regulatory tracking.
- AI-Assisted Deadline Prediction:Machine learning models trained on historical prosecution data are hybridizing with rules-based calendaring to flag anomalous deadline patterns before they trigger malpractice exposure.
- Mid-Market Channel Innovation:Direct-to-firm software distribution bypassing traditional value-added resellers is compressing implementation cycles and improving vendor margin capture.
Industry Challenges
- Attorney-Technologist Talent Gap:Docketing vendors struggle to hire product managers who understand both patent prosecution workflows and software architecture, slowing feature development cycles.
- Multi-Jurisdiction Complexity:Synchronizing deadlines across PCT national phase entries, EPO opposition windows, and national patent office annuities requires maintaining accurate rule sets for 150+ jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Docketing Solution Market |
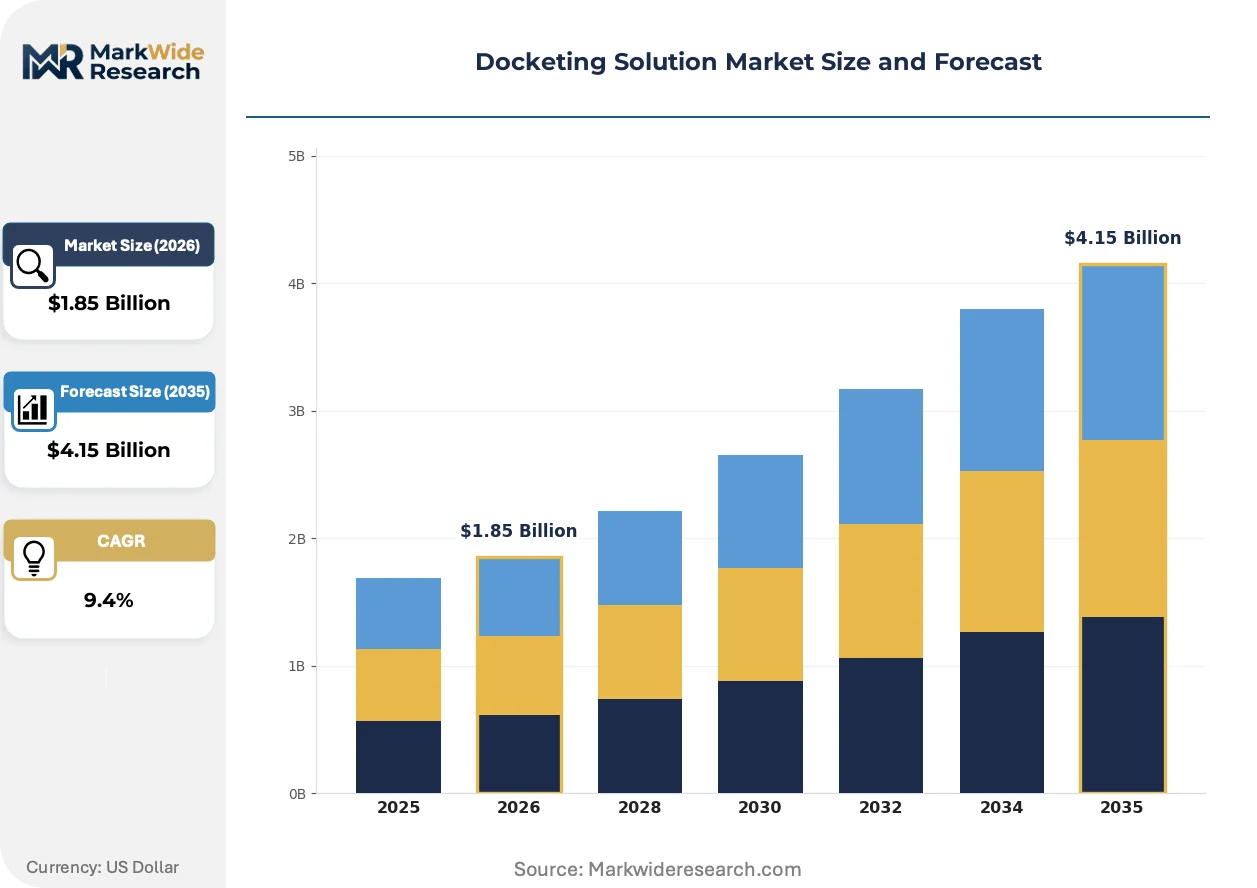
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Law Firms, Corporate Legal Departments, Government Agencies, Compliance Organizations Functionality: Case Management, Document Automation, Calendar Management, Reporting Tools Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups |
| Companies Covered | TM Cloud, FlexTrac, Sagacious IP, MerusCase, American LegalNet, Cardinal Intellectual Property Inc., PracticePanther Legal Case Management, Record Time Pty Ltd., Anaqua, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Docketing Solution Market Strategic Shifts
Artificial intelligence capabilities are penetrating deadline management systems at three distinct layers: predictive risk scoring, automated document generation, and natural language query interfaces that reduce attorney training burdens.
Natural language processing engines trained on patent prosecution histories are hybridizing with traditional rules-based calendaring to identify deadline conflicts invisible to static rule sets. Large law firms with dedicated innovation committees are piloting these hybrid systems for trademark opposition and patent reexamination proceedings. The structural consequence is compression of paralegal review hours previously allocated to manual docket audits.
GDPR Article 44 data transfer restrictions and California's CCPA successor legislation are forcing architectural redesign of cloud-hosted docketing platforms. Vendors must now maintain EU-isolated infrastructure instances and granular consent management for client matter metadata. European corporate legal departments and US firms with EU subsidiaries are driving procurement decisions toward vendors with certified data residency controls.
Subscription pricing models are displacing perpetual license arrangements across the buyer base. Corporate legal departments prefer operational expenditure treatment for compliance software, while mid-market firms value predictable monthly costs over capital-intensive upfront deployment. This shift is most visible in United States markets where law firm partnership structures favor cash flow smoothing over balance sheet asset accumulation.
Docketing Solution Market Segmentation
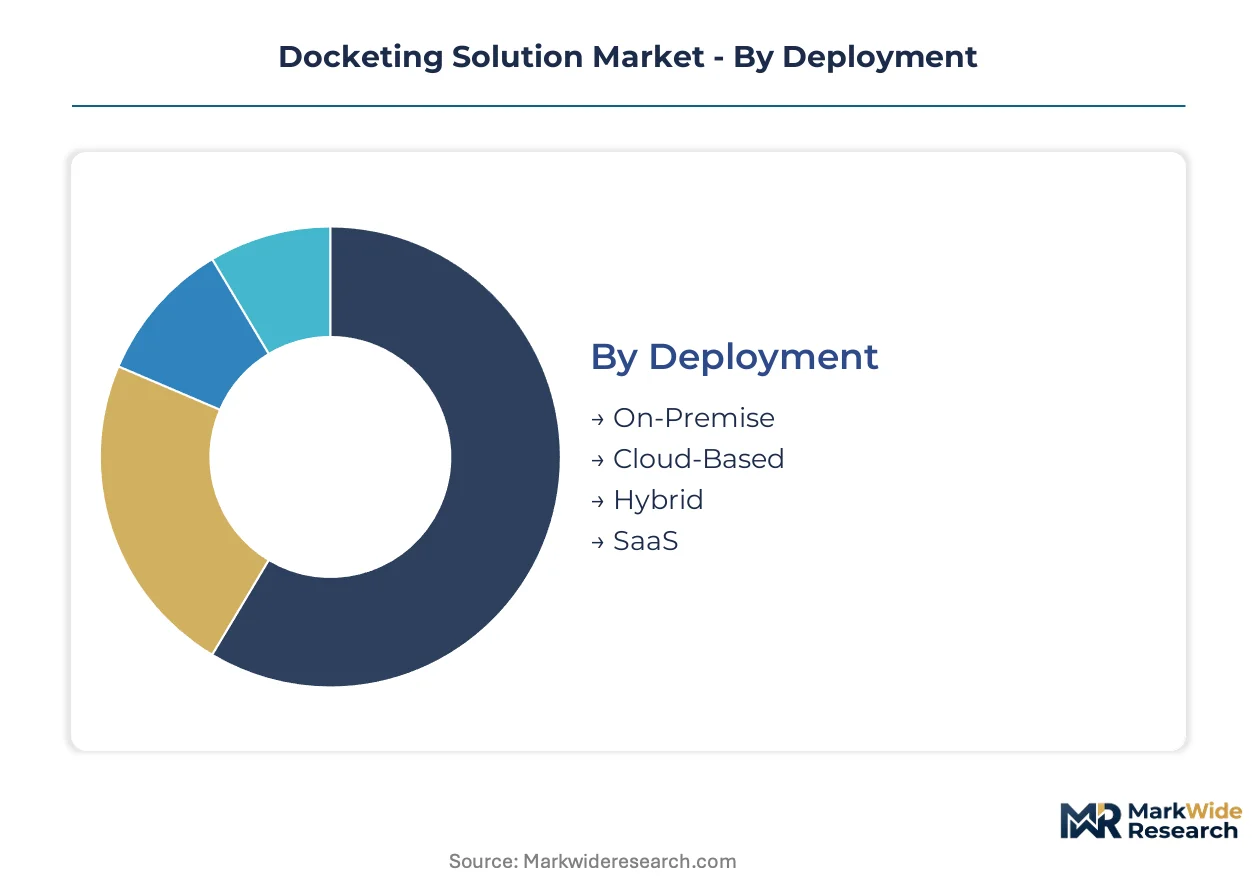
Docketing solutions fragment across deployment architectures, user sophistication, and functional depth. Procurement patterns diverge sharply between legacy on-premise holdouts and cloud-native entrants, while functionality investments track malpractice exposure levels.
Deployment:
Mature on-premise installations coexist with emerging serverless architectures as firms navigate data sovereignty constraints.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute layers eliminate server maintenance overhead for mid-market IP practices. United States law firms in California and New York are migrating fastest due to state bar technology competency mandates.
- SaaS:Subscription-native platforms with API-first designs enable rapid integration with USPTO Patent Center and EPO Online Filing. Corporate legal departments in Texas and Illinois favor this model for predictable operational expenditure treatment.
- On-Premise:Air-gapped installations serving defense contractors and classified patent work.
- Hybrid:Split configurations keeping sensitive matter data local while pushing calendaring logic to cloud.
Cloud-Based handles the majority of new procurement volume; SaaS is climbing the fastest on share as Fortune 500 legal departments consolidate vendors.
End User:
Customer type determines pricing tolerance and integration complexity, with procurement authority shifting from IT to general counsel.
- Corporate Legal Departments:In-house teams at pharmaceutical and technology companies absorb prosecution work previously routed to outside counsel. These buyers demand SOC 2 Type II certification and granular permission hierarchies for multi-jurisdiction portfolios.
- Law Firms:AmLaw 200 practices and boutique IP shops represent the installed base, with partnership structures favoring capital-light SaaS over perpetual licenses.
- Government Agencies:Public sector procurement with FedRAMP compliance requirements.
- Compliance Organizations:Life sciences regulatory affairs teams tracking FDA submission deadlines.
Law Firms retain the largest installed base; Corporate Legal Departments are expanding most quickly as insourcing accelerates.
Functionality:
Feature investment correlates with error cost exposure, driving disproportionate spending toward deadline-critical modules.
- Calendar Management:Rules-based engines calculating statutory deadlines across PCT national phase entries, EPO opposition windows, and USPTO response periods. Machine learning overlays now flag anomalous date patterns before they trigger malpractice claims.
- Document Automation:Template-driven generation of office action responses, IDS filings, and pro hac vice motions. This functionality captures premium pricing by compressing associate hours on repetitive prosecution tasks.
- Case Management:Matter-centric workflow orchestration with client billing integration.
- Reporting Tools:Dashboard analytics for portfolio health and examiner statistics.
Calendar Management anchors vendor pricing power; Document Automation is gaining share fastest as labor arbitrage pressures intensify.
Size:
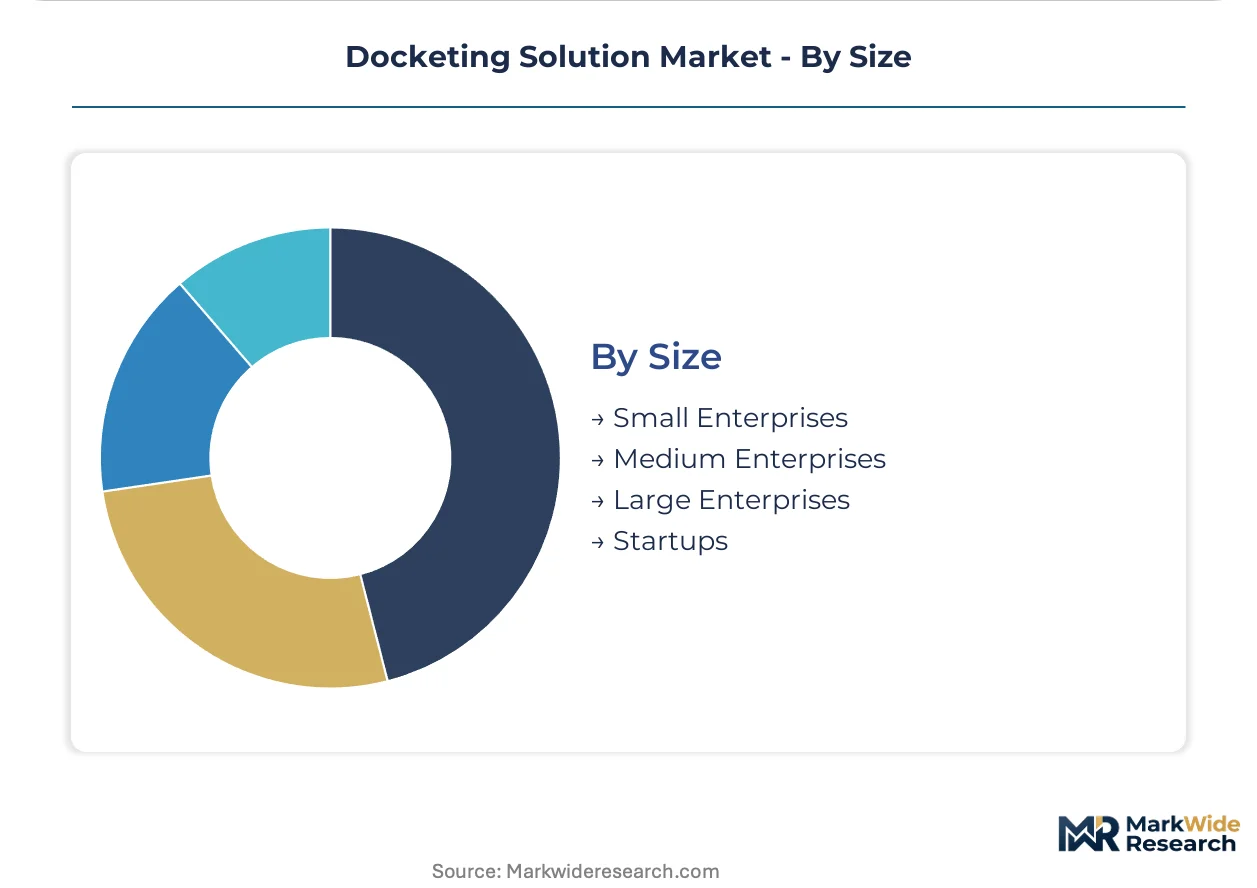
Enterprise scale dictates implementation approach, with mid-market firms driving the steepest expansion trajectory.
- Medium Enterprises:Regional IP boutiques and mid-cap corporate legal teams with 10-50 attorneys. These buyers prioritize configurable SaaS deployment with minimal professional services overhead.
- Large Enterprises:Global law firms and Fortune 500 legal departments with multi-jurisdiction portfolios. Procurement centers on API reliability and custom workflow engineering.
- Small Enterprises:Solo practitioners and micro-firms with basic deadline tracking needs.
- Startups:Venture-backed companies with lean legal infrastructure seeking lightweight compliance tools.
Large Enterprises command the highest contract values; Medium Enterprises are expanding most quickly as cloud migration democratizes access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Patent and Trademark Office's electronic filing infrastructure anchors North American docketing demand, while the European Patent Office's centralized opposition system and China's National Intellectual Property Administration digital platforms shape procurement patterns across major jurisdictions.
United States
Corporate legal departments in Texas and Illinois drive SaaS procurement for patent prosecution workflows. The USPTO Patent Center mandates real-time API integration, forcing vendors to rebuild calendaring engines around live data feeds. Silicon Valley and Boston legal tech clusters host the densest concentration of cloud-native docketing deployments.
China
Domestic law firms in Beijing and Shanghai scale docketing automation to manage surging patent filing volumes. The National Intellectual Property Administration's electronic filing mandates compress implementation timelines for foreign vendors entering the market. Yangtze River Delta manufacturing hubs generate concentrated demand for trademark docketing across consumer electronics and automotive sectors.
Germany
Industrial patent departments in Munich and Stuttgart prioritize deadline management for EPO opposition proceedings. GDPR Article 44 data transfer restrictions force architectural redesign of cloud-hosted platforms serving cross-border corporate clients. Baden-Württemberg automotive suppliers anchor regional demand for integrated IP portfolio tracking.
Japan
Tokyo-based corporate legal teams absorb prosecution work previously routed to outside counsel, creating direct vendor relationships. The Japan Patent Office's electronic filing system shapes product specifications for deadline calculation engines. Osaka pharmaceutical clusters drive adjacent demand for FDA-aligned regulatory tracking modules.
United Kingdom
London financial services legal departments invest in automated calendaring for trademark portfolio management across European subsidiaries. Post-Brexit regulatory divergence complicates deadline synchronization for UK-EU parallel filings. Southeast England technology corridors host the fastest-growing mid-market law firm adoption of configurable SaaS deployment.
Docketing Solution Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower functional depth. The vendor base clusters around three strategic archetypes: enterprise suite providers with patent office data feed integration, mid-market SaaS vendors with rapid deployment models, and niche specialists in life sciences regulatory tracking. Consolidation pressure intensifies as corporate legal departments demand unified deadline management across IP and compliance domains. M&A activity targets API reliability capabilities and vertical workflow expertise.
Within the enterprise platform tier, Anaqua, Inc. and Cardinal Intellectual Property Inc. anchor high-value procurement relationships with Fortune 500 legal departments. TM Cloud occupies a position in the mid-market configurable SaaS segment, exemplifying deployment models that reduce upfront infrastructure commitment for regional IP boutiques.
| Leading Market Players |
|---|
| TM Cloud |
| FlexTrac |
| Sagacious IP |
| MerusCase |
| American LegalNet |
| Cardinal Intellectual Property Inc. |
| PracticePanther Legal Case Management |
| Record Time Pty Ltd. |
| Anaqua, Inc. |
| Others |
Value Chain & Pricing Dynamics
Silicon Valley's cloud infrastructure concentration shapes downstream pricing power for docketing vendors, as compute costs and API reliability directly determine SaaS tier viability and margin capture across deployment models.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement from mid-market subscriptions, with Fortune 500 legal departments locking multi-year contracts at scale while regional boutiques absorb per-seat premiums. Certification level—particularly SOC 2 Type II and FedRAMP authorization—drives price stratification across premium, standard, and economy tiers. Cost compression in the mid-market segment is intensifying because configurable SaaS deployment reduces switching friction. Corporate legal departments demonstrate lowest price sensitivity due to malpractice exposure, whereas solo practitioners face acute budget constraints.
Supply Chain Analysis
Contract-manufacturing concentration for cloud infrastructure rests with hyperscale providers in the United States, Ireland, and Singapore, where data center capacity determines regional service availability. Software development draws from specialized talent pools in India and Eastern Europe for backend engineering, with US-based patent technologists commanding premium compensation. Single-source vulnerability emerges from USPTO API rate limiting, which constrains real-time synchronization capabilities. Distribution runs through direct-to-firm channels that bypass traditional value-added resellers, compressing implementation cycles and improving vendor margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of product managers fluent in both patent prosecution workflows and software architecture creates structural bottlenecks that favor incumbents with embedded institutional knowledge and complicates new entrant scaling.
For Market Incumbents: Build data feed moats through exclusive USPTO API integration partnerships that lock out competitors from real-time patent office synchronization. Invest in backward integration into AI-assisted deadline prediction models trained on proprietary prosecution histories. Defensive consolidation should target niche regulatory tracking specialists in life sciences to preempt cross-domain entrants from capturing FDA-aligned workflows. For New Entrants and Emerging Players: Establish a beachhead in mid-market trademark boutiques underserved by enterprise-focused suite providers, where configurable deployment and rapid onboarding create switching momentum. White-space concentration sits in European GDPR-compliant instances for US firms with EU subsidiaries, where data residency requirements have fragmented vendor options. Go-to-market leverage centers on channel partnerships with state bar technology competency programs in California and New York. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-automation play because regulatory filing mandates across patent offices and pharmaceutical regulators create irreversible demand for deadline management infrastructure. Target acquisition archetypes include vertical workflow specialists with deep EPO opposition expertise or FDA regulatory tracking modules. The signal to watch is USPTO Patent Center API expansion announcements, which would reset competitive positioning around real-time data feed access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep USPTO Patent Center API connectivity eliminates manual data entry errors for prosecution workflows. |
| Acquisition of Specialist Firm | Life sciences regulatory tracking expertise expands addressable market into FDA submission deadline management. |
| Product Launch | GDPR-compliant EU-isolated infrastructure instances unlock procurement from US firms with European subsidiaries. |
| Strategic Partnership | State bar technology competency alliances accelerate mid-market adoption through continuing education channels. |
| Geographic Expansion | Beijing and Shanghai law firm penetration captures surging patent filing volumes under CNIPA electronic mandates. |
Study Parameters
Desk research of patent office regulatory filings, legal technology trade publications, and cloud software SEC disclosures preceded structured interviews with IP operations directors, docketing system administrators, corporate legal department procurement officers, and patent office technology liaison staff. Primary intelligence combined with secondary validation across USPTO Patent Center documentation, EPO Online Filing system specifications, and FDA regulatory guidance databases. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Assumption sets held USPTO electronic filing mandate timelines and cloud migration adoption curves fixed while varying corporate legal department insourcing rates and AI feature penetration scenarios. Segmentation dimensions modeled include deployment architecture, organization size tier, functionality module depth, and jurisdictional complexity level. CAGRs derived from historical procurement pattern analysis and forward-looking technology adoption S-curves, with patent prosecution volume trends and regulatory deadline density serving as industry-specific forecast inputs.
Stress conditions across USPTO API rate limit changes, GDPR enforcement intensity variations, and corporate legal department budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that patent office system outages or regulatory filing mandate delays could materially revise trajectory. Quarterly review of USPTO technology roadmap disclosures and state bar technology competency mandate adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Super Apps Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Latin America and Europe Digital Signature Market