
 E-Ink E-Reader Market | 2026-2036
E-Ink E-Reader Market Size, Share, and Industry Trends Forecast 2026-2036
E-Ink E-Reader Market Insights
Taiwan is fragmenting as a manufacturing base for E Ink Holdings and downstream assemblers. Amazon leverages its Kindle ecosystem and Prime integration to sustain recurring content revenue. Kobo anchors its position through Rakuten's loyalty infrastructure and broad international bookstore coverage.
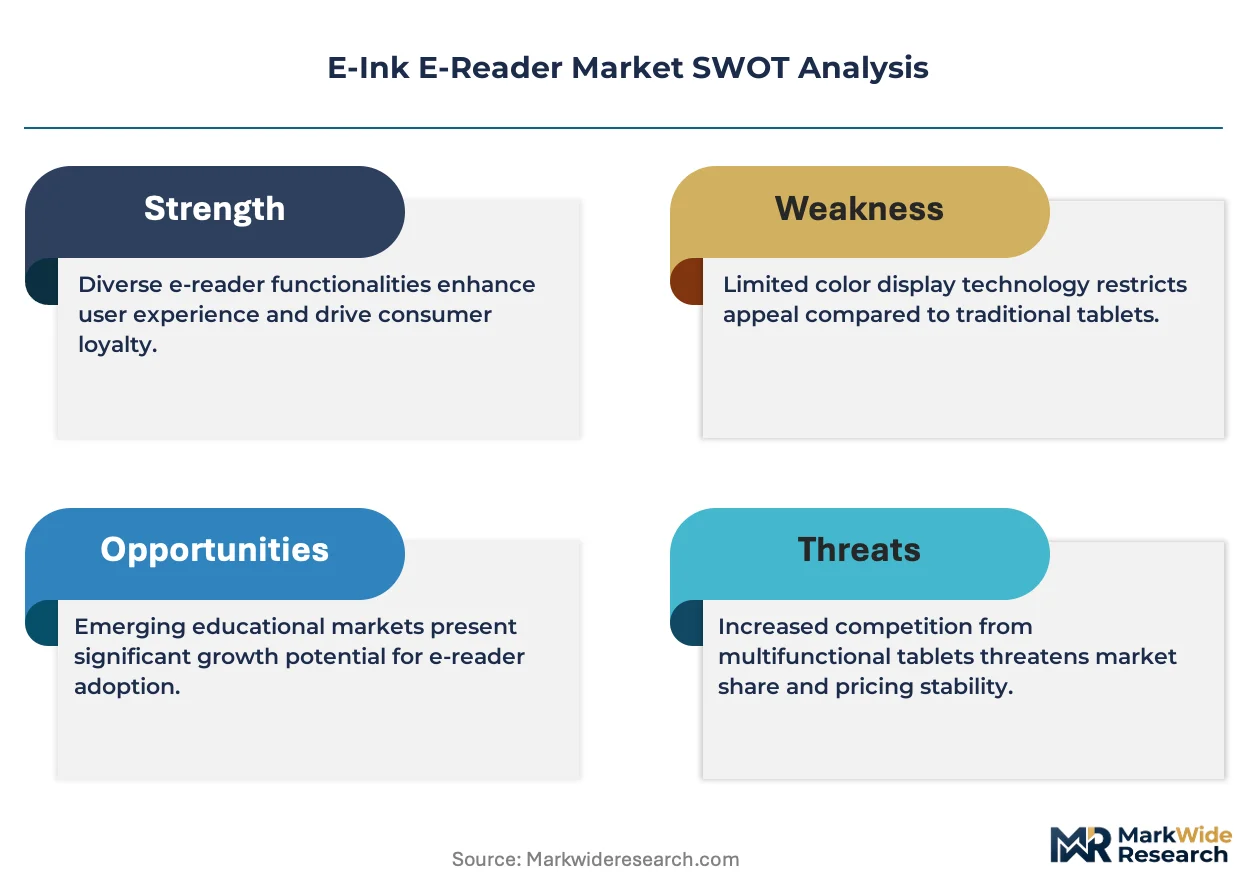
An E-Ink E-Reader employs electrophoretic display technology comprising microcapsules suspended in fluid, each containing negatively charged black particles and positively charged white particles that rearrange under electric fields to form grayscale images without backlighting. The technology eliminates refresh-induced eye strain and maintains static images at zero power draw, making it purpose-built for prolonged text consumption. E-Ink Carta dominates the premium device tier with higher contrast ratios and faster refresh rates, while Color E-Ink represents the fastest-growing display technology as publishers push illustrated content and academic textbooks toward digital formats. Educational Institutions within the Customer Type dimension command disproportionate procurement volumes through district-level and university-wide licensing agreements.
The EPA's ENERGY STAR program and the EU Ecodesign for Sustainable Products Regulation both impose standby power limits and material disclosure requirements on electronic display devices sold in their respective jurisdictions. Japan's METI enforces top-runner efficiency standards that effectively filter lower-performing display technologies from the domestic market. Stakeholders must weigh Color E-Ink yield improvements against front-lit monochrome alternatives as battery life and manufacturing cost trade-offs determine next-generation product roadmaps.
Market Dynamics
Color E-Ink yield improvements are compressing monochrome front-lit alternatives as manufacturers weigh battery life trade-offs against manufacturing cost curves in next-generation roadmaps.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Tightening energy efficiency standards for electronic displays accelerate replacement cycles for aging LCD-based reading devices in European institutional procurement.
- Educational textbook digitization:Publishers pushing illustrated content toward digital formats expand addressable hardware demand beyond text-only fiction readers.
- Japan:Aging demographics favor lightweight, eye-friendly devices for extended reading sessions, creating concentrated demand pull for large-form-factor E-Ink hardware.
Market Restraints
- Microcapsule supply concentration:Electrofluidic display component manufacturing clusters tightly in East Asian foundries, exposing downstream assemblers to single-source risk.
- Color E-Ink refresh latency:Technical limitations in particle rearrangement speed constrain video-capable applications, capping expansion beyond static document consumption.
- US EPA ENERGY STAR standby limits:Compliance testing timelines extend product certification cycles, delaying go-to-market windows for front-lit monochrome refreshes.
Strategic Opportunities
- Academic library district licensing:North American university system procurement aggregates volume through multi-campus agreements, bypassing retail channel fragmentation.
- Rakuten loyalty infrastructure convergence:Points-based ecosystem integration creates switching costs that hardware-agnostic competitors cannot replicate.
- Japan METI top-runner standards:Efficiency filtering mechanisms clear lower-performing display technologies from domestic shelves, reserving shelf space for premium E-Ink variants.
Industry Challenges
- Electrophoretic display engineering talent:Specialized microcapsule fluid dynamics expertise concentrates in legacy semiconductor regions, constraining R&D expansion.
- Front-lighting module integration complexity:Edge-lit LED uniformity requirements demand precision assembly capabilities that contract manufacturers struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Ink E-Reader Market |
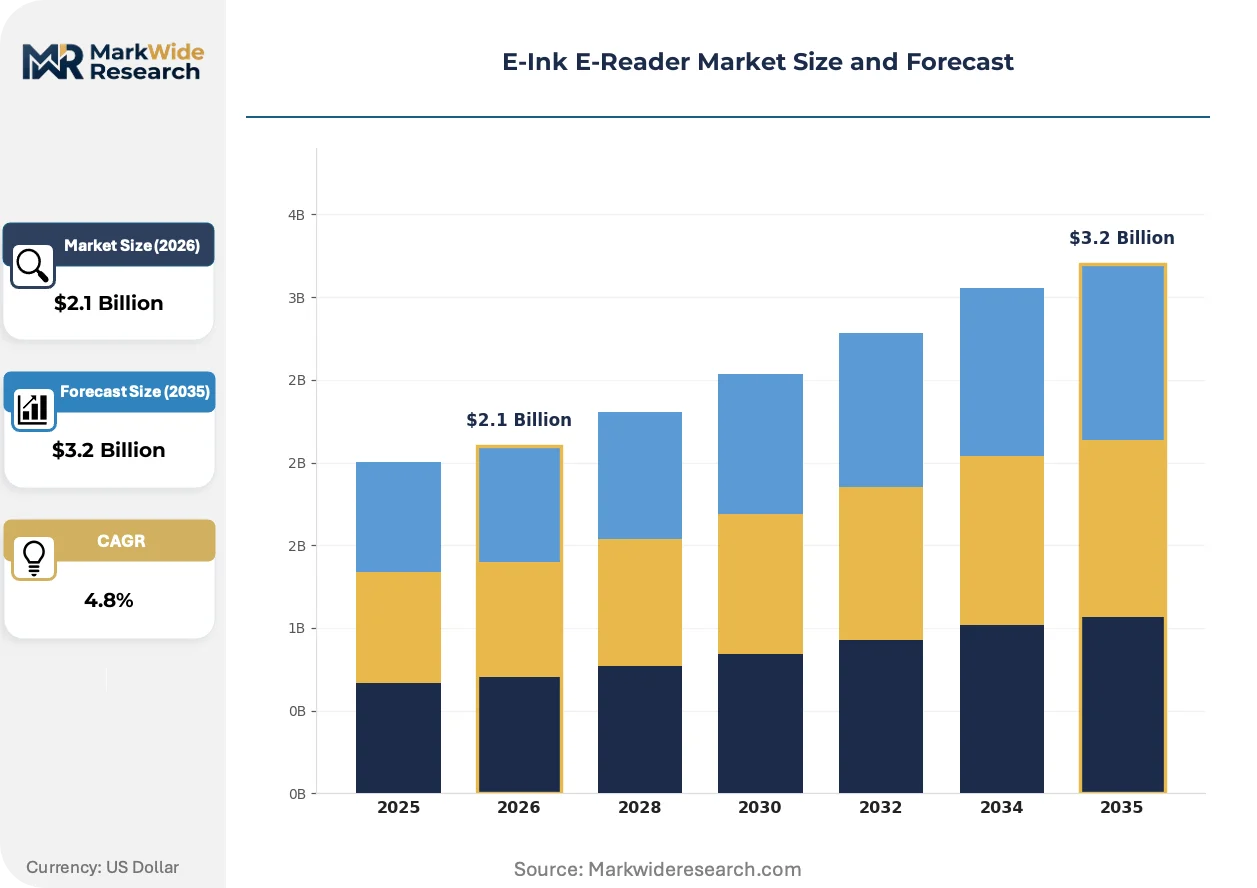
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
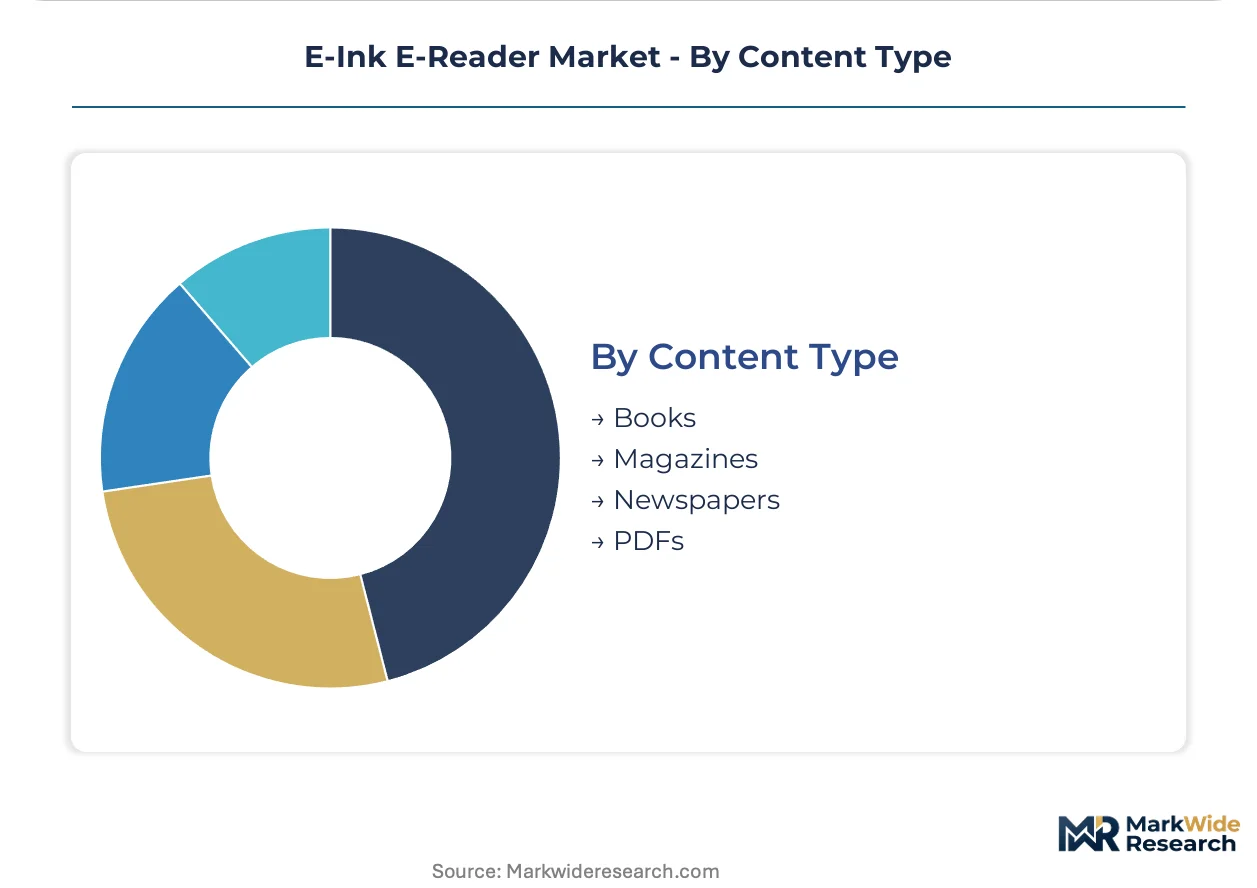
| Segmentation | Product Type: E-Readers, Tablets, Accessories, Software Customer Type: Individual Consumers, Educational Institutions, Libraries, Corporate Users Display Technology: E-Ink Carta, E-Ink Pearl, Color E-Ink, Front-lit Content Type: Books, Magazines, Newspapers, PDFs |
| Companies Covered | Amazon, Kobo, Barnes & Noble, PocketBook, Onyx Boox, Sony, Bookeen, Tolino, Bigme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Ink E-Reader Market Trends and Innovations
Display technology roadmaps are diverging as manufacturers balance color particle density against power draw, while procurement channels consolidate around institutional buyers with multi-year replacement schedules.
E-Ink Carta is migrating from premium monochrome positioning toward mid-tier standardization as educational institutions adopt district-level licensing. Higher contrast ratios and faster refresh rates now define baseline expectations rather than premium differentiation. This compression is forcing front-lit alternatives into narrower outdoor-specialist niches.
The EU Ecodesign for Sustainable Products Regulation imposes material disclosure requirements and standby power ceilings on electronic display devices sold in member states. Manufacturers must redesign power management circuits and submit component traceability documentation. Premium device tiers absorb compliance costs most readily, widening the gap against economy imports.
Library consortium procurement aggregates demand through centralized acquisition committees that negotiate multi-year replacement cycles. Retail channel disintermediation accelerates as academic and municipal buyers bypass consumer electronics distributors. Japan's aging reader base exhibits this pattern most visibly, with public library systems driving hardware refresh decisions.
E-Ink E-Reader Market Segmentation
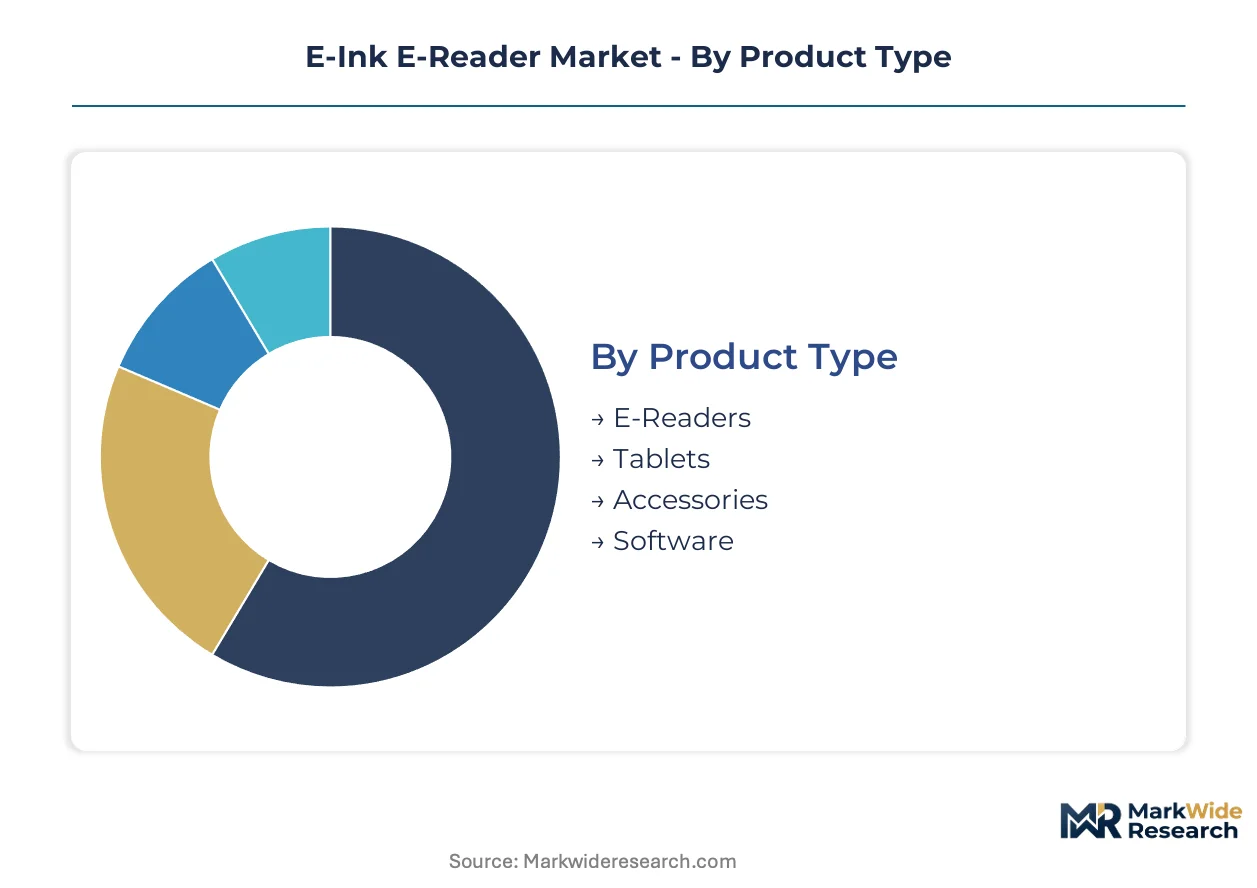
E-Ink E-Reader market segmentation reveals how procurement channels and display specifications diverge across use cases. Understanding these divisions exposes where volume concentrates and which technology tiers command premium positioning.
Product Type:
Mature hardware categories now compete with emerging software and service layers for margin capture.
- E-Readers:Dedicated single-function devices employing electrophoretic displays with zero static power draw. Japan's aging demographics drive concentrated demand for large-form-factor hardware in municipal library systems.
- Tablets:Multi-function slates with E-Ink variants competing against LCD alternatives in note-taking and document review applications. Educational Institutions in North America aggregate procurement through district-level licensing agreements that bypass retail fragmentation.
- Accessories:Protective cases, styluses, and charging docks extending device utility.
- Software:Content management platforms and annotation tools generating recurring revenue streams.
E-Readers handle the majority of throughput; Software is expanding most quickly on share as hardware margins compress.
Customer Type:
Volume concentration shifts from fragmented retail consumers toward institutional buyers with multi-year replacement schedules.
- Individual Consumers:Fragmented retail purchasers selecting devices through Amazon's Kindle ecosystem or Rakuten's Kobo infrastructure. Prime integration and points-based loyalty programs create switching costs that hardware-agnostic competitors cannot replicate.
- Educational Institutions:District-level and university-wide licensing agreements aggregating procurement volumes. Publishers pushing illustrated content toward digital formats expand addressable hardware demand beyond text-only applications.
- Libraries:Centralized acquisition committees negotiating multi-year replacement cycles. North American academic library systems increasingly bypass consumer electronics distributors through consortium procurement.
- Corporate Users:Enterprise document review and contract management applications requiring eye-friendly extended reading sessions.
Educational Institutions dominate absolute procurement volumes; Libraries are climbing the fastest on institutional share.
Display Technology:
Technology roadmaps diverge as manufacturers balance color particle density against power draw constraints.
- E-Ink Carta:Premium monochrome tier with higher contrast ratios and faster refresh rates. EU Ecodesign standby power ceilings and material disclosure requirements filter lower-performing alternatives from European institutional procurement.
- Color E-Ink:Fastest-growing display category as microcapsule yield improvements compress manufacturing cost curves. Technical limitations in particle rearrangement speed constrain video-capable applications, capping expansion beyond static document consumption.
- E-Ink Pearl:Legacy monochrome standard migrating toward economy positioning.
- Front-lit:Edge-lit LED modules enabling low-light reading with precision assembly requirements that contract manufacturers struggle to scale.
E-Ink Carta retains the majority of premium tier shipments; Color E-Ink shows the steepest expansion trajectory as textbook digitization accelerates.
Content Type:
Format specialization determines hardware specifications across consumer and institutional segments.
- Books:Text-dominant fiction and non-fiction consuming minimal display refresh cycles. Japan's public library systems drive hardware refresh decisions for extended reading sessions.
- Magazines:Illustrated periodicals requiring color display capabilities or grayscale dithering compromises.
- Newspapers:Daily periodical subscriptions integrated into Amazon and Rakuten content ecosystems.
- PDFs:Fixed-layout documents demanding larger screen formats for readable text rendering at standard zoom levels.
Books handle the majority of consumption hours; PDFs are gaining share fastest in corporate and academic procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microcapsule electrofluidic component manufacturing clusters tightly in East Asian foundries, exposing downstream assemblers to single-source risk while regulatory filtering mechanisms in developed economies reshape competitive access.
United States
Academic library consortiums aggregate procurement through centralized acquisition committees negotiating multi-year replacement cycles. The EPA's ENERGY STAR program imposes standby power limits on electronic display devices, extending product certification timelines. Greater Boston and Pacific Northwest research clusters drive institutional pilot programs for large-form-factor E-Ink hardware in university systems.
Japan
Aging demographics favor lightweight, eye-friendly devices for extended reading sessions in municipal library systems. METI enforces top-runner efficiency standards that filter lower-performing display technologies from domestic shelves. Tokyo and Osaka metropolitan areas concentrate public sector hardware refresh decisions, with Kanto region library systems driving premium device procurement volumes.
Germany
Educational textbook digitization expands addressable hardware demand beyond text-only applications in federal-state procurement frameworks. The EU Ecodesign for Sustainable Products Regulation imposes material disclosure requirements and standby power ceilings on electronic displays. Bavaria and Baden-Württemberg industrial clusters host precision assembly capabilities for edge-lit LED module integration.
Taiwan
E Ink Holdings anchors upstream electrophoretic display component supply for downstream global assemblers. National semiconductor infrastructure supports specialized microcapsule fluid dynamics expertise concentrated in legacy manufacturing regions. Hsinchu Science Park and Tainan Technology Industrial Park host foundry operations critical to color particle yield improvement roadmaps.
United Kingdom
Publisher migration of illustrated content toward digital formats creates pull for color-capable hardware in educational procurement. REACH and RoHS compliance requirements filter component sourcing for devices sold in member state markets. London and Southeast England concentrate content platform development and academic licensing negotiation functions.
E-Ink E-Reader Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling microcapsule supply and front-lighting module specifications. The vendor structure organizes around three strategic archetypes: ecosystem-locked platforms with content integration, hardware-agnostic assemblers sourcing commodity displays, and captive component manufacturers with proprietary electrofluidic technology. Competitive moves concentrate on vertical integration into microcapsule production and geographic expansion through institutional procurement channels bypassing retail fragmentation.
Among ecosystem-anchored platform operators, Amazon and Kobo exemplify divergent loyalty infrastructure strategies, while Onyx Boox occupies a position within the hardware-specialist tier serving document-intensive professional segments. These three anchors illustrate how competitive positioning stratifies between content-integrated platforms and display-agnostic device fabricators.
| Leading Market Players |
|---|
| Amazon |
| Kobo |
| Barnes & Noble |
| PocketBook |
| Onyx Boox |
| Sony |
| Bookeen |
| Tolino |
| Bigme |
| Others |
Pricing and Supply Chain Analysis
Single-source microcapsule dependency in East Asian foundries compresses pricing tier spreads while forcing downstream assemblers into captive supply arrangements or premium qualification premiums. EU Ecodesign standby power ceilings and material disclosure mandates widen the gap between certified premium tiers and economy imports that cannot absorb compliance overhead.
Pricing Analysis
The EU Ecodesign for Sustainable Products Regulation dictates the pricing tier structure across European institutional procurement, with standby power certification and component traceability documentation separating premium E-Ink Carta devices from uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects contrast ratio performance, front-lighting module integration, and battery endurance specifications. Pricing pressure stems from Color E-Ink yield improvements compressing monochrome alternatives as manufacturers balance particle density against power draw trade-offs. Educational Institutions exhibit highest price sensitivity through aggregated district licensing negotiations, while individual consumers in Japan's municipal library systems show lowest sensitivity due to replacement cycle centralization.
Supply Chain Analysis
Export-control restrictions on electrofluidic display manufacturing equipment limit technology transfer to alternative production geographies, reinforcing Taiwan's grip on microcapsule supply. Taiwan, Japan, and South Korea concentrate upstream electrophoretic component fabrication, with Hsinchu Science Park and Tainan Technology Industrial Park hosting critical foundry operations. Raw material dependencies center on proprietary microcapsule suspensions, edge-lit LED modules, and precision fluid dynamics engineering talent. Single-source vulnerability pervades the supply chain as E Ink Holdings controls core electrophoretic technology licensing. Distribution runs through institutional procurement channels that bypass retail fragmentation, with academic library consortiums and municipal systems aggregating volume through centralized acquisition committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized microcapsule fluid dynamics expertise concentrates in legacy semiconductor regions, constraining R&D expansion and creating defensive moats for incumbents with captive engineering pipelines.
For Market Incumbents: Harden supply chain resilience through backward integration into microcapsule production or long-term offtake agreements with Taiwan-based foundries, while accelerating Color E-Ink yield roadmaps to preempt monochrome margin erosion from educational procurement shifts. Lock in institutional channel control through multi-year district licensing templates that embed switching costs via annotation software and content ecosystem integration. For New Entrants and Emerging Players: North American academic library consortiums present the most penetrable white-space target, as centralized acquisition committees seek alternatives to Amazon and Rakuten ecosystems for large-form-factor hardware pilots. Enter through hardware-agnostic positioning emphasizing PDF rendering performance and open annotation standards, avoiding direct content ecosystem competition. For Investors and Strategic Acquirers: Japan's METI top-runner efficiency standards reshape the acquisition landscape by filtering lower-performing display technologies from domestic shelves, reserving shelf space for premium E-Ink variants with proven power management circuits. Target component specialists with proprietary electrofluidic technology and established foundry relationships rather than hardware-assemblers facing margin compression. Monitor Color E-Ink refresh latency breakthroughs as the signal indicating expansion potential beyond static document consumption into video-capable applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcapsule Production | Captive supply of electrofluidic components insulates against Taiwan foundry concentration risk. |
| Color E-Ink Yield Improvement Program | Manufacturing cost compression accelerates textbook digitization hardware replacement cycles. |
| Academic Library Consortium Partnership | Centralized procurement committees aggregate volume and bypass retail channel fragmentation. |
| EU Ecodesign Certification Investment | Compliance with standby power ceilings filters uncertified competitors from institutional tenders. |
| Front-Lighting Module Precision Assembly Scale-Up | Edge-lit LED uniformity capabilities capture premium tier positioning in low-light applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with E Ink Holdings engineering directors, downstream device assembler procurement leads, North American academic library acquisition committee members, and Japanese municipal library system administrators. Secondary validation drew from EPA ENERGY STAR certification databases, EU Ecodesign regulatory filings, METI efficiency standard publications, and SEC disclosures from listed ecosystem platform operators. Bottom-up demand aggregation across customer type segments was triangulated against top-down market sizing from component shipment data and foundry capacity utilization reports.
Calibration against historical replacement cycles and procurement lead times anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer type, display technology tier, and content format specialization, with regional regulatory cluster and institutional procurement channel structure as cross-cutting variables. CAGRs were derived from installed base turnover analysis and volume-weighted average replacement intervals. Forecast inputs incorporated Color E-Ink yield improvement trajectories and EU Ecodesign compliance cost absorption rates by device tier.
Practitioners should monitor microcapsule supply disruptions, regulatory deadline accelerations, and refresh latency breakthroughs for early signals of forecast deviation. Forecasts reflect assumptions around stable Taiwan foundry output and gradual Color E-Ink cost compression. Material shifts in export-control regimes or particle rearrangement speed improvements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Digital BSS Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market