
 Observability Platform Market | 2026-2036
Observability Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Observability Platform Market Analytics
The Observability Platform Market is shifting between premium full-stack suites and commodity point solutions as buyers reassess tool sprawl versus consolidation trade-offs. Datadog leverages its unified platform architecture to capture enterprise renewals. Elastic anchors its position through open-source distribution and search-native telemetry pipelines. Dynatrace differentiates via AI-driven root-cause automation for Kubernetes environments.
An observability platform aggregates logs, metrics, and traces into correlated telemetry streams, typically ingesting data through OpenTelemetry agents or vendor-specific collectors at throughput rates exceeding terabytes per hour. Cloud-based deployment now leads adoption as organizations prioritize elastic scaling over capital-intensive on-premises infrastructure, while APM and log management command the largest margin pools due to their criticality in incident response workflows.
FDA oversight of software-as-medical-device systems and HIPAA audit requirements shape telemetry retention and access controls for healthcare observability buyers in the United States. The EU AI Act and GDPR impose algorithmic transparency and data residency constraints that vendors must architect around for European deployments. Stakeholders should monitor evolving OpenTelemetry standardization and regional data-sovereignty rulings to anticipate compliance-driven procurement cycles.
Market Dynamics
OpenTelemetry standardization is compressing vendor lock-in advantages and forcing observability providers to differentiate on analytics depth rather than data ingestion control. This technical shift redistributes value from proprietary collectors to correlation engines and AI-driven insight layers.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic audit requirements in Europe are compelling enterprises to deploy telemetry systems capable of real-time model performance tracking and explainability logging for high-risk AI deployments.
- Kubernetes-native infrastructure expansion:Container orchestration adoption across financial services and e-commerce sectors is generating exponential trace volumes that legacy monitoring tools cannot economically process.
- Germany's legacy modernization wave:Mittelstand manufacturers and automotive suppliers are replacing siloed mainframe monitoring with unified platforms to support Industry 4.0 connected-factory initiatives.
Market Restraints
- Cloud egress cost volatility:Telemetry data transfer fees from hyperscale providers consume 15-30% of total observability budgets, creating unpredictable spending spikes during incident investigations.
- Collector software concentration:The OpenTelemetry project and three dominant commercial distributors control critical instrumentation libraries, creating single-point-of-failure risks for standardized data pipelines.
- Retention compliance friction:Conflicting HIPAA, GDPR, and SEC record-keeping requirements force buyers to maintain redundant storage architectures that duplicate infrastructure costs.
Strategic Opportunities
- Edge computing telemetry gaps:Distributed manufacturing sites and autonomous vehicle fleets in Japan and South Korea lack mature observability tooling for low-bandwidth, high-latency environments.
- FinOps-observability convergence:Cloud cost management platforms are integrating with telemetry pipelines to attribute infrastructure spending to specific services and teams.
- India's data localization mandates:RBI and CERT-In requirements for financial sector data residency are creating demand for sovereign-hosted observability infrastructure that global vendors must address through local partnerships.
Industry Challenges
- Site reliability engineering talent scarcity:Organizations struggle to hire engineers proficient in distributed systems debugging, SLO-based alerting, and chaos engineering methodologies.
- Multi-cloud instrumentation fragmentation:Vendor-specific agent incompatibilities force platform teams to maintain parallel telemetry stacks across AWS, Azure, and GCP environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Observability Platform Market |
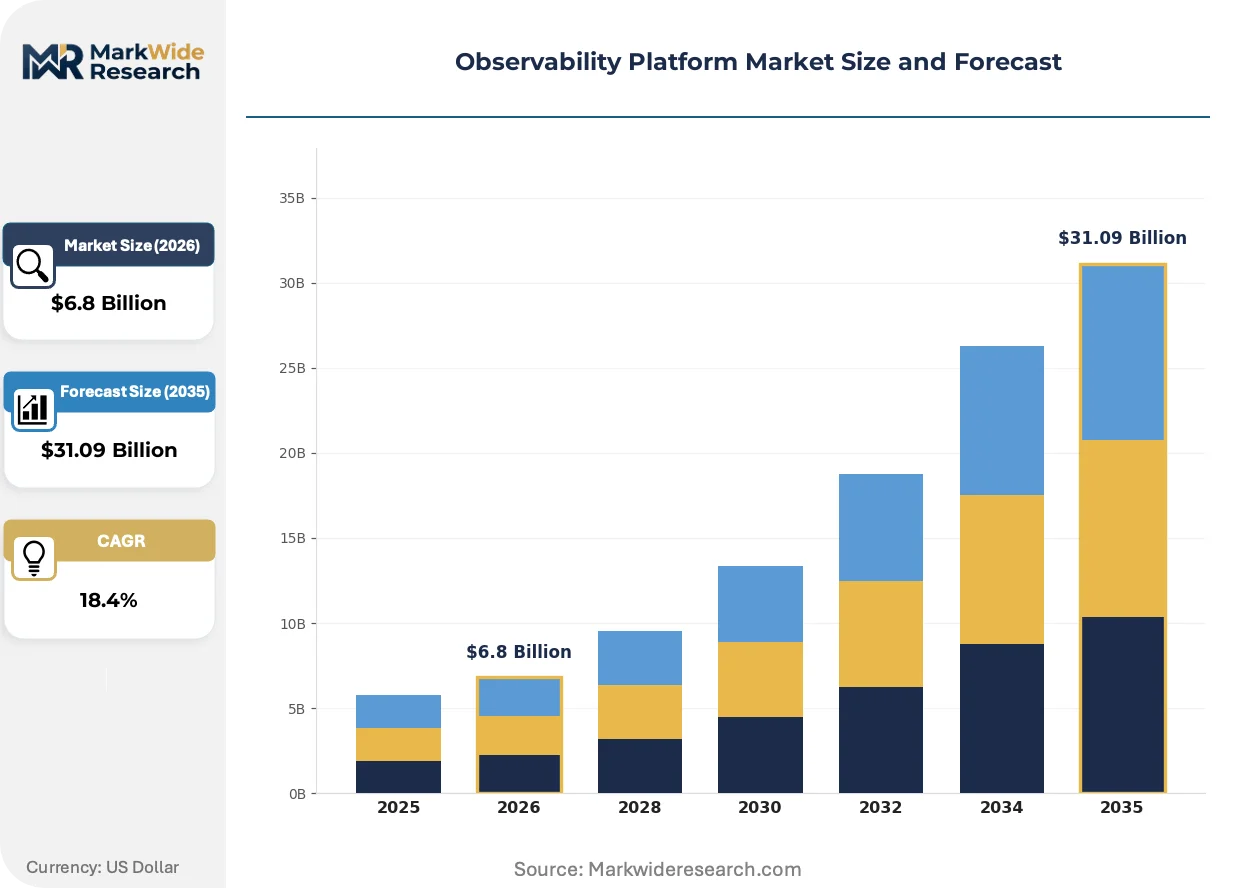
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Technology: APM, Log Management, Metrics Collection, Tracing End User: IT Operations, DevOps Teams, Application Developers, Security Teams Service Type: Monitoring, Analytics, Incident Management, Reporting |
| Companies Covered | New Relic, IBM Instana, Datadog, Cribl, Sumo Logic, Dynatrace, Elastic, AppDynamics, Splunk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Observability Platform Market Evolving Landscape
Telemetry pipelines are evolving from passive data conduits into active processing layers that filter, enrich, and route observability streams before central storage. This architectural shift reduces ingestion costs while enabling real-time anomaly detection at the edge.
eBPF kernel instrumentation is integrating security and performance telemetry collection directly into Linux operating systems without requiring application code modification. Cloud-native enterprises are adopting eBPF-based collectors to eliminate sidecar overhead in microservices deployments. This technology is compressing the traditional agent-based monitoring market by collapsing multiple data collection layers into a single kernel-level subsystem.
The EU AI Act's risk-classification framework is mandating continuous monitoring documentation for automated decision-making systems deployed in credit scoring, recruitment, and healthcare diagnostics. Vendors must architect audit-trail capabilities that capture model inputs, outputs, and confidence intervals with immutable timestamps. European financial institutions and public sector agencies are prioritizing procurement of observability platforms with built-in algorithmic governance modules to preempt regulatory enforcement actions.
Enterprise buyers are consolidating vendor relationships and demanding all-in-one platforms that span infrastructure monitoring, application performance management, and security analytics. This preference compression is marginalizing point-solution providers that lack integrated log-metric-trace correlation capabilities. The shift is most pronounced in US healthcare and German automotive verticals, where procurement teams face board-level pressure to reduce software sprawl and simplify vendor management overhead.
Observability Platform Market Segmentation
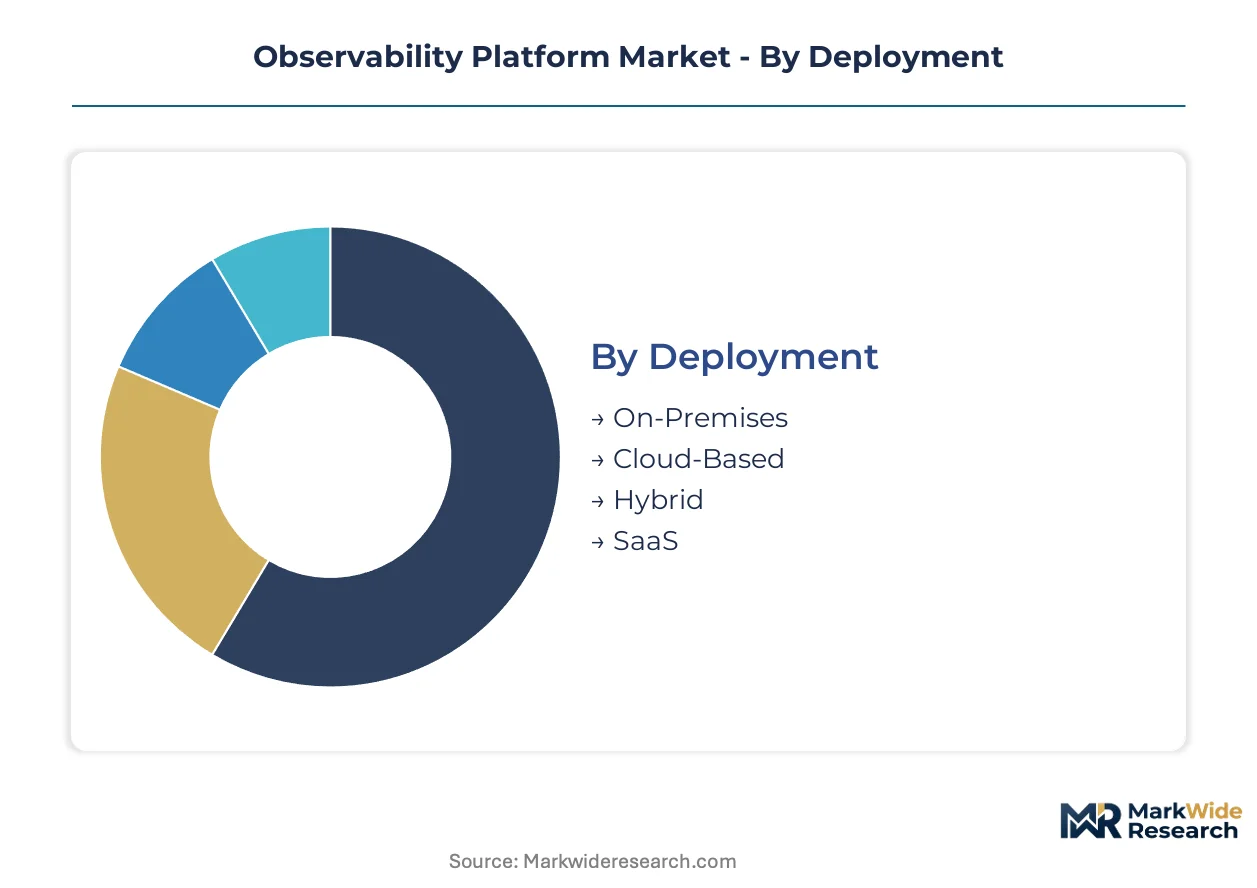
Observability platform procurement patterns diverge sharply by deployment economics, technical architecture, and organizational buyer type. Understanding these fault lines reveals where vendors must align product packaging with distinct budget cycles, compliance postures, and operational maturity levels.
Deployment:
Cost tier separates buyers in this category — capital-constrained mid-market firms gravitate toward consumption models while regulated enterprises absorb fixed infrastructure costs for control.
- On-Premises:Hardware-resident deployments with dedicated compute and storage clusters. German automotive suppliers and French defense contractors favor this model to satisfy CSRD data residency mandates and air-gapped security requirements.
- Cloud-Based:Fully managed services running on hyperscale infrastructure with elastic throughput scaling. US fintech startups and Singaporean e-commerce platforms dominate consumption here, driven by unpredictable traffic spikes and zero CapEx preference.
- Hybrid:Split architectures keeping sensitive telemetry on-premises while bursting analytics workloads to cloud. Japanese manufacturers deploying Industry 4.0 sensor networks adopt this pattern to balance latency-sensitive factory floor monitoring with centralized AI model training.
- SaaS:Multi-tenant software delivered through browser interfaces with standardized feature sets. Australian healthcare clinics and Dutch logistics operators select this tier for rapid deployment without platform engineering overhead.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as sovereignty requirements harden across European and Asia-Pacific jurisdictions.
Technology:
Application maturity determines technology selection — organizations with microservices architectures prioritize distributed tracing while monolithic legacy shops emphasize log aggregation.
- APM:Code-level performance instrumentation capturing transaction latency, error rates, and dependency mapping. Financial services firms in London and New York deploy APM suites to meet SEC and FCA operational resilience mandates for critical trading systems.
- Log Management:Centralized ingestion, indexing, and search across structured and unstructured event streams. Healthcare providers across Texas and California anchor procurement here to satisfy HIPAA audit trail requirements for patient data access logging.
- Metrics Collection:Time-series data aggregation for infrastructure health monitoring and capacity planning. Telecommunications operators in South Korea and Finland rely on metrics pipelines to manage 5G network slice performance at national scale.
- Tracing:Distributed request propagation across service meshes and container orchestration layers. Kubernetes-native enterprises in Bangalore and Stockholm drive adoption to debug microservices latency cascades.
Revenue concentrates in APM; the steepest expansion trajectory belongs to Tracing as service mesh adoption accelerates.
End User:
Organizational function shapes procurement authority and feature prioritization — platform engineering teams control budgets in advanced adopters while security teams increasingly veto vendor selection.
- IT Operations:Traditional infrastructure monitoring teams managing on-premises and cloud resource health. Brazilian retail conglomerates and Mexican banks staff these centers with engineers focused on uptime SLAs and incident escalation workflows.
- DevOps Teams:Cross-functional groups owning CI/CD pipelines and production deployment automation. Polish software houses and Israeli cybersecurity startups structure procurement around GitOps integration and infrastructure-as-code telemetry.
- Application Developers:Engineering teams requiring granular code performance feedback during feature development. Gaming studios in Montreal and Stockholm select tooling with embedded profiler visualizations and error tracking.
- Security Teams:Information security groups demanding threat detection through behavioral telemetry analysis. Italian energy utilities and Spanish critical infrastructure operators mandate security-centric observability to comply with NIS2 directive requirements.
DevOps Teams represent the dominant buyer segment; Security Teams are gaining procurement influence fastest as regulatory pressure intensifies.
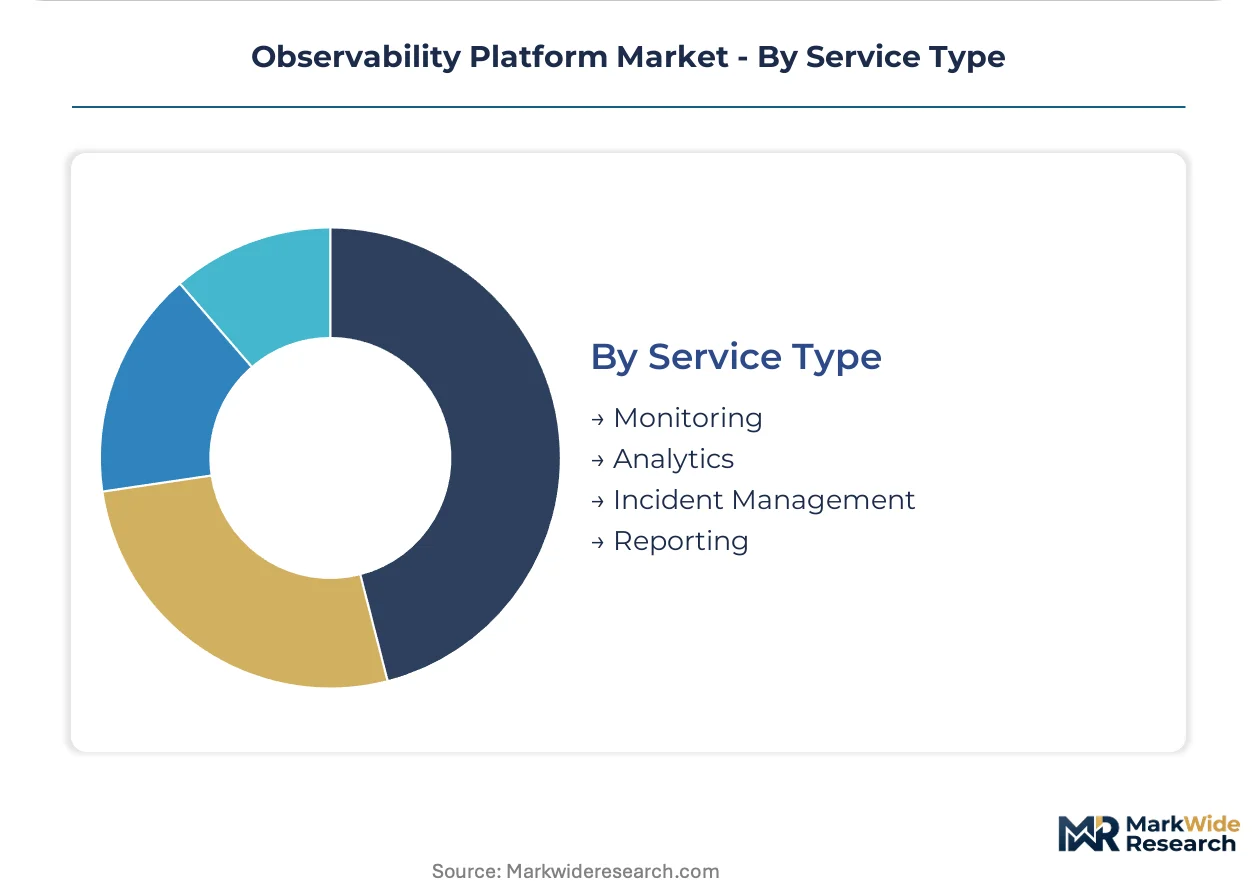
Service Type:
Value extraction stage differentiates buyers — reactive organizations purchase monitoring capabilities while mature operators invest in predictive analytics and automated response.
- Monitoring:Real-time dashboards and threshold-based alerting for system health visibility. Swiss pharmaceutical manufacturers and Austrian machinery builders standardize on monitoring-first deployments to support 24/7 production continuity.
- Analytics:Pattern recognition, anomaly detection, and root-cause correlation across telemetry dimensions. US insurance underwriters and UK credit card processors deploy analytics modules to identify fraud patterns in transaction flows.
- Incident Management:Coordinated response workflows integrating paging, runbook automation, and post-mortem documentation. French cloud service providers and Norwegian maritime logistics firms prioritize this capability for distributed team coordination.
- Reporting:Scheduled and ad-hoc compliance documentation for regulatory submissions and executive review. German automotive suppliers and Japanese electronics manufacturers require reporting suites to satisfy ISO 27001 and CSRD disclosure obligations.
Monitoring commands current spending; Analytics is climbing the fastest as AI-driven insight layers differentiate vendor offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors observability platform demand through its dense concentration of cloud-native enterprises and venture-backed infrastructure startups. The Bay Area's technology corridor generates disproportionate procurement volume for real-time telemetry systems.
United States
Financial services firms in Manhattan and Chicago drive APM procurement for trading system resilience. SEC operational continuity mandates require real-time monitoring documentation for critical market infrastructure. Healthcare clusters in Boston and Minneapolis anchor log management spending to satisfy HIPAA audit trail requirements for patient data access.
Germany
Mittelstand automotive suppliers across Bavaria and Baden-Württemberg modernize legacy mainframe monitoring for Industry 4.0 factory connectivity. CSRD sustainability reporting mandates require granular operational telemetry for supply chain carbon accounting. Stuttgart's automotive engineering corridor leads European deployment of unified observability platforms.
United Kingdom
London's fintech ecosystem generates concentrated demand for Kubernetes-native tracing tools. FCA operational resilience rules impose strict incident detection and recovery time objectives on payment systems. The Thames Valley technology corridor hosts expanding platform engineering teams prioritizing OpenTelemetry standardization.
Japan
Manufacturing conglomerates in the Chubu and Kansai regions deploy hybrid observability for sensor-heavy production lines. METI's data-free flow with trust initiative shapes cross-border telemetry governance requirements. Nagoya's automotive robotics cluster drives edge computing telemetry investment for low-latency quality control.
India
Bangalore's software services exporters and Mumbai's financial institutions expand cloud-based observability procurement. RBI data localization directives force global vendors toward domestic hosting partnerships. Hyderabad's cloud infrastructure corridor attracts sovereign-hosted platform deployments for banking compliance.
Observability Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across analytics depth and AI-driven insight capabilities. The market consolidates around full-stack platform providers while point-solution specialists face procurement pressure from enterprise vendor reduction initiatives. Three archetypes dominate: unified platform consolidators, open-source-native distributors, and AI-automation specialists. Competitive moves concentrate on strategic acquisitions for telemetry correlation technology and partnerships with hyperscale cloud providers for embedded distribution.
Within the unified platform tier, Datadog and Dynatrace exemplify consolidation-focused positioning. Elastic occupies a distinct archetype as an open-source-native distributor leveraging search-native architecture. Splunk represents the established incumbent navigating transition from on-premises licensing to cloud-native consumption models.
| Leading Market Players |
|---|
| New Relic |
| IBM Instana |
| Datadog |
| Cribl |
| Sumo Logic |
| Dynatrace |
| Elastic |
| AppDynamics |
| Splunk |
| Others |
Value Network & Pricing Analysis
Cloud compute spot pricing indices and hyperscale storage rate cards cascade through observability platform cost structures, compressing margins for SaaS-tiered offerings while amplifying pricing power for vendors with captive data center footprints and sovereign-hosted infrastructure partnerships.
Pricing Analysis
Value-based pricing anchored to telemetry throughput volumes and incident resolution outcomes dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by data retention depth and AI-driven analytics inclusion. Cost compression in the mid-market tier is intensifying because OpenTelemetry standardization enables buyer switching between functionally equivalent collectors. Financial services firms in Manhattan and London exhibit lowest price sensitivity due to regulatory audit requirements, while Southeast Asian e-commerce platforms demonstrate highest elasticity.
Supply Chain Analysis
Freight costs for edge hardware appliances and on-premises storage arrays remain marginal against cloud egress fees that dominate total cost of ownership calculations. Software development concentrates in the United States, Ireland, and India, while data center infrastructure draws from Taiwan, South Korea, and Germany. Single-source vulnerability in OpenTelemetry instrumentation libraries creates pipeline disruption risk. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The observability platform sector sits in a technology-transition phase as eBPF kernel instrumentation displaces legacy agent-based collectors and forces architectural reinvestment across vendor portfolios.
For Market Incumbents: Lock in enterprise renewals through unified platform bundling that collapses log-metric-trace silos into correlated telemetry streams. Deepen backward integration into eBPF-based data collection layers to eliminate third-party agent dependencies. Address the threat from open-source-native distributors by accelerating AI-driven insight differentiation beyond commodity data ingestion.
For New Entrants and Emerging Players: Capture edge computing telemetry gaps in Japanese manufacturing corridors and South Korean autonomous vehicle fleets where low-bandwidth, high-latency environments lack mature tooling. Target India's sovereign-hosted infrastructure requirements through domestic data center partnerships with RBI-compliant hosting providers. Lead with FinOps-observability convergence as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors telemetry correlation engine specialists and eBPF instrumentation startups ahead of platform consolidation waves. Long-term viability hinges on differentiation depth in AI-driven root-cause automation rather than data ingestion scale. Watch OpenTelemetry governance committee decisions as the critical inflection signal for vendor lock-in erosion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies log-metric-trace pipelines into correlated streams for German automotive CSRD compliance. |
| Strategic Partnership | Establishes sovereign-hosted infrastructure with Indian domestic cloud providers for RBI data localization. |
| Acquisition of Specialist Firm | Adds eBPF kernel instrumentation capabilities to eliminate sidecar overhead in Kubernetes environments. |
| Geographic Expansion | Builds edge computing telemetry presence in Nagoya automotive robotics clusters for low-latency quality control. |
| Product Launch | Introduces algorithmic governance modules satisfying EU AI Act audit-trail mandates for high-risk AI deployments. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and OpenTelemetry project documentation formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with platform engineering directors, IT procurement officers, SRE team leads, and channel integration specialists validated deployment pattern assumptions and pricing sensitivity thresholds. Bottom-up telemetry volume estimates and top-down enterprise software spend allocations were triangulated to anchor forecast confidence.
Bottom-up modeling of data ingestion throughput by deployment type and organization size was cross-checked against top-down IT operations software budget allocations across the projection horizon. Segmentation dimensions included deployment model, technology layer, end-user function, and service maturity tier. CAGRs were derived from elasticity-adjusted adoption curves and regulatory compliance-driven procurement cycle timing. Forecast inputs incorporated EU AI Act implementation schedules and Kubernetes-native infrastructure expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OpenTelemetry standardization velocity and regional data sovereignty rulings. Forecasts reflect documented assumptions about cloud egress cost trajectories and talent scarcity in site reliability engineering. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Saas for Spa Management Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Business Rules Management System Market
Software & Services
Runtime Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Channel Management Software Market
Software & Services
Creative Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Global Back Testing Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Strategy Management Software Market
Software & Services
HR Tech Market