
 Global IT Asset Disposition (ITAD) Market | 2026-2036
Global IT Asset Disposition (ITAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global IT Asset Disposition (ITAD) Market Foresight
The split between premium certified-disposition tiers and commodity hardware-recycling streams is realigning as enterprise buyers demand auditable data-destruction documentation. Sims Lifecycle Services leverages its multinational facility network to sustain compliance-grade service coverage across North America and Europe. Iron Mountain anchors its position through integrated logistics and secure transport infrastructure. ERI differentiates via specialized e-waste processing capacity at scale.
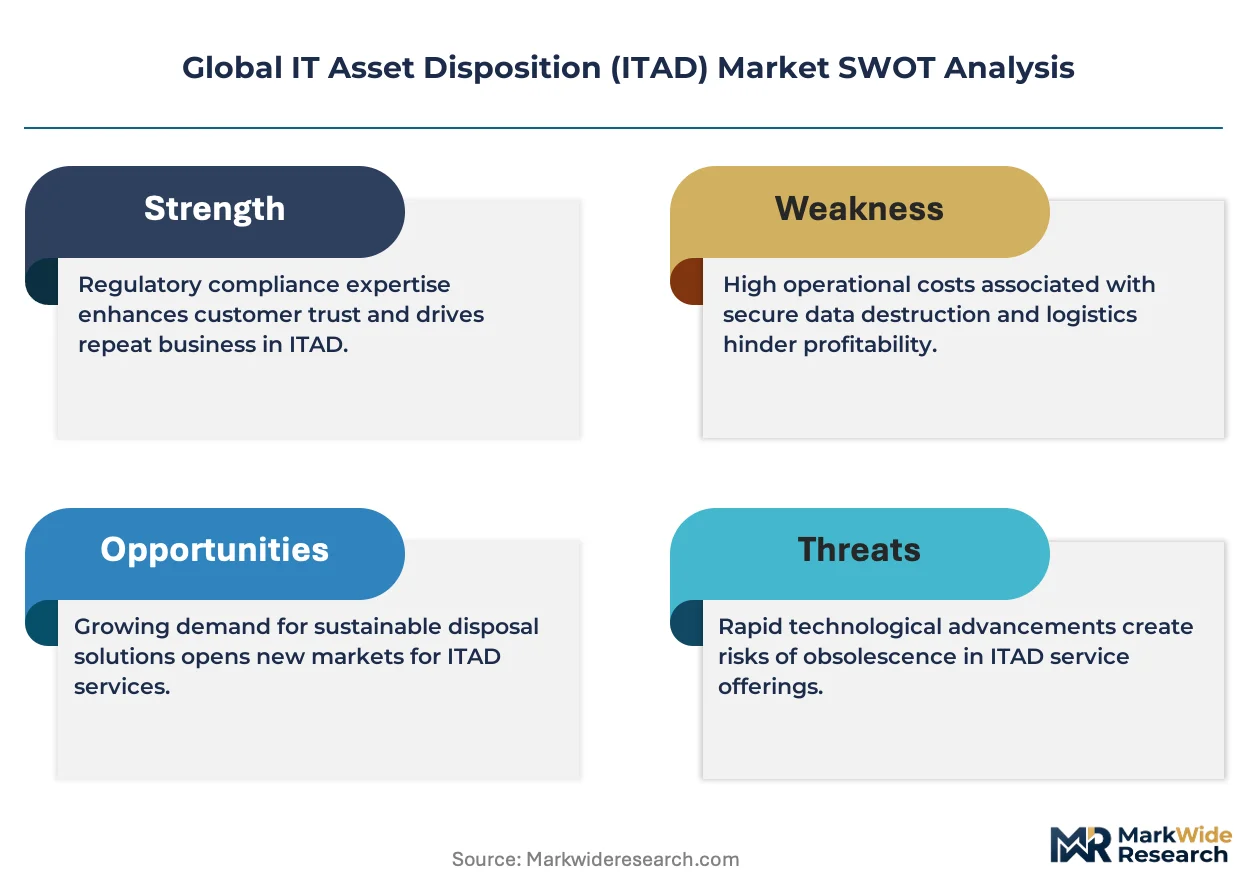
IT Asset Disposition encompasses the secure decommissioning, data sanitization, and environmentally responsible disposal of retired enterprise computing equipment, typically involving NIST 800-88 compliant overwrite verification or physical destruction methods for storage media. The primary commercial purpose is eliminating data breach liability while recovering residual value through refurbishment or precious-metal reclamation. Data Destruction and Asset Recovery command the strongest margin pools as regulatory pressure intensifies. Hardware Recycling and Refurbishment segments are expanding fastest among mid-market enterprises seeking circular-economy credentials. Logistics Management remains mature with thin margins concentrated among integrated operators.
EPA regulations in the United States, the EU WEEE Directive and GDPR across Europe, and R2 and e-Stewards certification standards collectively shape market access by mandating documented chain-of-custody and environmental compliance. The EU AI Act and emerging battery-passport requirements are extending traceability obligations to embedded IT assets. Stakeholders must monitor how fragmented national e-waste frameworks evolve and whether certification consolidation favors integrated service providers over specialized regional operators.
Market Dynamics
Enterprise data-retention mandates and circular-economy disclosure requirements are compressing refresh cycles while elevating certified-destruction documentation from procurement checkbox to board-level risk priority.
Growth Catalysts
- EU WEEE Directive enforcement:Member states now mandate documented chain-of-custody for enterprise electronics, forcing financial institutions and healthcare providers to adopt certified ITAD services or face penalties.
- Cloud migration waves:Data center decommissioning projects across North America and Europe are generating surges of retired server hardware requiring immediate sanitization before resale or recycling.
- Battery passport requirements:The EU's emerging traceability framework for embedded power sources is extending ITAD obligations to previously exempt edge devices and IoT endpoints.
Market Restraints
- Logistics cost volatility:Fuel price fluctuations and driver shortages in the United States and Germany are eroding margins on collection and transport services.
- Smelter concentration:Precious-metal recovery depends on a handful of refineries in Belgium and Japan, creating supply bottlenecks when processing volumes spike.
- GDPR liability fragmentation:Cross-border data transfers of sanitized assets trigger divergent national interpretations of adequacy, complicating multinational service contracts.
Strategic Opportunities
- India's PLI scheme expansion:Domestic electronics manufacturing incentives are creating parallel ITAD demand as local production scales and enterprise adoption accelerates.
- AI-enabled asset valuation:Machine learning models trained on component-level price data are rewriting residual-value recovery rates for refurbished enterprise storage.
- Embedded carbon accounting:The EU CSRD is pushing scope-3 disclosure requirements that favor ITAD providers offering verified lifecycle impact documentation.
Industry Challenges
- NIST 800-88 specialist scarcity:Certified sanitization technicians capable of executing and documenting compliant overwrite protocols remain concentrated in mature markets.
- R2-e-Stewards dual certification:Maintaining both standards requires redundant auditing and facility investments that strain mid-scale operators.
- Legacy tape media destruction:Magnetic storage formats from archived enterprise systems require specialized degaussing equipment that few processors maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IT Asset Disposition (ITAD) Market |
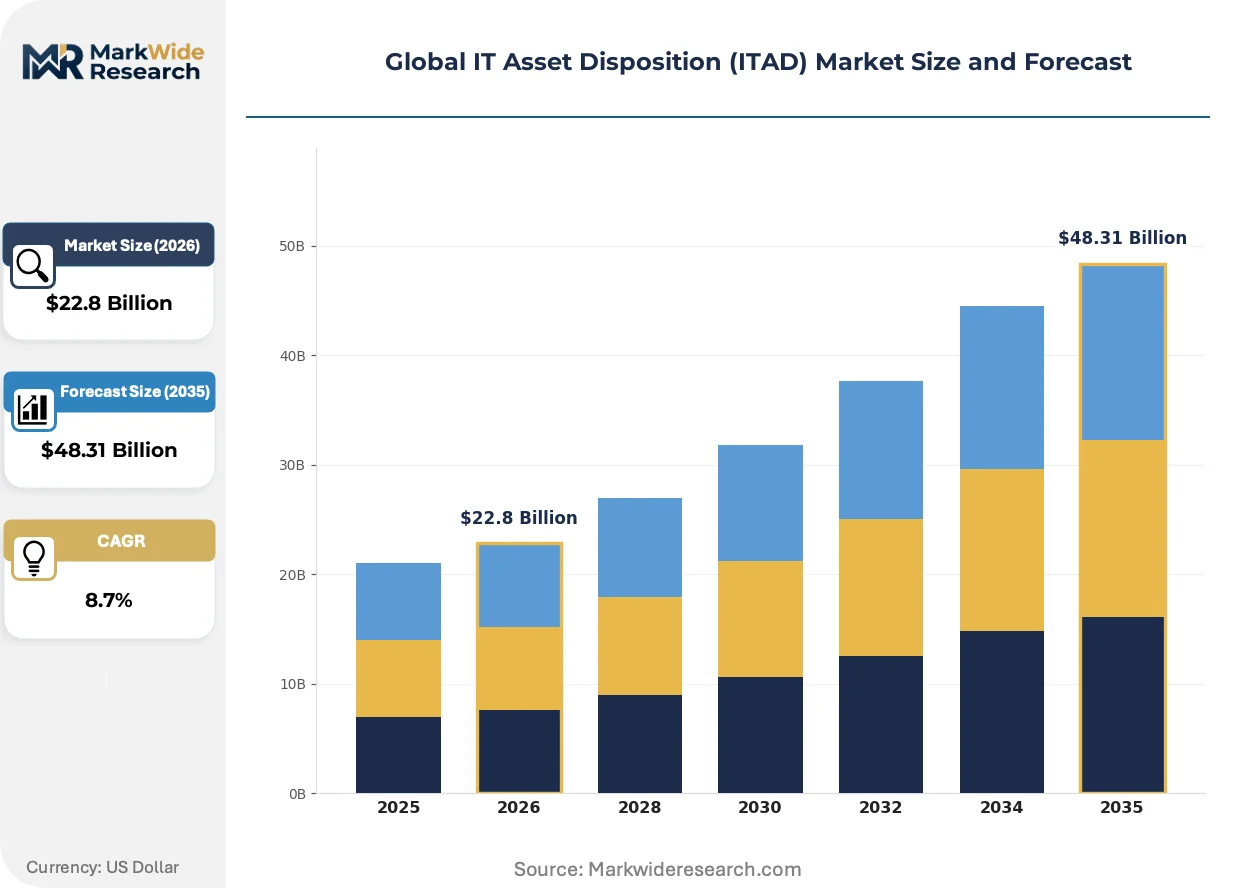
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $48.31 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Destruction, Hardware Recycling, Refurbishment, Logistics Management, IT Resale, Asset Recovery End User: Government Agencies, Financial Institutions, Educational Establishments, Telecommunications Providers, Technology Enterprises, Media Firms Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile Unit, Remote Service, Partner Network Equipment Type: Desktop Computers, Laptops, Servers, Storage Devices, Networking Gear, Mobile Devices |
| Companies Covered | Hewlett Packard Enterprise, Sims Lifecycle Services, Iron Mountain, HOBI International, Cascade Asset Management, ERI, Ingram Micro, Dynamic Lifecycle Innovations, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IT Asset Disposition (ITAD) Market Shifts & Advancements
Automation of data-destruction verification and the integration of blockchain-based custody logs are elevating service transparency from competitive differentiator to baseline procurement requirement.
Automated optical scanning systems paired with forensic-level overwrite verification are rewriting how enterprise buyers evaluate ITAD vendor competence. Financial services firms in London and Frankfurt now require real-time sanitization certificates before releasing payment. The technology is compressing acceptable vendor response windows from days to hours.
The EU AI Act's risk-classification framework is extending documentation obligations to AI training hardware containing sensitive model weights or proprietary datasets. German automotive manufacturers and French pharmaceutical groups face new mandates for segregated processing of GPU clusters. Facilities in the Netherlands and Ireland are retrofitting secure corridors to handle these segregated workflows.
Subscription-based ITAD contracts with guaranteed residual-value floors are displacing transactional spot-market arrangements in North American enterprise procurement. Healthcare systems in Texas and California now favor multi-year agreements bundling logistics, destruction, and recovery. The model concentrates volume with integrated operators capable of underwriting asset-price risk.
Global IT Asset Disposition (ITAD) Market Segmentation
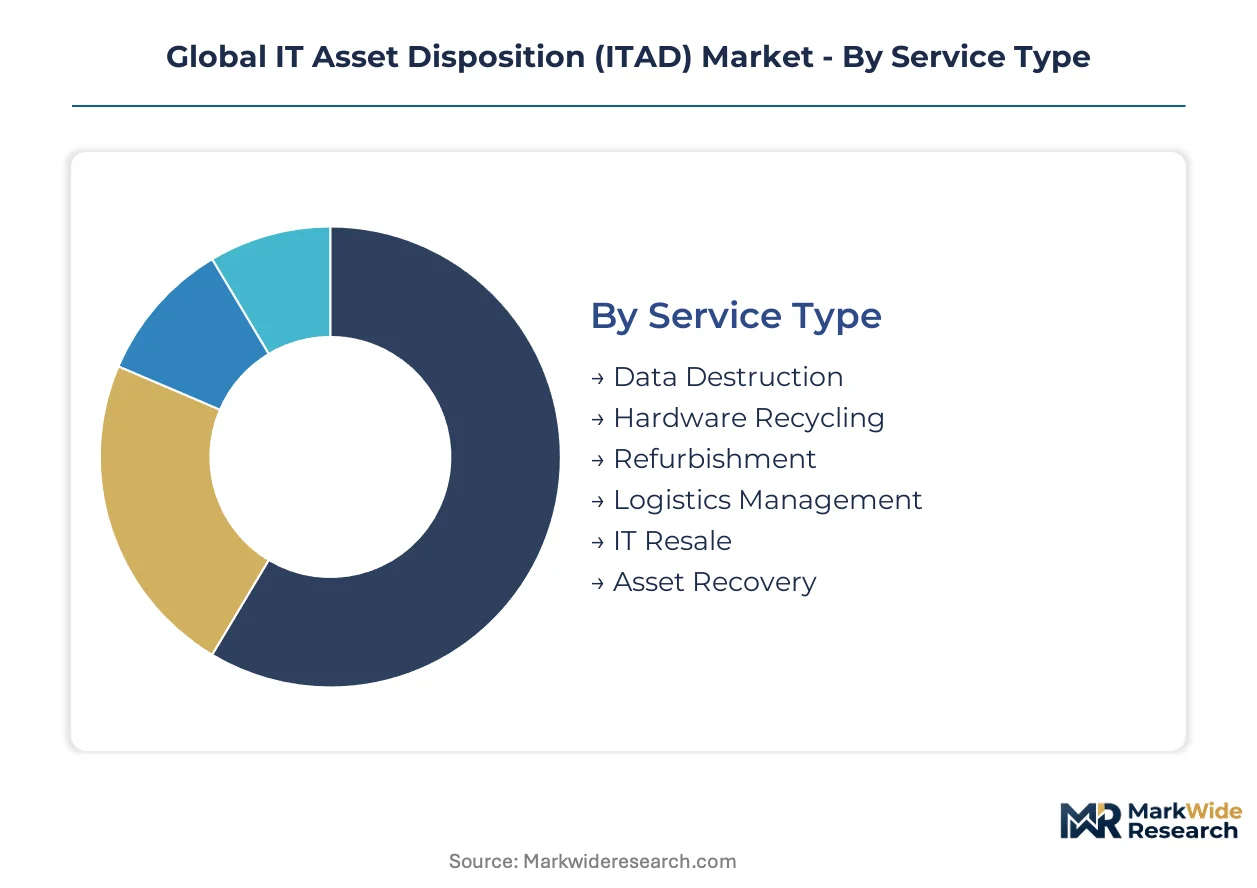
ITAD service differentiation hinges on capital intensity and compliance certification depth. Buyers select tiers based on data sensitivity, asset residual value, and regulatory exposure rather than commodity pricing alone.
Service Type:
Capital requirements vary sharply across service tiers, with certified destruction demanding specialized degaussing equipment and secure facility investments that commodity recycling operations avoid.
- Data Destruction:NIST 800-88 compliant overwrite verification and physical shredding of storage media require forensic-grade audit trails. Financial institutions in Germany and the United Kingdom now mandate real-time sanitization certificates before payment release, compressing vendor response windows from days to hours.
- Asset Recovery:Component-level refurbishment and precious-metal reclamation depend on volatile smelter relationships concentrated in Belgium and Japan. Margin pools here exceed commodity recycling by multiples when gold and palladium prices spike.
- Hardware Recycling:Environmental compliance through R2 and e-Stewards certification creates barrier-to-entry for mid-scale operators.
- Refurbishment:Functional testing and cosmetic grading for secondary-market resale.
- Logistics Management:Secure transport infrastructure with chain-of-custody documentation.
- IT Resale:Brokerage and auction services for sanitized enterprise equipment.
Most installed capacity flows through Logistics Management. Expansion is steepest in Asset Recovery.
End User:
Procurement sophistication separates regulated industries with board-level risk oversight from cost-driven institutional buyers.
- Financial Institutions:GDPR and SEC record-retention mandates drive demand for auditable destruction documentation. Frankfurt and London banking clusters now require segregated processing workflows for AI training hardware under the EU AI Act.
- Technology Enterprises:Cloud migration waves generate surges of retired server hardware requiring immediate sanitization. Data center decommissioning projects across the United States and Ireland concentrate volume with integrated operators capable of underwriting asset-price risk.
- Government Agencies:Classified data handling requires cleared personnel and secure facility accreditation.
- Telecommunications Providers:Network equipment refresh cycles and 5G infrastructure rollouts.
- Educational Establishments:Budget-constrained procurement favors basic recycling over certified destruction.
- Media Firms:Digital content archives on legacy tape media require specialized degaussing capacity.
Financial Institutions command premium pricing tiers. Technology Enterprises are gaining share fastest.
Deployment Model:
Physical asset proximity requirements constrain pure-digital delivery, favoring hybrid configurations that blend on-site verification with centralized processing.
- On-Premise:Mobile shredding units and degaussing equipment deployed directly at client facilities eliminate transit risk for highly sensitive storage media. German automotive manufacturers mandate this model for proprietary design files.
- Hybrid:On-site verification combined with centralized refurbishment creates auditability without sacrificing economies of scale. Dutch facilities pioneered secure corridor retrofits for GPU cluster segregation under emerging AI hardware regulations.
- Cloud-Based:Remote monitoring and certificate delivery for standardized sanitization workflows.
- Mobile Unit:Self-contained processing trailers for remote or classified locations.
- Remote Service:Software-based data wiping with network-connected verification.
- Partner Network:Certified subcontractor relationships extending geographic coverage.
Hybrid deployments capture the majority of enterprise contract value. Cloud-Based models are climbing the fastest among mid-market buyers.
Equipment Type:
Data density and component recoverability determine processing economics across hardware categories.
- Servers:High-value components including CPUs, memory modules, and enterprise storage drives justify detailed refurbishment. Cloud hyperscalers in Virginia and Dublin generate the largest concentrated volumes.
- Storage Devices:SSD and HDD sanitization demands specialized overwrite protocols or physical destruction. NIST 800-88 specialist scarcity concentrates certified capacity in mature markets.
- Laptops:Standardized form factors enable efficient resale channel development.
- Desktop Computers:Declining enterprise adoption reduces refresh volumes.
- Networking Gear:Cisco and Juniper equipment retains secondary-market value.
- Mobile Devices:Battery passport requirements under EU frameworks extend ITAD obligations to previously exempt endpoints.
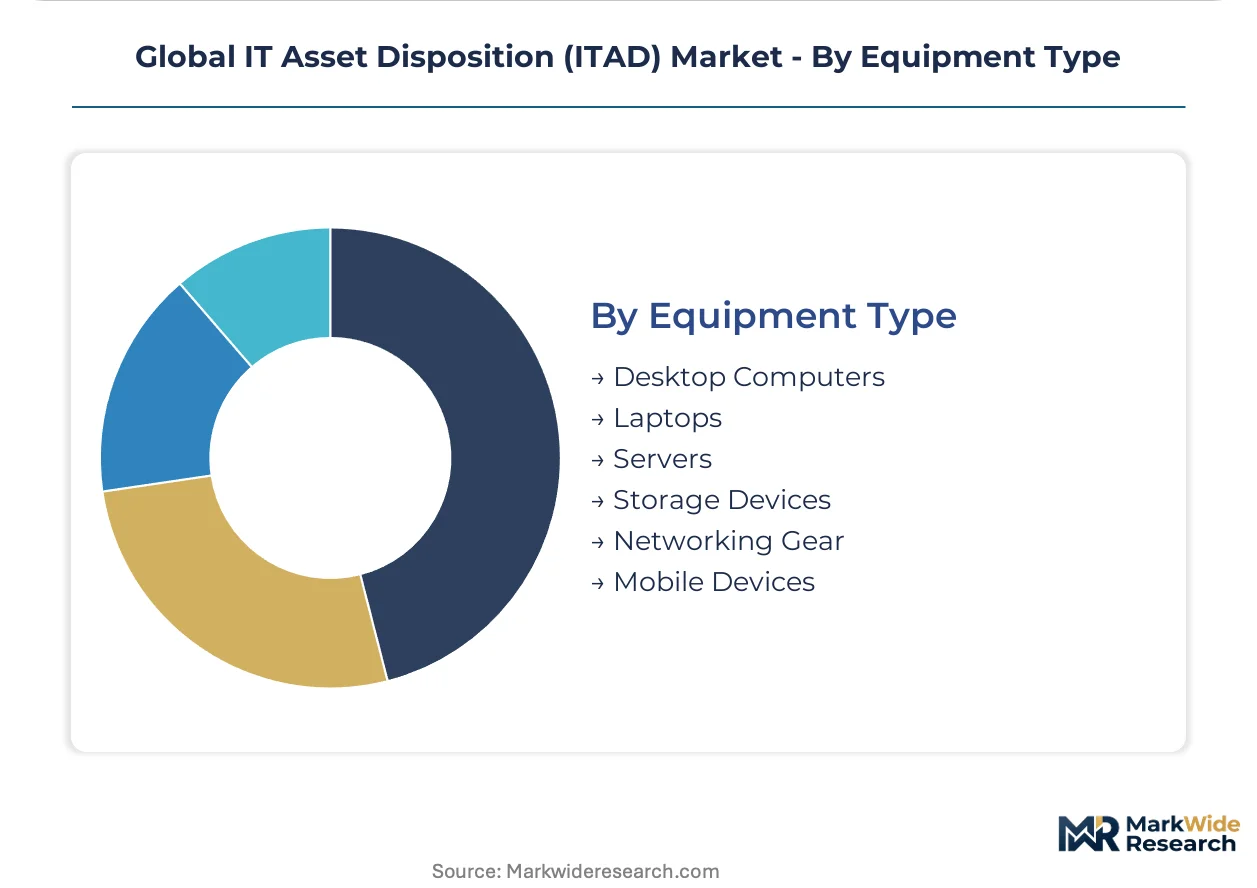
Servers dominate processing volume by weight. Storage Devices show the steepest expansion trajectory as data retention mandates lengthen hardware lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified sanitization technicians cluster disproportionately in Germany, the United States, and the United Kingdom, anchoring enterprise-grade ITAD capacity in these markets while creating supply bottlenecks elsewhere.
United States
Cloud hyperscalers in Virginia and Texas generate concentrated server decommissioning volumes. EPA regulations mandate documented chain-of-custody for enterprise electronics. Dallas-Fort Worth and Northern Virginia data center clusters drive demand for immediate on-site sanitization services.
Germany
Frankfurt's banking sector demands segregated processing workflows for AI training hardware under the EU AI Act. The KBA enforces strict transport documentation for sensitive equipment. Bavarian automotive manufacturers mandate on-premise destruction for proprietary design files.
United Kingdom
London financial institutions require real-time sanitization certificates before payment release. GDPR compliance pressures elevate certified destruction from procurement checkbox to board-level priority. The M4 corridor technology cluster generates steady enterprise refresh volumes.
India
Domestic electronics manufacturing incentives under the PLI scheme create parallel ITAD demand as local production scales. BIS certification requirements tighten environmental compliance standards. Bengaluru and Hyderabad enterprise adoption accelerates refresh cycle compression.
Netherlands
Dutch facilities pioneer secure corridor retrofits for GPU cluster segregation under emerging AI hardware regulations. The CSRD pushes scope-3 disclosure requirements favoring verified lifecycle impact documentation. Amsterdam's data center concentration drives specialized processing demand.
Global IT Asset Disposition (ITAD) Market Competitive Landscape
Top-tier vendors anchor certified-destruction and integrated logistics tiers, while mid-scale operators compete on regional coverage and commodity recycling margins. Market structure favors multinational facility networks capable of sustaining compliance-grade service coverage across multiple jurisdictions. Strategic archetypes include integrated logistics-security providers, specialized e-waste processors at scale, and OEM-captive service arms. Dominant competitive moves center on certification consolidation and geographic expansion through facility retrofitting.
Within the integrated logistics tier, Iron Mountain and Sims Lifecycle Services exemplify archetypes combining secure transport infrastructure with multinational facility networks. ERI occupies a position representing specialized e-waste processing capacity at scale. Hewlett Packard Enterprise and Dell Technologies sit within the OEM-captive tier, leveraging hardware manufacturing relationships to secure enterprise decommissioning contracts. These three groupings represent the primary competitive vectors reshaping procurement consolidation.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Sims Lifecycle Services |
| Iron Mountain |
| HOBI International |
| Cascade Asset Management |
| ERI |
| Ingram Micro |
| Dynamic Lifecycle Innovations |
| Dell Technologies |
| Others |
Supply & Pricing Matrix
Blockchain-based custody logging and automated sanitization verification are compressing cost-to-serve while concentrating premium-tier contracts with operators capable of real-time certificate delivery. This technology shift simultaneously erodes margins for legacy processors lacking forensic-grade audit infrastructure and rewards integrated networks with multinational facility footprints.
Pricing Analysis
The bundled-versus-unbundled service split separates subscription-based multi-year agreements with residual-value guarantees from transactional spot-market arrangements. Three-tier pricing structure across certified destruction, standard refurbishment, and commodity recycling tiers reflects NIST 800-88 compliance depth and chain-of-custody documentation rigor. Cost compression in logistics-heavy collection services stems from fuel volatility and driver shortages across the United States and Germany. Mid-market educational establishments exhibit highest price sensitivity, while Frankfurt and London financial institutions accept substantial premiums for segregated AI hardware processing under EU AI Act mandates.
Supply Chain Analysis
Logistics cost volatility in secure transport corridors between enterprise data centers and processing facilities is reshaping network economics across the ITAD value chain. Supply concentration clusters in the United States, Germany, and the United Kingdom where certified sanitization technicians anchor enterprise-grade capacity. Precious-metal recovery draws from smelter relationships concentrated in Belgium and Japan, creating single-source vulnerability during volume spikes. Distribution runs through integrated operators combining secure transport infrastructure with multinational facility networks, though mid-scale regional players retain commodity recycling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ITAD hinges on automation-driven cost compression in data-destruction verification and the premium-tier shift toward subscription contracts with guaranteed residual-value floors.
For Market Incumbents: Cement dominance in certified destruction tiers by retrofitting secure corridors for GPU cluster segregation under EU AI Act mandates. Acquire NIST 800-88 specialist capacity in Germany and the United Kingdom where technician scarcity threatens service coverage. Deepen backward integration into precious-metal refining relationships to offset smelter concentration risk in Belgium and Japan. For New Entrants and Emerging Players: Cloud-based certificate delivery platforms offer the most penetrable entry vector for mid-market buyers seeking standardized sanitization workflows without premium logistics overhead. Target India's PLI scheme expansion zones where domestic electronics manufacturing incentives are creating parallel ITAD demand in Bengaluru and Hyderabad. Lead with AI-enabled asset valuation tools that rewrite residual-value recovery rates for refurbished enterprise storage. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale operators struggling with redundant R2-e-Stewards dual certification auditing burdens. The five-to-ten-year viability window favors acquisition targets with established secure transport infrastructure and multinational facility networks capable of underwriting asset-price risk. Watch for consolidation signals when fuel price stabilization compresses logistics cost volatility and restores margin visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Corridor Retrofitting | EU AI Act GPU segregation mandates in Netherlands and Ireland facilities create compliance-grade differentiation. |
| Blockchain Custody Integration | Real-time sanitization certificates compress vendor response windows from days to hours for London financial institutions. |
| Subscription Contract Expansion | Multi-year agreements with residual-value floors displace spot-market arrangements in Texas and California healthcare systems. |
| Smelter Relationship Deepening | Upstream control over Belgium and Japan precious-metal recovery insulates against processing volume spike bottlenecks. |
| India PLI Zone Entry | BIS certification alignment captures electronics manufacturing incentive-driven ITAD demand in Bengaluru and Hyderabad. |
Research Methodology
Direct dialogue with ITAD operations directors, enterprise procurement officers at financial institutions, data center decommissioning project managers, and certified sanitization technicians grounded qualitative findings. Secondary validation drew from EPA enforcement records, EU WEEE Directive implementation reports, R2 and e-Stewards certification databases, and hyperscaler capex disclosures. Bottom-up facility capacity assessments and top-down enterprise refresh cycle modeling were triangulated against regional regulatory cluster analysis.
Bottom-up volume modeling tracked server decommissioning flows from Virginia and Dublin data center clusters, while top-down demand assessment sized financial institution compliance spending across GDPR and EU AI Act jurisdictions. Segmentation dimensions included service type tier, end-user industry vertical, deployment model configuration, and equipment category density. CAGRs were derived from regression analysis against enterprise refresh cycle compression rates and regulatory enforcement intensity indices, with cross-validation against smelter throughput capacity and logistics cost indices.
The model assumes a particular technology adoption path for blockchain-based custody logging and automated optical scanning systems; alternative pathways for AI-enabled asset valuation would alter the outlook for residual-value recovery rates and subscription contract penetration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines, fuel price stabilization trajectories, and precious-metal market volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Revops Platform Market
Digital Solutions
UK Route Optimization Software Market