
 Monitoring Tools Market | 2026-2036
Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Monitoring Tools Market Analytics
Capital-intensity divergence between hyperscale cloud providers and specialized observability vendors is redrawing competitive boundaries in monitoring tools. Microsoft Corporation leverages its Azure ecosystem to bundle infrastructure monitoring with compute contracts, sustaining integrated platform economics. Datadog competes through granular application performance telemetry, while Dynatrace anchors its position in AI-driven root-cause automation for enterprise Kubernetes environments.
Monitoring tools encompass software and hardware instrumentation that captures, aggregates, and analyzes operational telemetry from distributed computing infrastructure, typically processing metrics at sub-minute intervals to trigger automated alerts. These systems serve to maintain service-level objectives, detect anomalous behavior, and enable forensic investigation of system degradation across hybrid technology stacks. Application Performance Monitoring commands premium pricing due to complex distributed tracing requirements, while Security Monitoring exhibits the fastest expansion as zero-trust architectures mandate continuous verification telemetry. Cloud-Based deployment now dominates new procurement, though Hybrid configurations retain substantial share in regulated industries requiring on-premises data sovereignty.
FDA guidelines for software as a medical device, EU NIS2 cybersecurity mandates, and SEC disclosure rules for material cyber incidents collectively elevate monitoring tool compliance from operational convenience to regulatory necessity. The EU AI Act further imposes continuous logging obligations on high-risk automated decision systems, directly expanding observability addressable markets. Stakeholders must weigh specialization depth against platform breadth when allocating R&D budgets across emerging telemetry domains.
Market Dynamics
Cloud-native telemetry architectures are compressing deployment cycles from months to days, forcing incumbent vendors to rearchitect legacy agent-based collection systems around open standards like OpenTelemetry. This structural shift privileges vendors with native Kubernetes instrumentation over those anchored in virtual-machine-era monitoring paradigms.
Growth Catalysts
- EU AI Act logging mandates:High-risk automated decision systems in financial services and healthcare must maintain continuous audit trails, directly expanding observability procurement budgets across Frankfurt, Paris, and Amsterdam.
- Industrial digitization in Germany:The country's Industrie 4.0 programs require real-time oversight of manufacturing execution systems, pulling predictive maintenance telemetry into unified monitoring platforms.
- Zero-trust security architectures:Continuous verification telemetry requirements are displacing periodic security audits with always-on security monitoring, particularly in US federal contractor supply chains.
Market Restraints
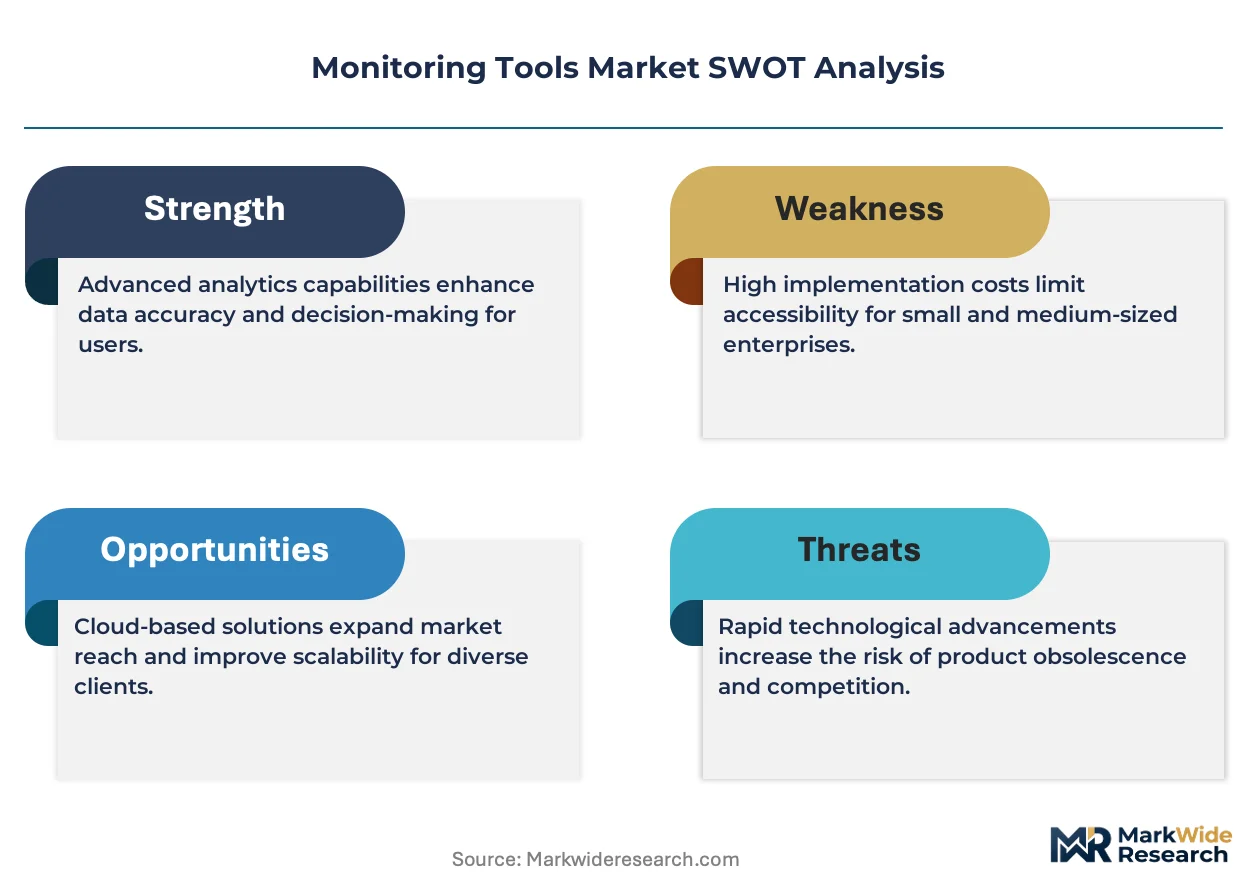
- Specialized engineering talent scarcity:Expertise in distributed systems tracing and eBPF kernel instrumentation concentrates in San Francisco, Seattle, and Berlin, inflating implementation costs elsewhere.
- Data sovereignty fragmentation:Divergent national data localization requirements—India's data protection rules, China's cybersecurity law, Russia's data localization mandates—force redundant infrastructure deployment.
- Legacy agent lock-in:Decades of SNMP and WMI instrumentation in industrial control systems create technical debt that slows cloud-migration timelines and extends sales cycles.
Strategic Opportunities
- India's digital public infrastructure expansion:The country's unified payments interface and health stack create greenfield demand for observability across state-level data centers.
- Carbon-aware workload scheduling:Convergence of telemetry platforms with grid-intensity data enables workload shifting to low-carbon hours, opening sustainability-linked procurement channels.
- Edge computing telemetry gaps:Manufacturing sites and retail locations lack mature observability, creating first-mover advantage for vendors with lightweight agent architectures.
Industry Challenges
- eBPF instrumentation expertise:Kernel-level telemetry collection demands rare systems programming skills that most enterprise IT organizations cannot source internally.
- Multi-cloud correlation complexity:Normalizing metrics, logs, and traces across AWS, Azure, and GCP control planes requires architectural investment that strains mid-market budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monitoring Tools Market |
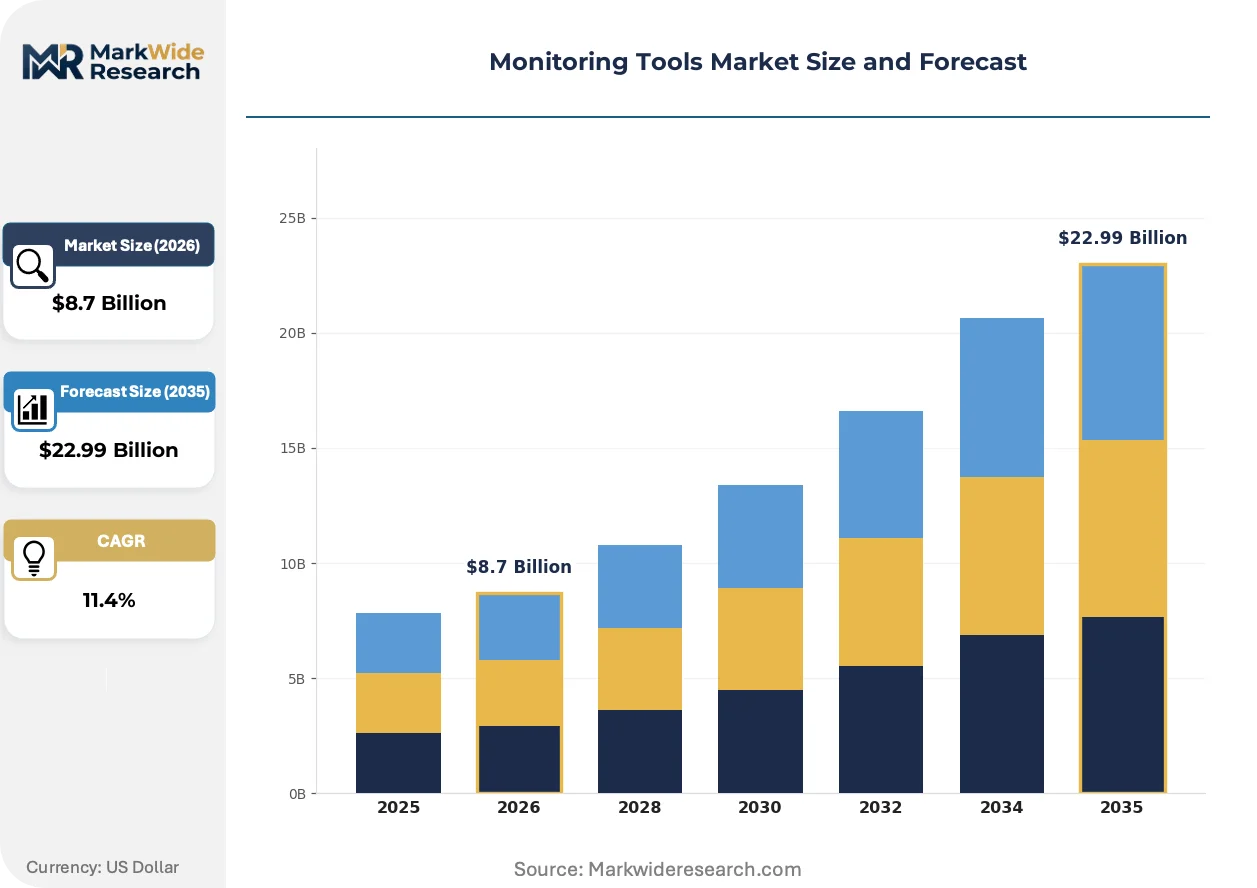
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Monitoring, Application Performance Monitoring, Security Monitoring, System Monitoring Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Departments, Service Providers, Enterprises, Government Solution: Log Management, Performance Analytics, User Experience Monitoring, Incident Management |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Datadog, Splunk, Cisco Systems, Dynatrace, SolarWinds, IBM Corporation, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monitoring Tools Market Evolving Landscape
Telemetry pipelines are evolving from proprietary collection agents toward vendor-neutral instrumentation standards. This architectural pivot is compressing switching costs and redistributing value capture from data ingestion volume toward analytics sophistication.
OpenTelemetry is supplanting vendor-specific application performance monitoring agents as the dominant instrumentation standard. Financial services institutions in London and Singapore are adopting it aggressively to avoid lock-in. The standardization of telemetry collection is commoditizing raw data ingestion and forcing vendors to differentiate on correlation engines and automated remediation.
The EU NIS2 Directive mandates incident reporting timelines that legacy monitoring architectures cannot satisfy. Critical infrastructure operators must deploy sub-second detection capabilities to meet the directive's 24-hour notification windows. German energy utilities and French healthcare networks are accelerating procurement of security information and event management platforms with native SOAR integration.
Enterprise buyers are consolidating monitoring spend through platform contracts rather than best-of-breed point solutions. Infrastructure teams at US healthcare systems and European automotive manufacturers now prioritize unified observability over specialized tools. This preference shift favors vendors with broad telemetry coverage, compressing addressable markets for narrowly focused application performance monitoring specialists.
Monitoring Tools Market Segmentation
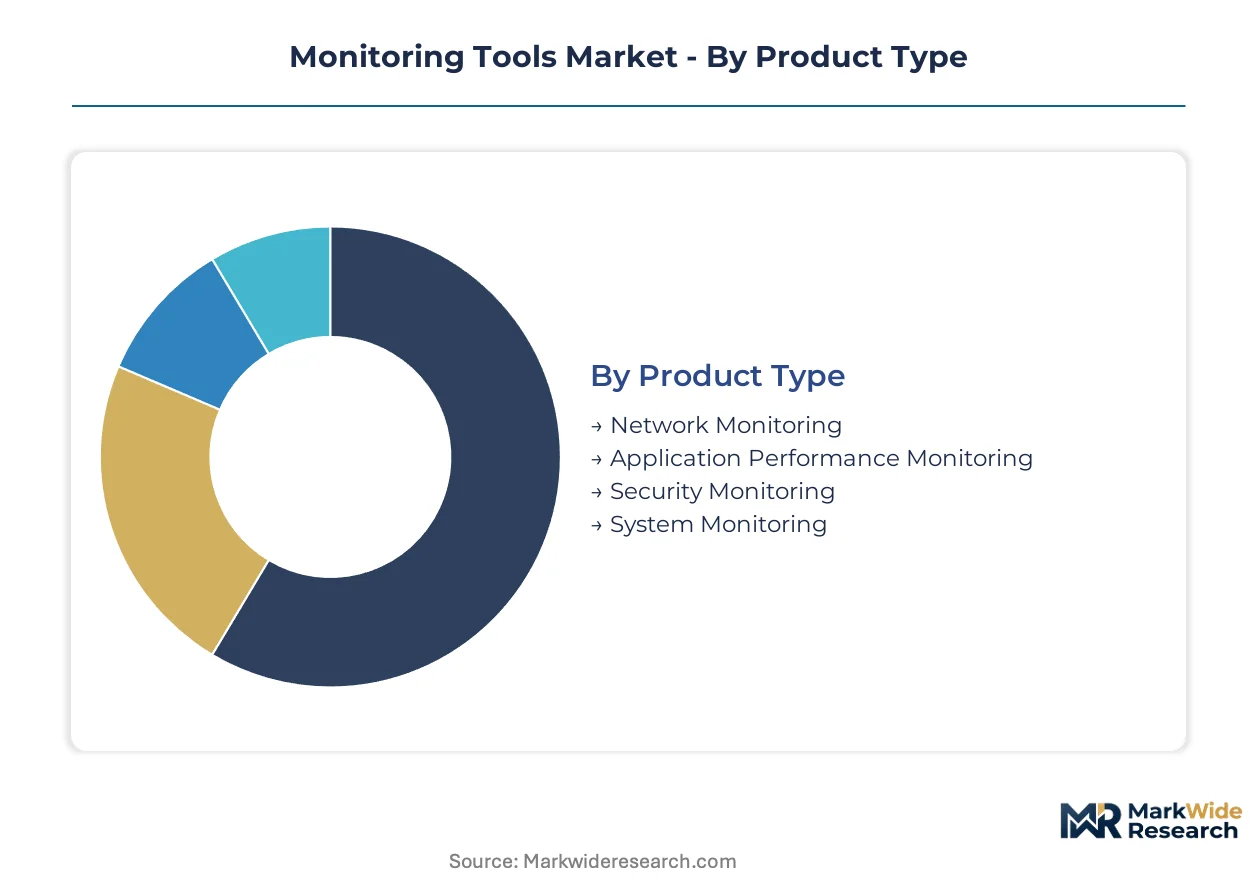
Segmentation in monitoring tools reveals distinct margin architectures across telemetry collection modes, deployment topologies, and operational workflows. Procurement patterns diverge sharply between compliance-driven government buyers and velocity-focused cloud-native enterprises, reshaping vendor product roadmaps and pricing structures.
Product Type:
Margin pools concentrate in application-layer telemetry where distributed tracing complexity sustains premium pricing, while network infrastructure monitoring faces commoditization pressure from open-source alternatives.
- Application Performance Monitoring:Captures distributed traces, code-level latency measurements, and dependency mapping across microservices architectures. Financial services institutions in Frankfurt and Singapore are expanding procurement budgets to satisfy EU AI Act logging mandates for high-risk automated decision systems.
- Security Monitoring:Correlates threat intelligence feeds with behavioral analytics and endpoint telemetry. Zero-trust architectures in US federal contractor supply chains are displacing periodic audits with continuous verification requirements, accelerating platform procurement faster than other product categories.
- Network Monitoring:Tracks packet flows, device health, and topology changes across physical and virtual infrastructure layers. SNMP-based legacy instrumentation in industrial control systems creates implementation friction that extends sales cycles.
- System Monitoring:Collects CPU, memory, disk, and process metrics from servers and virtual machines. Mid-market enterprises favor this category for baseline infrastructure visibility before advancing to full-stack observability.
Application Performance Monitoring holds installed capacity. Security Monitoring is rotating up the share rankings.
Deployment:
Cloud-native delivery models are compressing deployment cycles from months to days, though regulated industries maintain hybrid configurations to satisfy data sovereignty requirements.
- Cloud-Based:Delivers telemetry ingestion, storage, and analytics through hyperscale provider infrastructure. German automotive manufacturers and French healthcare networks are migrating workloads to meet EU NIS2 Directive incident reporting timelines that legacy architectures cannot satisfy.
- Hybrid:Combines on-premises collectors with cloud analytics planes to satisfy data residency constraints. India's digital public infrastructure expansion and state-level data center buildouts are creating greenfield demand for this deployment model.
- On-Premises:Maintains complete telemetry stack within customer-controlled facilities. Energy utilities and defense contractors in Germany retain this model for operational technology networks air-gapped from public internet.
- SaaS:Provides fully managed multi-tenant observability with consumption-based pricing. Small and mid-sized enterprises in the United Kingdom and Netherlands prefer this option for minimal operational overhead.
On-Premises retains the largest installed base. Cloud-Based deployment is climbing the fastest.
End User:
Procurement authority is fragmenting as DevOps teams gain direct purchasing power alongside traditional IT procurement functions, reshaping vendor sales motion and contract structures.
- Enterprises:Large organizations with dedicated platform engineering teams consolidating monitoring spend through unified contracts. US healthcare systems and European automotive manufacturers now prioritize breadth of telemetry coverage over specialized point solutions.
- Government:Federal, state, and municipal agencies with stringent compliance and security classification requirements. SEC disclosure rules for material cyber incidents and FDA software-as-medical-device guidelines elevate monitoring from operational convenience to regulatory necessity.
- IT Departments:Internal technology organizations managing infrastructure for single enterprises. These buyers favor agent-based collection systems with mature configuration management integrations.
- Service Providers:Managed service providers and systems integrators delivering observability as a managed offering to downstream clients. Multi-tenant architectures and white-label capabilities differentiate vendor suitability for this segment.
Enterprises command the deepest vendor relationships. Government is gaining procurement velocity fastest.
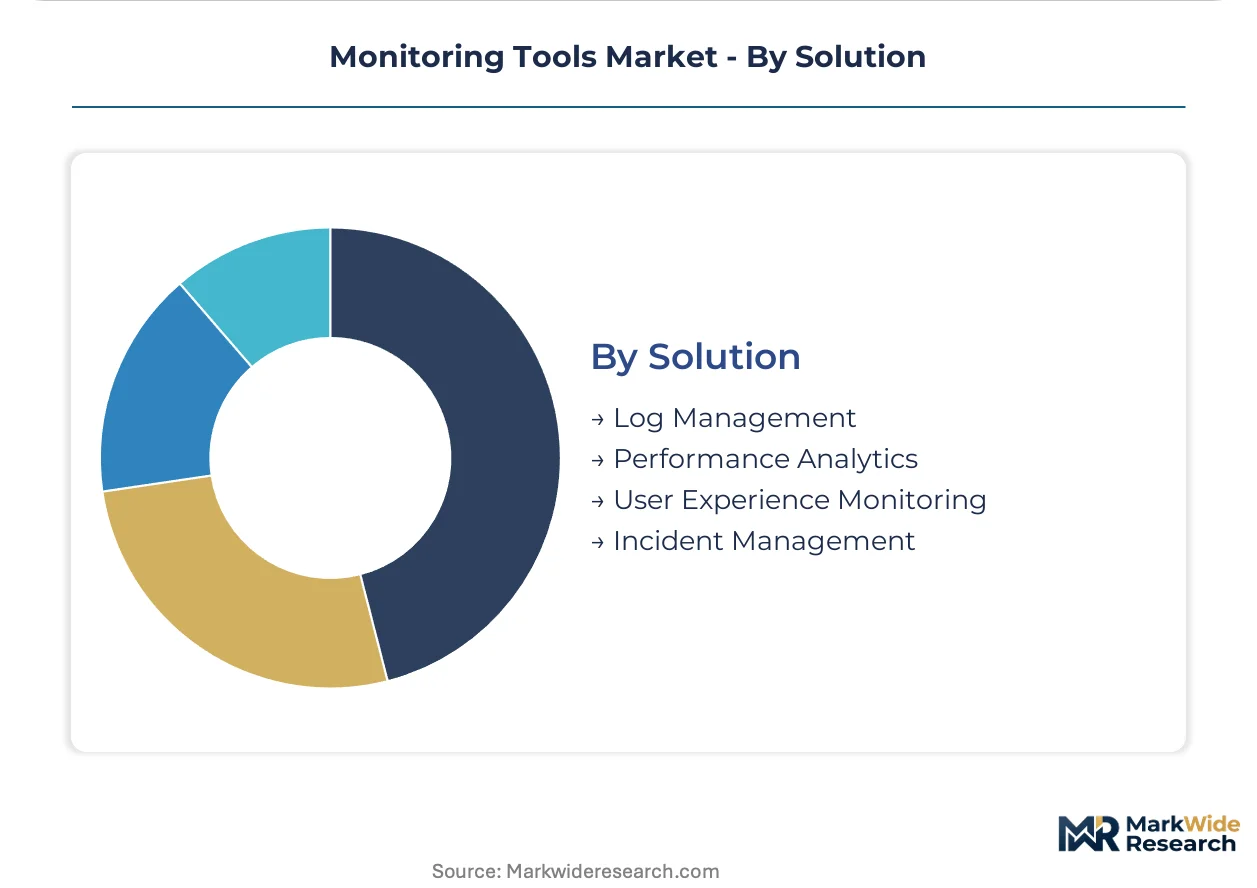
Solution:
Workflow integration depth determines pricing power, with platforms embedding remediation automation commanding premiums over passive analytics tools.
- Incident Management:Orchestrates alerting, escalation, and response workflows with native SOAR platform integration. French healthcare networks and German energy utilities are accelerating procurement to satisfy EU NIS2 Directive 24-hour notification windows.
- Performance Analytics:Applies statistical and machine learning methods to telemetry streams for anomaly detection and capacity forecasting. Carbon-aware workload scheduling features are opening sustainability-linked procurement channels in Nordic markets.
- Log Management:Centralizes structured and unstructured event data with search and retention policies. OpenTelemetry standardization is commoditizing collection and shifting value toward correlation engine sophistication.
- User Experience Monitoring:Captures synthetic transactions and real user session data to quantify application responsiveness. Retail and e-commerce operators deploy this solution to protect revenue-critical digital storefronts.
Log Management maintains the broadest deployment footprint. Incident Management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes monitoring tools through industrial digitization mandates that prioritize manufacturing execution system oversight, while the United States deploys them for zero-trust security compliance in federal contractor networks. This consumption-mix differential reflects Europe's regulatory-driven procurement versus North America's security-centric adoption patterns.
Germany
Industrie 4.0 programs require real-time telemetry across manufacturing networks, pulling predictive maintenance data into unified platforms. The EU NIS2 Directive imposes 24-hour incident notification windows that legacy architectures cannot satisfy. Energy utilities in North Rhine-Westphalia and automotive manufacturers in Bavaria are accelerating procurement of security information and event management platforms with native SOAR integration.
United States
Zero-trust security architectures mandate continuous verification telemetry across federal contractor supply chains, displacing periodic audits with always-on monitoring. SEC disclosure rules for material cyber incidents elevate observability from operational convenience to regulatory necessity. Healthcare systems in the Northeast Corridor and defense contractors in Virginia are consolidating monitoring spend through unified platform contracts.
France
Healthcare networks must deploy sub-second detection capabilities to meet EU NIS2 Directive reporting timelines. The EU AI Act logging mandates for high-risk automated decision systems expand observability procurement budgets across Paris and Lyon. Energy operators in Île-de-France are migrating workloads to cloud-based deployment to satisfy directive requirements that on-premises legacy systems cannot meet.
India
Digital public infrastructure expansion through the unified payments interface and health stack creates greenfield demand for observability across state-level data centers. The country's data protection rules force hybrid deployment configurations combining on-premises collectors with cloud analytics planes. Telangana and Karnataka are emerging as concentration points for monitoring tool deployment in government data centers.
United Kingdom
Financial services institutions in London and Singapore are adopting OpenTelemetry aggressively to avoid vendor lock-in. Small and mid-sized enterprises prefer SaaS delivery for minimal operational overhead. The concentration of fintech operators in London drives demand for application performance monitoring with granular distributed tracing capabilities.
Monitoring Tools Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the monitoring tools market, with hyperscale cloud providers leveraging platform bundling against pure-play observability vendors. The competitive structure privileges vendors with native Kubernetes instrumentation over those anchored in virtual-machine-era paradigms. Three archetypes dominate: integrated cloud platforms, AI-driven automation specialists, and open-standards-native challengers. M&A activity concentrates on telemetry correlation engine acquisitions, while strategic partnerships focus on OpenTelemetry standardization efforts.
Within the integrated platform tier, Microsoft Corporation exemplifies ecosystem bundling economics through Azure-anchored infrastructure monitoring. Datadog occupies a position representing granular application performance telemetry specialization. Dynatrace anchors the AI-driven root-cause automation archetype for enterprise Kubernetes environments. These three companies collectively illustrate the strategic divergence between breadth-first platform consolidation and depth-first observability specialization.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Datadog |
| Splunk |
| Cisco Systems |
| Dynatrace |
| SolarWinds |
| IBM Corporation |
| Google Cloud |
| Others |
Value Network & Pricing Analysis
EU NIS2 Directive compliance certification gates vendor qualification and simultaneously stratifies price tiers across the European monitoring tools procurement landscape. Buyers in Frankfurt and Paris pay premiums for platforms with native SOAR integration that satisfies 24-hour incident notification mandates, while uncertified alternatives compete on cost elsewhere.
Pricing Analysis
Contract structures in monitoring tools split between annual SaaS subscriptions with consumption-based tiers and multi-year enterprise platform agreements with committed minimums. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by AI-driven automation depth and Kubernetes-native instrumentation sophistication. Price erosion runs through the standard tier as OpenTelemetry commoditizes raw telemetry ingestion. Small and mid-sized enterprises in the United Kingdom exhibit highest price sensitivity, while German automotive manufacturers prioritize capability breadth over unit cost.
Supply Chain Analysis
eBPF kernel instrumentation expertise concentrates in San Francisco, Berlin, and Seattle, creating a talent chokepoint that inflates implementation costs and extends delivery timelines. Software development draws from specialized systems programming skills, hyperscale cloud infrastructure, and open-source community contributions. Single-source vulnerability in distributed tracing library maintenance poses structural risk as key OpenTelemetry components rely on volunteer-maintained code. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in monitoring tools hinge on OpenTelemetry standardization eroding data ingestion moats and redistributing value toward correlation engines. Interoperability shifts favor vendors with native Kubernetes instrumentation over legacy virtual-machine-era architectures.
For Market Incumbents: Compound platform stickiness through embedding automated remediation workflows that extend beyond telemetry collection into incident response orchestration. Deepen vertical integration into eBPF kernel instrumentation capabilities to defend against open-source commoditization. Prioritize certification investment for EU AI Act and NIS2 Directive compliance to maintain pricing power in European procurement cycles.
For New Entrants and Emerging Players: Edge computing telemetry gaps in manufacturing sites and retail locations represent underserved white-space where lightweight agent architectures can establish first-mover position. India's digital public infrastructure expansion offers the most penetrable geography for greenfield deployment. Pursue channel partnerships with systems integrators delivering observability as managed services to bypass direct enterprise sales barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed application performance monitoring specialists facing consolidation pressure from unified observability platforms. Long-term viability favors vendors with AI-driven root-cause automation and broad telemetry coverage over narrow point solutions. Watch for hyperscaler bundling economics compressing standalone vendor margins as the inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding OpenTelemetry-native instrumentation reduces switching costs and accelerates procurement cycles for Kubernetes environments. |
| Acquisition of Specialist Firm | Telemetry correlation engine acquisitions address skill gaps in eBPF kernel programming and distributed systems tracing. |
| Strategic Partnership | Hyperscaler marketplace listings expose monitoring tools to cloud migration budgets at financial services institutions. |
| Geographic Expansion | State-level data center buildouts in India create greenfield demand for hybrid deployment observability platforms. |
| Product Launch | Carbon-aware workload scheduling features open sustainability-linked procurement channels in Nordic energy markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform engineering directors, DevOps team leads, IT procurement officers, and managed service provider executives. Secondary validation drew from SEC filings of publicly traded observability vendors, hyperscaler capex disclosures, EU regulatory documentation on NIS2 and AI Act implementation, and OpenTelemetry community contribution metrics. Bottom-up telemetry volume estimates and top-down IT spend allocation models were triangulated to cross-check market sizing.
Across the analysis window, forecasts model deployment topology, organization size tier, vertical industry segment, and integration complexity as core segmentation dimensions. CAGRs derive from elasticity modeling of cloud migration velocity against regulatory compliance deadlines. Industry-specific inputs include Kubernetes adoption curves in financial services, Industrie 4.0 program spending trajectories in Germany, and zero-trust architecture implementation timelines in US federal contractor supply chains.
Material uncertainties — regulatory enforcement intensity, open-source standardization pace, and hyperscaler bundling economics — sit outside the modeled envelope. Forecasts reflect assumptions about continued cloud migration momentum and sustained EU compliance mandate expansion. Practitioners should keep alternative scenarios live as OpenTelemetry ecosystem maturity and talent availability constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Communication Test Equipment (CTE) Market