
 AGV Dispatch Management Platforms Market | 2026-2036
AGV Dispatch Management Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
AGV Dispatch Management Platforms Market Insights
Germany is rewriting deployment benchmarks for AGV dispatch systems through its dense automotive manufacturing corridor. Daifuku leverages deep integration with conveyor and storage systems to anchor European fulfillment networks. KION Group sustains technology leadership through proprietary fleet management algorithms that optimize multi-vendor robot coordination. Toyota Industries dominates Asia-Pacific manufacturing sites with dispatch platforms tightly coupled to its own AGV hardware ecosystem.
AGV dispatch management platforms are software systems that orchestrate the movement, task allocation, and traffic management of automated guided vehicles through real-time fleet communication protocols, typically processing positional data at sub-second intervals to prevent deadlock and optimize route efficiency in material handling environments. Their primary purpose is to synchronize heterogeneous robot fleets with warehouse execution systems and enterprise resource planning layers. Cloud-based deployments are capturing the fastest expansion as third-party logistics operators seek elastic capacity without capital-heavy infrastructure commitments. Machine learning segments command premium positioning by enabling predictive maintenance and dynamic path recalculation that reduces fleet idle time. Warehouse automation applications remain the volume anchor, though pharmaceuticals is emerging as a high-margin niche where cleanroom-compatible dispatch protocols justify specialized software licensing.
The EU Machinery Directive and CE marking requirements shape product development cycles by mandating functional safety validation for autonomous navigation algorithms before market entry. OSHA workplace safety standards in the United States influence deployment architectures by requiring human-robot collision avoidance protocols that dispatch platforms must enforce in mixed-traffic zones. Japan's METI industrial automation guidelines promote interoperability frameworks that vendors must address to access precision manufacturing sectors. Stakeholders must weigh regulatory compliance roadmaps against the pace of edge-computing advancements that promise decentralized fleet decision-making.
Market Dynamics
Edge computing architectures are compressing decision latency in AGV dispatch systems from centralized cloud dependencies to localized processing nodes, forcing software vendors to rearchitect fleet orchestration algorithms for distributed intelligence.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics operators in Germany are deploying multi-vendor fleet orchestration to manage surge order volumes during peak retail periods.
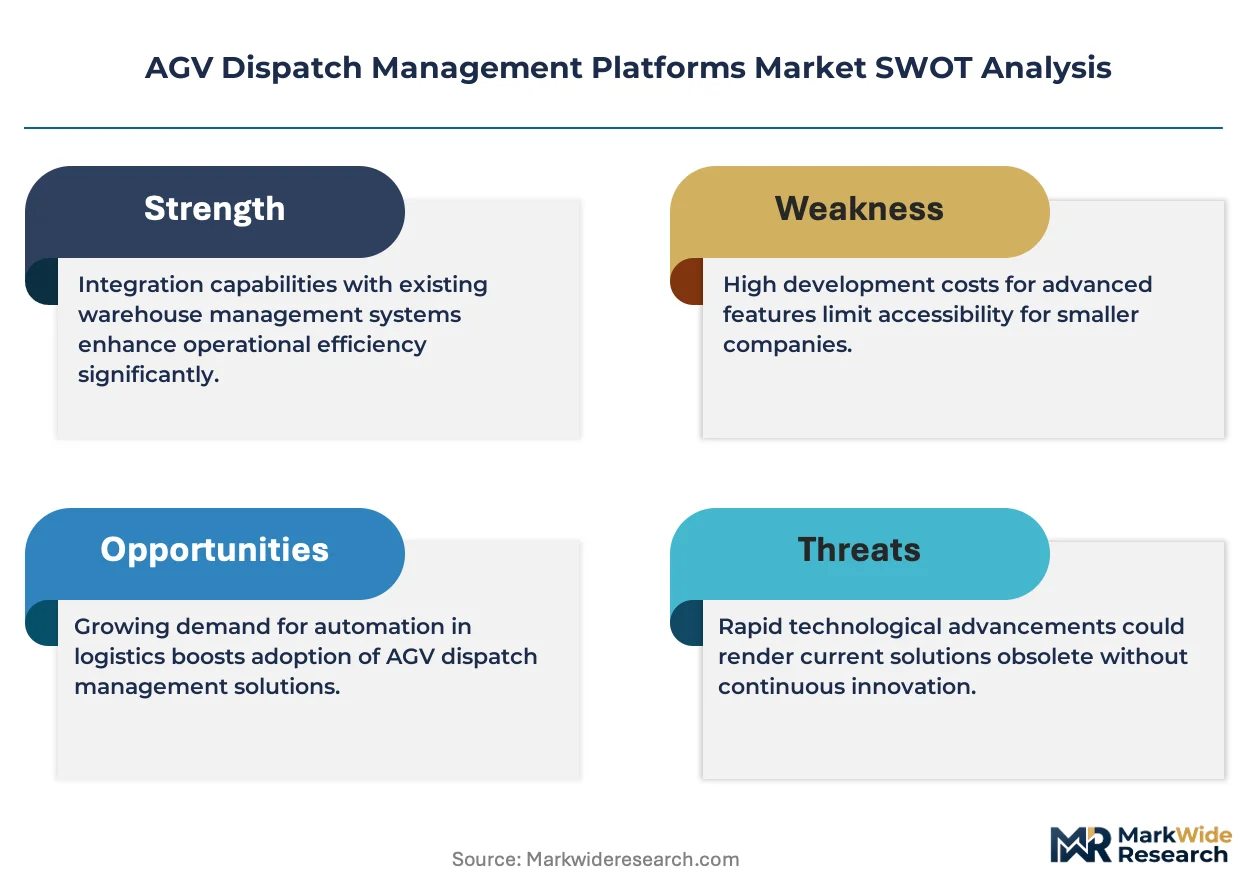
- EU AI Act compliance frameworks:Safety certification requirements for autonomous navigation algorithms are accelerating procurement of validated dispatch software by automotive OEMs.
- Pharmaceutical cleanroom protocols:Specialized dispatch licensing for contamination-controlled environments is opening high-margin deployment opportunities in sterile manufacturing facilities.
Market Restraints
- Functional safety validation costs:CE marking requirements under the EU Machinery Directive extend product development cycles by 12-18 months for new algorithm releases.
- Semiconductor supply concentration:Edge-computing hardware dependencies on Taiwanese foundry capacity create procurement bottlenecks for localized processing nodes.
- Legacy warehouse management integration:Proprietary communication protocols in incumbent ERP systems constrain plug-and-play deployment of cloud-native dispatch platforms.
Strategic Opportunities
- India's PLI scheme for logistics automation:Production-linked incentives for warehouse robotics are creating first-mover advantages for dispatch platform vendors establishing local partnerships.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling real-time fleet coordination in sprawling manufacturing campuses previously unreachable by Wi-Fi.
- Japan's METI interoperability frameworks:Standardized robot-to-robot communication protocols are reducing integration friction for multi-vendor deployments in precision manufacturing.
Industry Challenges
- Multi-protocol integration complexity:Dispatch platforms must simultaneously support VDA 5050, MassRobotics, and proprietary OEM interfaces without performance degradation.
- Safety-certified software talent scarcity:Functional safety engineering expertise for autonomous navigation validation remains concentrated among a limited pool of specialists in Stuttgart and Munich.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AGV Dispatch Management Platforms Market |
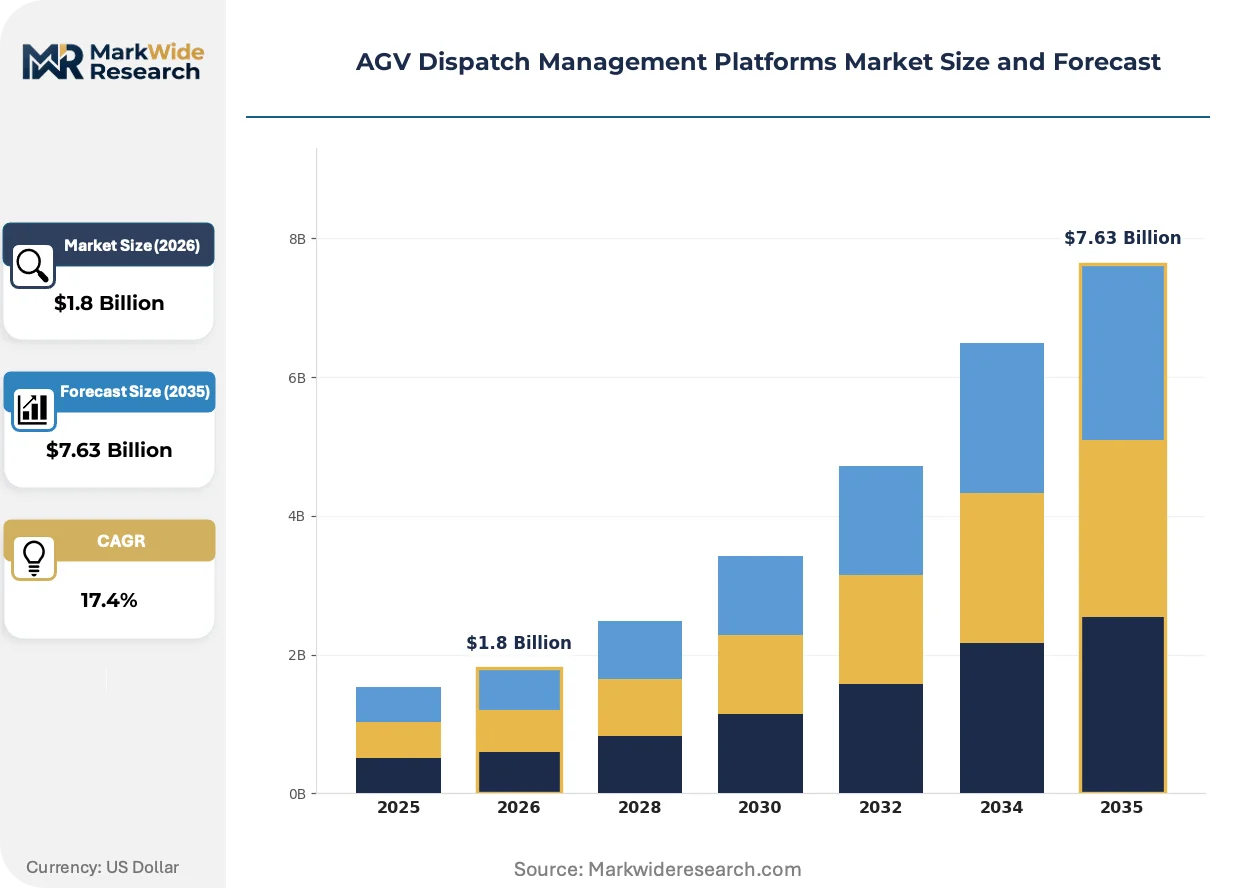
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.63 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Cloud-based, On-premise Technology: Wireless Communication, RFID, LIDAR, Machine Learning, GPS, Bluetooth Application: Warehouse Automation, Factory Automation, Pharmaceuticals, Food Processing, E-commerce Fulfillment End User: Manufacturers, Logistics Providers, Third-party Operators, Research Institutions |
| Companies Covered | Daifuku, KION Group, Toyota Industries, Dematic, Jungheinrich, Swisslog, Seegrid, JBT, SSI Schäfer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AGV Dispatch Management Platforms Market Trends and Innovations
Machine learning inference is migrating from cloud data centers to vehicle-mounted edge processors, collapsing the round-trip latency that previously constrained real-time path optimization in dense fleet environments.
Digital twin simulation is hybridizing physical deployment workflows by enabling virtual commissioning of dispatch algorithms against warehouse digital replicas before live fleet activation. Automotive OEMs in Wolfsburg are adopting this pre-deployment validation to minimize production line disruption during AGV network upgrades. The technology is compressing commissioning timelines from months to weeks while reducing collision incidents during initial rollout phases.
Japan's METI industrial automation guidelines are mandating interoperability certifications for dispatch software accessing precision manufacturing sectors. Vendors must demonstrate VDA 5050 compliance and open API architectures to qualify for public infrastructure procurement. German automotive suppliers exporting to Japanese electronics factories are accelerating certification investments to maintain market access.
Subscription-based licensing is displacing perpetual software purchases among third-party logistics operators seeking elastic capacity without capital-heavy infrastructure commitments. Cloud-native deployments with usage-based pricing are capturing mid-market warehouse operators previously priced out of on-premise implementations. This shift is most visible in Netherlands-based fulfillment networks serving cross-border e-commerce volumes.
AGV Dispatch Management Platforms Market Segmentation
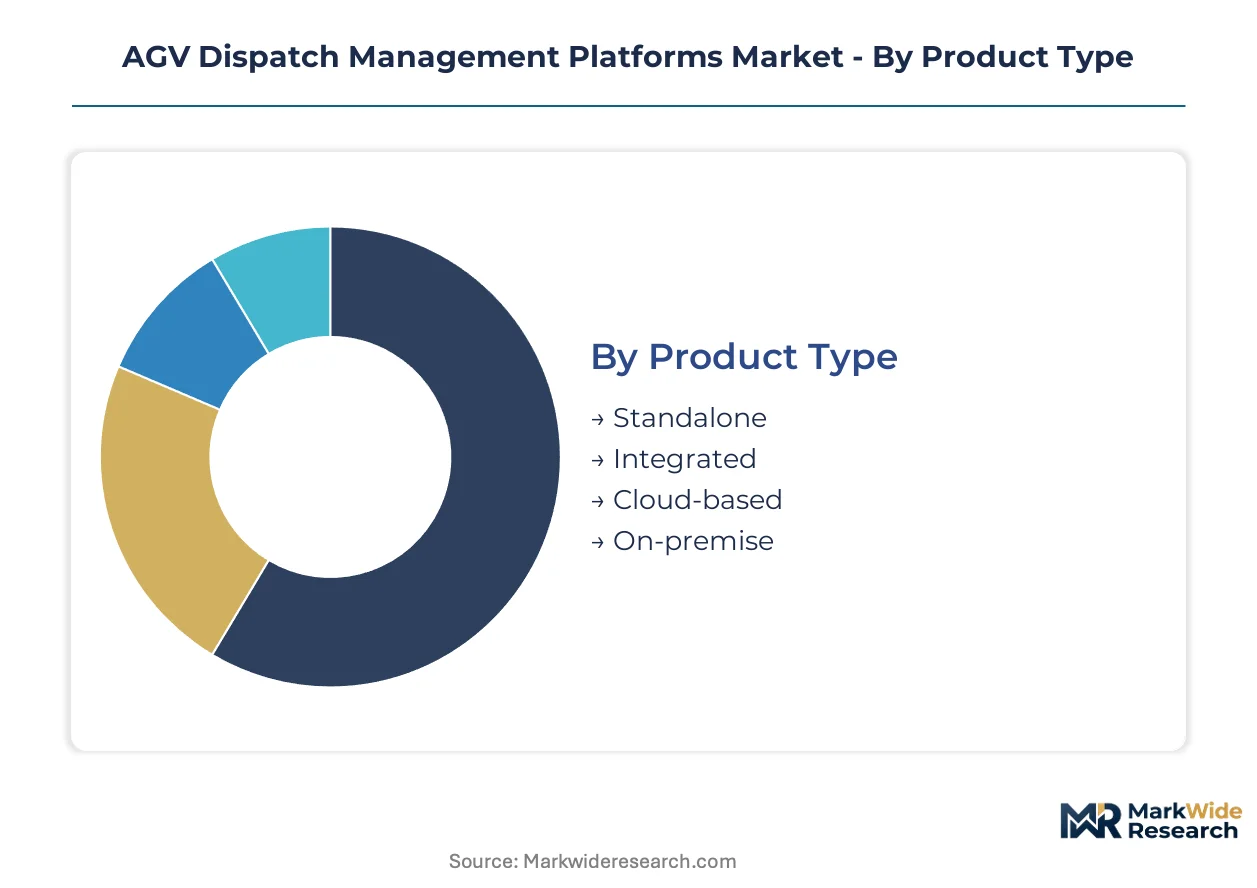
AGV dispatch platforms segment across deployment architectures, sensing technologies, and operational environments. Procurement cycles vary dramatically — cloud-native solutions refresh quarterly while on-premise installations lock capital for years.
Product Type:
Deployment models diverge sharply in renewal velocity. Cloud-based contracts turn over fastest as operators renegotiate capacity tiers seasonally. On-premise licenses cycle slowest due to capital amortization schedules.
- Cloud-based:Elastic compute architectures enable usage-based pricing that scales with fleet size. Third-party logistics operators in Netherlands fulfillment hubs favor this model for peak-season capacity surges without infrastructure lock-in. The EU AI Act's algorithm validation requirements are accelerating procurement of pre-certified cloud stacks over custom builds.
- Integrated:Tight coupling with warehouse execution systems and enterprise resource planning layers creates sticky deployments. Automotive OEMs in Stuttgart manufacturing corridors specify these bundles to minimize multi-vendor integration friction during line upgrades.
- Standalone:Modular dispatch software deploys alongside existing automation infrastructure. Mid-market manufacturers in India's PLI scheme zones adopt these for phased fleet expansion.
- On-premise:Perpetual licensing with localized data residency satisfies pharmaceutical cleanroom protocols requiring air-gapped operational technology networks.
Integrated deployments anchor the volume base while cloud-based solutions gain share at the steepest rate.
Technology:
Sensor and communication layers stratify by precision requirements and electromagnetic environment constraints. LIDAR and machine learning command premium positioning through safety certification complexity.
- Machine Learning:Predictive maintenance algorithms and dynamic path recalculation reduce fleet idle time in dense multi-robot environments. German automotive plants in Wolfsburg specify ML-enabled dispatch for collision avoidance in mixed human-robot traffic zones.
- LIDAR:Sub-centimeter positional accuracy enables navigation in GPS-denied indoor facilities. Pharmaceutical sterile manufacturing in Basel corridors mandates LIDAR-based dispatch for contamination-controlled material movement.
- Wireless Communication:Wi-Fi and 5G private networks transmit fleet coordination commands at sub-second intervals. Japanese electronics factories under METI interoperability guidelines standardize on wireless protocols for multi-vendor robot fleets.
- RFID:Floor-mounted transponders provide absolute positioning reference points in high-bay storage environments.
- GPS:Outdoor yard management and sprawling campus logistics rely on satellite positioning for vehicle localization.
- Bluetooth:Low-energy beacons supplement indoor positioning in confined aisles where LIDAR line-of-sight degrades.
Wireless communication underpins the widest deployment base while machine learning expands most quickly through predictive capability premiums.
Application:
End-use environments impose divergent cleanliness, throughput, and safety constraints. E-commerce and pharmaceuticals sit at opposite poles of volume-versus-margin positioning.
- Warehouse Automation:High-bay storage retrieval and cross-dock sortation drive the core installed base. German third-party logistics networks serving cross-border e-commerce operate the densest fleet concentrations.
- Pharmaceuticals:Cleanroom-compatible dispatch protocols with contamination tracking justify specialized software licensing. Swiss and German sterile manufacturing facilities enforce FDA and EMA validation requirements on navigation algorithms.
- E-commerce Fulfillment:Surge-volume orchestration during peak retail periods demands elastic fleet scaling. Netherlands-based operators lead deployment of multi-vendor coordination for same-day delivery commitments.
- Factory Automation:Just-in-sequence material delivery to production lines requires millisecond-level dispatch latency.
- Food Processing:Washdown-compatible hardware interfaces and allergen segregation protocols constrain software architecture choices.
Warehouse automation commands the largest fleet counts while pharmaceuticals delivers the steepest margin expansion trajectory.
End User:
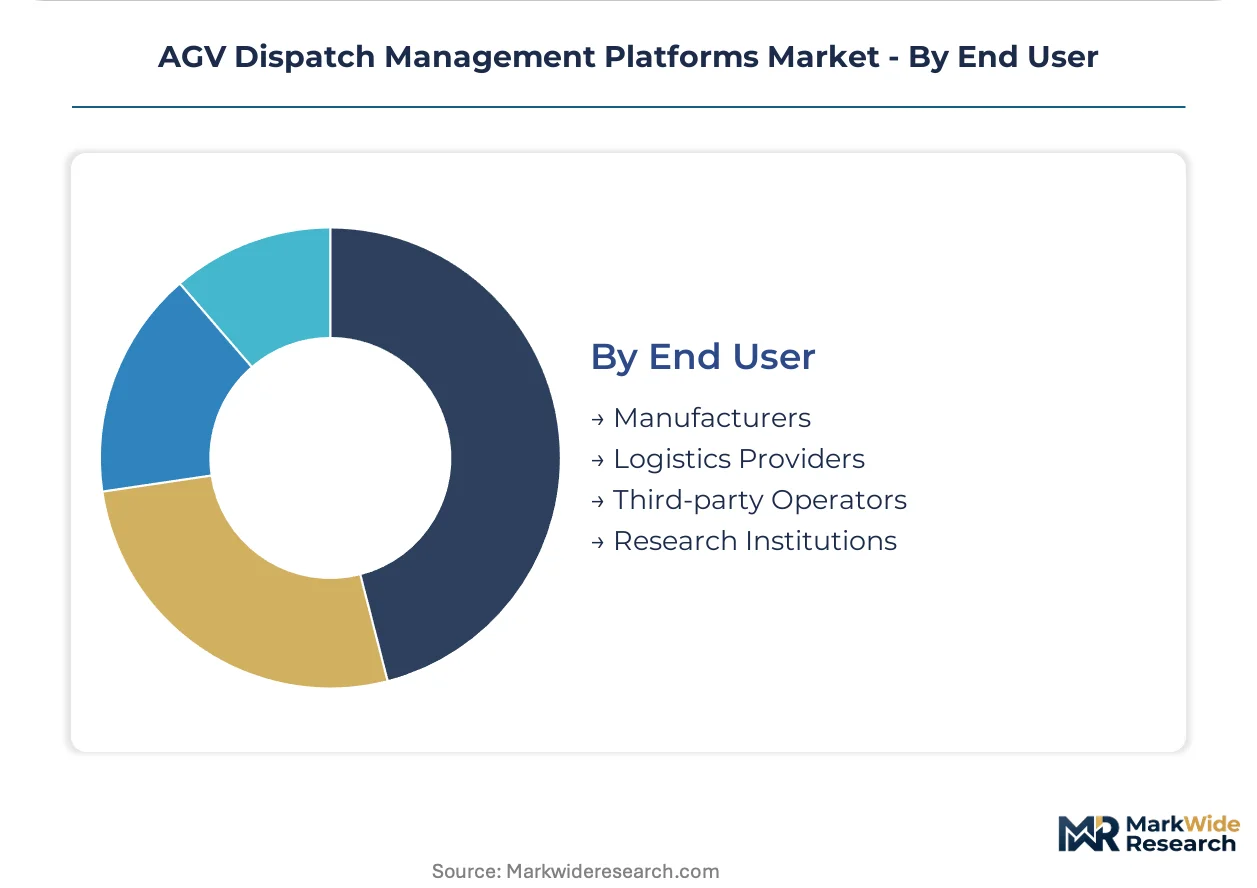
Customer archetypes separate by in-house technical capability and procurement sophistication. Manufacturers self-integrate while logistics providers demand turnkey orchestration.
- Logistics Providers:Asset-light operators prioritize cloud-native dispatch with usage-based economics. India's emerging warehouse automation sector under PLI incentives favors operational expenditure models over capital deployment.
- Manufacturers:Automotive OEMs in Germany's Stuttgart-Wolfsburg corridor operate captive fleet management competencies. Toyota Industries and KION Group subsidiaries deploy proprietary dispatch tightly coupled to in-house AGV hardware.
- Third-party Operators:Fulfillment specialists serving multiple retail clients require multi-tenant dispatch architectures with client-isolated workflow logic.
- Research Institutions:University robotics labs and national research centers pilot edge-computing dispatch algorithms before commercial transfer.
Manufacturers retain the deepest installed base while logistics providers are climbing the fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European procurement frameworks, compelling automotive OEMs to validate autonomous navigation algorithms before fleet deployment. German manufacturing corridors set the densest concentration benchmarks worldwide.
Germany
Automotive OEMs in Stuttgart and Wolfsburg operate captive AGV networks exceeding thousand-unit fleets per facility. The EU Machinery Directive mandates CE marking with functional safety validation extending development cycles. Baden-Württemberg's manufacturing belt concentrates software engineering talent for safety-certified dispatch systems.
United States
OSHA workplace safety standards enforce human-robot collision avoidance in mixed-traffic warehouse zones. Third-party logistics operators in California and Illinois prioritize cloud-native dispatch for elastic peak-season scaling. The Midwest automotive corridor sustains legacy on-premise installations tied to ERP integration requirements.
Japan
METI industrial automation guidelines mandate VDA 5050 interoperability for precision manufacturing access. Toyota Industries anchors proprietary dispatch tightly coupled to in-house AGV hardware across Aichi Prefecture plants. Kansai region electronics factories standardize on wireless protocols for multi-vendor fleet coordination.
India
The PLI scheme for logistics automation subsidizes warehouse robotics deployment in Maharashtra and Karnataka. Asset-light operators favor operational expenditure models over capital-heavy infrastructure commitments. Delhi-NCR fulfillment hubs pilot multi-tenant dispatch architectures for cross-border e-commerce volumes.
Netherlands
Randstad logistics networks serve as Europe's cross-border e-commerce fulfillment gateway. Cloud-native dispatch with usage-based pricing captures mid-market operators previously priced out of on-premise implementations. Rotterdam port automation drives edge-computing pilot programs for sprawling campus coordination.
AGV Dispatch Management Platforms Market Competitive Landscape
Capability concentration sits with specialized software vendors; scale advantage sits with diversified automation conglomerates. The vendor base stratifies across three tiers: captive hardware-integrated platforms, multi-vendor fleet orchestration specialists, and cloud-native SaaS providers. Dominant competitive moves include backward integration into edge-computing hardware and strategic partnerships for 5G private network deployment.
Among diversified automation conglomerates, Daifuku, KION Group, and Toyota Industries exemplify contrasting archetypes. Daifuku leverages deep European fulfillment network integration. KION Group sustains technology leadership through proprietary fleet management algorithms. Toyota Industries dominates Asia-Pacific manufacturing with dispatch platforms tightly coupled to captive AGV hardware ecosystems.
| Leading Market Players |
|---|
| Daifuku |
| KION Group |
| Toyota Industries |
| Dematic |
| Jungheinrich |
| Swisslog |
| Seegrid |
| JBT |
| SSI Schäfer |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwanese semiconductor foundries is compressing edge-computing hardware availability and forcing dispatch software vendors toward longer-term contracting postures with pricing premiums for guaranteed supply.
Pricing Analysis
German automotive OEMs pay 40-60% premiums over Netherlands-based logistics operators for equivalent dispatch functionality due to EU Machinery Directive certification requirements and embedded safety engineering. The dominant structure is three-tier pricing across premium, standard, and economy levels, with differentiation driven by ISO 26262 functional safety grade and after-sales service bundling. Cost compression in the economy tier is intensifying because cloud-native SaaS entrants are undercutting on-premise perpetual licenses. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for cleanroom-validated deployments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for edge-computing hardware components. Manufacturing concentrates in Taiwan, South Korea, and Germany for semiconductors, precision sensors, and industrial computing modules respectively. The ecosystem draws from specialized silicon wafers, LIDAR components, and 5G private network equipment as critical inputs. Single-source vulnerability in Taiwanese foundry capacity creates procurement bottlenecks for localized processing nodes. Distribution runs through systems integrators and direct OEM relationships rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AGV dispatch market is crossing a platform-economics inflection as VDA 5050 interoperability transforms captive hardware ecosystems into open orchestration layers.
For Market Incumbents: Insulate installed base relationships through backward integration into safety-certified edge hardware and accelerated EU AI Act compliance investments. Daifuku and KION Group face displacement risk from cloud-native SaaS entrants offering elastic pricing without capital commitment. Priority lever: captive supply of pre-validated algorithm stacks that compress customer procurement cycles. For New Entrants and Emerging Players: Pursue India's PLI scheme zones and mid-market pharmaceutical cleanroom deployments as the most penetrable white-space targets. Netherlands-based fulfillment networks already show pricing saturation, while German automotive corridors demand certification depth that favors incumbents. Go-to-market angle: usage-based SaaS pricing with rapid deployment templates for warehouse automation greenfield sites. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native dispatch vendors serving multi-tenant logistics networks. Long-term viability over a 5-10 year window favors platforms with demonstrated VDA 5050 interoperability and METI certification access. Acquisition target archetype: specialized machine learning inference engines for predictive fleet maintenance. Signal to watch: 5G private network deployment velocity in Japanese electronics manufacturing clusters as indicator of real-time coordination demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| VDA 5050 Interoperability Certification | Unlocks access to Japanese precision manufacturing under METI guidelines and German automotive supplier exports. |
| Edge-Computing Hardware Integration | Compresses decision latency for automotive OEMs in Stuttgart-Wolfsburg corridors demanding sub-second fleet coordination. |
| Cloud-Native SaaS Platform Launch | Captures Netherlands-based logistics operators seeking elastic capacity without infrastructure lock-in. |
| Pharmaceutical Cleanroom Validation | Opens high-margin Swiss and German sterile manufacturing where FDA and EMA algorithm requirements justify premium licensing. |
| 5G Private Network Partnership | Enables real-time fleet coordination in sprawling Rotterdam port campuses previously unreachable by Wi-Fi coverage. |
Research Methodology
A standing panel of fleet operations directors, warehouse automation engineers, safety certification specialists, and third-party logistics procurement leads provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SEC filings, EU Machinery Directive certification databases, METI interoperability registries, and customs trade data for industrial automation equipment. Bottom-up fleet deployment counts triangulated against top-down software licensing revenue estimates.
Scenario-bracketing framed demand projections across the analysis window with segmentation across deployment architecture, sensing technology, application environment, and end-user archetype. CAGRs derived from fitted growth curves applied to base-year fleet penetration rates, incorporating EU AI Act implementation timelines and India's PLI scheme disbursement schedules as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at automotive OEMs or semiconductor foundry utilization rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and edge-computing hardware availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Underwater Jetpack Market