
 Global Correspondence Management System Market | 2026-2036
Global Correspondence Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Correspondence Management System Market Intelligence
ISO 27001 certification is collapsing the vendor landscape for enterprise correspondence platforms, eliminating providers lacking audited information security management systems. Microsoft Corporation leverages its Azure cloud infrastructure to anchor large-scale government deployments across North America and Western Europe. IBM Corporation competes through specialized compliance management modules that address sector-specific retention mandates in banking and insurance. OpenText Corporation dominates on-premises legacy transitions, sustaining revenue from institutions with hybrid deployment requirements.
A correspondence management system constitutes an integrated software platform that captures, routes, tracks, and archives inbound and outbound communications across physical and digital channels, typically supporting document formats from scanned mail to structured XML messages. The primary industrial purpose centers on ensuring audit trails, regulatory compliance, and operational continuity for organizations processing high volumes of time-sensitive communication. Cloud deployment leads absolute revenue contribution as banking institutions and insurance firms migrate off legacy infrastructure, while compliance management use cases generate the fastest expansion due to intensifying regulatory scrutiny. Software as a Service offerings capture widening margin pools through recurring subscription structures, though professional services retain importance in complex multi-system integrations for government agencies.
The US SEC and HIPAA frameworks mandate retention and accessibility standards that directly shape product development priorities for vendors serving financial and healthcare-adjacent sectors, while GDPR and the EU AI Act impose cross-border data governance constraints that limit hosting architecture choices. Japan's METI guidelines on electronic document authenticity further fragment certification requirements for multinational platform providers. Stakeholders must evaluate whether to consolidate around dominant cloud-native stacks or preserve interoperability with specialized compliance modules as regulatory divergence accelerates.
Market Dynamics
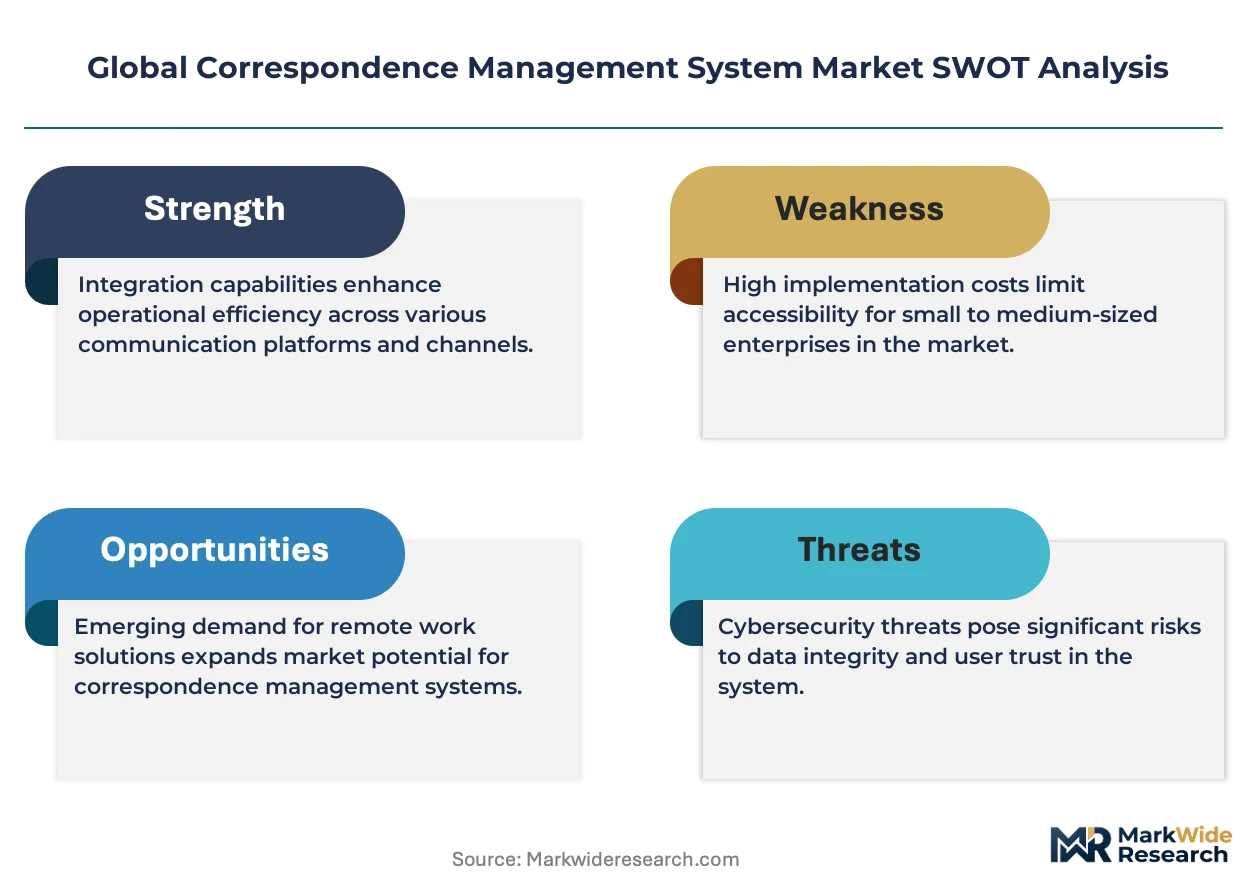
ISO 27001 certification requirements are compressing the vendor landscape, forcing institutions to abandon unaudited platforms and consolidate around providers with validated information security management systems.
Growth Catalysts
- EU AI Act compliance mandates:European financial institutions must deploy traceable, auditable communication systems for algorithmic decision documentation, accelerating platform replacement cycles.
- Cloud infrastructure migration:Banking and insurance firms are abandoning on-premises legacy systems for scalable SaaS architectures that reduce operational overhead.
- Germany:Regulatory stringency around data residency and document retention is compelling premium platform upgrades among mid-tier financial institutions.
Market Restraints
- ISO 27001 audit costs:Small and mid-sized vendors face prohibitive certification expenses that eliminate competitive participation in enterprise procurement.
- Hybrid deployment complexity:Institutions with legacy on-premises infrastructure encounter integration friction that extends implementation timelines and inflates professional services dependency.
- Cross-border data governance:GDPR and EU AI Act constraints limit hosting architecture choices for multinational deployments, fragmenting platform standardization.
Strategic Opportunities
- India:RBI guidelines on digital customer communication are creating demand for compliant correspondence platforms among expanding private banking networks.
- Natural language processing convergence:Integration of NLP with automated routing engines enables intelligent classification of unstructured inbound communications.
- Outcome-based pricing models:Vendors can capture recurring revenue through success metrics tied to compliance audit pass rates and processing efficiency gains.
Industry Challenges
- Multi-system integration complexity:Government agencies require specialized professional services to bridge legacy document management with modern correspondence platforms.
- Certification timeline compression:Accelerating regulatory deadlines in the EU and Japan strain vendor capacity to deliver compliant solutions before enforcement dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Correspondence Management System Market |
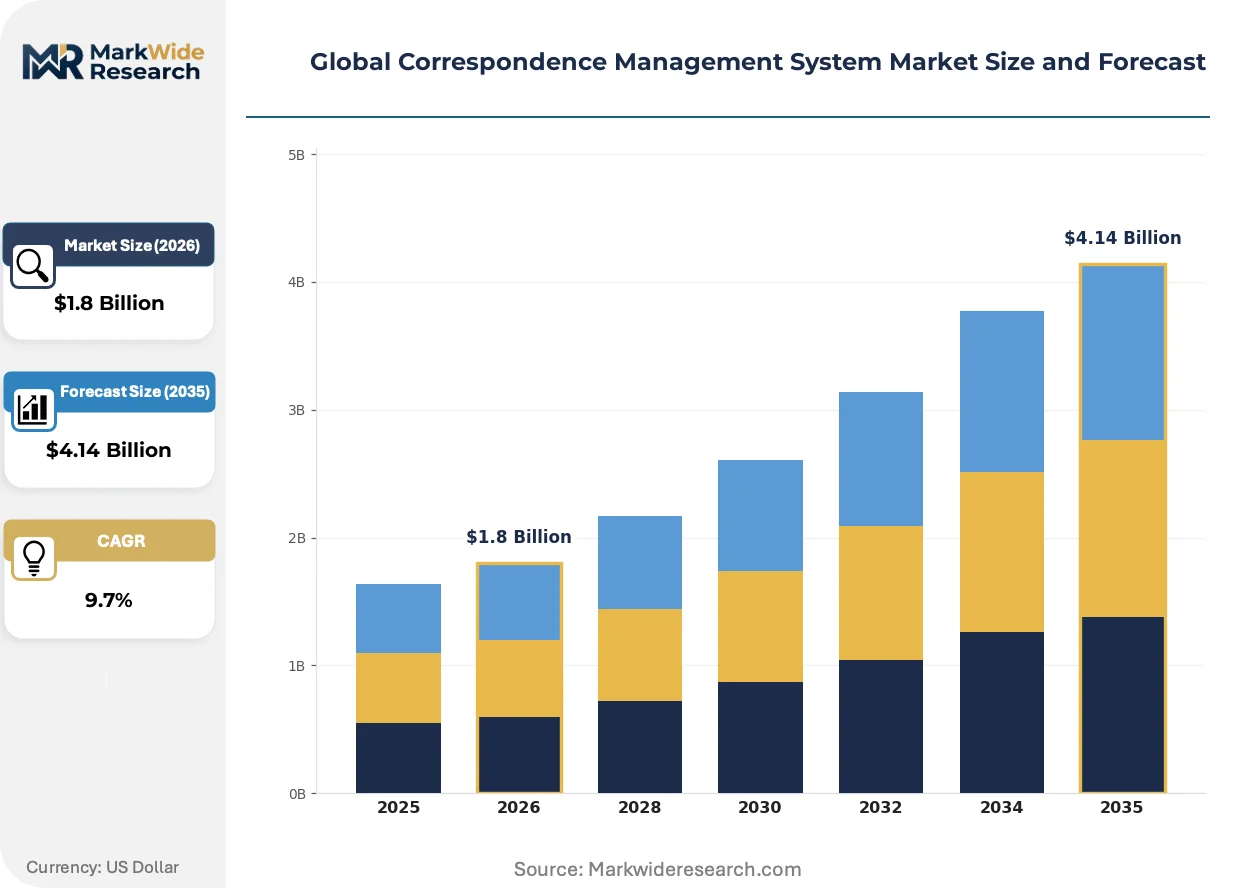
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Managed Services Offering: Software License, Software as a Service, Professional Services, Support & Maintenance Use Case: Customer Communication, Legal Documentation, Internal Collaboration, Compliance Management, Vendor Correspondence End User: Banking Institutions, Insurance Firms, Government Agencies, Legal Firms, Educational Institutions |
| Companies Covered | Microsoft Corporation, Pitney Bowes Inc., IBM Corporation, Hyland Software Inc., Newgen Software Technologies Ltd., Adobe Inc., Quadient SA, Fabasoft AG, OpenText Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Correspondence Management System Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how correspondence platforms classify, route, and archive communications, with regulatory pressure simultaneously mandating greater transparency in automated decision systems.
Natural language processing engines are bifurcating the market between basic keyword-based routing and advanced semantic understanding systems. Large banking institutions in Germany and France are adopting contextual analysis tools that interpret intent from unstructured email and scanned document content. This capability compression is eliminating vendors unable to deliver machine-learning-based classification, concentrating procurement around AI-native platform providers.
The EU AI Act imposes documentation requirements on automated communication systems that influence customer outcomes, compelling vendors to embed explainability modules. Financial institutions must now demonstrate how algorithmic routing decisions were reached during regulatory audits. Insurance sector deployments across the Netherlands and Belgium are most affected, with carriers retrofitting existing platforms to capture decision audit trails.
Subscription-based procurement is displacing perpetual license models as buyers prioritize operational expenditure predictability. Mid-sized banks in Canada and Australia are leading this transition, negotiating multi-year SaaS contracts with embedded compliance update guarantees. This shift compresses vendor cash conversion cycles while locking in recurring revenue streams that fund continuous platform development.
Global Correspondence Management System Market Segmentation
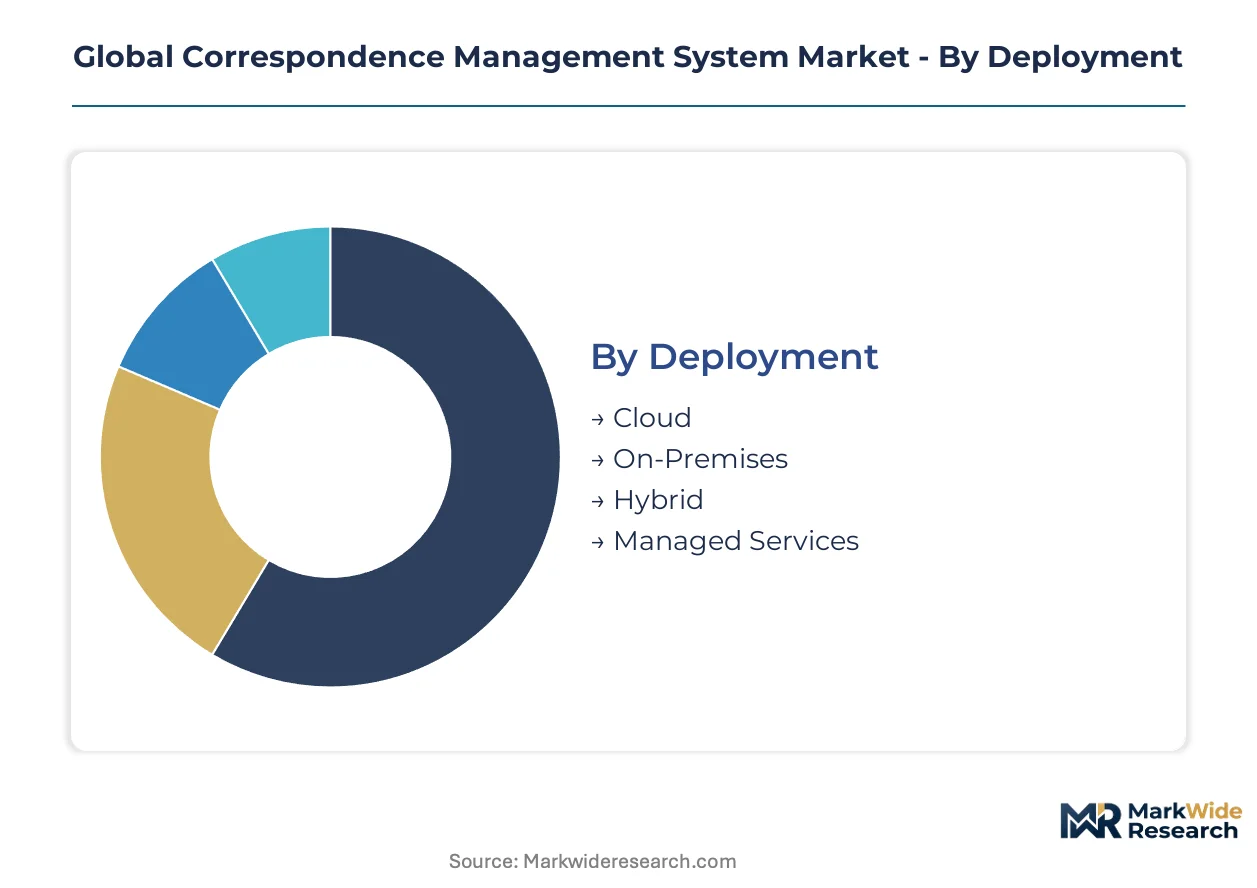
Correspondence management system procurement divides sharply between cloud-native architectures and legacy infrastructure preservation, with deployment choices cascading through pricing models, integration complexity, and compliance certification requirements across financial and government verticals.
Deployment:
Cloud deployments face substitution pressure from hybrid architectures as institutions with legacy document repositories resist full migration, while managed services erode both pure-cloud and on-premises positions through bundled operational accountability.
- Cloud:Multi-tenant SaaS architectures deliver elastic capacity for seasonal communication volumes. Banking institutions in Germany and France are consolidating procurement around ISO 27001-certified cloud platforms to satisfy GDPR data residency mandates without capital infrastructure commitment.
- On-Premises:Single-tenant installations retain air-gapped security for classified government communications. Defense agencies and central banks in Japan and Switzerland sustain demand despite higher total cost of ownership and extended implementation timelines.
- Hybrid:Split architectures route sensitive correspondence through on-premises nodes while leveraging cloud scale for routine processing. Insurance firms with decades of legacy document stores favor this model to defer full migration costs.
- Managed Services:Outsourced platform operation transfers compliance liability to vendor specialists. Mid-tier financial institutions in Canada and Australia adopt this model to access enterprise-grade security without internal security operations center investment.
On-Premises anchors the volume base while Managed Services gains share at the steepest rate.
Offering:
Recurring revenue models are displacing perpetual licenses as procurement teams prioritize operational expenditure predictability and embedded upgrade guarantees over upfront capital allocation.
- Software License:Perpetual purchase with annual maintenance contracts persists in government sectors with rigid capital budgeting cycles. Federal agencies in the United States and state-level entities in India negotiate multi-year site licenses to avoid subscription volatility.
- Software as a Service:Subscription pricing bundles platform access, infrastructure, and compliance updates into predictable monthly fees. Private banking networks in Singapore and the United Arab Emirates are migrating entire correspondence workflows to SaaS architectures.
- Professional Services:Custom integration, data migration, and workflow design address complex multi-system environments. Large insurance carriers in the Netherlands and Belgium require specialized consulting to bridge legacy policy administration with modern correspondence platforms.
- Support & Maintenance:Technical assistance, patch management, and help desk operations sustain platform performance. This segment expands through SLA-tiered offerings that guarantee response times for critical communication infrastructure.
Software License dominates current revenue contribution while Software as a Service climbs the fastest.
Use Case:
Compliance Management commands premium pricing through embedded audit trail functionality, while Customer Communication faces commoditization from generic email platforms and messaging applications.
- Customer Communication:Outbound statement generation, inbound inquiry routing, and multi-channel response orchestration. Retail banks in the United Kingdom and Spain deploy these capabilities to unify branch, digital, and call center touchpoints.
- Legal Documentation:Contract lifecycle correspondence, litigation hold management, and privileged communication archiving. Law firms in New York and London require tamper-proof chains of custody for discovery proceedings.
- Internal Collaboration:Cross-departmental memo distribution, policy dissemination, and executive briefing workflows. Large educational institutions in Australia use these tools to coordinate geographically distributed campuses.
- Compliance Management:Regulatory filing documentation, audit trail preservation, and algorithmic decision logging. EU AI Act mandates are accelerating deployment across French and German financial institutions.
- Vendor Correspondence:Procurement negotiation records, contract amendment tracking, and supplier performance documentation. Manufacturing conglomerates in Japan standardize vendor communication to satisfy METI electronic document authenticity guidelines.
Customer Communication provides the broadest installed base while Compliance Management expands most quickly.
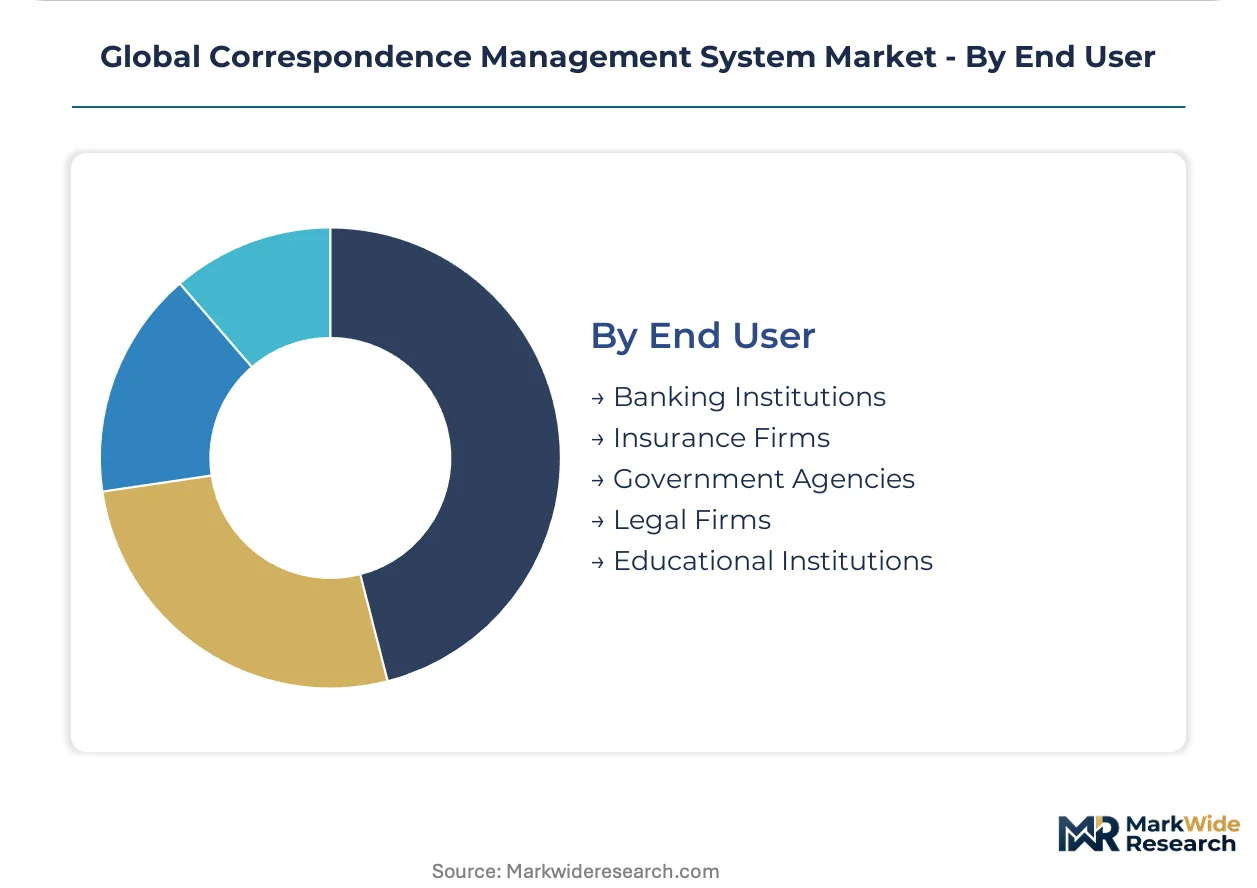
End User:
Banking Institutions concentrate procurement volume through centralized vendor negotiations, while Legal Firms fragment demand across specialized practice management integrations.
- Banking Institutions:Universal banks, private banks, and cooperative banking networks processing high-volume transactional correspondence. RBI guidelines in India are driving compliant platform adoption across expanding private banking networks.
- Insurance Firms:Life, property-casualty, and reinsurance carriers managing policyholder communications and claims correspondence. Dutch and Belgian carriers retrofit platforms to capture EU AI Act decision audit trails.
- Government Agencies:Federal, state, and municipal entities with classified and unclassified communication requirements. United States federal deployments favor Azure-anchored architectures for FedRAMP compliance.
- Legal Firms:Corporate law practices, litigation boutiques, and regulatory specialists requiring privilege protection. Magic Circle firms in London demand integration with existing document management systems.
- Educational Institutions:Universities, research hospitals, and multi-campus systems coordinating administrative and academic correspondence. Australian universities lead SaaS migration among this segment.
Banking Institutions anchor the volume base while Government Agencies gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking institutions and government agencies concentrate procurement across five national markets where regulatory stringency and digital infrastructure maturity intersect most sharply.
United States
Federal agencies and large banking networks drive enterprise-scale deployments. SEC retention mandates and HIPAA accessibility standards shape vendor product roadmaps. Washington D.C. and New York Metro anchor government and financial sector procurement respectively.
Germany
Mid-tier financial institutions pursue premium platform upgrades under data residency and document retention requirements. GDPR and EU AI Act compliance obligations accelerate replacement cycles. Frankfurt's banking cluster and Munich's insurance hub concentrate deployment activity.
India
Expanding private banking networks generate compliant platform demand under RBI digital communication guidelines. SaaS migration outpaces on-premises adoption among tier-2 institutions. Mumbai and Bangalore financial districts lead implementation timelines.
Japan
Central banks and defense agencies sustain on-premises demand for air-gapped security. METI electronic document authenticity guidelines fragment certification requirements for multinational providers. Tokyo's government district and Osaka's financial center maintain divergent procurement preferences.
United Kingdom
Retail banking consolidation drives unified correspondence platform procurement across branch, digital, and call center channels. FCA conduct rules and emerging AI governance expectations influence vendor selection. London's Square Mile and Edinburgh's insurance cluster represent distinct deployment archetypes.
Global Correspondence Management System Market Key Industry Players
Player mix skews toward cloud-native technology conglomerates and specialized compliance software vendors, with tiered competitive dynamics separating infrastructure-scale providers from modular specialists. Strategic positioning concentrates around three archetypes: hyperscale cloud platforms with integrated correspondence modules, legacy document management vendors transitioning to hybrid architectures, and compliance-focused specialists with sector-specific retention expertise. Dominant competitive moves include strategic partnerships between cloud infrastructure providers and compliance software vendors, plus portfolio diversification into adjacent customer communication management segments.
Within the hyperscale tier, Microsoft Corporation and IBM Corporation exemplify divergent approaches to enterprise capture. Microsoft leverages Azure cloud infrastructure to anchor large-scale government deployments, while IBM competes through specialized compliance management modules addressing banking and insurance retention mandates. OpenText Corporation occupies a distinct position among legacy transition specialists, sustaining revenue from institutions with hybrid deployment requirements. Adobe Inc. and Quadient SA represent customer experience platform vendors extending into correspondence management through adjacent capability integration.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Pitney Bowes Inc. |
| IBM Corporation |
| Hyland Software Inc. |
| Newgen Software Technologies Ltd. |
| Adobe Inc. |
| Quadient SA |
| Fabasoft AG |
| OpenText Corporation |
| Others |
Cost & Logistics Intelligence
Multi-year SaaS contracts with embedded compliance update guarantees lock in both supply access and price visibility for banking institutions migrating off legacy infrastructure. These structures transfer operational risk to vendors while securing predictable operational expenditure for buyers navigating intensifying regulatory deadlines.
Pricing Analysis
Cost-plus contracts with ISO 27001 certification indexation anchor enterprise procurement in Germany and France. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized deployments from mid-market SaaS and basic on-premises licenses. Price differentiation hinges on audit trail granularity and AI explainability module inclusion. Pricing pressure stems from subscription fatigue among tier-2 financial institutions in Canada and Australia. Government agencies exhibit lowest price sensitivity due to capital budgeting rigidity, while mid-tier banks in India face acute cost compression.
Supply Chain Analysis
The United States and Germany anchor hyperscale cloud infrastructure for government and banking deployments. Taiwan and South Korea feed semiconductor components for on-premises server installations. Japan sustains specialized air-gapped hardware production for defense and central bank requirements. Supply chain risk concentrates in single-source vulnerability for FedRAMP-authorized hosting capacity. Distribution runs through direct vendor relationships with procurement teams at large financial institutions and systems integrators serving government agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional services and managed services layers expand faster than software licensing, transforming hardware-light correspondence platforms into recurring-revenue service businesses. Vendors capturing compliance liability through outsourced platform operation command premium positioning.
For Market Incumbents: Fortify ISO 27001 certification moats through continuous audit investment to exclude emerging cloud-native competitors lacking validated security management systems. Deepen vertical integration into NLP engine development to preserve classification capability leadership against AI-native entrants. Lock in government agency relationships through FedRAMP-authorized Azure partnerships that raise switching costs.
For New Entrants and Emerging Players: RBI certification fast-tracks unlock tier-2 private banking networks in India before incumbent compliance modules saturate the market. White-space concentrates in outcome-based pricing models tied to audit pass rates, where established vendors lack flexible contract structures. Target mid-sized insurance carriers in the Netherlands and Belgium retrofitting for EU AI Act decision logging through lightweight explainability modules.
For Investors and Strategic Acquirers: Compliance-focused specialists with sector-specific retention expertise represent the highest-conviction acquisition archetype as regulatory divergence accelerates. Long-term viability centers on recurring revenue share exceeding seventy percent and embedded update guarantees that compound switching costs. Watch for enforcement date acceleration in Japan's METI guidelines as inflection indicator for platform replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-anchored architectures satisfy FedRAMP requirements for United States federal agencies. |
| Acquisition of Specialist Firm | NLP engine providers enable semantic classification capabilities for German banking institutions. |
| Strategic Partnership | Systems integrators bridge legacy document management with modern correspondence platforms. |
| Product Launch | Explainability modules address EU AI Act algorithmic decision documentation mandates. |
| Geographic Expansion | SaaS migration targets tier-2 institutions in Mumbai and Bangalore financial districts. |
Research Approach
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and integration specialists and refined through secondary validation. Primary fieldwork drew from correspondence management vendors, banking technology executives, government digital transformation leads, and compliance software specialists. Secondary sources encompassed SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and EU regulatory implementation guidance. Bottom-up deployment modeling and top-down market sizing triangulated volume and value estimates.
Variance decomposition across deployment mode, organization size, vertical, integration complexity, and regional adoption pattern structured the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included cloud migration velocity at German mid-tier banks, RBI compliance timeline adherence in India, and EU AI Act enforcement date probability distributions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated cloud infrastructure investment would require recalibration. Forecasts reflect assumptions around certification timeline compression and hybrid deployment persistence. Specific risk factors include cross-border data governance fragmentation and single-source cloud infrastructure concentration. Recalibration cycles align with material shifts in EU AI Act implementation guidance and METI electronic document authenticity enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Integration Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Australia ICT Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Poland ICT Market