
 System Integrator Market | 2026-2036
System Integrator Market Size, Share, and Industry Trends Forecast 2026-2036
System Integrator Market Outlook
Cloud-native middleware is pivoting away from legacy on-premises orchestration layers as enterprises prioritize elastic infrastructure economics. IBM sustains deep mainframe-to-cloud migration expertise that anchors its position in regulated verticals. Tata Consultancy Services dominates large-scale manufacturing integration programs across multiple continents. Accenture differentiates through industry-specific solution accelerators that compress deployment timelines for complex ERP overlays.
A system integrator designs, implements, and validates unified technology architectures that connect disparate hardware, software, and network components into coherent operational workflows, typically adhering to specifications such as ISA-95 for industrial automation interoperability. These entities serve the primary commercial purpose of reducing integration risk, accelerating time-to-value, and ensuring security compliance across heterogeneous technology estates. Implementation services command the largest revenue share within the service type dimension, reflecting the labor-intensive nature of custom configuration and testing. Cloud computing within the technology dimension exhibits the fastest expansion trajectory, driven by hybrid infrastructure mandates and edge-to-core data synchronization requirements. Custom software solutions capture disproportionate margin pools due to the sticky, recurring enhancement engagements they generate post-deployment.
The EU AI Act, NIS2 Directive, and ISO/IEC 27001 framework collectively elevate the compliance burden for automated system deployments, compelling end users to source integration partners with certified governance capabilities rather than generic IT contractors. In the United States, NIST cybersecurity standards and SEC disclosure rules for critical infrastructure operators similarly filter vendor eligibility toward audited system integrators. Stakeholders must monitor how fragmentation between regional certification regimes reshapes partner ecosystem strategies and cross-border service delivery models.
Market Dynamics
The convergence of operational technology and information technology architectures is forcing manufacturing enterprises to abandon siloed automation stacks in favor of unified control systems that span factory floors to enterprise clouds.
Growth Catalysts
- EU AI Act compliance mandates:Automated system deployments in European manufacturing now require certified governance capabilities, directing procurement budgets toward audited integration partners rather than generic IT contractors.
- Industrial IoT sensor proliferation:Shop-floor digitization projects in German automotive and machinery sectors generate sustained demand for complex ISA-95-compliant interoperability solutions.
- NIS2 Directive security requirements:Critical infrastructure operators across EU member states must demonstrate supply-chain resilience, elevating system integrators with documented cybersecurity frameworks above commodity vendors.
Market Restraints
- Certified engineer scarcity:The shallow talent pool for ISA-95 and IEC 62443 credentials constrains project scaling velocity across European industrial hubs.
- Legacy equipment lock-in:Brownfield manufacturing sites with decades-old programmable logic controllers resist seamless cloud-native middleware integration without costly hardware refresh cycles.
- Fragmented regional standards:Divergent certification regimes between the EU AI Act, US NIST frameworks, and Asian industrial protocols complicate cross-border service delivery models for multinational integrators.
Strategic Opportunities
- Edge-to-core data synchronization:Hybrid infrastructure mandates in process industries create white space for integrators bridging on-premises historians with cloud analytics platforms.
- ISO/IEC 27001 certification arbitrage:Enterprises facing SEC disclosure rules for critical infrastructure seek partners with pre-audited security postures, compressing vendor selection timelines.
- India manufacturing expansion:PLI scheme incentives for domestic electronics and automotive production attract system integrators capable of replicating German shop-floor architectures at scale.
Industry Challenges
- Multi-protocol integration complexity:Harmonizing OPC-UA, MQTT, and proprietary fieldbus standards within single operational architectures demands specialized engineering teams that command premium labor rates.
- Cybersecurity liability exposure:Integration partners assume increasing legal responsibility for breach incidents in connected operational environments, necessitating expanded insurance coverage and contractual safeguards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System Integrator Market |
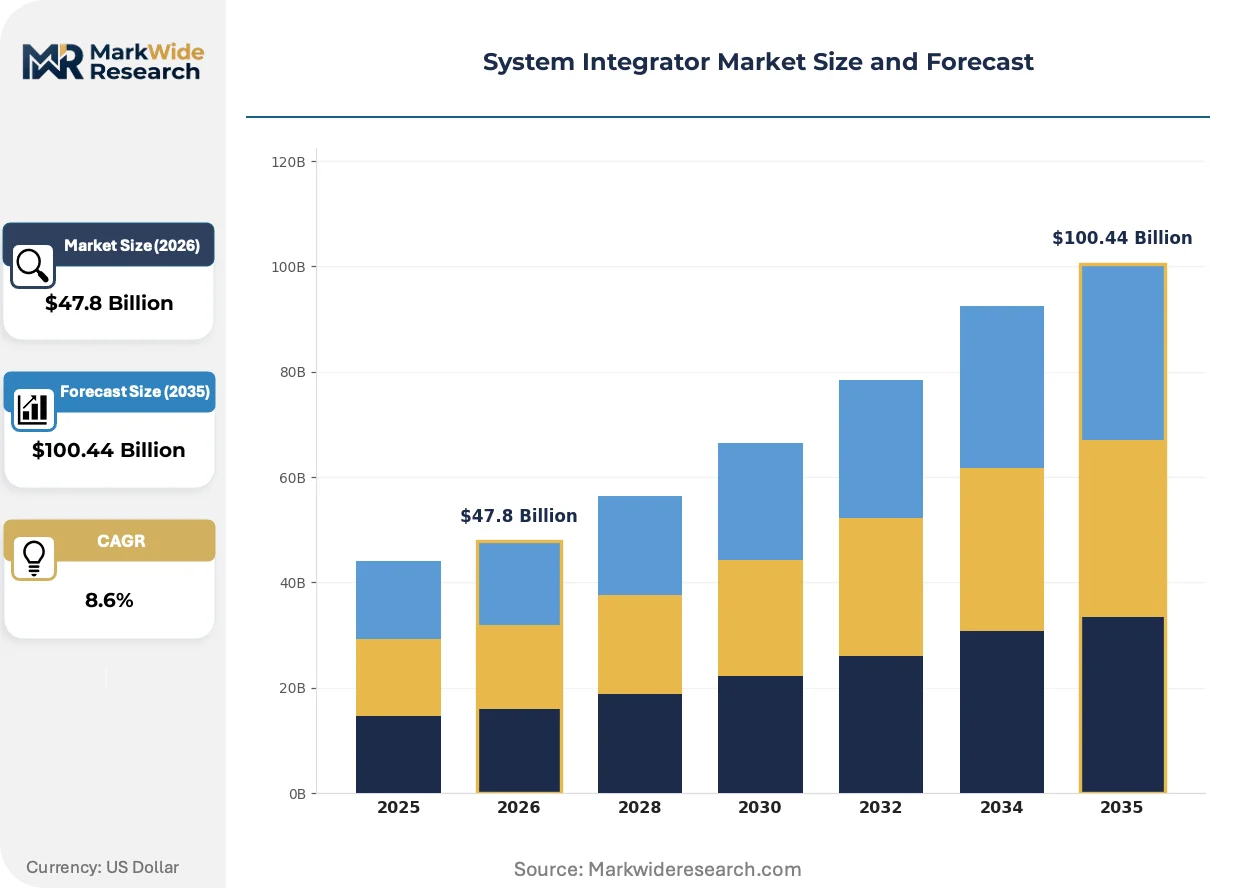
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Maintenance, Support End User: Manufacturing, Healthcare, Retail, Telecom Technology: IoT, Cloud Computing, AI, Automation Solution: Custom Software, Data Integration, Network Solutions, Security Systems |
| Companies Covered | Accenture, IBM, Tata Consultancy Services, Cognizant, Capgemini, John Wood Group PLC, ATS Corporation, JR Automation, Tesco Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System Integrator Market Strategic Shifts
Cloud-native middleware is absorbing functionality previously embedded in on-premises orchestration layers, compressing deployment timelines while expanding the addressable scope of integration projects.
Digital twin technology is absorbing physical asset modeling capabilities into software-defined environments, enabling pharmaceutical and energy sector buyers to simulate operational changes before capital deployment. Siemens and Rockwell Automation customers in North American process industries now mandate virtual commissioning deliverables as standard contract inclusions. This capability compression is absorbing traditional system acceptance testing phases into pre-implementation simulation cycles.
The EU AI Act's risk-based classification framework is restructuring vendor qualification protocols for automated decision systems deployed in European manufacturing. High-risk applications now require conformity assessments and post-market monitoring plans that only certified integration partners can architect. German automotive suppliers have responded by embedding AI governance checkpoints into every stage of their digitization roadmaps.
Buyer procurement patterns are consolidating vendor relationships around full-lifecycle accountability rather than discrete project engagements. Energy sector operators in Texas and Louisiana now contract system integrators for decade-long operational technology management, unbundling hardware supply from ongoing optimization services. This preference shift is most visible in US Gulf Coast petrochemical clusters where operational continuity premiums exceed initial capital expenditure considerations.
System Integrator Market Segmentation
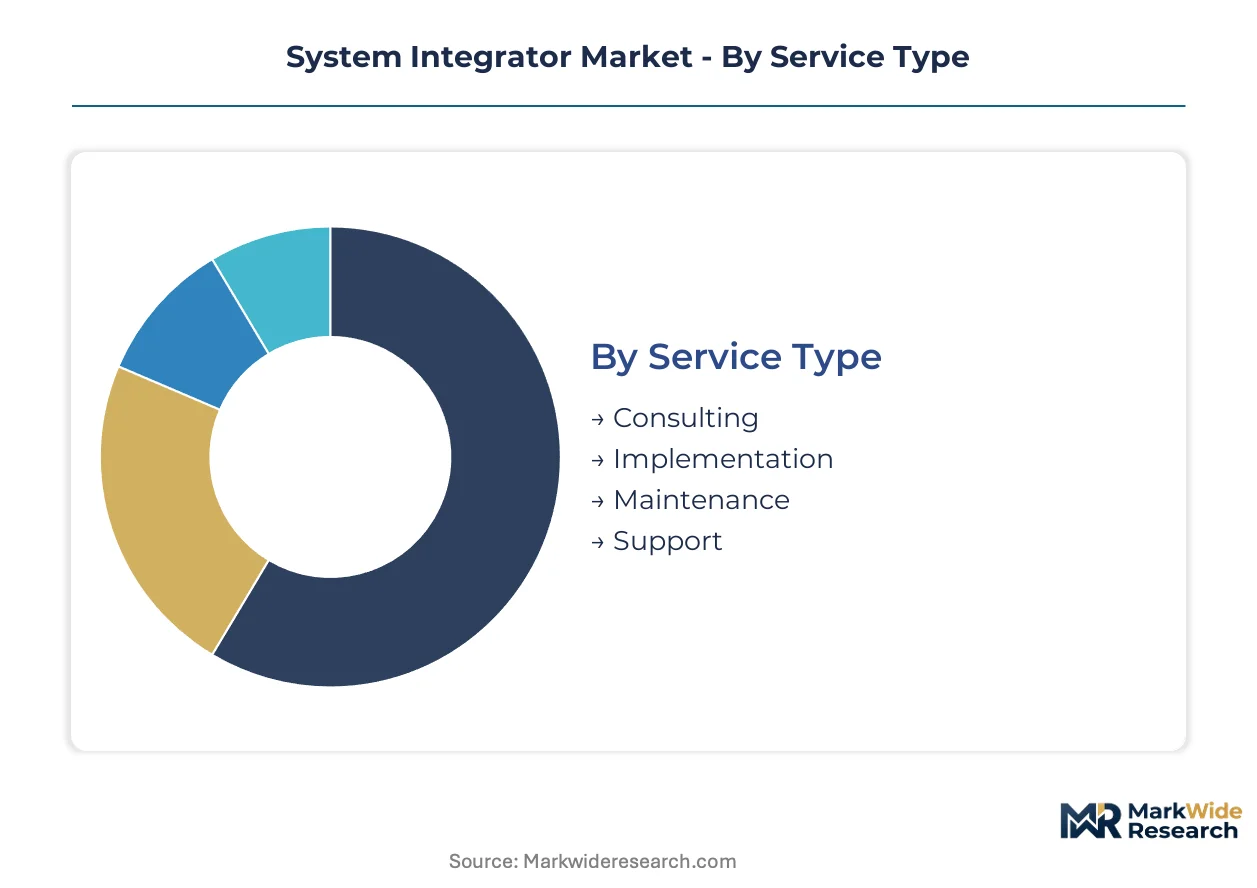
System integrators serve heterogeneous technology estates that demand tailored engagement models across service depth, industry vertical, and technology stack. Segmentation clarity enables procurement teams to match vendor capabilities against specific integration complexity and compliance requirements.
Service Type:
Standalone advisory engagements sit apart from embedded lifecycle contracts that span design through operational handover.
- Implementation:Custom configuration, testing, and validation of unified architectures consumes the largest labor allocation within integration programs. German automotive producers anchor sustained demand for ISA-95-compliant shop-floor deployments that compress operational technology and information technology convergence timelines.
- Consulting:Architecture design and governance framework development precedes capital commitment in regulated verticals. EU AI Act risk classification mandates are redirecting procurement budgets toward certified advisory partners capable of documenting conformity assessments for automated decision systems.
- Maintenance:Post-deployment optimization and patch management sustains recurring revenue relationships.
- Support:Tiered response capabilities address operational continuity requirements in critical infrastructure environments.
Implementation leads volumes today; consulting is gaining share fastest.
End User:
Cost tier stratification separates capital-intensive process industries from asset-light service sectors with differing integration risk tolerance.
- Manufacturing:Industrial IoT sensor proliferation and brownfield automation retrofits generate complex interoperability requirements. German machinery producers and Texas petrochemical operators anchor the highest-value integration contracts due to operational continuity premiums.
- Healthcare:Medical device connectivity and HIPAA-compliant data architectures demand specialized validation protocols. FDA-regulated environments restrict vendor eligibility to integrators with documented quality management systems.
- Retail:Omnichannel fulfillment and inventory synchronization drive middleware investments.
- Telecom:Network function virtualization and edge infrastructure deployment creates systems integration demand.
Manufacturing dominates contract value; healthcare is climbing the fastest.
Technology:
Application maturity separates proven infrastructure layers from emerging capability domains requiring specialized engineering talent.
- Cloud Computing:Hybrid infrastructure mandates and edge-to-core data synchronization requirements absorb functionality from legacy on-premises orchestration layers. Elastic economics expand project scope while compressing deployment timelines for enterprise resource planning overlays.
- IoT:Shop-floor sensor networks and industrial gateway deployment demand OPC-UA and MQTT protocol harmonization. NIS2 Directive supply-chain resilience requirements elevate integrators with certified cybersecurity frameworks above commodity vendors.
- AI:Automated decision system deployment requires governance checkpoint architecture under emerging regulatory frameworks.
- Automation:Robotic process automation and control system integration sustains baseline demand across manufacturing verticals.
Cloud Computing anchors revenue concentration; IoT is expanding most quickly.
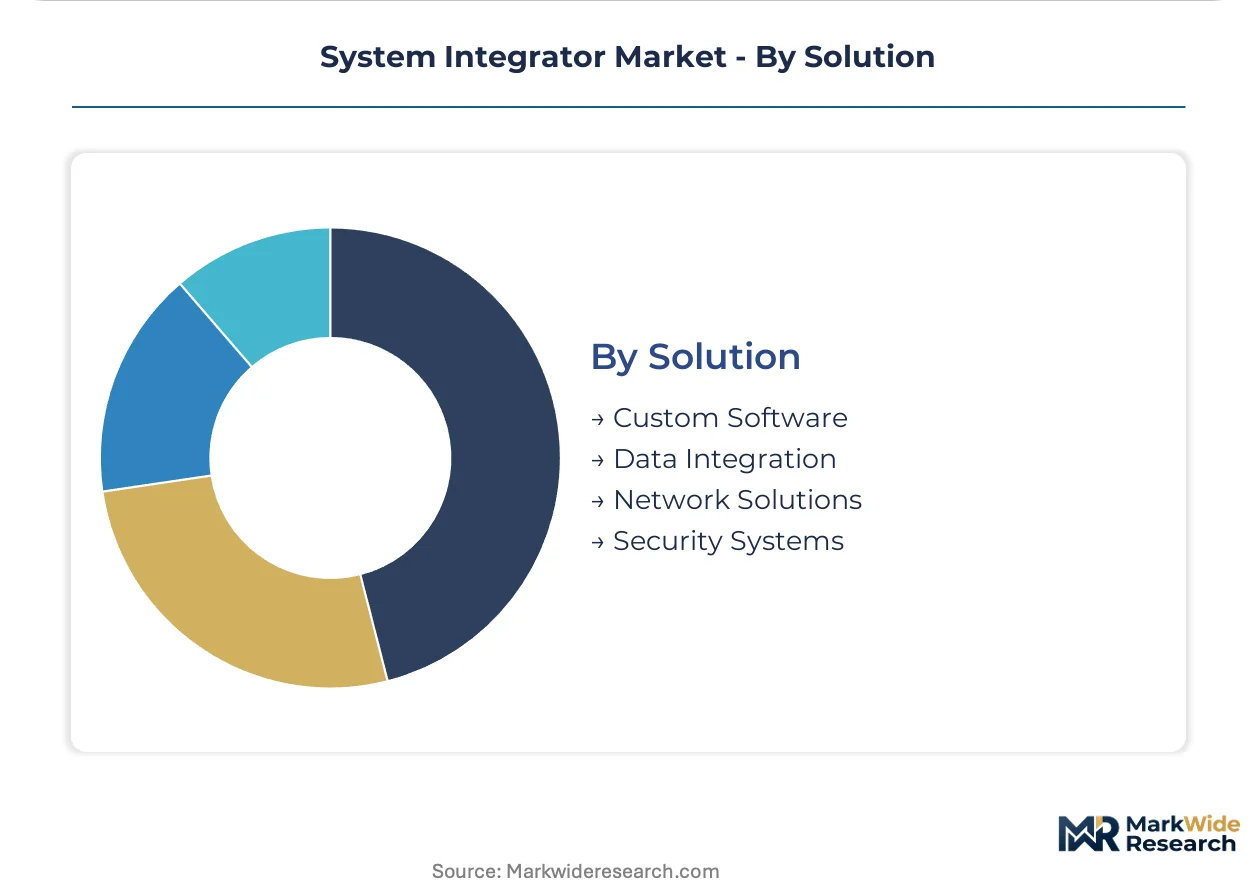
Solution:
Margin structure differentiates sticky recurring engagements from discrete project deliverables with limited post-deployment attachment.
- Custom Software:Bespoke application development generates enhancement-driven recurring revenue streams post-initial deployment. Proprietary code ownership creates switching costs that sustain long-term client relationships.
- Security Systems:IEC 62443-certified industrial cybersecurity architectures command premium pricing due to certified engineer scarcity and liability exposure in connected operational environments.
- Data Integration:Enterprise information consolidation and analytics pipeline construction addresses heterogeneous data source harmonization.
- Network Solutions:Converged operational technology and information technology infrastructure deployment supports unified control system objectives.
Custom Software captures the highest margin pools; Security Systems is seeing the steepest pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and machinery producers anchor complex shop-floor digitization projects that concentrate procurement budgets for ISA-95-compliant interoperability solutions.
United States
Texas and Louisiana petrochemical operators anchor decade-long operational technology management contracts that unbundle hardware supply from ongoing optimization services. NIST cybersecurity standards and SEC disclosure rules for critical infrastructure operators filter vendor eligibility toward audited system integrators. Gulf Coast clusters absorb premium pricing for operational continuity guarantees that exceed initial capital expenditure considerations.
Germany
Automotive suppliers and machinery producers generate sustained demand for complex brownfield automation retrofits requiring OPC-UA and MQTT protocol harmonization. EU AI Act risk-based classification mandates and NIS2 Directive security requirements redirect procurement toward certified integration partners with documented governance capabilities. Bavarian and Baden-Württemberg industrial corridors embed AI governance checkpoints into every stage of digitization roadmaps.
India
Electronics and automotive production expansion under PLI scheme incentives attracts system integrators capable of replicating German shop-floor architectures at domestic scale. Central Electricity Authority grid modernization mandates and BIS industrial automation standards elevate compliance requirements for foreign technology deployments. Maharashtra and Gujarat manufacturing clusters concentrate demand for hybrid infrastructure bridging on-premises historians with cloud analytics platforms.
China
Process industries in Yangtze River Delta and Pearl River Delta regions mandate edge-to-core data synchronization for smart factory certifications under MIIT industrial internet frameworks. GB standards for industrial control system security and dual carbon goals for energy-intensive sectors reshape vendor qualification protocols. Shandong Peninsula chemical operators prioritize virtual commissioning deliverables that compress traditional system acceptance testing phases.
Japan
Automotive and precision machinery producers in Chubu and Kansai regions sustain demand for robotic process automation integration with legacy equipment estates. METI Society 5.0 roadmaps and JIS standards for industrial cybersecurity create certified engineer requirements that constrain project scaling velocity. Toyota and Osaka industrial corridors favor full-lifecycle vendor relationships over discrete project engagements for operational continuity assurance.
System Integrator Market Competitive Environment
Global majors compete with regional champions across certification depth and industry-specific solution accelerators that compress deployment timelines for complex ERP overlays. The vendor base stratifies into three tiers: full-lifecycle account managers with decade-long contractual frameworks, discrete project specialists with premium labor rates for brownfield complexity, and cloud-native platforms absorbing middleware functionality from legacy orchestration layers. Consolidation pressure intensifies as buyer procurement patterns favor partners with pre-audited security postures over commodity contractors. Dominant competitive moves include geographic expansion into India manufacturing corridors and strategic partnerships bridging ISA-95 credentials with AI governance capabilities.
Within the full-lifecycle tier, Accenture exemplifies industry-specific solution acceleration through proprietary frameworks that reduce ERP overlay deployment risk. IBM occupies a position anchored in mainframe-to-cloud migration expertise that sustains relevance in regulated verticals with stringent audit requirements. Tata Consultancy Services represents the scale-driven archetype across multiple continents, capturing large-scale manufacturing integration programs that demand certified governance capabilities under divergent regional frameworks. These three entities collectively illustrate how certification arbitrage and vertical specialization reshape competitive positioning across heterogeneous technology estates.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| Tata Consultancy Services |
| Cognizant |
| Capgemini |
| John Wood Group PLC |
| ATS Corporation |
| JR Automation |
| Tesco Controls |
| Others |
Value Chain & Pricing Dynamics
ISA-95-certified engineers in Bavaria and Baden-Württemberg command labor-rate premiums that widen spreads between premium-tier certified integrators and economy-tier commodity contractors. This workforce concentration compresses margins for mid-tier players while amplifying pricing power for holders of IEC 62443 and ISO/IEC 27001 credentials.
Pricing Analysis
Input-cost pass-through from certified engineer scarcity drives project-based pricing with embedded risk premiums for complex brownfield deployments. Price differentiation separates full-lifecycle partners with audited governance frameworks from discrete project specialists competing on labor rates. Pricing pressure stems from cloud-native platforms absorbing middleware functionality previously delivered through custom integration. Small and mid-sized manufacturers exhibit highest price sensitivity, while German automotive and Texas petrochemical operators absorb premiums for operational continuity guarantees.
Supply Chain Analysis
Reverse-logistics flows for industrial gateway refurbishment and PLC remanufacturing create secondary supply channels that moderate raw material exposure. Component sourcing concentrates in Germany, China, and Japan for industrial automation hardware, with software talent pools distributed across India and Eastern Europe. Supply chain risk centers on single-source vulnerability for specialized fieldbus protocol chips subject to export control restrictions. Distribution runs through direct enterprise sales teams for large manufacturing accounts, supplemented by regional system integrator networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in system integration rests on certified engineer scarcity enabling premium-tier pricing, while cloud-native automation compresses delivery costs for standardized deployments.
For Market Incumbents: Hedge against cloud-native platform displacement by embedding AI governance capabilities into existing ISA-95 service portfolios. Acquire boutique cybersecurity specialists with IEC 62443 credentials to defend against emerging pure-play industrial security vendors. Prioritize decade-long operational technology management contracts in Gulf Coast petrochemical clusters where switching costs compound. For New Entrants and Emerging Players: Channel partners with existing manufacturing maintenance relationships offer the lowest-friction entry path for IoT gateway deployment services. Target India's PLI-subsidized electronics manufacturing corridors where German shop-floor architectures require domestic replication at scale. Lead with edge-to-core data synchronization offerings that bridge on-premises historians with cloud analytics platforms. For Investors and Strategic Acquirers: Cloud hyperscalers expanding industrial verticals represent the most active acquirer category in this space, seeking certified governance capabilities to satisfy EU AI Act requirements. Mid-sized integrators with documented ISO/IEC 27001 frameworks and automotive sector concentration offer viable acquisition profiles. Monitor NIS2 Directive enforcement timelines as inflection indicators for cybersecurity service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Arbitrage Investment | EU AI Act compliance mandates redirect procurement toward pre-audited partners with documented governance frameworks. |
| Geographic Expansion into India | PLI scheme incentives for domestic electronics production attract integrators capable of replicating German architectures. |
| Strategic Partnership with Hyperscalers | Cloud-native middleware absorption creates white space for integrators bridging edge infrastructure with enterprise clouds. |
| Acquisition of Cybersecurity Specialist | IEC 62443-certified capabilities command premium pricing due to engineer scarcity and liability exposure. |
| Full-Lifecycle Contract Conversion | Texas petrochemical operators now unbundle hardware supply from decade-long operational technology management engagements. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand-side calibration. Interviews with plant engineers, OEM procurement teams, integration specialists, and aftermarket service heads combined with secondary validation from SEC filings, customs trade data, and industrial automation association reports. Bottom-up project pipeline analysis triangulates against top-down sector expenditure estimates.
Rate-of-change decomposition separates volume effects from pricing and mix shifts across the projection horizon. Segmentation dimensions modeled include service type depth, end-user vertical, technology stack maturity, and solution margin structure. CAGRs derive from regression against industrial capital expenditure cycles and regulatory compliance deadline clustering. Specific forecast inputs incorporate brownfield automation retrofit backlogs and certified engineer supply constraints.
Revisions become necessary when EU AI Act enforcement intensity, NIS2 Directive supply-chain audit scope, or cloud-native platform functionality absorption materially diverge from baseline assumptions. Practitioners should monitor German automotive supplier governance checkpoint implementation rates and India PLI scheme capacity commissioning timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
US Transcription Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Green IT Services Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Bahrain ICT Market