
 DIY Smart Home Market | 2026-2036
DIY Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
DIY Smart Home Market Intelligence
A transition from single-vendor ecosystems to multi-source device procurement is repositioning the competitive landscape for DIY smart home solutions. Amazon leverages its Alexa platform to create a central hub for disparate devices. Google competes directly with its Assistant and Nest product family, pursuing a similar strategy. In contrast, SimpliSafe specializes in user-installable security systems, targeting a specific consumer need for home protection.
DIY smart home systems comprise consumer-installable devices that allow for remote control and automation of household functions via a central application. These products typically connect using standard wireless protocols like Wi-Fi or Zigbee, communicating with a user's smartphone or a voice assistant. Smart lighting and security cameras represent high-volume entry points for new users. The energy management use case is primarily driven by smart thermostats, a segment with higher initial investment but clear long-term value.
Data privacy regulations, including Europe's GDPR, impose stringent requirements on how consumer data is collected and managed by device manufacturers. In parallel, product certification bodies like the US Federal Communications Commission (FCC) and Europe's CE marking process govern radio emissions and electrical safety. Navigating the fragmented ecosystem of competing connectivity standards like Thread and Z-Wave remains the central challenge for both vendors and consumers.
Market Dynamics
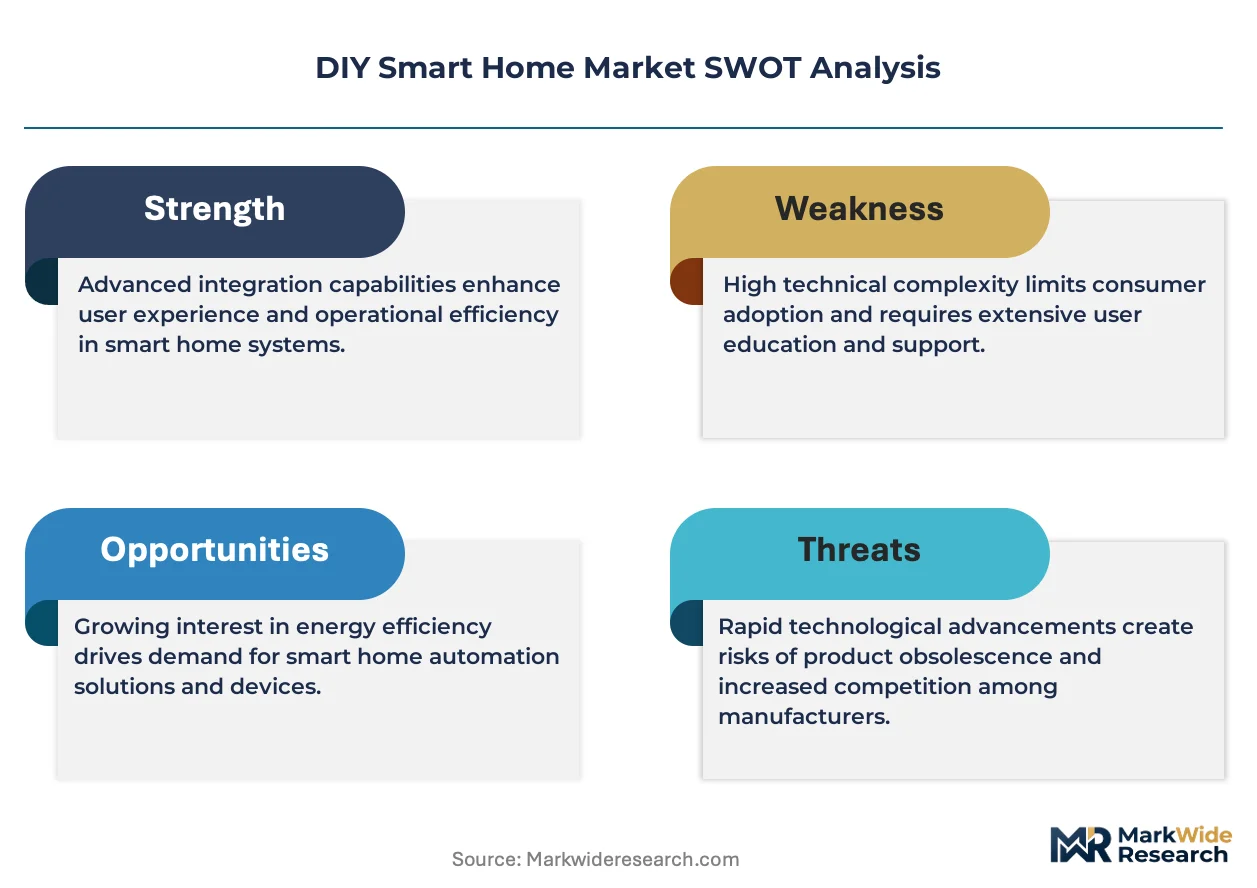
The central force shaping the market is the consumer-led push for interoperability, which is dismantling closed, single-vendor ecosystems. This shift favors open standards like Thread, compelling manufacturers to compete on device-level innovation rather than on platform lock-in.
Growth Catalysts
- Connectivity Simplification:The proliferation of the Thread protocol reduces setup complexity and improves device-to-device communication reliability, lowering the barrier to entry for non-technical consumers and encouraging multi-device purchases.
- Energy Cost Management:Heightened focus on energy efficiency, particularly in markets like Germany, drives adoption of smart thermostats and lighting. Consumers are motivated by the clear return on investment from reduced utility bills.
- Governmental Incentives:Rebate programs and tax credits for energy-efficient home upgrades, often including smart thermostats, provide a direct financial incentive for homeowners to invest in energy management solutions.
Market Restraints
- Interoperability Fragmentation:Despite progress with new standards, the coexistence of multiple protocols like Z-Wave, Zigbee, and proprietary Wi-Fi implementations creates confusion for consumers and development hurdles for manufacturers.
- Data Privacy Scrutiny:Regulations like Europe's GDPR impose strict rules on data collection and processing. Consumer apprehension over how personal data is used by smart devices can slow adoption, especially for cameras and microphones.
- High Initial Investment:The upfront cost for a comprehensive system, particularly including high-value items like smart thermostats or advanced security systems, remains a significant barrier for budget-conscious households.
Strategic Opportunities
- Predictive Automation with AI:Integrating on-device artificial intelligence allows systems to learn user behaviors and automate routines without explicit commands, moving from reactive control to proactive home management.
- Expansion into Wellness Monitoring:There is a growing opportunity for devices that monitor air quality, water leaks, or even provide non-intrusive ambient assisted living support for elderly residents, expanding beyond core security and lighting.
- Targeting New Construction:Collaborating with homebuilders to pre-install a foundational smart home package in new properties creates a sticky customer base and establishes a platform for future device sales.
Industry Challenges
- Navigating Certification Pathways:Manufacturers face complex and varied compliance requirements, including FCC radio-frequency testing in the United States and CE marking for safety and emissions in Europe, which can delay product launches.
- Ensuring Backward Compatibility:As technology evolves, maintaining support and interoperability for older-generation devices on new platforms presents a significant software development and customer support challenge for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY Smart Home Market |
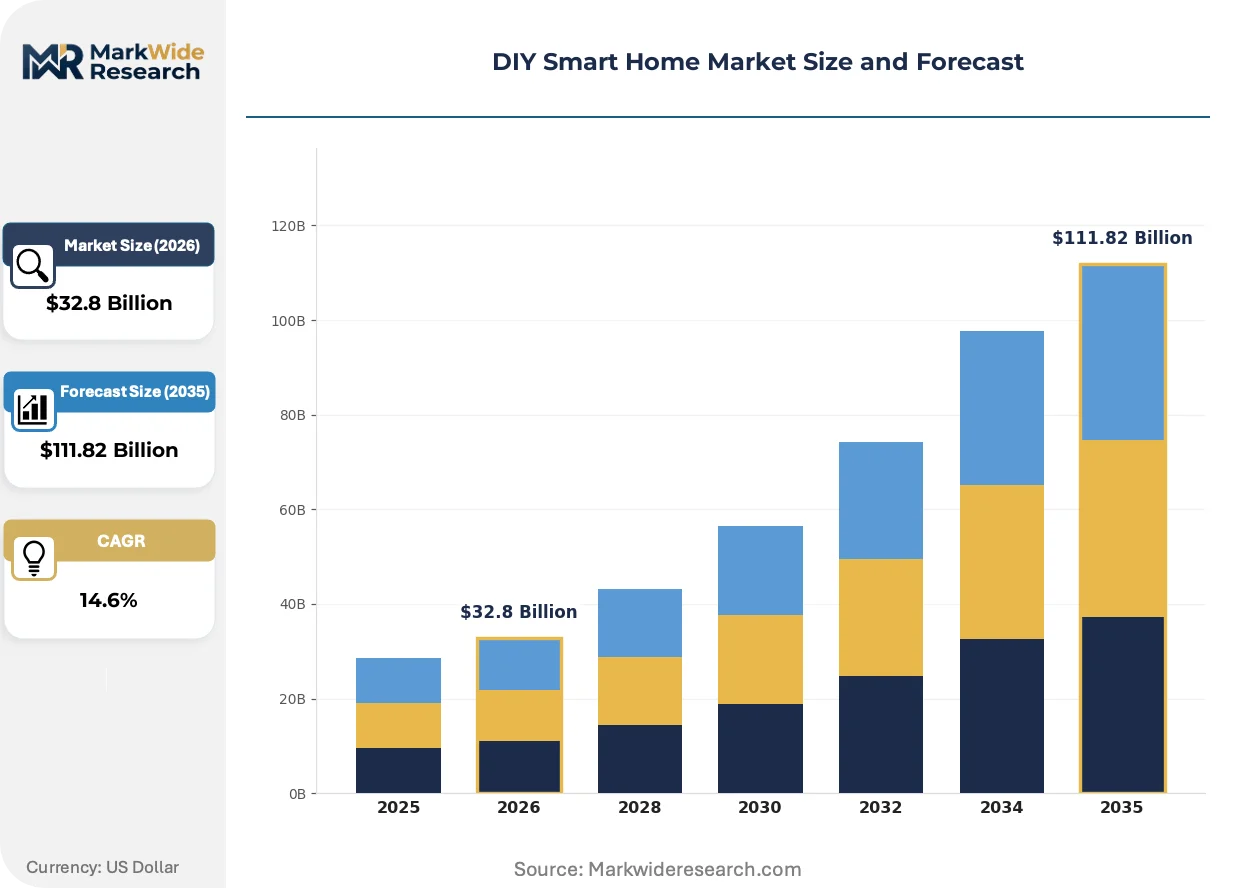
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $111.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Security Cameras, Thermostats, Voice Assistants, Smart Locks Connectivity: Wi-Fi, Zigbee, Z-Wave, Bluetooth, Thread Use Case: Home Automation, Energy Management, Security Surveillance, Entertainment Control, Environmental Monitoring Customer Type: Homeowners, Renters, Property Managers, DIY Enthusiasts, Remote Workers |
| Companies Covered | SwitchBot, Plume Design, Amazon, Sense, Brilliant, Google, Aqara, SimpliSafe, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY Smart Home Market Strategic Shifts & Innovations
A fundamental transition from remote device control to proactive home automation is underway. This evolution is driven by more powerful on-device processing and a market-wide push for open, interoperable ecosystems that empower consumer choice.
On-device AI, or edge computing, embeds processing capabilities directly into smart home products. Homeowners in the security camera and smart display segments are adopting these devices for faster response times and improved data privacy. This trend of local processing is converging with open standards like Matter, enabling the creation of more autonomous, secure, and responsive home environments that are less dependent on cloud connectivity.
Europe's General Data Protection Regulation (GDPR) establishes a stringent global benchmark for consumer data privacy. Its principles are forcing manufacturers to re-architect data flows, emphasizing data minimization and transparent user consent. The smart speaker and video doorbell segments are most affected, needing to innovate features that function effectively while respecting strict privacy boundaries to maintain access to the European market.
A notable behavioral shift shows consumers prioritizing individual device performance over brand loyalty, assembling systems from multiple vendors. This disrupts the traditional walled-garden strategy, putting pressure on platforms to embrace openness and third-party integration. This procurement pattern is most pronounced in North America, where technologically savvy users actively research and select best-in-class products for lighting, security, and climate control independently.
DIY Smart Home Market Segmentation
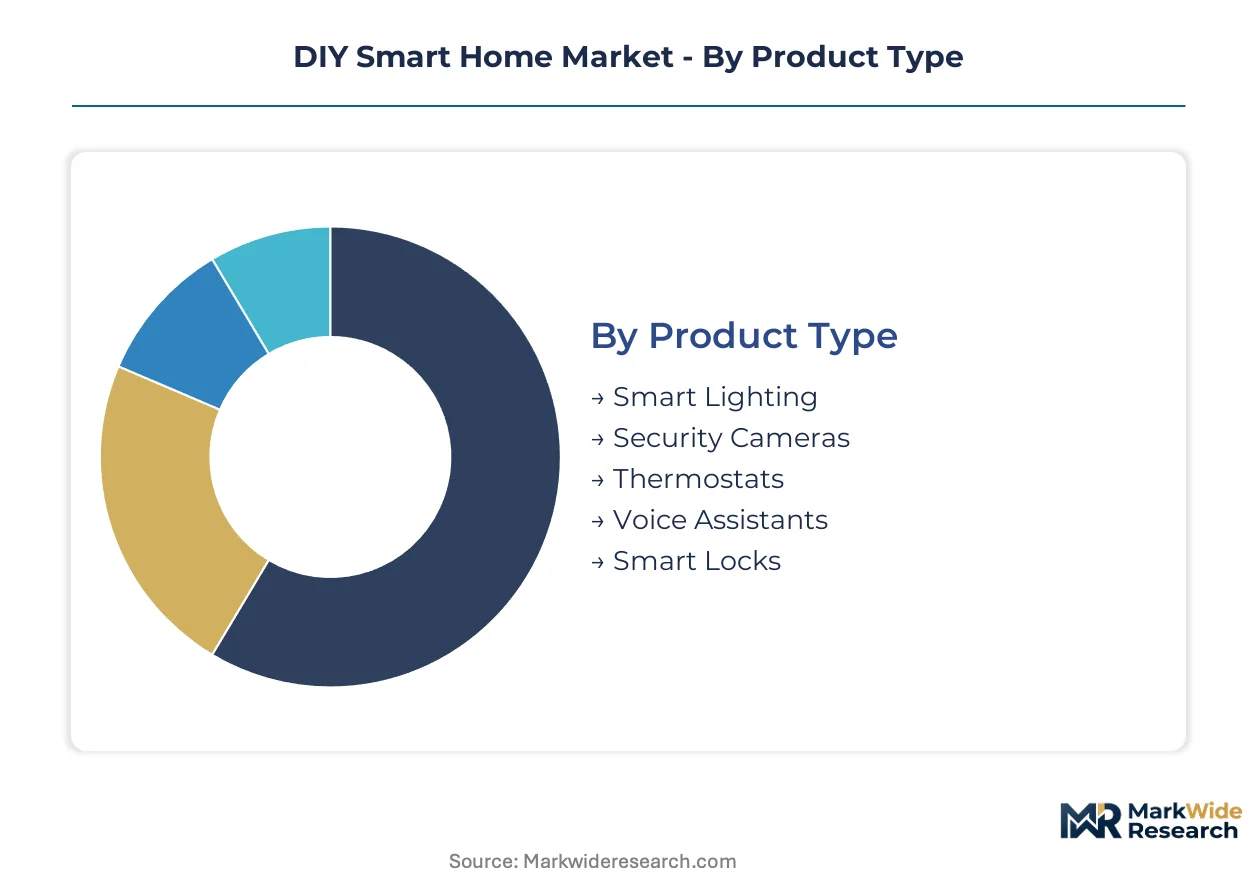
The DIY Smart Home market segmentation reveals varied entry points and value propositions for consumers. Understanding these distinct segments assists manufacturers in tailoring product development and market outreach. This analysis details the different product types, connectivity standards, use cases, and customer profiles driving market expansion.
Product Type:
Analyzing product types by their capital intensity clarifies consumer investment patterns and manufacturer focus on premium or entry-level solutions.
- Smart Lighting:These systems integrate LED bulbs, switches, and hubs, allowing for remote control, scheduling, and color changes via smartphone applications. Demand concentrates in markets like Germany, where energy efficiency goals motivate consumers to reduce utility bills through optimized lighting.
- Security Cameras:These devices offer real-time video monitoring, motion detection, and two-way audio, often with local or cloud storage options. North American homeowners prioritize these systems for property protection, driven by a desire for enhanced safety and remote surveillance capabilities.
- Thermostats:Programmable devices manage home heating and cooling, learning user preferences and optimizing energy consumption.
- Voice Assistants:Smart speakers and displays respond to voice commands, acting as central hubs for controlling other smart home devices and accessing information.
- Smart Locks:Keyless entry systems provide remote access control, temporary guest codes, and integration with broader security platforms for enhanced home access management.
Smart Lighting absorbs the bulk of installed capacity; Security Cameras is expanding most quickly.
Connectivity:
The application focus within connectivity standards highlights how different protocols serve specific performance and interoperability needs for DIY smart home devices.
- Wi-Fi:This ubiquitous wireless protocol leverages existing home network infrastructure for direct device-to-cloud communication, enabling easy setup for many smart home products. Its broad adoption underpins general home use, allowing for straightforward integration of individual devices.
- Thread:This low-power mesh networking protocol facilitates direct, secure, and reliable device-to-device communication without a central hub, improving interoperability across different manufacturers. Its design supports multi-vendor systems, simplifying setup and enhancing the user experience for complex smart home ecosystems.
- Zigbee:A mesh network protocol designed for low-power, short-range communication, often requiring a hub for internet connectivity.
- Z-Wave:A wireless communication protocol optimized for smart home devices, known for its reliability and low power consumption, typically operating on a mesh network.
- Bluetooth:This short-range wireless technology connects devices directly, often used for initial setup or local control of individual smart home gadgets.
Demand for Wi-Fi underpins broad market access, while Thread drives innovation.
Use Case:
Examining use cases through the lens of customer types clarifies how diverse consumer needs shape demand for specific smart home functionalities.
- Home Automation:This segment involves setting up routines and rules for devices to operate autonomously, such as lights turning on at sunset or blinds closing automatically. DIY Enthusiasts often drive demand for these complex, integrated systems, seeking seamless and convenient living environments.
- Energy Management:Solutions in this area focus on optimizing energy consumption through smart thermostats, smart plugs, and energy monitoring devices, aiming to reduce utility costs. Homeowners in regions like Germany prioritize these solutions, motivated by clear financial returns from reduced energy bills.
- Security Surveillance:This use case encompasses security cameras, motion sensors, and door/window sensors for monitoring and protecting property.
- Entertainment Control:Devices like smart speakers, smart TVs, and universal remotes integrate to manage media playback and content distribution throughout the home.
- Environmental Monitoring:This segment includes sensors for air quality, temperature, humidity, and water leaks, providing alerts and maintaining comfortable living conditions.
Home Automation represents a foundational offering, with Energy Management showing significant growth potential.
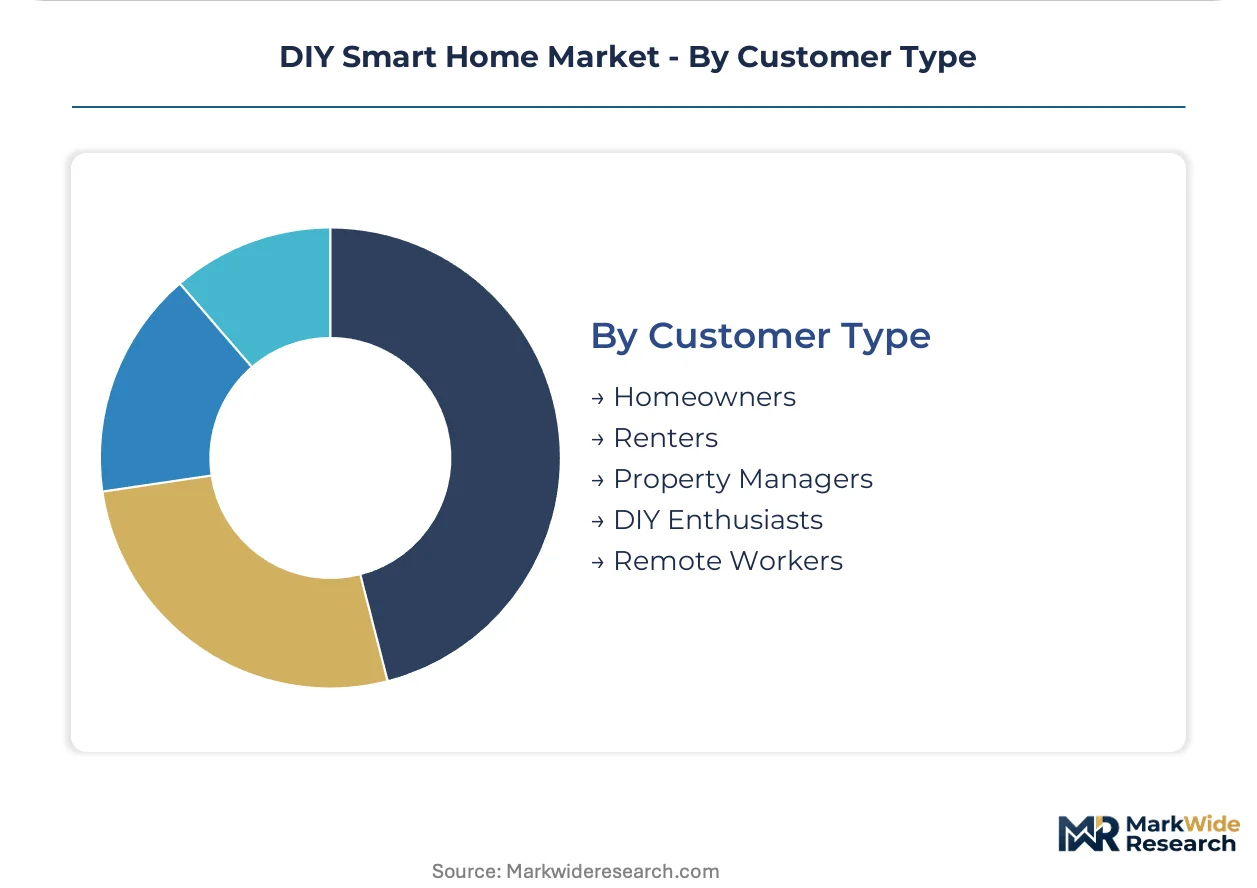
Customer Type:
Analyzing customer types by their volume contribution reveals the primary market constituents and emerging consumer groups influencing product design.
- Homeowners:This segment represents the largest volume of DIY smart home adopters, investing in long-term solutions for property value enhancement, security, and energy efficiency. Homeowners in North America often integrate comprehensive systems, seeking both convenience and robust home protection.
- DIY Enthusiasts:These consumers possess technical aptitude and a strong interest in customizing and integrating various smart home devices from multiple vendors. This group drives demand for open standards and advanced automation features, influencing the development of interoperable solutions.
- Renters:This group seeks portable and easy-to-install smart home devices that do not require permanent modifications to their living spaces.
- Property Managers:These professionals implement smart home solutions for multiple units, focusing on remote management, energy savings, and tenant amenities.
- Remote Workers:This segment adopts smart home devices that enhance productivity, comfort, and security within their home office environments.
The market primarily caters to Homeowners, but DIY Enthusiasts is increasingly influencing product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a prominent center for technology innovation, anchors the DIY smart home market's regional dynamics. This market exhibits varied adoption patterns driven by energy concerns, technological readiness, and specific regulatory frameworks across different geographies. Consumer demand for convenience and cost savings shapes local market development.
United States
Homeowners in the United States prioritize security surveillance and home automation for property protection and convenience. The FCC governs radio emissions and electrical safety for smart home devices, ensuring product compliance. Silicon Valley, California, remains a hub for smart home technology development, fostering AI-driven automation.
Germany
Demand for energy management solutions, particularly smart thermostats and lighting, drives market growth in Germany. The EU Green Deal and CE marking influence product design and market entry for manufacturers. Munich and Berlin are centers for smart home startups, focusing on energy efficiency and data privacy.
China
Consumer interest in smart lighting and voice assistants fuels market expansion in China, reflecting a preference for integrated ecosystems. China's GB standards ensure product quality and safety, impacting local and international manufacturers. Shenzhen, a major manufacturing hub, produces a vast array of smart home devices for global distribution.
United Kingdom
Security cameras and smart lighting are key entry points for DIY smart home adoption among UK consumers seeking practical solutions. The GDPR imposes stringent data privacy regulations on device manufacturers operating in the region. London's tech ecosystem supports companies developing user-friendly smart home interfaces and platforms.
Japan
Advanced automation and wellness monitoring solutions attract Japanese consumers, particularly for ambient assisted living support. Japan's METI oversees industrial product standards, ensuring quality and interoperability in the smart home sector. Tokyo's innovation clusters explore predictive AI for seamless home management and elderly care.
DIY Smart Home Market Key Industry Players
Ecosystem expansion dominates the current competitive landscape, driven by consumer demand for interoperability and multi-source device procurement. The market exhibits a tiered structure, with established technology giants competing with specialized solution providers and component manufacturers. Strategic partnerships, technology diversification, and platform integration represent dominant competitive moves among market participants. This shift actively dismantles traditional single-vendor ecosystems.
Within the platform provider archetype, Amazon, with its Alexa ecosystem, and Google, through its Assistant and Nest products, anchor comprehensive smart home solutions. These technology companies represent a strategy centered on creating central hubs for disparate devices and fostering broad third-party integration. SimpliSafe, in contrast, exemplifies a specialized security-focused approach, targeting specific consumer needs for user-installable home protection systems. These players occupy distinct positions within the evolving market, catering to different consumer priorities and technical aptitudes.
| Leading Market Players |
|---|
| SwitchBot |
| Plume Design |
| Amazon |
| Sense |
| Brilliant |
| Aqara |
| SimpliSafe |
| Apple |
| Others |
Cost & Logistics Intelligence
Semiconductor chip prices, a key input for smart home devices, often cascade through the supply chain, influencing the final pricing tiers for consumer-facing products. This directly impacts both entry-level and premium device costs.
Pricing Analysis
Warranty and service bundling significantly differentiate smart home product offerings across various price points. The market employs a hybrid pricing model, combining per-unit transactional device sales with optional subscription services for cloud storage or advanced features. Brand premium and after-sales support drive price differentiation among manufacturers. Pricing pressure stems from the highly competitive landscape, with renters demonstrating the highest price sensitivity, while homeowners show greater willingness to invest.
Supply Chain Analysis
Reverse logistics, including device returns and refurbishment flows, represents a growing operational challenge for smart home manufacturers. Geographic supply concentration centers heavily in China for manufacturing and Taiwan for advanced semiconductor components, relying on specialized sensors and plastic compounds. Geopolitical tensions impacting component availability pose a structural supply chain risk. Distribution runs through online retail platforms and specialized consumer electronics stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Persistent semiconductor chip shortages continue to constrain device availability, propping up pricing across several smart home product categories. This supply-constrained environment necessitates strategic adjustments from market participants.
For Market Incumbents:Acquire specialized AI software firms to deepen on-device processing capabilities and enhance predictive automation features. This defensive move counters the threat of platform lock-in erosion from open standards like Matter. Incumbents should also invest heavily in R&D for advanced sensor technologies to maintain a competitive edge. Building stronger direct-to-consumer channels can enhance control over customer experience.
For New Entrants and Emerging Players:Capture niche opportunities in wellness monitoring solutions, such as air quality sensors or non-intrusive ambient assisted living devices. The renter segment, seeking portable and easy-to-install devices, remains a highly penetrable market for focused offerings. New entrants should leverage direct-to-consumer online sales with flexible subscription bundles to gain market share. Collaboration with new construction developers also offers a strategic entry point.
For Investors and Strategic Acquirers:Distressed-cycle entries favor mid-cap specialized solution providers in Europe, particularly those with strong data privacy compliance frameworks. Long-term viability, over a five-to-ten-year window, remains strong for integrated platform providers and specialized hardware innovators. Acquisition targets should possess robust intellectual property in AI algorithms or unique sensor technologies. Practitioners should monitor the adoption rates of unified connectivity standards like Matter as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Open Standards | Enables broader device compatibility, attracting more users to a unified smart home ecosystem. |
| Investment in Edge AI Processing | Improves device responsiveness and enhances data privacy by minimizing cloud dependency. |
| Expansion into Wellness Monitoring Devices | Addresses evolving consumer needs beyond security, creating new revenue streams for manufacturers. |
| Strategic Partnerships with Homebuilders | Establishes early market presence in new properties, securing a foundational customer base. |
| Enhancing Data Privacy Compliance | Builds consumer trust and ensures market access in regions with stringent regulations like Europe. |
Research Approach
Independent corroboration across industry association reports, government energy statistics, and technology news archives underwrites the qualitative findings. This study combined extensive primary interviews with smart home device manufacturers, platform developers, electronics retailers, and utility providers. Secondary research validated insights through patent databases and academic literature. A bottom-up and top-down triangulation approach ensured robust market sizing and forecast accuracy.
Historical reference periods anchored the comparable-period framing, establishing a robust baseline for future projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, connectivity standard, use case, customer type, and regional regulatory environments. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Key industry-specific forecast inputs included consumer spending on home electronics and energy efficiency policy changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical trade policies and rapid technological obsolescence. Forecasts reflect assumptions regarding market growth and adoption rates. Practitioners should monitor major shifts in regulatory frameworks and consumer privacy concerns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Electrical Calibration Equipment Market
Others
Augmented Reality in Energy and Utilities Market
Others
North America Thermoformed Plastics Market
Others
Czech Republic Market
Others
Global Hydraulics Market
Others
Digital Audio Decoders Market
Others
Pickup Truck Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Global OTA Testing Market
Others
Air Purification Systems Market
Others
Spain Smart Home Market
Others
North America Astrology Market
Others
Nutricosmetics Market
Others
Digital Education Projector Market
Others
North America Medical Simulation Market
Others
Exosome Technologies Market