
 Global Hydraulics Market | 2026-2036
Global Hydraulics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulics Market Outlook
Electro-hydraulic integration is reshaping how fluid power systems interface with digital controls and predictive maintenance platforms. Bosch Rexroth AG leverages its automation heritage to anchor smart actuator development in European manufacturing corridors. Parker Hannifin Corporation sustains broad geographic coverage through distributed service networks and component standardization. Danfoss A/S specializes in compact power-dense solutions for electrified mobile machinery.
Hydraulics denotes fluid power systems transmitting force through pressurized oil or water-glycol mixtures, typically operating at pressures from 3,000 to 6,000 psi in industrial applications and up to 10,000 psi in specialized mobile equipment. These systems convert mechanical energy to fluid pressure and back to mechanical work, enabling precise force control in heavy-load environments. Hydraulic pumps and valves capture concentrated margin pools due to precision machining requirements and replacement part cyclicality. Mobile equipment applications outpace stationary counterparts as mining and construction OEMs prioritize payload efficiency and telematics integration. Smart hydraulics represents the fastest-expanding technology segment, though hydrostatic drives retain dominance in agricultural traction systems.
EPA emissions standards and the EU F-Gas Regulation compel OEMs to redesign hydraulic circuits for reduced fluid volumes and lower leakage rates. ISO fluid cleanliness codes and REACH chemical restrictions shape material selection for seals and hose assemblies across export-bound supply chains. China's MIIT efficiency mandates and India's BIS certification requirements add compliance layers for multinational component suppliers. Stakeholders must weigh electrification timelines against hydraulic system upgrade cycles when allocating R&D budgets across product portfolios.
Market Dynamics
Electro-hydraulic integration is compressing traditional component replacement cycles as construction and mining OEMs demand predictive maintenance compatibility. The shift from standalone hydraulic circuits to sensor-embedded intelligent systems redefines supplier qualification criteria and aftermarket revenue models.
Growth Catalysts
- EPA emissions standards:Tier 4 Final and Stage V regulations in the United States and Europe compel OEMs to redesign hydraulic architectures for reduced fluid volumes and lower parasitic losses.
- Telematics integration:Mining operators in Australia and Chile now specify CAN-bus-enabled hydraulic actuators for real-time payload optimization and remote diagnostics.
- India's BIS certification requirements:Mandatory efficiency testing for imported hydraulic components accelerates localization investments by multinational suppliers serving infrastructure projects.
Market Restraints
- Specialized steel alloying inputs:Precision-machined valve bodies require vacuum-degassed bearing steel grades concentrated among Japanese and German metallurgical suppliers.
- Seal material concentration:Fluorocarbon and hydrogenated nitrile formulations for high-pressure applications depend on limited European and North American chemical producers.
- Electrification substitution:Battery-electric construction equipment prototypes in Germany and South Korea eliminate hydraulic powertrains entirely in favor of direct electric drive.
Strategic Opportunities
- Water-glycol fluid systems:Fire-resistant hydraulic fluids open penetration in underground mining operations across Indonesia and South Africa where thermal safety mandates apply.
- Remanufactured component channels:Circular economy incentives under the EU Green Deal subsidize certified rebuilt pumps and motors for cost-sensitive agricultural machinery fleets.
- 5G-enabled remote diagnostics:Chinese and Brazilian construction contractors now prioritize hydraulic systems with edge-computing capabilities for fleet-wide condition monitoring.
Industry Challenges
- Mechatronics engineering scarcity:Integration of hydraulic, electronic, and software disciplines exceeds available talent pools in Midwestern US manufacturing corridors and Central European industrial regions.
- ISO fluid cleanliness certification:Achieving ISO 4406 18/16/13 codes for smart hydraulic components extends validation timelines by eight to fourteen months for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulics Market |
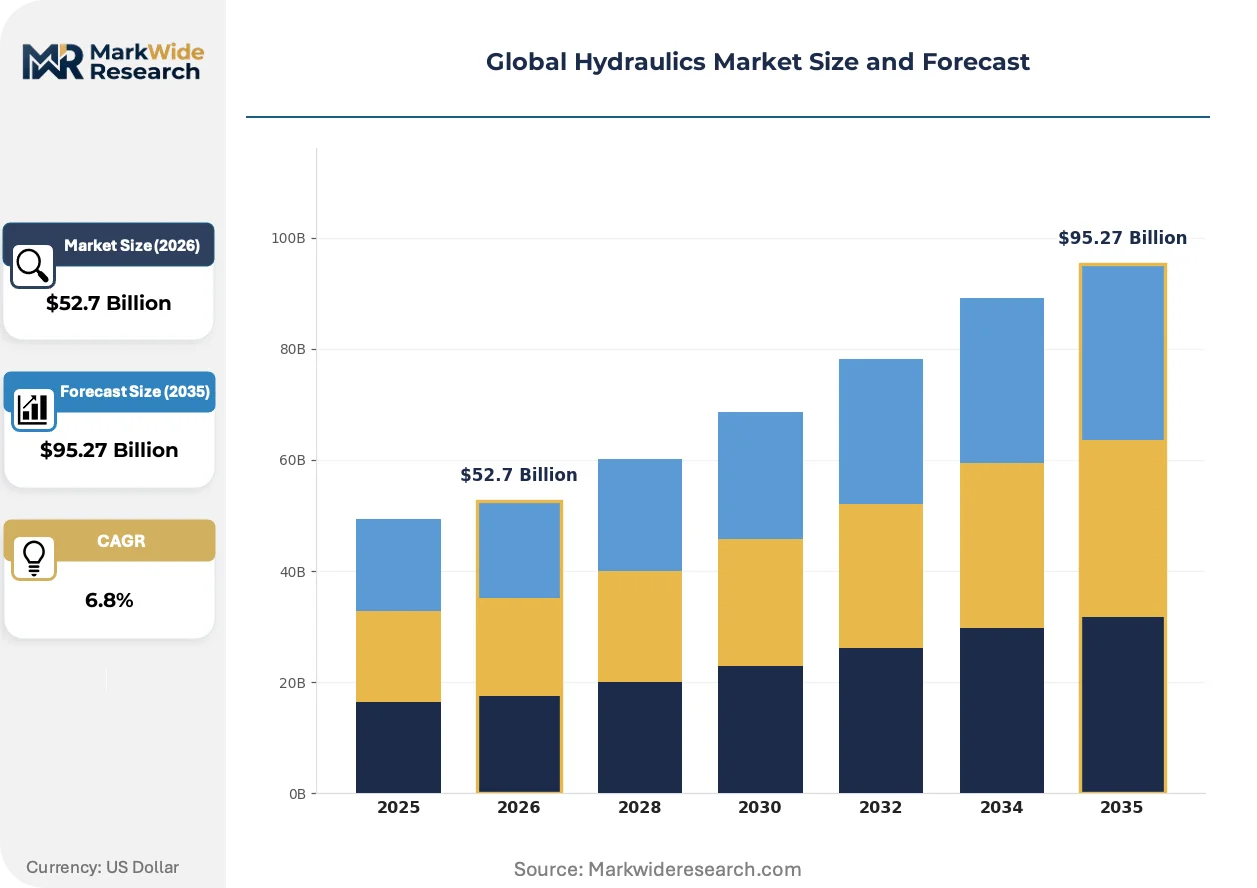
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Cylinders, Hydraulic Pumps, Hydraulic Motors, Hydraulic Valves End User: Aerospace, Manufacturing, Construction, Agriculture Application: Machine Tools, Material Handling, Stationary Equipment, Mobile Equipment Technology: Electro-Hydraulic, Hydrostatic, Hydraulic Actuators, Smart Hydraulics |
| Companies Covered | Eaton Corporation, Kawasaki Heavy Industries, Parker Hannifin Corporation, Gates Corporation, Manuli Hydraulics, Bosch Rexroth AG, KYB Corporation, Alfagomma Group, Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulics Market Strategic Shifts
Digital twin technology is virtualizing how hydraulic system performance gets specified, commissioned, and maintained across heavy equipment fleets. This convergence of physics-based modeling with operational data streams redefines supplier-customer technical relationships.
Digital hydraulic valve technology replaces discrete on/off solenoids with independently controllable poppet arrays, enabling software-defined flow characteristics without mechanical redesign. Agricultural machinery OEMs in Denmark and the Netherlands pilot these systems for sub-millisecond implement response. The technology is virtualizing traditional hardware-based pressure and flow control, compressing prototyping cycles from months to weeks.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon-based working fluids, forcing reformulation of synthetic hydraulic oils with lower global warming potential. Seal compatibility testing under REACH chemical restrictions now extends to bio-based ester and polyalkylene glycol alternatives. Mobile equipment manufacturers serving European export markets accelerate qualification of water-glycol and vegetable oil formulations for construction and forestry applications.
Aftermarket service unbundling disrupts traditional distributor relationships as fleet operators purchase hydraulic components directly from manufacturers while sourcing installation and maintenance through independent technicians. Brazilian mining contractors and Indonesian palm oil plantation operators increasingly separate procurement of smart actuators from fluid analysis and resealing services. This fragmentation pressures incumbent distribution networks to specialize in technical consulting rather than inventory holding.
Global Hydraulics Market Segmentation
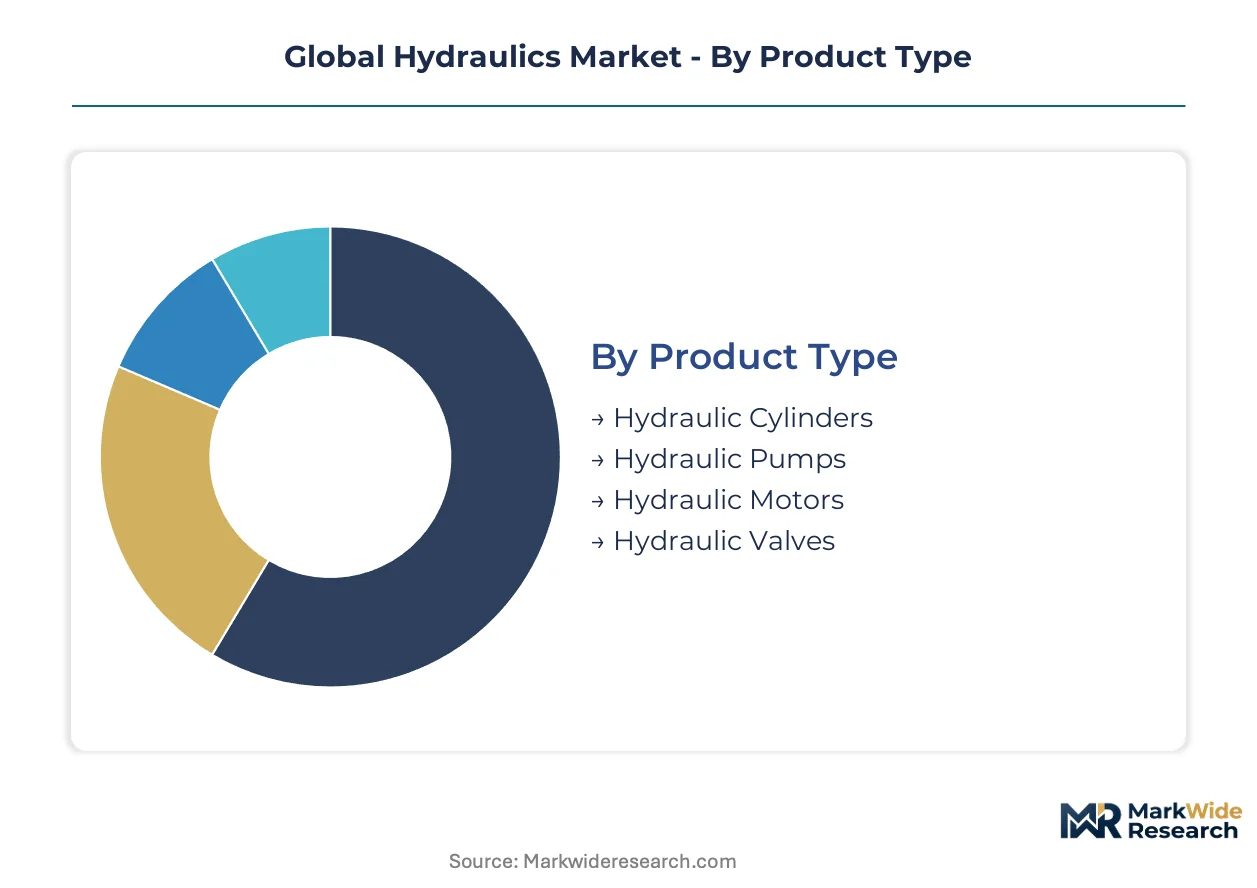
Hydraulics manufacturers configure product portfolios around replacement cycle velocity and application intensity. Segment boundaries blur as electro-hydraulic convergence reshapes traditional component hierarchies and service revenue models.
Product Type:
Hydraulic pumps and motors turn over fastest in mining fleets, while cylinders and valves extend service intervals through rebuild programs.
- Hydraulic Pumps:Positive displacement units converting mechanical energy to fluid pressure, with gear, vane, and piston architectures serving distinct load profiles. Australian and Chilean mining operators specify CAN-bus-enabled pump packages for real-time flow optimization and predictive seal replacement scheduling.
- Hydraulic Valves:Precision-machined flow control devices operating at pressures up to 10,000 psi in specialized mobile equipment. German and Japanese OEMs now mandate digital hydraulic valve compatibility for construction equipment platforms targeting EPA Tier 4 Final compliance.
- Hydraulic Cylinders:Linear actuators dominating heavy-lift applications with resealable designs supporting multiple overhaul cycles.
- Hydraulic Motors:Rotary output devices concentrated in agricultural traction and conveyor drive systems.
Hydraulic pumps anchor the volume base while smart valve configurations gain share at the steepest rate.
End User:
Cost tiers separate specification-intensive aerospace applications from price-sensitive agricultural machinery procurement patterns.
- Construction:Earthmoving and lifting equipment consuming the largest fluid power volumes globally. Chinese and Indian infrastructure contractors prioritize hydraulic system telematics integration for fleet utilization tracking across dispersed job sites.
- Manufacturing:Presses, injection molding, and metal forming equipment requiring ISO 4406 cleanliness codes for precision positioning repeatability.
- Agriculture:Tractor and implement hydraulics facing margin pressure from remanufactured component channels subsidized under EU Green Deal circular economy incentives.
- Aerospace:Flight control and landing gear actuation systems demanding fire-resistant fluid compatibility and traceable metallurgical certification.
Construction absorbs the highest absolute component volumes while manufacturing applications command the steepest technology premiums.
Application:
Mobile equipment applications outpace stationary counterparts in sensor integration intensity and connectivity specification rates.
- Mobile Equipment:Construction, mining, and forestry machinery operating in variable ambient conditions with high shock loading. Brazilian and Indonesian contractors now separate smart actuator procurement from fluid analysis services, fragmenting traditional distribution relationships.
- Material Handling:Forklifts, cranes, and conveyor systems balancing duty cycles against energy recovery requirements.
- Machine Tools:Precision manufacturing equipment where thermal stability and positioning accuracy determine hydraulic circuit design.
- Stationary Equipment:Industrial presses and power units with longer depreciation horizons and slower technology refresh rates.
Mobile equipment dominates replacement part demand while material handling systems adopt electrification fastest.
Technology:
Supply concentration in mechatronics engineering talent pools constrains expansion timelines for integrated electro-hydraulic platforms.
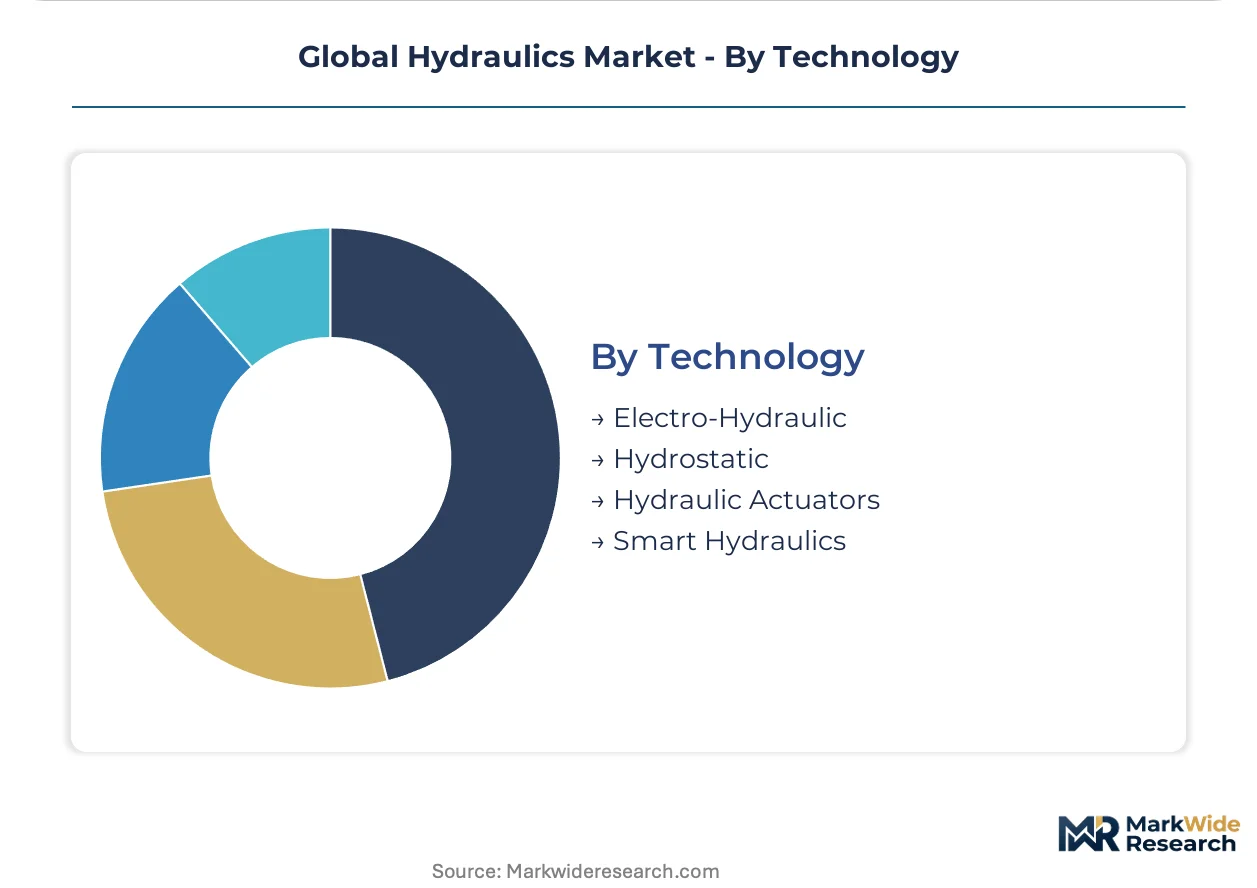
- Smart Hydraulics:Sensor-embedded systems with edge-computing capabilities enabling condition-based maintenance and remote diagnostics. Chinese and Brazilian construction contractors specify these packages for fleet-wide monitoring across 5G-enabled job sites.
- Electro-Hydraulic:Solenoid-actuated valves and proportional control systems interfacing with digital machine controllers. German and Japanese OEMs expand orders for these architectures as Stage V emissions regulations tighten fluid efficiency requirements.
- Hydrostatic:Closed-loop transmission systems retaining dominance in agricultural traction applications.
- Hydraulic Actuators:Cylinder and motor combinations serving discrete motion control functions in legacy equipment platforms.
Smart hydraulics climbs the fastest while hydrostatic drives retain installed base dominance in agricultural corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and mining operators in China, Germany, and the United States drive the largest absolute component volumes. OEM procurement patterns concentrate in industrial corridors where emissions regulations and infrastructure investment cycles intersect.
United States
EPA Tier 4 Final standards compel construction equipment OEMs to redesign hydraulic architectures for reduced parasitic losses. Mining operators in Arizona and Nevada now specify CAN-bus-enabled actuators for real-time payload optimization. The Permian Basin oilfield services sector sustains demand for high-pressure fracturing pumps and valve packages.
Germany
Stage V emissions regulations accelerate electro-hydraulic integration in earthmoving equipment platforms. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon-based working fluids, forcing seal compatibility testing for bio-based alternatives. Industrial clusters in Baden-Württemberg and Bavaria anchor precision valve machining and smart actuator development.
China
MIIT efficiency mandates add compliance layers for multinational component suppliers serving infrastructure projects. State-owned construction contractors in the Yangtze River Delta prioritize telematics-integrated hydraulic systems for fleet utilization tracking. Domestic pump and motor manufacturers in Shandong Province expand capacity for electrified mobile machinery.
Japan
METI industrial efficiency programs drive replacement of legacy hydraulic circuits in automotive press lines. Vacuum-degassed bearing steel grades from Japanese metallurgical suppliers concentrate precision-machined valve body production. Construction equipment OEMs in Tokyo and Osaka expand orders for sensor-embedded intelligent systems.
Brazil
BIS certification requirements for imported hydraulic components accelerate localization investments by multinational suppliers. Mining contractors in Minas Gerais separate smart actuator procurement from fluid analysis services, fragmenting traditional distribution relationships. Agricultural machinery fleets in São Paulo state access remanufactured pumps subsidized under circular economy incentives.
Global Hydraulics Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented distribution networks. The vendor base organizes into three tiers: diversified fluid power conglomerates with automation heritage, regional hose and fitting specialists, and precision-machining component suppliers. Consolidation pressure concentrates among mid-scale valve and cylinder fabricators facing electrification substitution. Dominant competitive moves include backward integration into seal material supply and geographic expansion through certified remanufacturing partnerships.
Among diversified fluid power conglomerates, Eaton Corporation and Parker Hannifin Corporation exemplify channel-controlling archetypes with distributed service networks. Bosch Rexroth AG anchors the automation-integrated tier, representing the convergence of hydraulic heritage with digital control platforms. Danfoss A/S occupies a position within the compact power-dense specialization segment for electrified mobile machinery.
| Leading Market Players |
|---|
| Eaton Corporation |
| Kawasaki Heavy Industries |
| Parker Hannifin Corporation |
| Gates Corporation |
| Manuli Hydraulics |
| Bosch Rexroth AG |
| KYB Corporation |
| Alfagomma Group |
| Danfoss A/S |
| Others |
Value Chain & Pricing Dynamics
Japanese and German metallurgical suppliers concentrate vacuum-degassed bearing steel grades for precision-machined valve bodies, anchoring margin pools in pump and motor replacement cycles where OEMs extract value through captive aftermarket channels.
Pricing Analysis
Cost-plus contracts with steel indexation dominate long-term supply agreements between component fabricators and bearing steel mills. Pricing stratifies across premium, standard, and economy tiers based on ISO cleanliness certification levels and telematics integration depth. Cost compression in standard-grade cylinders is intensifying because Brazilian and Indonesian contractors now separate smart actuator procurement from fluid analysis services. Agricultural machinery fleets exhibit the highest price sensitivity due to remanufactured pump subsidies under EU Green Deal circular economy incentives.
Supply Chain Analysis
Specialized steel alloying inputs draw from Japanese and German metallurgical suppliers, while fluorocarbon seal formulations rest on limited European and North American chemical producers. Raw material dependencies span vacuum-degassed bearing steel, hydrogenated nitrile elastomers, and high-purity base oils for synthetic formulations. Single-source vulnerability concentrates in precision valve machining capabilities clustered in Baden-Württemberg and Bavaria. Distribution runs through OEM captive service networks and independent remanufacturing channels serving cost-sensitive agricultural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as mining capital expenditure rebounds across Australian and Chilean operations, releasing pent-up demand for CAN-bus-enabled hydraulic packages.
For Market Incumbents: Pre-empt electrification substitution by accelerating backward integration into seal material supply and expanding certified remanufacturing partnerships in São Paulo state. Anchor defensive positioning through captive control of smart actuator firmware architectures before battery-electric construction equipment prototypes from German and South Korean OEMs reach commercial scale. For New Entrants and Emerging Players: Establish a beachhead in water-glycol fluid system retrofits for Indonesian and South African underground mining operations where thermal safety mandates create compliance-driven replacement cycles. Target independent fluid analysis and resealing services as Brazilian and Indonesian contractors fragment traditional distribution relationships, unbundling procurement from maintenance. For Investors and Strategic Acquirers: Capital is best deployed toward precision-machining component suppliers with ISO 4406 certification capabilities and established relationships with Australian mining operators. Long-term viability over the next decade hinges on exposure to predictive maintenance integration rather than commodity hydraulic replacement. Watch electrification timelines at German and Japanese construction equipment OEMs as the critical inflection signal for hydraulic system upgrade cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Materials | Captive supply of fluorocarbon formulations reduces dependency on European chemical producers. |
| Certified Remanufacturing Partnership | EU Green Deal subsidies for rebuilt pumps unlock cost-sensitive agricultural machinery fleets in São Paulo. |
| Digital Hydraulic Valve Development | Software-defined flow characteristics compress prototyping cycles for Danish and Dutch agricultural OEMs. |
| 5G-Enabled Remote Diagnostics Platform | Edge-computing capabilities align with Chinese and Brazilian contractor fleet monitoring priorities. |
| Water-Glycol Fluid System Qualification | Fire-resistant formulations penetrate Indonesian and South African underground mining safety mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hydraulic OEM procurement teams, aftermarket service directors, mining fleet maintenance managers, and precision machining plant engineers; and secondary validation through customs trade records, SEC 10-K filings from listed fluid power conglomerates, ISO certification databases, and EU F-Gas Regulation implementation reports. Bottom-up component demand modeling triangulated against top-down equipment production forecasts from construction and mining machinery databases.
Forecast inputs span product type segmentation across pumps, valves, cylinders and motors; end-use intensity across construction, manufacturing, agriculture and aerospace; technology tier differentiation between smart hydraulics, electro-hydraulic and hydrostatic architectures; and geographic regulatory clusters including EPA Tier 4 Final, EU Stage V, and China's MIIT efficiency mandates. CAGRs were derived from replacement cycle velocity analysis and electrification substitution elasticity modeling across mobile equipment applications.
Sensitivities concentrate around electrification adoption curves at German and Japanese construction OEMs, steel alloy price volatility from Japanese and German metallurgical suppliers, and REACH chemical restriction expansions affecting seal material formulations. Cross-checking against equipment production data from construction and mining machinery manufacturers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitator Bead Mill Market
Others
Textile Composites Market
Others
IoT Testing Market
Others
Global Retail Media Networks Market
Others
Hookah Tobacco Market
Others
Global Drug Discovery Informatics Market
Others
North America Medical Simulation Market
Others
Mobile Computing Devices Market
Others
APAC Smart Home Market
Others
Fiber to the X (Fttx) Tester Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Automatic Barriers and Bollards Market
Others
Storage Dewar and Dry Shipper Market
Others
Traditional PC Market
Others
Global Mica Market
Others
Spain Automotive LED Lighting Market