
 Smart Home and Office Market | 2026-2036
Smart Home and Office Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home and Office Market Outlook
Shortages of embedded systems engineers and IoT security specialists is unwinding delivery timelines for integrated building platforms. Amazon.com, Inc. leverages its Alexa ecosystem to dominate voice-first home automation, while Google LLC anchors its position through Nest hardware tied to cloud analytics. Samsung Electronics Co., Ltd. competes by extending its SmartThings protocol across white-goods and display categories.
Smart home and office systems encompass networked sensors, actuators, and controllers that communicate over protocols such as Zigbee 3.0 operating at 2.4 GHz with mesh-range extensions up to 100 meters per hop, enabling centralized management of lighting, climate, access, and audiovisual environments in residential and commercial buildings. Smart Security System deployments lead value capture among product types due to recurring monitoring subscriptions and insurance-mandated upgrades. Energy Management applications within corporate offices sustain the fastest expansion trajectory as ESG reporting requirements tighten operational efficiency targets.
FCC Part 15 rules in the United States govern unlicensed radio emissions for Wi-Fi and Bluetooth devices, while the EU AI Act classifies certain biometric-enabled security systems as high-risk, mandating conformity assessments before CE marking. BIS certification in India blocks market entry for uncertified smart lighting and thermostat imports. Stakeholders must monitor divergence between regional cybersecurity mandates to avoid fragmented product architectures that inflate compliance costs.
Market Dynamics
EU AI Act high-risk classification for biometric security systems is forcing manufacturers to redesign certification pathways before CE marking, compressing product development cycles and elevating compliance costs across integrated building platforms.
Growth Catalysts
- ESG Reporting Mandates:Corporate sustainability disclosure requirements in Germany and France are accelerating thermostat and lighting retrofits in commercial buildings. Facility managers face binding efficiency targets.
- Zigbee 3.0 Mesh Protocol:Standardized 2.4 GHz connectivity with 100-meter hop extensions is reducing interoperability friction between sensor networks and central controllers. Installers favor unified infrastructure.
- Insurance-Mandated Security Upgrades:Property underwriters in the United Kingdom and Netherlands now require certified smart monitoring systems for commercial coverage renewals. Recurring subscription revenues follow deployment.
Market Restraints
- Embedded Systems Engineer Scarcity:Talent shortages in firmware development and IoT security architecture are extending delivery timelines for integrated building platforms by 4-8 months.
- Fragmented Cybersecurity Mandates:Divergence between FCC Part 15 emissions rules, EU GDPR data localization, and BIS certification requirements in India forces redundant product architectures.
- Silicon Supply Concentration:Advanced microcontroller fabrication concentrates in Taiwan and South Korea, exposing thermostat and sensor manufacturers to geopolitical supply interruptions.
Strategic Opportunities
- Commercial Building Retrofit Programs:Germany's federal building efficiency incentives cover 30-50% of smart HVAC upgrade costs for structures over 25 years old. Municipal procurement channels remain underdeveloped.
- Matter Protocol Convergence:Unified application-layer standard bridging Wi-Fi, Thread, and Zigbee is eliminating hub fragmentation. Early adopters gain cross-platform compatibility advantages.
- Edge AI Processing:On-device inference for occupancy detection and anomaly recognition reduces cloud dependency and latency. Semiconductor vendors are releasing sub-watt neural accelerators for sensor nodes.
Industry Challenges
- GDPR Compliance Architecture:Biometric data retention limits and purpose-specification requirements demand redesigned data pipelines for facial-recognition access systems. Legal review cycles add 6-12 weeks.
- Legacy Building Integration:BACnet and Modbus protocols in 1990s-era commercial HVAC infrastructure resist seamless API bridging. Custom middleware development inflates project costs.
- Conformity Assessment Bottlenecks:EU AI Act high-risk system notifications face 12-18 month backlogs at notified bodies. Product launches stall awaiting CE marking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home and Office Market |
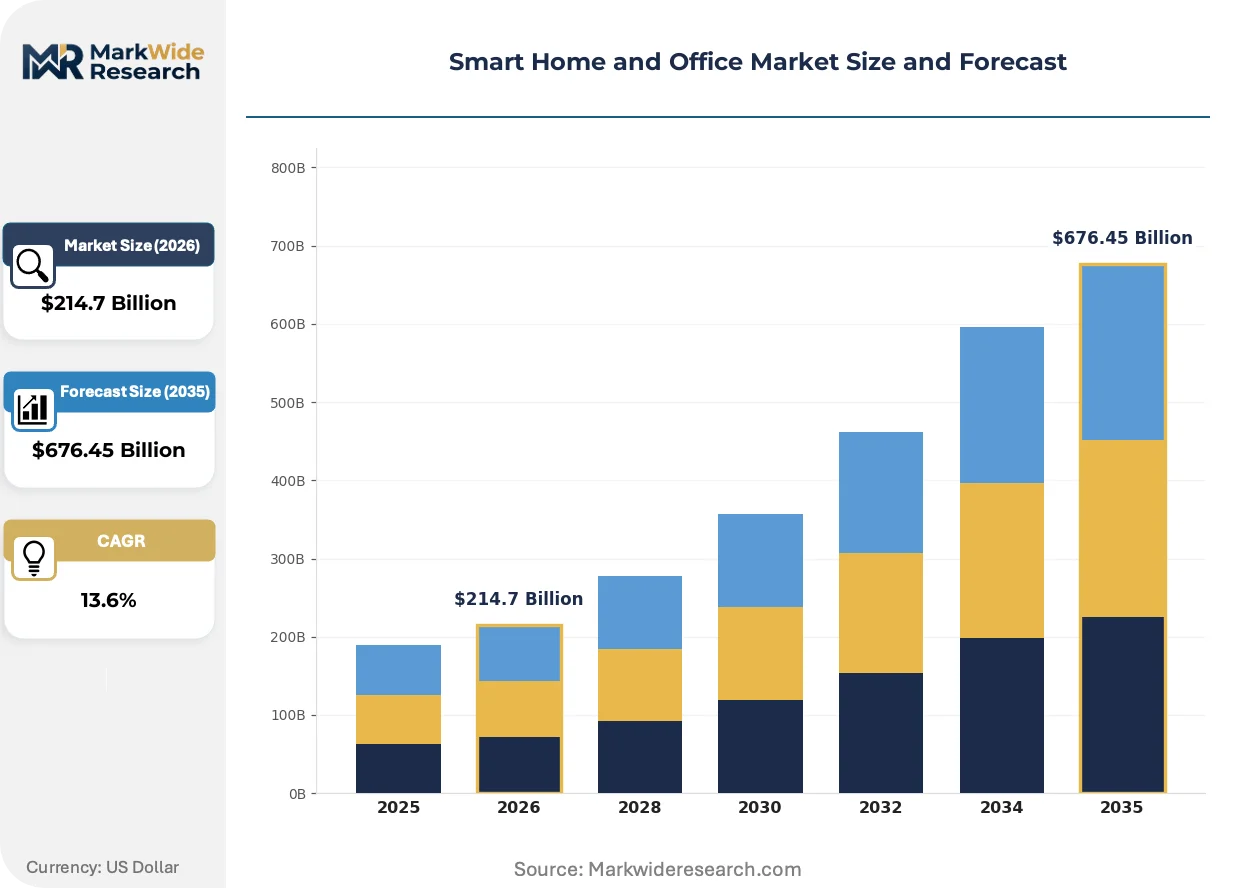
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $676.45 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostat, Smart Security System, Smart Speaker End User: Residential Consumers, Small Businesses, Corporate Offices, Property Managers Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Home Automation, Energy Management, Security Monitoring, Environmental Control |
| Companies Covered | Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Schneider Electric SE, Honeywell International Inc., Johnson Controls International plc, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home and Office Market Strategic Shifts
Matter protocol unification, edge AI deployment, and regulatory-driven data governance are compressing technology cycles and reshaping competitive differentiation in connected building systems.
Thread mesh networking with IPv6-native architecture is displacing proprietary Zigbee implementations in premium residential installations. Multi-brand ecosystems from thermostat, lock, and lighting vendors now interoperate without manufacturer-specific hubs. This convergence is collapsing the middleware layer that previously captured 15-20% of system value.
EU AI Act biometric surveillance restrictions are reclassifying facial-recognition access systems as high-risk AI. Manufacturers must submit technical documentation, risk management systems, and post-market monitoring plans to notified bodies before CE marking. German commercial security integrators are pivoting toward fingerprint and mobile-credential alternatives to avoid conformity assessment delays.
Facility managers in corporate offices are consolidating vendor relationships around platform-agnostic service contracts. Single-source accountability for HVAC, lighting, and access control is displacing point-solution procurement through electrical contractors. This concentration is most visible in Netherlands and Belgium, where integrated facilities management contracts now specify outcome-based energy efficiency guarantees rather than equipment specifications.
Smart Home and Office Market Segmentation
Smart home and office procurement decisions fragment across technical specifications, regulatory compliance tiers, and operational scale requirements. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape vendor prioritization.
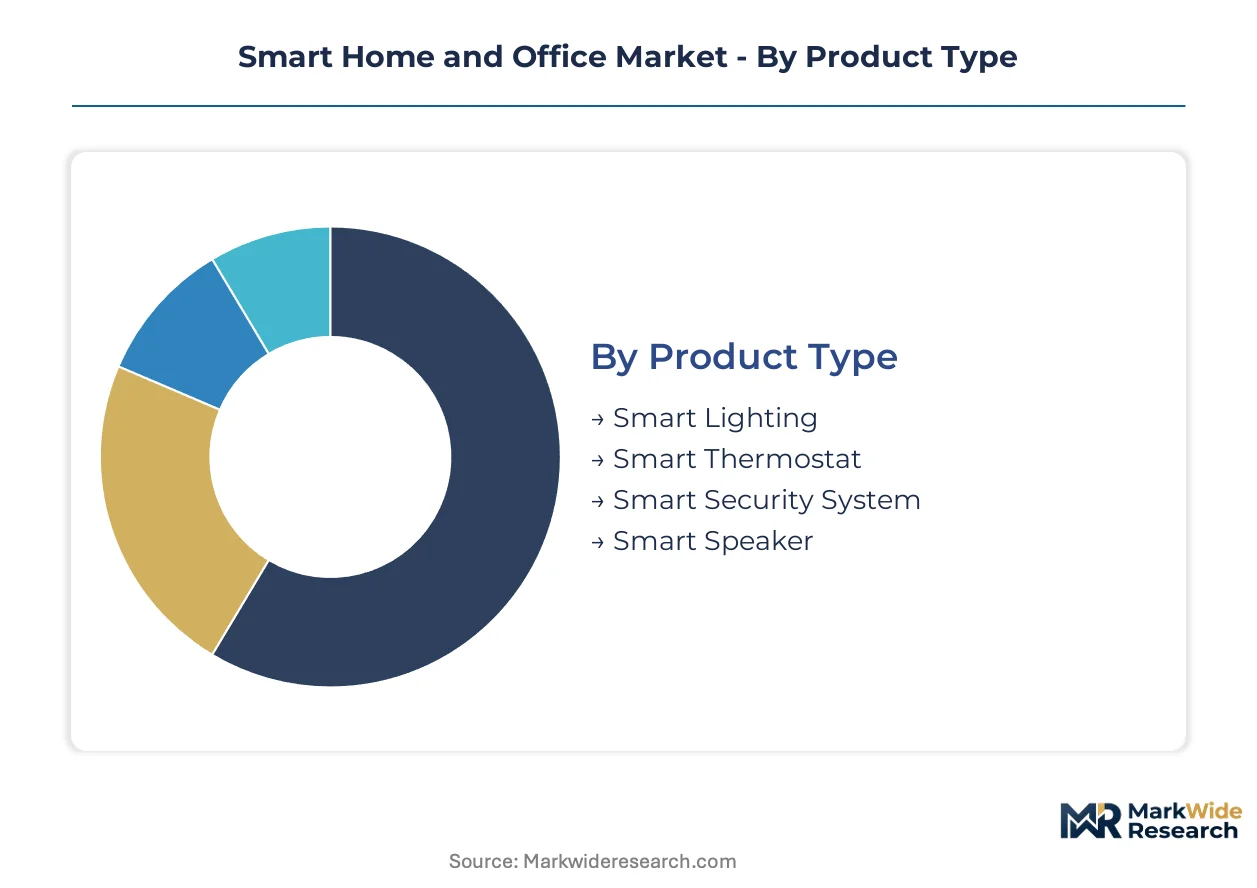
Product Type:
FCC Part 15 emissions testing in the United States and EU AI Act biometric restrictions create divergent certification cost structures across hardware categories.
- Smart Security System:Biometric-enabled access control and video analytics platforms fall under EU AI Act high-risk classification, mandating conformity assessments before CE marking. Insurance underwriters in the United Kingdom and Netherlands now require certified installations for commercial coverage renewals, anchoring recurring subscription revenue streams.
- Smart Thermostat:Environmental sensors with occupancy detection and machine-learning climate optimization face GDPR data retention scrutiny for biometric inference patterns. Germany's federal building efficiency incentives cover 30-50% of upgrade costs for structures over 25 years old, concentrating demand in municipal retrofit programs.
- Smart Lighting:BIS certification in India blocks uncertified imports, forcing redundant product architectures for subcontinent market entry.
- Smart Speaker:Voice-first interfaces leverage cloud analytics pipelines subject to GDPR purpose-specification requirements and data localization mandates.
Established volume favors Smart Security System; emerging adoption favors Smart Thermostat.
End User:
Procurement authority and ESG reporting obligations differentiate customer segments by contract value and technical complexity.
- Corporate Offices:Facility managers consolidate vendor relationships around platform-agnostic service contracts with outcome-based energy efficiency guarantees. Binding sustainability disclosure requirements in Germany and France compress thermostat and lighting retrofit timelines.
- Property Managers:Multi-tenant commercial portfolios demand centralized environmental control with tenant-level submetering and API-accessible consumption data.
- Residential Consumers:Matter protocol convergence eliminates hub fragmentation, enabling cross-platform compatibility without manufacturer-specific infrastructure.
- Small Businesses:Cost-constrained deployments favor Wi-Fi-native devices over dedicated mesh networks, accepting higher latency for reduced capital expenditure.
Contract concentration favors Corporate Offices; price elasticity favors Small Businesses.
Technology:
Protocol selection determines interoperability reach, power consumption, and middleware requirements in integrated building platforms.
- Zigbee:Mesh-range extensions up to 100 meters per hop at 2.4 GHz enable scalable sensor networks with self-healing topology. Installers favor unified Zigbee 3.0 infrastructure for commercial lighting and climate deployments.
- Wi-Fi:Ubiquitous residential coverage supports high-bandwidth audiovisual streaming but consumes excessive power for battery-operated sensor nodes.
- Bluetooth:Low-energy beacons dominate proximity-based access credentialing and indoor positioning in Netherlands corporate campuses.
- Z-Wave:Sub-GHz spectrum penetration through building materials sustains niche presence in security-focused residential installations.
Installer preference favors Zigbee; residential convenience favors Wi-Fi.
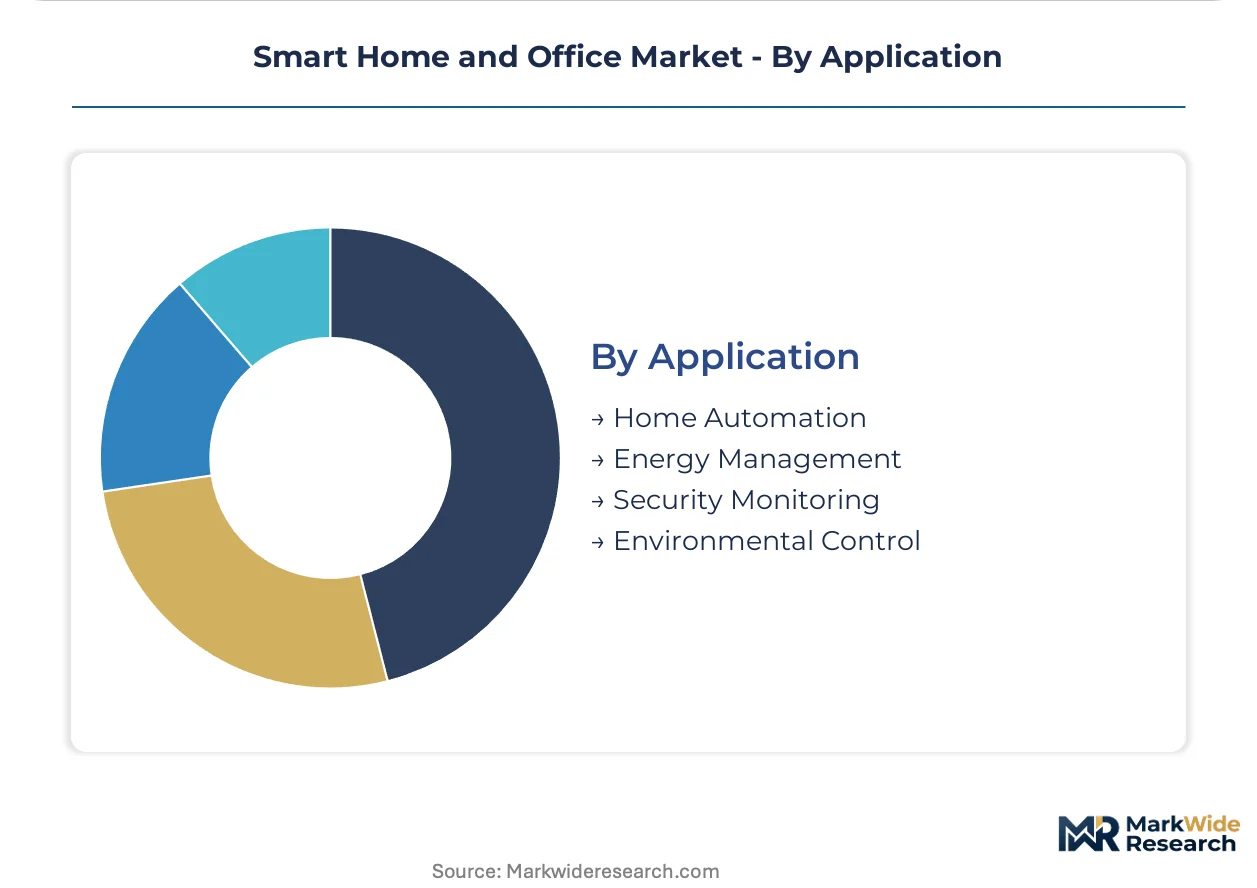
Application:
Functional use cases align with distinct hardware specifications, data governance regimes, and service revenue models.
- Energy Management:ESG reporting mandates in France and Germany sustain the steepest expansion trajectory as facility managers face binding operational efficiency targets.
- Security Monitoring:Recurring subscription revenues and insurance-mandated upgrades anchor value capture, though EU AI Act biometric restrictions compress product development cycles.
- Home Automation:Voice control and scene programming concentrate demand in premium residential segments with multi-brand ecosystem expectations.
- Environmental Control:HVAC integration with legacy BACnet and Modbus infrastructure demands custom middleware development, inflating project costs for 1990s-era commercial buildings.
Regulatory tailwinds favor Energy Management; margin stability favors Security Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act anchor regulatory complexity in Germany, where commercial building retrofits concentrate demand for environmental control systems. Facility managers across multiple geographies face divergent certification timelines that reshape procurement patterns.
United States
Corporate office ESG disclosures and insurance-mandated security upgrades drive thermostat and monitoring deployments. FCC Part 15 emissions rules govern unlicensed radio devices for Wi-Fi and Bluetooth connectivity. Silicon Valley clusters anchor cloud analytics integration for voice-first home automation platforms.
Germany
Federal building efficiency incentives covering 30-50% of HVAC upgrade costs accelerate retrofit programs for structures over 25 years old. The EU AI Act high-risk classification for biometric security systems forces conformity assessment redesigns before CE marking. Munich and Frankfurt facility managers consolidate vendor relationships around outcome-based energy guarantees.
United Kingdom
Property underwriters now require certified smart monitoring systems for commercial coverage renewals, anchoring recurring subscription revenues. GDPR data retention limits for biometric inference patterns demand redesigned data pipelines. London commercial security integrators pivot toward fingerprint alternatives to avoid AI Act delays.
India
BIS certification blocks uncertified smart lighting and thermostat imports, forcing redundant product architectures for market entry. Corporate sustainability targets in Bangalore and Mumbai drive environmental control upgrades. Domestic manufacturing incentives reshape supply chain localization for sensor networks.
Netherlands
Integrated facilities management contracts specify outcome-based energy efficiency guarantees rather than equipment specifications. Bluetooth low-energy beacons dominate proximity-based access credentialing in Amsterdam and Rotterdam corporate campuses. Zigbee 3.0 mesh infrastructure unifies lighting and climate deployments across commercial portfolios.
Smart Home and Office Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the integrated building platform landscape. Cloud-native voice ecosystems and industrial automation conglomerates occupy distinct competitive tiers with minimal overlap in customer procurement channels. Three archetypes dominate: consumer electronics ecosystems extending from mobile and display categories, industrial building automation specialists with legacy HVAC integration capabilities, and pure-play security platforms monetizing through recurring monitoring subscriptions. Consolidation pressure concentrates around middleware layer elimination and Matter protocol convergence, while geographic expansion into German municipal retrofit channels represents the primary growth vector.
Among cloud-native ecosystem providers, Amazon.com, Inc. and Google LLC exemplify voice-first platform strategies anchored in cloud analytics pipelines, while Samsung Electronics Co., Ltd. represents the consumer electronics conglomerate archetype extending protocol reach across white-goods categories. Schneider Electric SE and Siemens AG occupy positions within the industrial automation tier where legacy BACnet integration capabilities differentiate project execution. Johnson Controls International plc and Honeywell International Inc. sit within the building controls specialist segment where outcome-based service contracts reshape competitive positioning. Apple Inc. and LG Electronics Inc. represent premium-tier hardware vendors pursuing cross-platform compatibility through Matter protocol adoption.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Schneider Electric SE |
| Honeywell International Inc. |
| Johnson Controls International plc |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer substitution toward 12-inch advanced node production is compressing microcontroller unit economics while simultaneously shifting procurement gravity toward East Asian foundry networks. This dual displacement tightens margin structures for thermostat and sensor OEMs locked into legacy 8-inch supply agreements.
Pricing Analysis
Price spreads between German municipal retrofit channels and Indian BIS-certified import tiers exceed 40 percent at equivalent specification levels. Three-tier pricing structure across premium Matter-certified, standard Zigbee-native, and economy Wi-Fi-only tiers dominates hardware categories. Certification grade and volume scale drive differentiation, with EU AI Act conformity assessments adding 15-20 percent compliance premiums to biometric-enabled security systems. Pricing pressure stems from silicon supply concentration and embedded engineer scarcity compressing development budgets. Small businesses exhibit highest price sensitivity, while corporate offices under ESG mandates accept outcome-based service premiums.
Supply Chain Analysis
Taiwan and South Korea anchor advanced microcontroller fabrication, feeding sensor node and thermostat controller production. Raw material dependencies center on silicon wafers, rare-earth magnets for actuator motors, and lithium-ion cells for battery-backed devices. Single-source vulnerability concentrates at the 28nm and below process nodes where only two foundry groups maintain volume capacity. Distribution runs through electrical contractor networks in commercial segments and consumer electronics retail in residential channels, with direct-to-enterprise platforms gaining share among facility management consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Matter protocol convergence collapses middleware value capture and redistributes margin toward ecosystem orchestrators and edge-AI silicon suppliers.
For Market Incumbents: Compound cloud analytics integration depth to defend against voice-first platform disintermediation. Extend backward integration into neural accelerator silicon for sensor nodes to offset ARM licensing cost inflation. Lock municipal procurement channels in Germany through outcome-based energy guarantee contracts before facilities management consolidation accelerates.
For New Entrants and Emerging Players: Differentiate on GDPR-compliant data architecture for biometric access systems facing EU AI Act redesign cycles. Target Netherlands integrated facilities management contracts where outcome-based specifications displace equipment-centric procurement. Lead with Thread-native hardware to exploit Matter convergence timing before incumbent protocol migrations complete.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors edge-AI semiconductor specialists and middleware-eliminating protocol platforms. Long-term viability favors vendors with captive silicon supply or certified conformity assessment pipelines through notified body relationships. Watch conformity assessment backlog duration at German and French notified bodies as the primary inflection signal for product launch velocity and working capital intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Eliminates hub fragmentation and collapses 15-20 percent middleware value capture across multi-brand residential deployments. |
| Edge AI Silicon Development | On-device inference reduces cloud dependency latency and GDPR data transfer exposure for biometric security systems. |
| Notified Body Partnership | Secures EU AI Act conformity assessment pipeline priority for high-risk biometric product launches facing 12-18 month backlogs. |
| Backward Integration into MCUs | Captive supply of advanced node microcontrollers insulates against Taiwan-South Korea foundry concentration risk. |
| Outcome-Based Service Contracts | Platform-agnostic energy guarantees align vendor incentives with corporate ESG reporting mandates in Germany and France. |
Study Parameters
Operator-level perspectives from facilities management directors, smart building integration specialists, IoT security architects, and electrical contractor procurement leads anchored the qualitative base. These primary insights combined with secondary validation from BIS certification filings, EU AI Act implementation guidance, SEC 10-K disclosures from ecosystem providers, and Zigbee Alliance interoperability certifications. Bottom-up project pipeline analysis across German municipal retrofit programs triangulated against top-down market sizing from connected device shipment databases.
Sensitivity analysis tested forecast robustness across silicon supply disruption scenarios and regulatory implementation delay assumptions. Segmentation modeling spanned product type, end user archetype, protocol technology, and application function across the projection horizon. CAGR derivation employed installed base replacement cycle analysis and new construction penetration curve fitting. Industry-specific inputs included EU AI Act conformity assessment throughput rates and German federal building efficiency incentive budget allocations.
The analysis sits within stated boundaries; outcomes outside sustained ESG mandate enforcement or Matter protocol adoption acceleration would require recalibration. Forecasts reflect documented assumptions regarding silicon supply continuity and notified body capacity expansion. Recalibration cycles align with material shifts in EU AI Act implementation timelines or geopolitical disruptions to East Asian semiconductor fabrication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Snus Market
Others
Spain Feed Additives Market
Others
Industrial Tablet PC Market
Others
Thermoformed Plastics Market
Others
Global Platform Trolley Market
Others
Brazil Lime Market
Others
Badminton Apparel Market
Others
Fire Sprinkler Market
Others
Hotel Wardrobe Market
Others
India 3D Printing Construction Market
Others
Voice Controlled Devices Market
Others
Fluorite Market
Others
Hypersensitivity Market
Others
Air Separation Plant Market
Others
China Packaging Primers Market