
 Asia-Pacific Programmatic Display Advertising Market | 2026-2036
Asia-Pacific Programmatic Display Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Programmatic Display Advertising Market Insights
Buyer concentration across Asia-Pacific e-commerce platforms is recalibrating how demand-side platforms negotiate inventory access. Google LLC leverages its integrated ad tech stack to sustain dominance across search and display inventory pools. The Trade Desk, Inc. competes through independent demand-side positioning that appeals to brands seeking data portability across walled gardens.
Programmatic display advertising denotes automated, algorithm-driven buying and selling of visual ad inventory through real-time auctions or reserved deals, utilizing demand-side platforms, supply-side platforms, and ad exchanges connected via application programming interfaces. The primary commercial purpose centers on delivering targeted brand messages to specific audience segments at scale while optimizing cost-per-impression through machine learning bid models. Video ads within the format dimension command premium inventory valuations as connected television expands across South Korea and Australia. Real-time bidding in the ad type category captures the highest transaction velocity, though programmatic direct sustains margin advantages for premium publishers in Japan's consolidated media landscape.
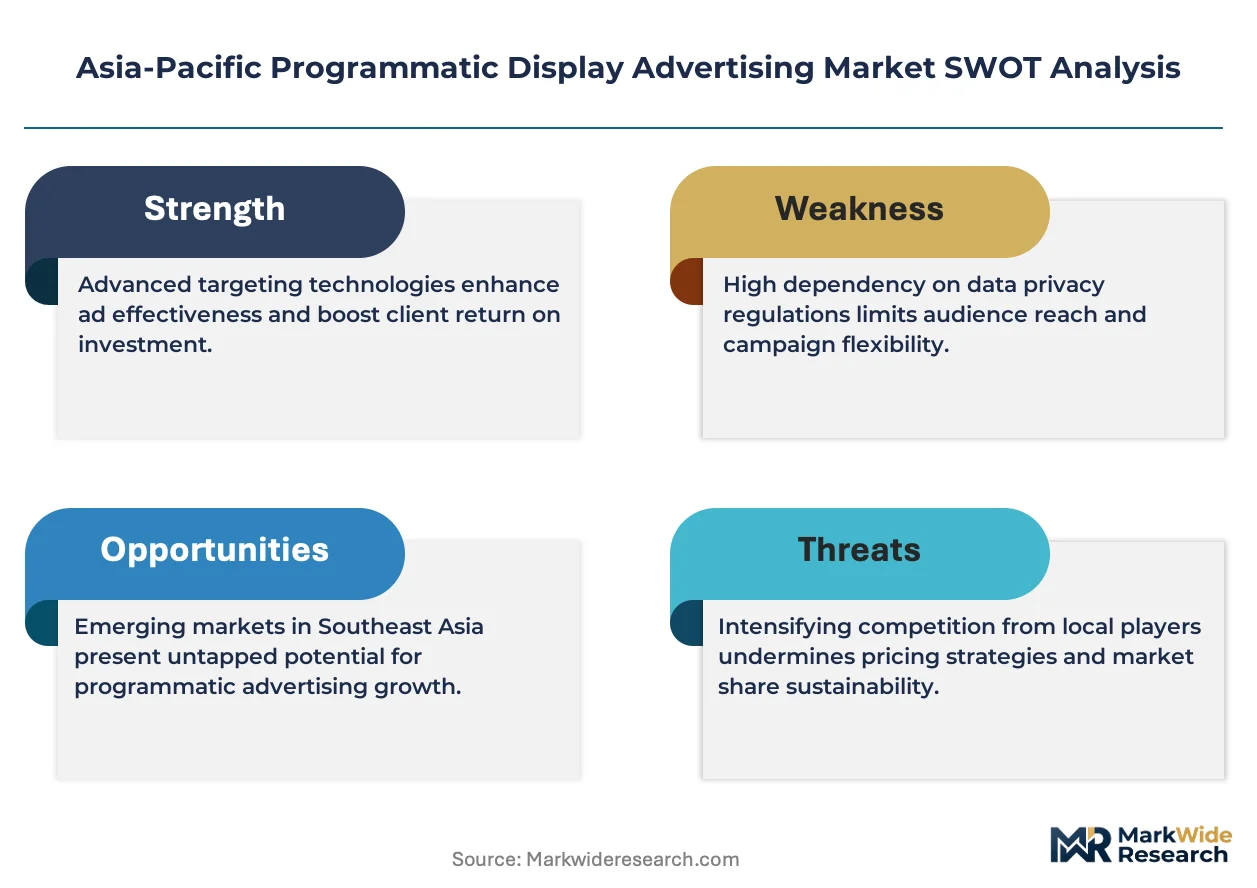
India's Digital Personal Data Protection Act and Australia's Privacy Legislation Amendment (Enforcement and Other Measures) Act constrain third-party data flows, compelling advertisers to adopt first-party data strategies and contextual targeting frameworks. China's Personal Information Protection Law and Cybersecurity Law further segment how multinational platforms operate across mainland inventory pools. Stakeholders must monitor regulatory divergence between data localization requirements in China, consent-based frameworks in Australia, and sectoral guidelines emerging from Singapore's Personal Data Protection Commission as they architect cross-border audience strategies.
Market Dynamics
The Asia-Pacific programmatic display advertising market is experiencing structural recalibration as mobile-first consumption patterns concentrate demand in Indonesia's metropolitan digital economies and India's regulatory framework forces publishers toward first-party data architectures.
Growth Catalysts
- Mobile-First Consumption:Indonesia's metropolitan digital economies now drive the majority of brand allocation decisions, with smartphone-native audiences commanding premium inventory valuations across video and native formats.
- Privacy Regulation:India's Digital Personal Data Protection Act is accelerating investment in consent management platforms and contextual targeting infrastructure as publishers rebuild audience segmentation capabilities.
- Connected Television:South Korea and Australia are absorbing substantial ad tech infrastructure expansion as streaming platforms open inventory to programmatic pipes, creating new premium video supply.
Market Restraints
- Data Localization Requirements:China's Personal Information Protection Law segments multinational platform operations, forcing redundant tech stack deployments and inflating operational overhead for cross-border campaigns.
- Supply Concentration:Google's integrated ad tech stack dominance across search and display inventory pools limits price discovery and negotiating leverage for independent demand-side platforms.
- Third-Party Cookie Deprecation:Identifier fragmentation across Safari, Chrome, and regional browser alternatives complicates frequency capping and attribution modeling throughout Southeast Asia.
Strategic Opportunities
- Retail Media Networks:E-commerce platforms across Southeast Asia are expanding automated ad buying infrastructure, creating closed-loop measurement environments that bypass traditional cookie dependencies.
- Regulatory Tailwind:Singapore's Personal Data Protection Commission sectoral guidelines are establishing regional best practices that favor first-movers in privacy-preserving targeting technologies.
- Programmatic Direct:Japan's consolidated media landscape sustains margin advantages for premium publishers willing to automate reserved deal workflows rather than open auction exposure.
Industry Challenges
- Technical Talent Scarcity:Machine learning engineering expertise for bid algorithm optimization remains concentrated in Bangalore, Sydney, and Singapore, creating recruitment bottlenecks for regional platform expansions.
- Legacy System Integration:Established publishers in Australia and Japan face protracted timelines connecting proprietary ad servers to real-time bidding infrastructure without revenue disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Programmatic Display Advertising Market |
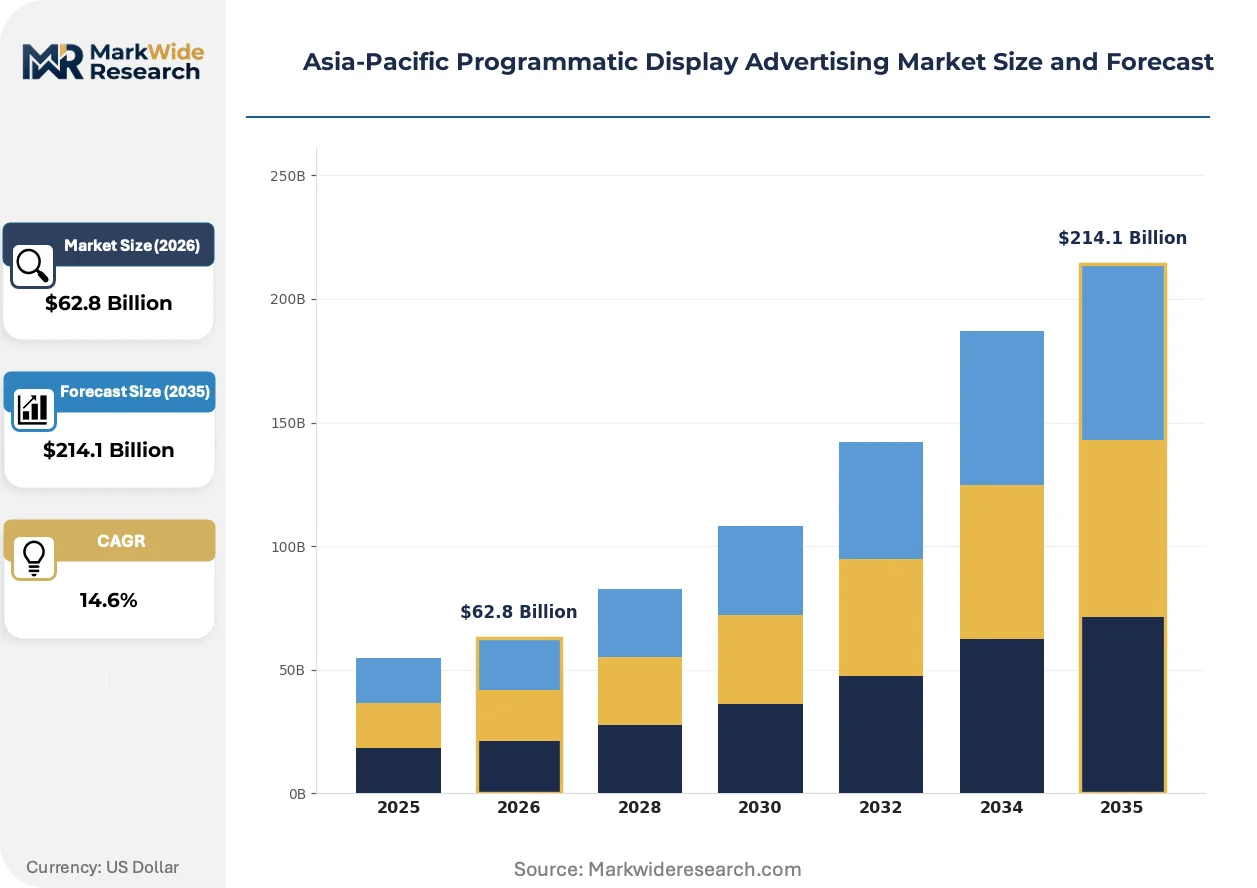
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $214.1 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Banner Ads, Video Ads, Native Ads, Rich Media Ads Channel: Social Media, Mobile Apps, Websites, Email Target Audience: Millennials, Gen Z, Small Businesses, E-commerce Ad Type: Retargeting Ads, Contextual Ads, Programmatic Direct, Real-Time Bidding |
| Companies Covered | The Trade Desk, Inc., Google LLC, AnyMind Group Pte. Ltd., Moloco, Inc., InMobi Pte. Ltd., Appier Inc., Amazon.com LLC (Amazon Advertising), VIOOH, Hivestack Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Programmatic Display Advertising Market Trends and Innovations
Automation architectures across the Asia-Pacific region are absorbing substantial investment as publishers and platforms recalibrate around privacy-preserving measurement and inventory diversification beyond traditional display formats.
Artificial intelligence is absorbing escalating computational resources across demand-side platforms as probabilistic audience modeling replaces deterministic matching. E-commerce advertisers in Indonesia and Vietnam are deploying these capabilities at scale, compressing campaign setup timelines from weeks to hours while expanding creative variant testing beyond human-managed thresholds.
Australia's Privacy Legislation Amendment (Enforcement and Other Measures) Act is tightening consent requirements and penalty structures for data breaches. Publishers operating across Australian inventory pools are accelerating server-side data clean room deployments, with financial services and healthcare advertisers most affected due to sensitive data handling obligations.
Buyer concentration among Asia-Pacific e-commerce platforms is compressing traditional agency intermediation. Direct platform relationships now dominate performance campaign planning in Southeast Asia, with brand marketing teams internalizing programmatic operations previously outsourced to media agencies, a pattern most visible in Indonesia's Tokopedia and Shopee-centric digital economies.
Asia-Pacific Programmatic Display Advertising Market Segmentation
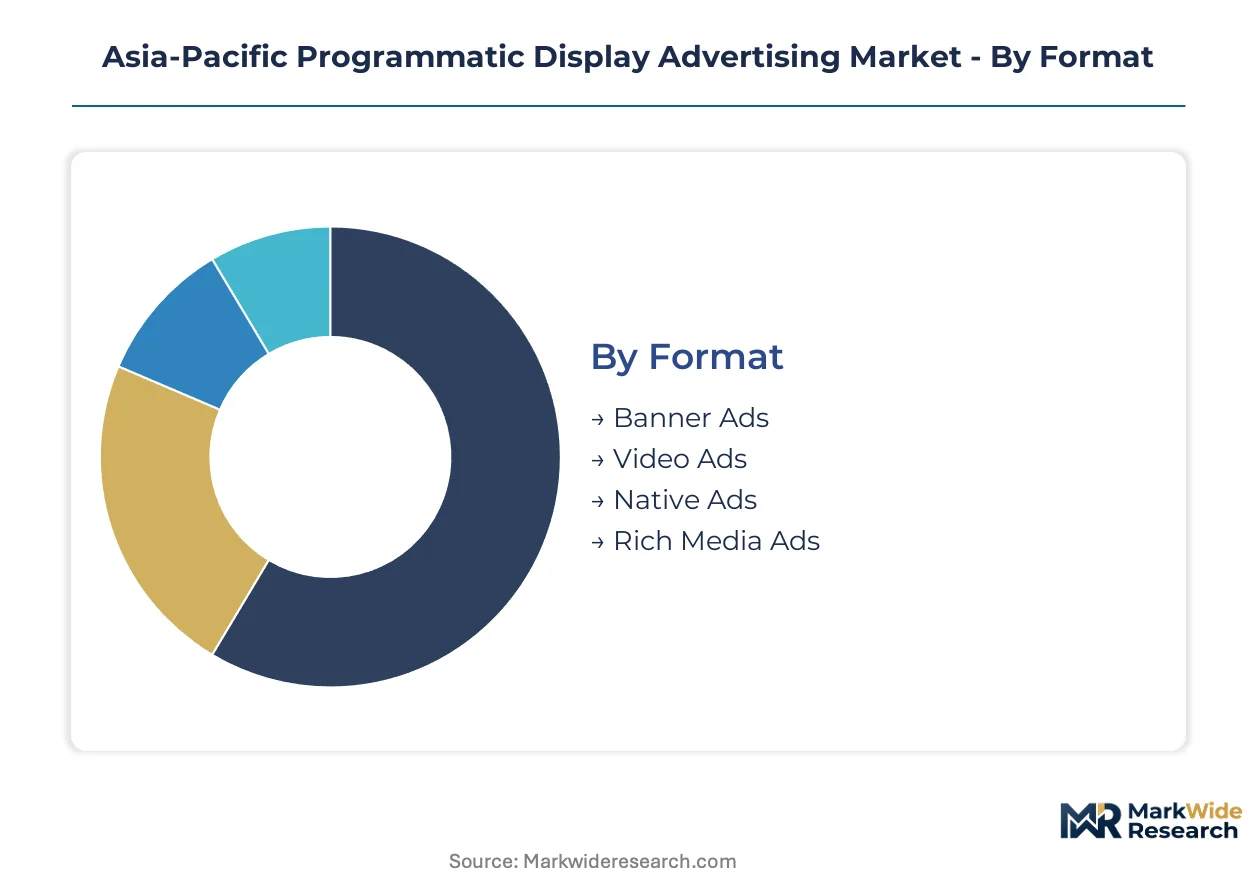
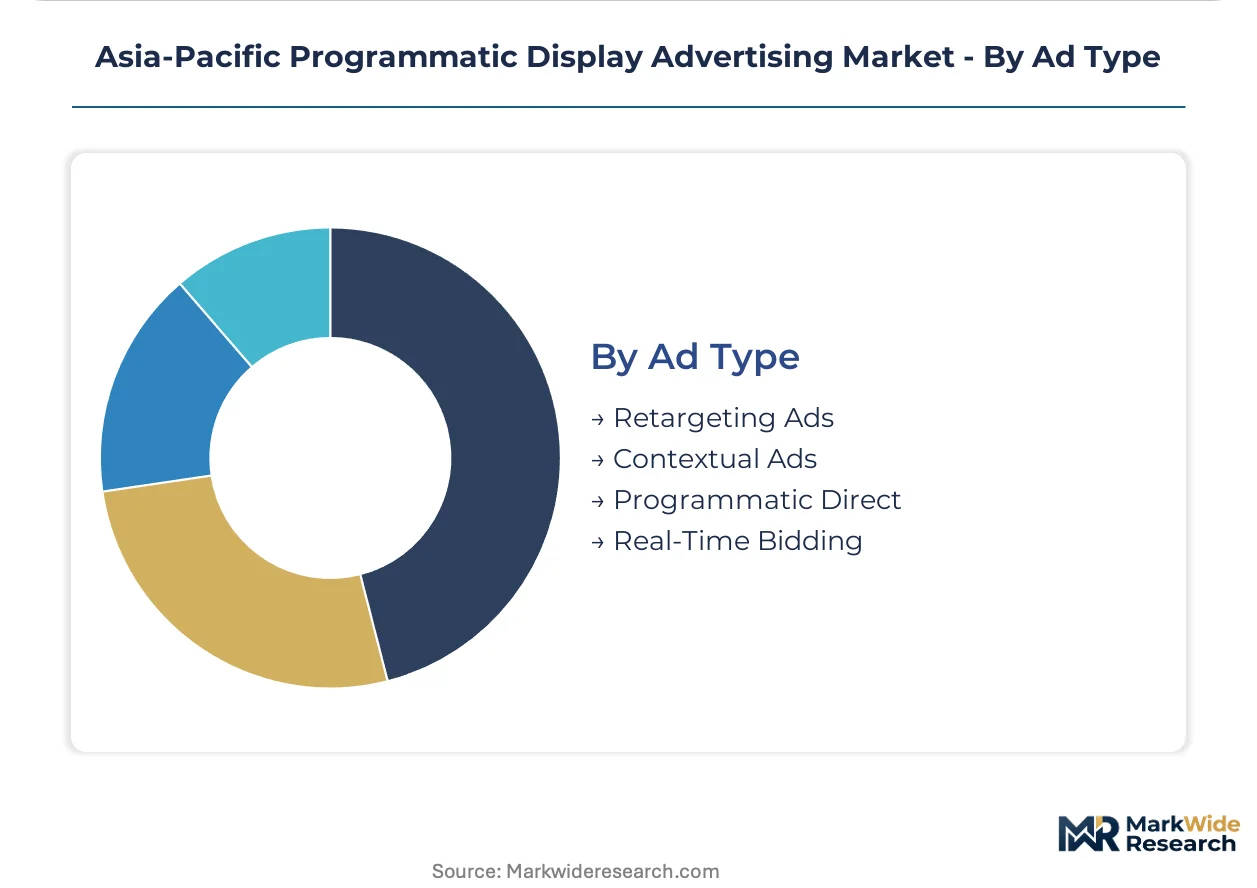
Programmatic display advertising in Asia-Pacific fragments across four intersecting dimensions that determine inventory valuation, targeting precision, and campaign architecture. Format and channel choices reflect mobile-first consumption patterns concentrated in Indonesia and India, while ad type selection increasingly pivots on privacy regulation compliance.
Format:
Budget allocation across formats diverges sharply between brand awareness objectives and performance-driven campaigns, with video commanding premium inventory in connected television markets.
- Video Ads:Connected television expansion across South Korea and Australia has opened premium supply pools for streaming inventory. Advertisers in these markets now prioritize video completion rates over click-through metrics, reshaping bid algorithm optimization.
- Native Ads:These units match publisher content aesthetics through dynamic creative assembly, reducing ad fatigue in Indonesia's scroll-heavy mobile environments. E-commerce platforms favor native formats for product discovery campaigns where intrusion minimization drives conversion.
- Banner Ads:Standard display units retain volume dominance across remnant inventory pools in Southeast Asia, though viewability concerns depress pricing in non-premium placements.
- Rich Media Ads:Interactive formats with expandable or gamified elements absorb higher production budgets from automotive and consumer electronics advertisers seeking engagement depth.
Volume sits with banner inventory; growth tilts toward video as streaming platforms proliferate.
Channel:
Inventory access patterns concentrate demand where first-party data richness enables audience modeling without third-party cookie dependencies.
- Mobile Apps:Indonesia's smartphone-native audiences transact primarily through in-app environments, with super-app ecosystems like Gojek and Grab embedding programmatic pipes directly into service interfaces. These closed loops bypass traditional ad exchange fragmentation.
- Social Media:Platform-specific algorithms in India and Vietnam determine creative distribution, with short-form video inventory absorbing disproportionate demand from fast-moving consumer goods brands.
- Websites:Publisher-direct relationships sustain premium pricing in Japan's consolidated media landscape, where brand safety concerns limit open auction participation.
- Email:Newsletter inventory remains underdeveloped programmatically across Asia-Pacific, though Australia's consent-heavy regulatory environment favors this channel's explicit opt-in structures.
Transaction density clusters in mobile apps; privacy compliance advantages are expanding fastest in email.
Target Audience:
Segmentation strategy reflects generational digital behavior divergence and business model differentiation in addressable markets.
- E-commerce:Direct-to-consumer brands in Southeast Asia concentrate programmatic spend on conversion-optimized audiences, with Shopee and Tokopedia first-party data enabling closed-loop attribution that bypasses cookie deprecation challenges.
- Gen Z:Short attention spans and platform-native content consumption in Vietnam and Philippines drive demand for six-second video and vertical creative formats.
- Millennials:Established purchasing power in South Korea and Australia supports higher cost-per-thousand thresholds for premium inventory targeting this cohort.
- Small Businesses:Self-serve platform adoption in India accelerates as simplified buying interfaces reduce agency dependency for local advertisers.
Spend concentrates with e-commerce targets; Gen Z segments are gaining share fastest in platform-native environments.
Ad Type:
Buying mechanism selection determines data architecture requirements and measurement methodology compatibility.
- Real-Time Bidding:Open auction dynamics dominate Southeast Asia's long-tail inventory, with algorithmic bid optimization compressing human intervention in campaign management.
- Programmatic Direct:Reserved deal workflows sustain margin advantages for premium publishers in Japan, where brand safety and viewability guarantees justify fixed pricing over auction volatility.
- Retargeting Ads:Identifier fragmentation across Safari, Chrome, and regional browsers complicates frequency capping, forcing probabilistic modeling adoption.
- Contextual Ads:India's Digital Personal Data Protection Act accelerates investment in content-based targeting as behavioral data availability contracts.
Transaction velocity peaks in real-time bidding; privacy regulation tailwinds favor contextual fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side platform negotiations concentrate inventory access across Southeast Asian e-commerce ecosystems, while privacy legislation in India and Australia forces architectural rebuilds of audience segmentation infrastructure.
Indonesia
Metropolitan digital economies in Jakarta and Surabaya drive brand allocation decisions through smartphone-native consumption patterns. The country's Ministry of Communication and Informatics enforces data localization provisions that complicate cross-border audience data flows. Super-app ecosystems in Greater Jakarta embed programmatic pipes directly into service interfaces, bypassing traditional ad exchange fragmentation.
India
Direct-to-consumer brands concentrate programmatic spend on conversion-optimized audiences through e-commerce first-party data. The Digital Personal Data Protection Act mandates consent management platform investment and constrains third-party data activation. Bangalore's machine learning engineering clusters supply bid algorithm optimization talent to regional platform expansions.
Japan
Premium publishers sustain margin advantages through automated reserved deal workflows rather than open auction exposure. The Act on Protection of Personal Information governs cross-border data transfers and consent documentation requirements. Tokyo-Osaka corridor media consolidation limits open auction participation due to brand safety concerns.
South Korea
Streaming platforms absorb substantial ad tech infrastructure expansion as connected television inventory opens to programmatic pipes. The Personal Information Protection Commission enforces strict data breach notification and consent granularity standards. Seoul Capital Area demand-side platforms prioritize video completion rate optimization over click-through metrics.
Australia
Server-side data clean room deployments accelerate among publishers serving financial services and healthcare advertisers. The Privacy Legislation Amendment (Enforcement and Other Measures) Act tightens consent requirements and penalty structures for data breaches. Sydney and Melbourne clusters concentrate machine learning engineering expertise for probabilistic audience modeling.
Asia-Pacific Programmatic Display Advertising Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue independent demand-side positioning and retail media network expansion. Market structure tilts toward integrated technology stacks that combine search, display, and video inventory access. Three archetypes dominate: walled garden platforms with captive data ecosystems, independent demand-side platforms emphasizing data portability, and e-commerce-derived retail media networks with closed-loop attribution. Competitive moves concentrate on strategic partnerships with super-app ecosystems and geographic expansion into Vietnam and Philippines programmatic infrastructure.
Within the independent platform tier, The Trade Desk, Inc. and Moloco, Inc. represent demand-side positioning that appeals to brands seeking data portability across walled gardens. Google LLC anchors the integrated stack archetype through combined search and display inventory dominance. AnyMind Group Pte. Ltd. exemplifies regional specialists building automated ad buying infrastructure across Southeast Asian e-commerce platforms.
| Leading Market Players |
|---|
| The Trade Desk, Inc. |
| Google LLC |
| AnyMind Group Pte. Ltd. |
| Moloco, Inc. |
| InMobi Pte. Ltd. |
| Appier Inc. |
| Amazon.com LLC (Amazon Advertising) |
| VIOOH |
| Hivestack Inc. |
| Others |
Pricing and Supply Chain Analysis
E-commerce platform concentration across Southeast Asia concentrates procurement leverage among a handful of super-app ecosystems, compressing transaction fees toward volume-scaled SaaS-tiered models that reward closed-loop attribution capabilities.
Pricing Analysis
Volume-scaled remnant inventory transacts through open auction dynamics at compressed margins, while premium video supply through connected television commands fixed-rate reserved deal structures in South Korea and Australia. Price differentiation hinges on first-party data richness and viewability certification tier, with Indonesia's metropolitan advertisers absorbing higher cost-per-thousand thresholds for super-app embedded placements. Pricing pressure intensifies in banner inventory pools as viewability concerns depress demand, though contextual targeting premiums in India offset behavioral data constraints. Small business self-serve adopters exhibit highest price sensitivity, while multinational CPG brands anchored in Japan's consolidated media landscape accept fixed pricing for brand safety guarantees.
Supply Chain Analysis
Indonesia's data localization mandates under the Ministry of Communication and Informatics reshape cloud infrastructure sourcing, compelling redundant domestic server deployments for cross-border campaign management. Ad tech engineering talent concentrates in Bangalore, Sydney, and Singapore, with machine learning bid algorithm expertise drawing from these clusters for regional platform expansion. Supply chain risk centers on single-source vulnerability in identifier resolution services as third-party cookie deprecation fragments addressability across Safari, Chrome, and regional browser alternatives. Distribution runs through demand-side platform aggregators connecting to supply-side platforms via application programming interfaces, with direct publisher integrations gaining share in Japan's premium inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering scarcity props pricing for algorithm optimization services, constraining platform expansion timelines and sustaining margin premiums for talent-rich clusters.
For Market Incumbents: Deploy consent management infrastructure as the primary defensive lever against India's Digital Personal Data Protection Act compliance deadlines, while securing exclusive super-app integration partnerships in Indonesia's Gojek and Grab ecosystems to preempt independent demand-side platform encroachment. First-party data clean room investments offset identifier fragmentation threats from Safari and Chrome deprecation timelines. For New Entrants and Emerging Players: Enter via Vietnam and Philippines programmatic infrastructure buildouts, where e-commerce platform ad tech penetration remains below Indonesian saturation levels and local machine learning engineering costs undercut Singapore salary benchmarks. White-space opportunity concentrates in retail media network automation for mid-market e-commerce platforms lacking in-house demand-side platform capabilities. For Investors and Strategic Acquirers: The window for entry favors privacy-preserving targeting technology specialists with contextual AI and server-side data clean room deployments, as regulatory tailwinds from Singapore's Personal Data Protection Commission sectoral guidelines accelerate enterprise adoption curves. Acquisition target archetype: independent demand-side platforms with established Indonesia-Australia corridor client relationships. Signal to watch: consent management platform consolidation velocity as India's enforcement deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Clean Room Deployment | Server-side infrastructure bypasses cookie deprecation constraints across Safari and Chrome environments. |
| Super-App Integration Partnership | Embedded programmatic pipes in Gojek and Grab capture Indonesia's smartphone-native transaction volume. |
| Contextual AI Capability Acquisition | Machine learning content analysis replaces behavioral targeting under India's data protection framework. |
| Consent Management Platform Consolidation | Regulatory deadlines from India's Digital Personal Data Protection Act compress vendor selection timelines. |
| Connected Television Inventory Access | Streaming platform partnerships in South Korea and Australia open premium video supply pools. |
Research Methodology
Independent corroboration across demand-side platform executives, supply-side platform technical directors, e-commerce advertising operations leads, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork combined structured interviews with ad tech engineering managers in Bangalore, Sydney, and Singapore clusters alongside secondary validation through TRAI consultation papers, IAB Southeast Asia industry frameworks, SEC filings from listed ad tech platforms, and customs data on cloud infrastructure equipment imports. Bottom-up transaction volume modeling triangulated against top-down media spend allocation surveys.
Rate-of-change decomposition across the analysis window isolates mobile-first consumption acceleration, privacy regulation implementation phases, and connected television inventory expansion as distinct velocity components. Segmentation dimensions modeled include format type, channel environment, target audience archetype, and ad transaction mechanism, with CAGRs derived from algorithmic bid volume trajectories and premium inventory pricing trends. Forecast inputs incorporate e-commerce gross merchandise value growth curves and streaming platform subscriber conversion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated third-party cookie deprecation timelines or sudden data localization enforcement shifts. Assumptions reflect current regulatory implementation schedules and technology platform roadmap disclosures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitation System Market
Others
Liposomes Market
Others
Technical Films Market
Others
DIY Smart Home Market
Others
Allogeneic T Cell Therapies Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Latin America Automotive HVAC Market
Others
Wearable Translator Market
Others
Indoor LBS Market
Others
Drum Motor Market
Others
Kuwait Retail Market
Others
Security Bottles Market
Others
Hypersensitivity Market
Others
Global Learning Analytics Market
Others
Electric Pallet Jack Truck Market
Others
Binoculars and Mounting Solutions Market