
 North America Astrology Market | 2026-2036
North America Astrology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Astrology Market Insights
Certified astrologer supply is rotating toward digital-native practitioners trained in app-based delivery rather than traditional in-person consultation models. Co-Star, Inc. leverages algorithmic natal chart generation to sustain user retention across its mobile platform. Chani Nicholas Inc. anchors premium subscription revenue through personalized horoscope content. Sanctuary competes on real-time astrologer chat interfaces that differentiate its service from static forecast providers.
North American astrology encompasses the commercial provision of celestial interpretation services, natal chart analysis, and predictive forecasting delivered through software algorithms or credentialed practitioners using ephemeris data and house system calculations. The field serves wellness-seeking consumers, corporate human-resource teams, and media publishers requiring serialized content. Horoscope forecasting through mobile apps captures the fastest-growing delivery mode as in-person consultation matures into a premium niche. Individual users represent the deepest customer type pool, while businesses and wellness centers concentrate margin in B2B licensing arrangements.
The Federal Trade Commission monitors advertising claims in astrology-related wellness products, while state-level consumer protection boards in California and New York enforce disclosure standards for paid spiritual services. The absence of federal occupational licensing for astrologers creates fragmented entry barriers that vary by municipality. Stakeholders must track how platform liability doctrines evolve for algorithmic content that users interpret as guidance.
Market Dynamics
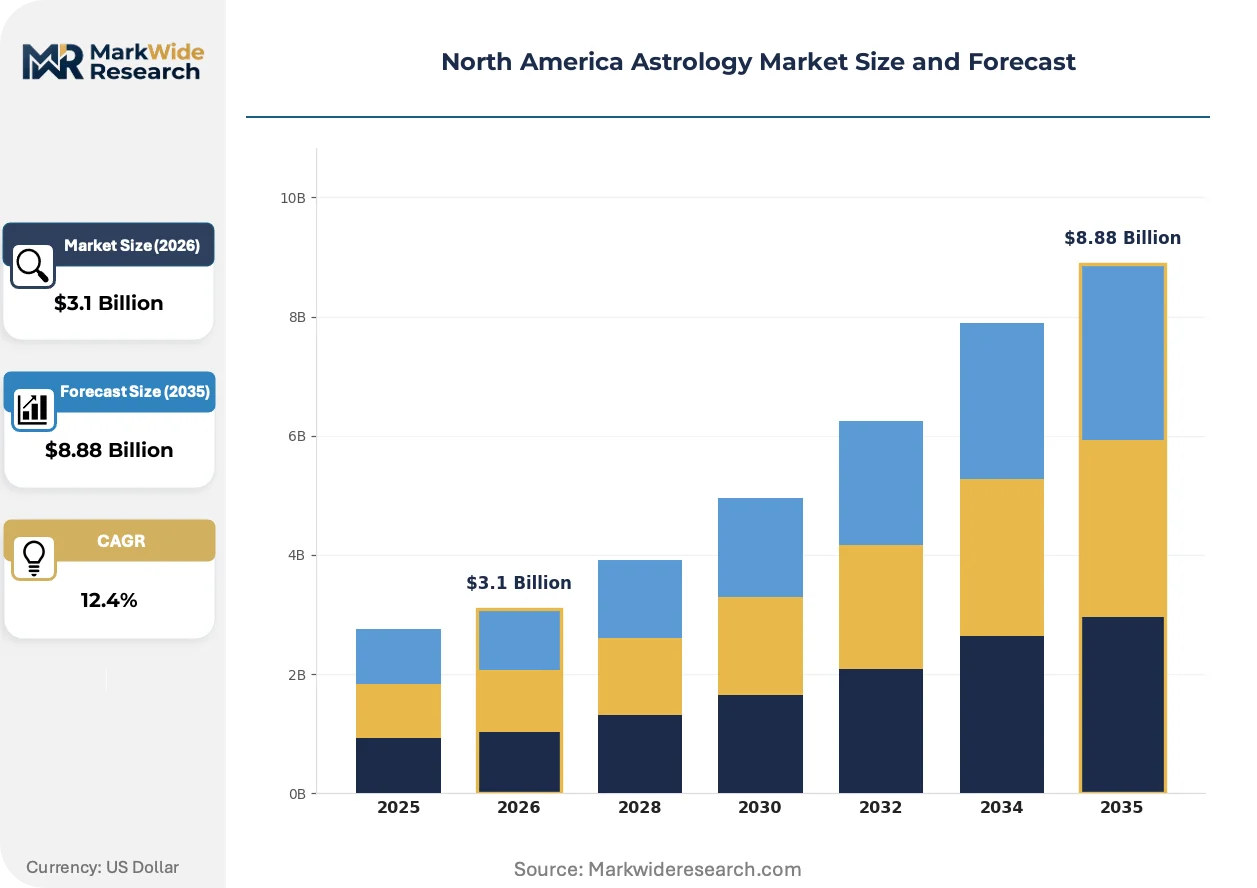
Algorithmic natal chart generation is displacing manual ephemeris calculations as the dominant service delivery mode, compressing consultation costs while expanding addressable user bases across mobile-first demographics in the United States and Canada.
Growth Catalysts
- State-level wellness licensing variations:California's progressive credentialing framework enables astrology practitioners to bundle celestial interpretation with licensed therapeutic modalities, expanding service bundling opportunities.
- Mobile platform penetration:Gen Z and millennial users across the United States drive sustained engagement through push-notification horoscope delivery and social sharing features.
- Corporate human-resource integration:Wellness program administrators in New York's digital media corridor incorporate astrological profiling into team-building and conflict-resolution protocols.
Market Restraints
- FTC advertising scrutiny:The Federal Trade Commission's enforcement actions against unsubstantiated wellness claims in astrology-adjacent products create compliance overhead for predictive forecasting providers.
- Practitioner supply fragmentation:The absence of federal occupational licensing produces uneven service quality across municipalities, constraining brand standardization for platform operators.
- Algorithmic liability exposure:Evolving platform liability doctrines for AI-generated guidance content expose app developers to litigation risk in jurisdictions with expansive consumer protection statutes.
Strategic Opportunities
- B2B wellness center licensing:Spa and retreat operators in British Columbia seek white-label horoscope content to differentiate membership packages without in-house astrologer employment.
- Real-time chat infrastructure:On-demand astrologer access via messaging interfaces captures premium pricing from users dissatisfied with static daily forecasts.
- Ephemeris data API commercialization:Standardized celestial calculation feeds enable third-party developers to build niche applications without proprietary astronomical database investment.
Industry Challenges
- Digital-native practitioner training gaps:Traditional astrologers lack proficiency in app-based delivery interfaces and subscription retention analytics, limiting workforce scalability.
- Cross-border data governance:Canadian and US privacy frameworks impose divergent consent requirements on natal chart data storage, complicating unified platform architecture.
- Consumer protection disclosure standards:New York and California mandate explicit labeling of entertainment versus guidance intent, forcing content redesign and checkout flow modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Astrology Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultations, Horoscopes, Forecasting, Counseling Delivery Mode: Online, In-Person, Mobile Apps, Telephonic Customer Type: Individual Users, Businesses, Wellness Centers, Educational Institutions Content Type: Articles, Videos, Podcasts, Workshops |
| Companies Covered | Susan Miller’s Astrology Zone LLC, AstroMatrix LLC, Co-Star, Inc., Horoscope.com Inc, Sanctuary, The Pattern Inc, Astrolink Inc, Time Nomad, Chani Nicholas Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Astrology Market Trends and Innovations
Generative artificial intelligence is compressing production timelines for personalized horoscope content while reshaping competitive differentiation between algorithmic and human practitioner services across North American markets.
Machine learning models trained on historical ephemeris data and user feedback loops are displacing rule-based astrological engines in mobile applications. Gen Z subscribers in the United States demonstrate higher retention rates on platforms deploying adaptive forecasting that incorporates biographical user inputs. This capability compression is eroding the premium positioning of static natal chart reports while elevating real-time interpretive chat as the defensible value layer.
The Federal Trade Commission's intensified scrutiny of wellness-adjacent advertising claims is forcing astrology service providers to implement explicit entertainment disclaimers and substantiation protocols for predictive accuracy assertions. Platform operators now embed mandatory disclosure screens before payment processing to preempt enforcement action. California and New York state consumer protection boards are extending disclosure requirements to influencer partnerships and affiliate marketing arrangements, affecting content creator economics.
Subscription fatigue among millennial users is fragmenting demand across micro-payment and à la carte consultation models rather than annual commitments. Astrology apps respond with tiered access structures that gate advanced features behind usage-based credits rather than recurring charges. This behavioral shift is most pronounced in Canadian metropolitan markets where discretionary wellness spending faces household budget compression.
North America Astrology Market Segmentation
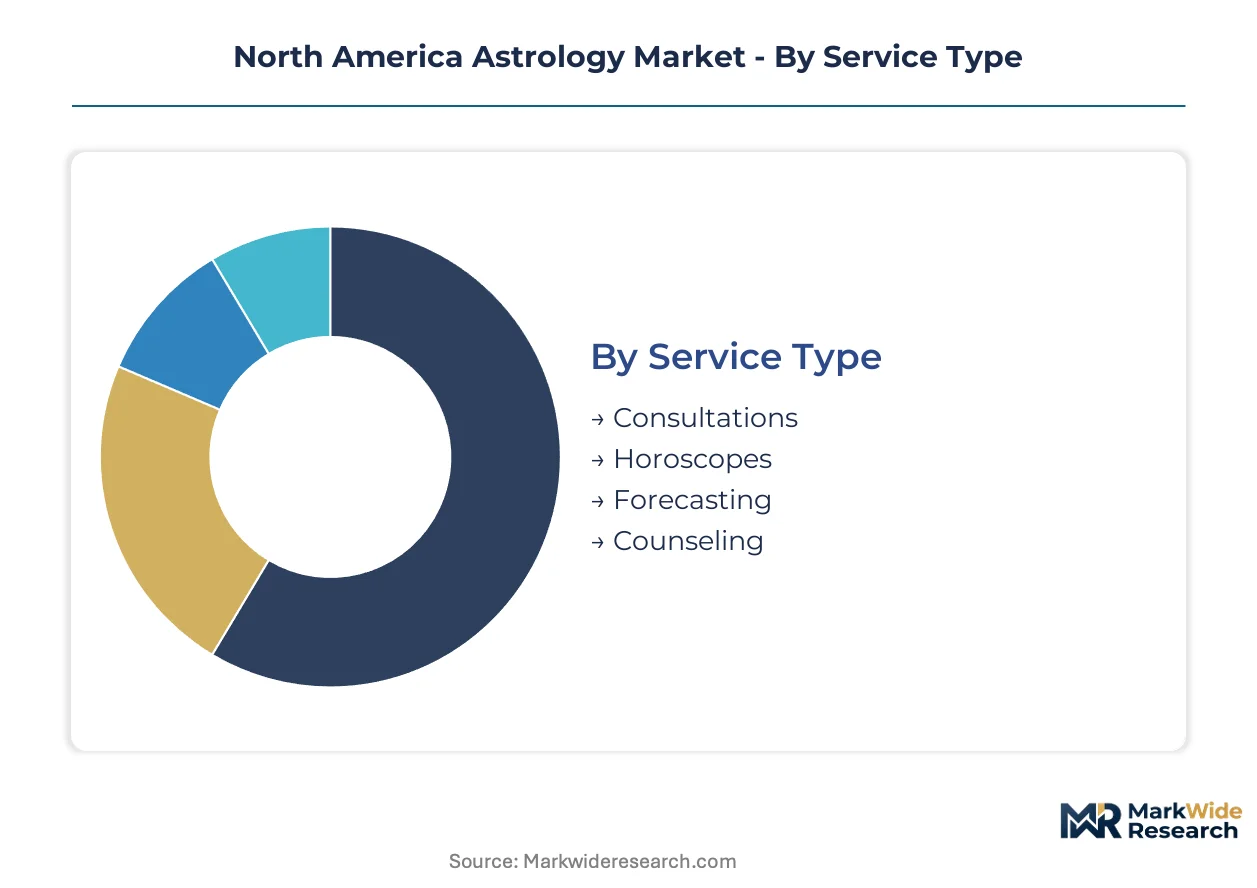
Segmentation in the North America Astrology Market reveals how service delivery, customer acquisition, and content monetization diverge across distinct operational models. Understanding these partitions exposes where platform operators concentrate development resources versus where premium pricing endures.
Service Type:
Channel-mix distribution varies sharply across service categories, with algorithmic offerings scaling through mobile storefronts while practitioner-dependent formats rely on appointment-based booking systems.
- Consultations:One-on-one interpretive sessions with credentialed practitioners, delivered via video call or in-person appointment. California's wellness corridor concentrates premium demand, where practitioners bundle natal chart analysis with licensed therapeutic modalities to command higher session rates.
- Horoscopes:Serialized celestial forecasts generated through ephemeris data algorithms and distributed via push notification or email subscription. Gen Z users across the United States drive volume through social sharing features, though FTC disclosure requirements now mandate explicit entertainment labeling before payment processing.
- Forecasting:Predictive timeline analysis covering career, relationship, and financial transitions. New York's digital media corridor purchases enterprise licenses for team-building applications.
- Counseling:Extended therapeutic engagement combining astrological frameworks with wellness coaching protocols. British Columbia spa operators white-label this content for membership differentiation.
Consultations dominate installed base. Horoscopes are where expansion concentrates.
Delivery Mode:
Cost-tier stratification separates automated platforms from human-mediated services, with pricing gaps widening as algorithmic quality improves.
- Online:Web-based portals offering subscription access to chart libraries and archived interpretive content. Desktop retention lags mobile-first alternatives across Canadian metropolitan markets facing household budget compression.
- In-Person:Physical consultation appointments at dedicated studios or wellness centers. New York and California consumer protection boards enforce disclosure standards for paid spiritual services, elevating compliance overhead.
- Mobile Apps:Native smartphone applications with real-time chart generation and social integration. United States millennial and Gen Z demographics sustain engagement through push-notification delivery and tiered access structures gating advanced features behind usage credits.
- Telephonic:Voice-only consultation services targeting users preferring audio privacy or limited data connectivity. Rural United States markets and older demographics maintain this channel's relevance despite platform migration.
Mobile Apps dominate installed base. Telephonic is where expansion concentrates.
Customer Type:
Application-specific requirements shape product configuration, with B2B contracts demanding API integration while individual users prioritize interface simplicity.
- Individual Users:Personal subscribers seeking self-directed celestial interpretation and daily guidance. Subscription fatigue fragments demand toward micro-payment models rather than annual commitments, most pronounced in Canadian markets.
- Businesses:Corporate human-resource departments integrating astrological profiling into team dynamics and conflict-resolution protocols. New York digital media employers represent the deepest enterprise pool.
- Wellness Centers:Spa, retreat, and holistic health operators licensing white-label horoscope content. British Columbia operators seek this content to differentiate membership packages without in-house astrologer employment.
- Educational Institutions:Universities and continuing-education programs offering astrology coursework for professional certification. California's progressive credentialing framework enables bundled therapeutic modality training.
Individual Users dominate installed base. Wellness Centers are where expansion concentrates.
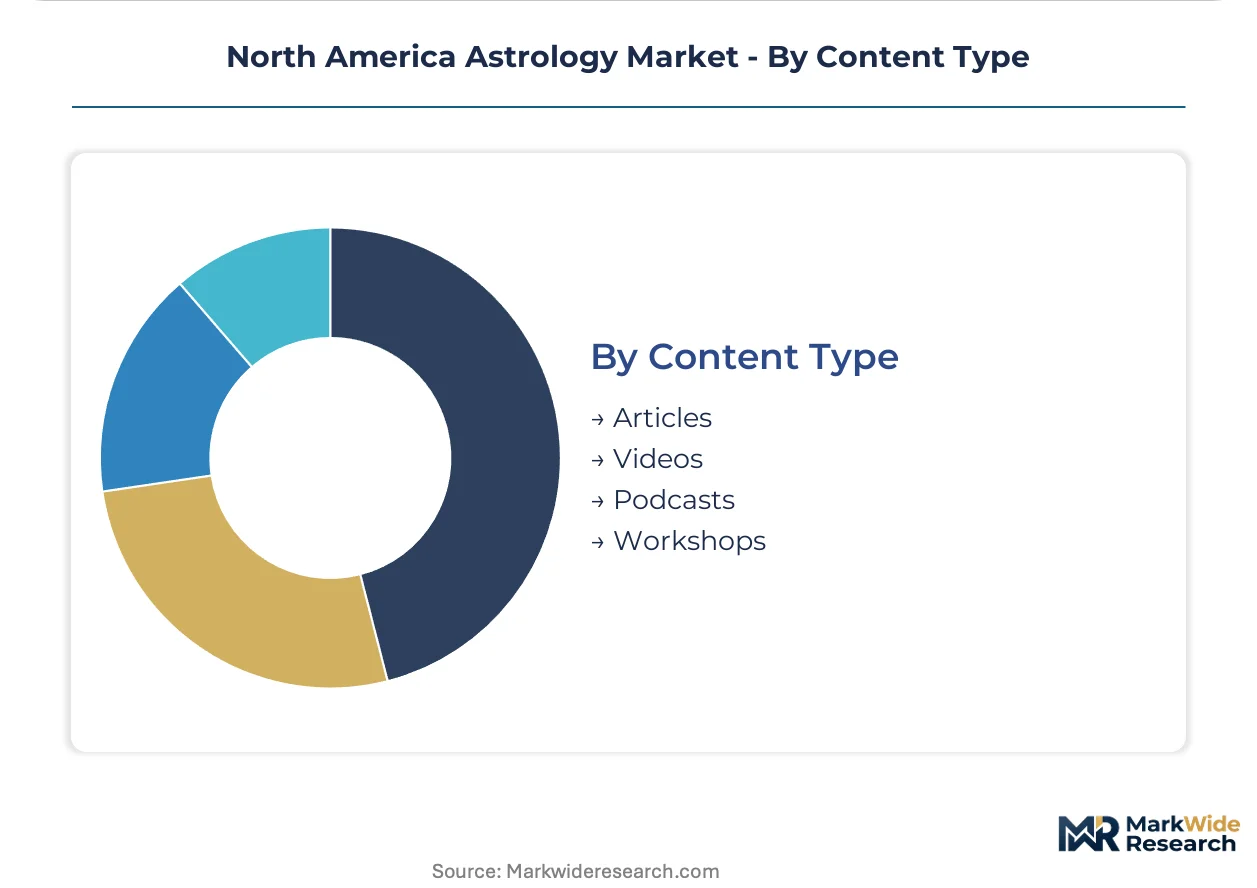
Content Type:
Volume economics favor scalable formats, though premium pricing persists in synchronous interactive offerings requiring real-time practitioner presence.
- Articles:Text-based interpretive content optimized for search discovery and email newsletter distribution. Platform operators embed mandatory disclosure screens to preempt FTC enforcement action on wellness-adjacent claims.
- Videos:Visual chart walkthroughs and forecast explanations distributed through streaming platforms and social feeds. Gen Z retention rates climb on adaptive content incorporating biographical user inputs.
- Podcasts:Audio-only serialized programming covering transit analysis and celebrity chart examination. Commuter-friendly format captures United States metropolitan audiences during transit hours.
- Workshops:Synchronous group learning sessions delivered virtually or in-person. Real-time interpretive chat commands premium pricing from users dissatisfied with static forecast delivery.
Articles dominate installed base. Workshops are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC monitors advertising claims across United States astrology markets, while Health Canada and provincial consumer protection boards regulate disclosure standards north of the border. State-level licensing variations and municipal entry barriers fragment service delivery across both countries.
United States
California's wellness economy and New York's digital media corridor concentrate demand for algorithmic natal chart services and corporate HR integration. The FTC enforces substantiation protocols for predictive accuracy assertions in wellness-adjacent products. Los Angeles and San Francisco anchor practitioner supply chains bundling celestial interpretation with licensed therapeutic modalities.
Canada
British Columbia spa operators drive white-label horoscope licensing demand to differentiate membership packages without in-house astrologer employment. Provincial consumer protection boards enforce disclosure standards for paid spiritual services that exceed federal baselines. Toronto and Vancouver metropolitan markets exhibit pronounced subscription fatigue, fragmenting demand toward micro-payment models.
California
Progressive credentialing frameworks enable astrology practitioners to bundle services with licensed therapeutic modalities, expanding premium pricing opportunities. The California Department of Consumer Affairs monitors disclosure compliance for spiritual service providers. Silicon Valley tech corridors supply engineering talent for mobile platform development and ephemeris data API commercialization.
New York
Digital media employers in Manhattan and Brooklyn purchase enterprise licenses for team-building and conflict-resolution applications of astrological profiling. The New York State Attorney General enforces explicit labeling mandates for entertainment versus guidance intent. Hudson Valley wellness retreat clusters sustain demand for synchronous practitioner consultations.
Ontario
Toronto's metropolitan user base demonstrates higher sensitivity to discretionary wellness spending compression, accelerating shift toward usage-based credit models. Health Canada guidelines on wellness product advertising influence platform disclosure screen design. The Greater Toronto Area concentrates educational institutions offering professional astrology certification coursework.
North America Astrology Market Competitive Landscape
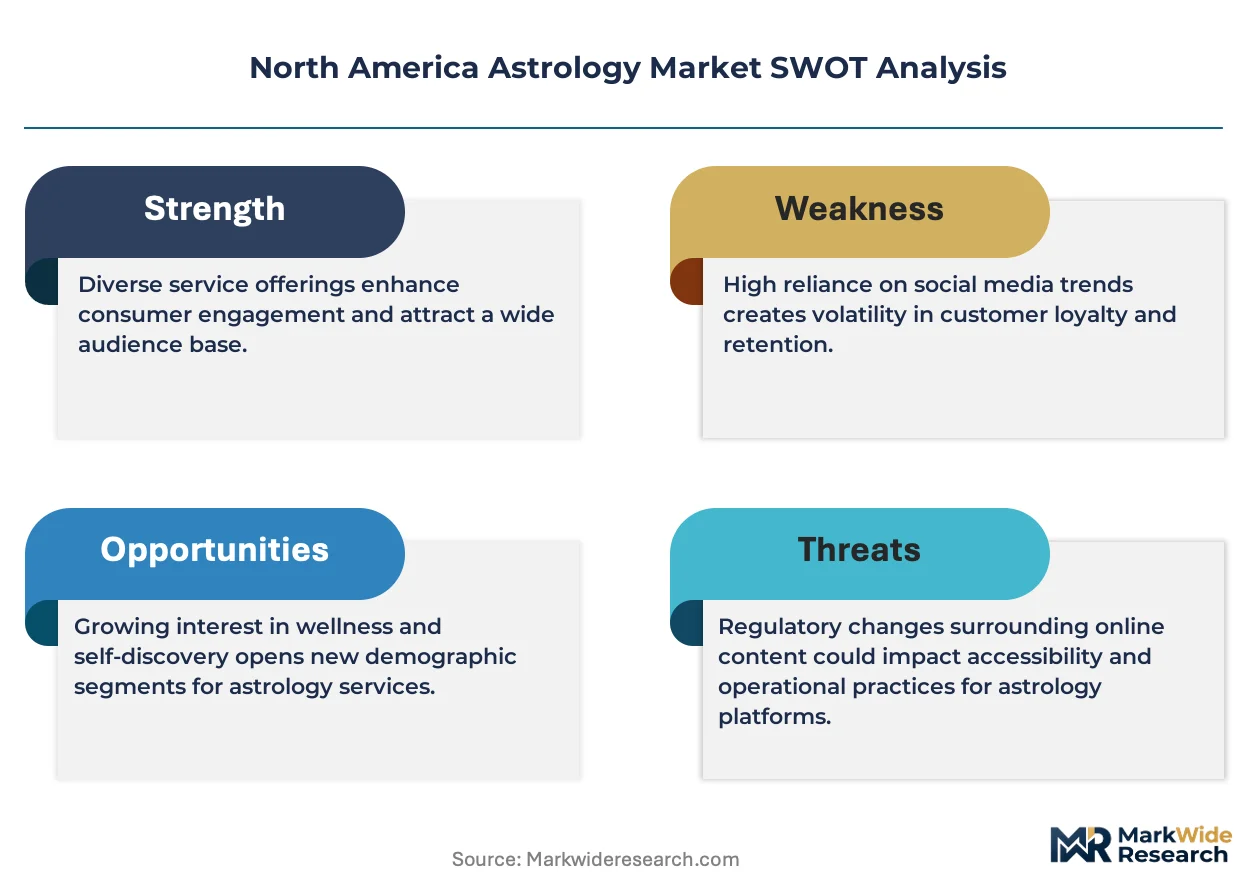
A small set of integrated leaders sits above a broader specialist tier, with algorithmic platform operators commanding mobile-first user bases and practitioner-dependent services defending premium pricing through real-time access. The competitive field stratifies across three archetypes: venture-backed mobile applications leveraging machine learning for retention, boutique subscription services anchored by personality-driven content, and white-label infrastructure providers licensing ephemeris calculation engines. Dominant competitive moves center on B2B wellness center partnerships and tiered access structures that gate advanced features behind usage credits.
Within the algorithmic platform tier, Co-Star, Inc. and The Pattern Inc exemplify venture-scaled mobile-first operators that have displaced manual ephemeris calculations with adaptive forecasting engines. Chani Nicholas Inc occupies a position in the personality-anchored subscription segment where premium content commands recurring revenue through individualized horoscope delivery. These three entities represent the primary competitive archetypes: technology-scaled retention platforms, creator-driven premium subscriptions, and the hybrid models emerging at their intersection.
| Leading Market Players |
|---|
| Susan Miller's Astrology Zone LLC |
| AstroMatrix LLC |
| Co-Star, Inc. |
| Horoscope.com Inc |
| Sanctuary |
| The Pattern Inc |
| Astrolink Inc |
| Time Nomad |
| Chani Nicholas Inc |
| Others |
Pricing and Supply Chain Analysis
California's progressive credentialing framework gates both practitioner qualification and premium pricing tiers simultaneously, bundling licensed therapeutic modalities with celestial interpretation to command higher session rates while fragmenting supply access across municipalities lacking equivalent standards.
Pricing Analysis
California-to-New York price spreads exceed threefold for equivalent consultation services, with Los Angeles practitioners bundling natal chart analysis with licensed wellness coaching. Three-tier pricing structure across premium, standard, and economy levels separates algorithmic mobile subscriptions from real-time chat access and in-person therapeutic bundles. Cost compression in algorithmic tiers is intensifying because machine learning models displace rule-based engines without proportional quality degradation. Individual users in Canadian metropolitan markets exhibit highest price sensitivity, while corporate HR departments in New York's digital media corridor demonstrate lowest sensitivity due to wellness program budget insulation.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for ephemeris data hardware and specialized astronomical calculation equipment. Supply concentrates in the United States for mobile platform engineering talent, Canada for white-label content production, and select European jurisdictions for legacy ephemeris database licensing. Raw material dependencies include proprietary astronomical datasets, cloud computing infrastructure, and licensed therapeutic modality frameworks. Single-source vulnerability pervades ephemeris data providers, where exclusive licensing agreements tether multiple platforms to identical upstream repositories. Distribution runs through direct-to-consumer mobile storefronts for algorithmic services and appointment-based booking systems for practitioner-mediated formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative artificial intelligence inflection compresses production timelines for personalized content, creating high-growth disruption as machine learning displaces rule-based engines and reshapes competitive differentiation between algorithmic and human practitioner services.
For Market Incumbents: Shield premium subscription revenue by embedding real-time interpretive chat as the defensible value layer above commoditized algorithmic forecasts. Fortify against venture-scaled mobile entrants through exclusive practitioner network lock-in and California credentialing bundling. Vertical integration into proprietary ephemeris data API commercialization reduces dependency on licensed upstream repositories. For New Entrants and Emerging Players: Lead with white-label horoscope licensing for British Columbia spa operators seeking membership differentiation without in-house astrologer employment. Target wellness center B2B arrangements as the most penetrable segment, where procurement lacks technical evaluation capacity. Deploy usage-based credit models rather than annual subscriptions to capture Canadian metropolitan markets exhibiting pronounced subscription fatigue. For Investors and Strategic Acquirers: FTC advertising scrutiny reshapes the acquisition landscape by elevating compliance infrastructure value and penalizing platforms lacking mandatory disclosure screen implementation. Long-term viability across the projection horizon favors targets with established practitioner networks and algorithmic retention engines rather than personality-dependent content brands. Watch for platform liability doctrine evolution in California and New York as the critical inflection signal for litigation risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Ephemeris Data API Commercialization | Standardized celestial calculation feeds enable third-party developers to build niche applications without proprietary database investment. |
| Real-Time Chat Infrastructure Deployment | On-demand astrologer access via messaging interfaces captures premium pricing from users dissatisfied with static forecast delivery. |
| B2B Wellness Center Licensing | Spa and retreat operators in British Columbia seek white-label horoscope content to differentiate membership packages. |
| Algorithmic Retention Engine Investment | Machine learning models trained on historical ephemeris data and user feedback loops displace rule-based astrological engines. |
| Regulatory Compliance Infrastructure | Mandatory disclosure screens before payment processing preempt FTC enforcement action on wellness-adjacent advertising claims. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with mobile platform executives, licensed astrology practitioners, wellness center procurement managers, and corporate HR wellness administrators; and secondary validation through FTC enforcement records, state consumer protection board filings, App Store analytics, and ephemeris database licensing agreements. Bottom-up triangulation across individual user subscription data and top-down cross-check against platform revenue disclosures anchored volume estimates.
Across the analysis window, forecasts modeled service type, delivery mode, customer type, and content type segmentation dimensions with regional regulatory cluster overlays. CAGRs derived from historical engagement trajectory analysis and demographic penetration modeling. Industry-specific inputs included Gen Z retention coefficients on adaptive forecasting platforms and corporate wellness program adoption curves in New York's digital media corridor.
Forecasts assume regulatory continuity in FTC advertising enforcement and California consumer protection regimes; material policy shifts would require re-modeling practitioner disclosure requirements and platform liability exposure. Specific risks that could revise projections include algorithmic liability doctrine expansion, federal occupational licensing implementation, and cross-border data governance divergence between Canadian and US privacy frameworks. Practitioners should keep alternative scenarios live as platform liability doctrines and state-level credentialing requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Gem Faceting Machine Market
Others
Infant Fever Stickers Market
Others
Global Mobile Gambling Market
Others
Air Separation Unit Market
Others
North America Halal Food and Beverage Market
Others
Finished Leather Market
Others
Global Multi-Access Edge Computing Market
Others
Germany 3D Printing Construction Market
Others
Prunes Market
Others
Europe Indoor LBS Market
Others
Asia Pacific Contract Packaging Market
Others
LAMEA Astrology Market
Others
Germany Smart Home Market
Others
South Korea Smart Home Market
Others
Japan 3D Printing Construction Market
Others
US Mobile MRI Services Market