
 Digital Audio Decoders Market | 2026-2036
Digital Audio Decoders Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Audio Decoders Market Analytics
South Korea's semiconductor fabrication expansion is reconfiguring supply dynamics for digital audio decoder silicon. Analog Devices leverages its precision converter portfolio to anchor high-fidelity professional audio applications. Qualcomm competes through integrated Snapdragon Sound platforms that bundle decoding with wireless transmission. Texas Instruments sustains broad industrial and automotive decoder supply through its mixed-signal manufacturing scale.
A digital audio decoder converts compressed or encoded digital audio streams into analog signals or uncompressed digital formats for playback, typically handling sample rates from 44.1 kHz to 192 kHz and bit depths of 16 to 24 bits. The device serves as the critical signal-processing bridge between content sources and acoustic output systems in consumer, automotive, and professional environments. Integrated decoders dominate volume shipments as system-on-chip architectures absorb discrete functions to reduce board space and power draw. Dolby Atmos technology commands premium positioning in home theater and automotive segments where object-based spatial audio differentiates user experiences. USB-C decoders represent the fastest-growing product configuration as mobile and laptop OEMs eliminate dedicated headphone jacks.
The FCC equipment authorization framework and the EU Radio Equipment Directive constrain decoder electromagnetic emissions and interoperability certification pathways. China's MIIT enforces GB standards for audio equipment that affect import and domestic product compliance requirements. Dolby Laboratories' proprietary licensing structure creates additional standard-essential patent layers that manufacturers must navigate for branded codec support. Stakeholders must monitor regulatory divergence between North American and Asian certification regimes as regional content protection and audio format mandates harden.
Market Dynamics
Automotive OEMs are embedding object-based spatial audio architectures as standard equipment, compressing upgrade cycles and forcing tier-2 suppliers to absorb decoder integration costs previously borne by discrete component vendors.
Growth Catalysts
- EU Radio Equipment Directive harmonization:Unified electromagnetic compatibility certification across member states reduces redundant testing burdens for decoder hardware destined for automotive and consumer electronics channels.
- Automotive immersive audio mandates:Premium vehicle platforms now specify 16+ channel decoding as standard, pulling silicon demand from home theater into cabin entertainment systems.
- South Korean foundry expansion:Domestic semiconductor fabrication capacity for mixed-signal audio chips is loosening foundry allocation constraints that previously bottlenecked decoder supply.
Market Restraints
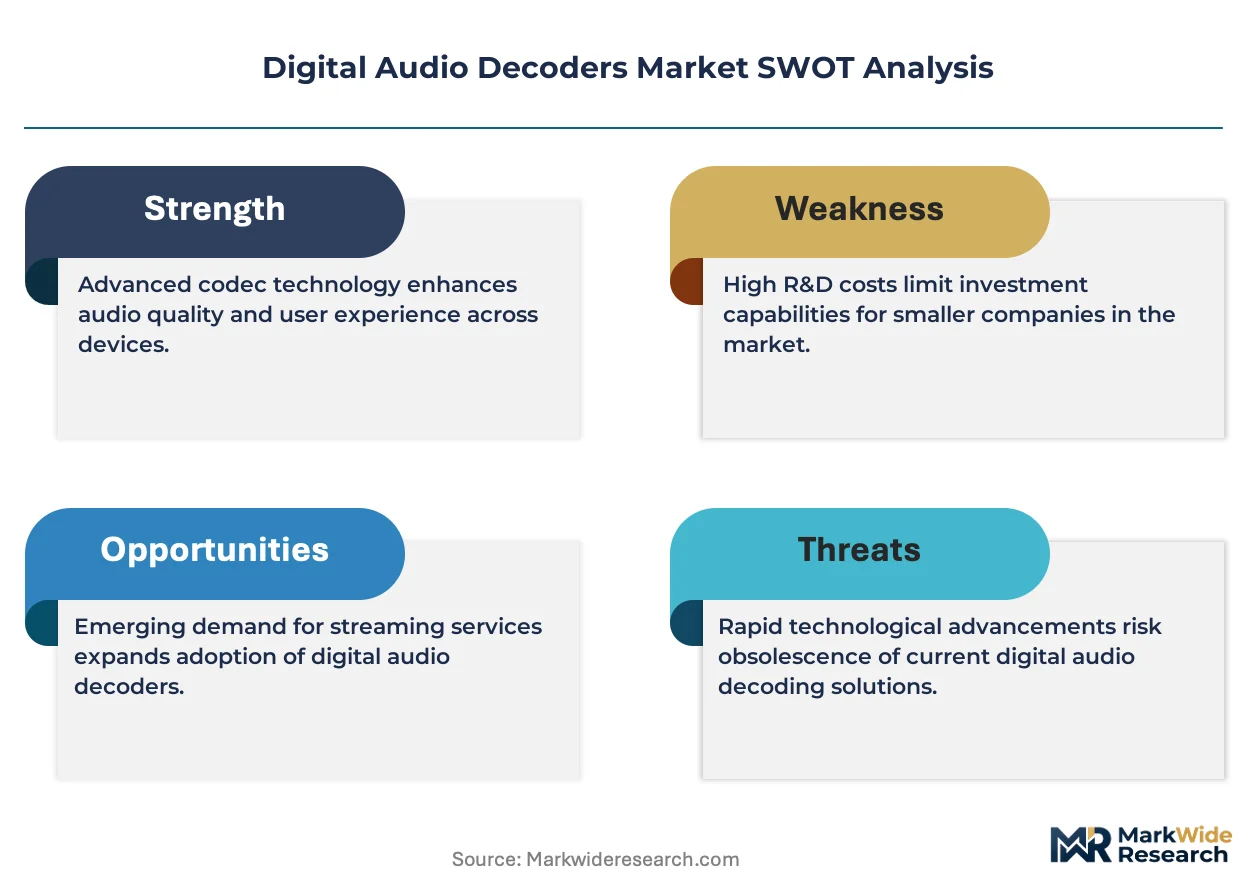
- Dolby licensing cost structure:Proprietary codec royalties impose fixed per-unit fees that compress margins on sub-$50 decoder modules in price-sensitive consumer tiers.
- Silicon supply concentration:Advanced node mixed-signal production clusters in Taiwan and South Korea, exposing decoder vendors to single-point disruption risks.
- Legacy analog interface persistence:Industrial and pro-audio equipment retains RCA and XLR connectivity, fragmenting decoder design requirements and preventing pure-digital optimization.
Strategic Opportunities
- India BIS certification alignment:Simplified type-approval pathways for audio equipment under revised electronics safety standards reduce time-to-market for decoder imports.
- USB-C audio unification:Mobile and computing OEM elimination of 3.5mm jacks is creating attach-rate expansion for external DAC-decoder dongles in laptop and tablet ecosystems.
- Automotive software-defined audio:Over-the-air codec updates enable subscription monetization of premium decoding features, decoupling hardware from content format evolution.
Industry Challenges
- Multichannel calibration expertise scarcity:Automotive and home theater integrators face shortages of acoustic engineers capable of tuning object-based spatial audio systems to cabin or room geometry.
- FCC equipment authorization timelines:Electromagnetic compatibility certification queues for decoder hardware extend lead times, compressing product launch windows against format standard releases.
- IP fragmentation across codec standards:Patent thickets surrounding MPEG-H, DTS:X, and Auro-3D force vendors to maintain multi-license compliance programs with divergent royalty structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Audio Decoders Market |
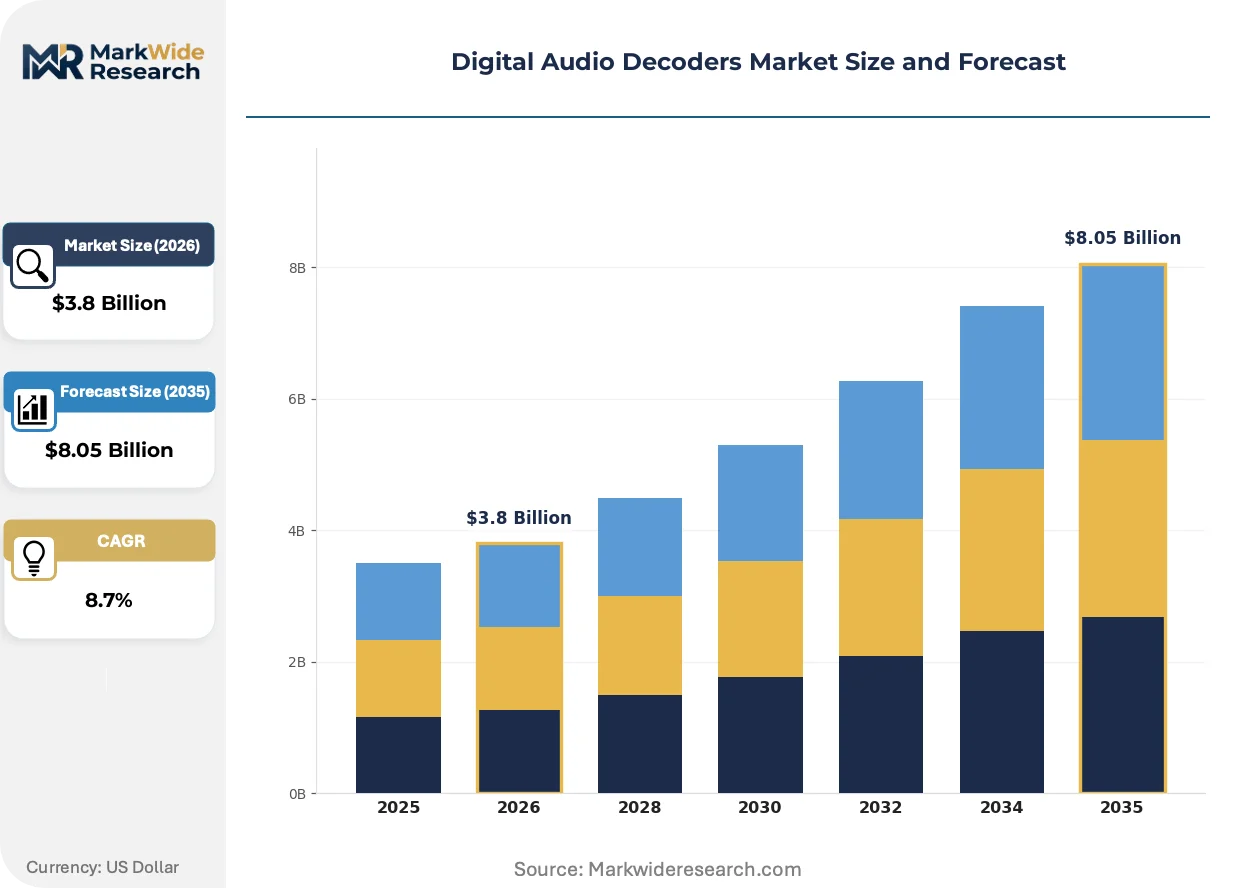
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Decoders, Integrated Decoders, USB-C Decoders, HDMI Decoders Technology: Digital Signal Processing, Dolby Atmos, DTS, PCM End User: Home Theater Systems, Automotive Audio, Professional Audio Equipment, Streaming Devices Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Analog Devices, Cirrus Logic, Qualcomm, Realtek Semiconductor, STMicroelectronics, Texas Instruments, Dolby Laboratories, Sony Corporation, Synopsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Audio Decoders Market Evolving Landscape
Decoder architecture is converging with wireless transmission and AI-driven spatial processing, collapsing discrete component boundaries while regulatory pressure on electromagnetic emissions intensifies hardware design constraints.
Discrete DAC-decoder chipsets are migrating from standalone board-mounted packages into system-on-chip implementations that combine decoding, amplification, and wireless baseband. Mobile OEMs and automotive tier-1s now specify single-silicon solutions to reduce bill-of-materials complexity and board area. This integration is compressing the addressable market for dedicated decoder vendors while expanding the functional scope of surviving suppliers.
China's MIIT enforcement of updated GB standards for audio equipment electromagnetic emissions is forcing decoder redesigns to satisfy stricter conducted and radiated interference limits. Domestic certification laboratories face testing backlogs, delaying product launches for manufacturers targeting Chinese consumer electronics channels. Automotive decoder suppliers are responding by pre-certifying modules against both GB and FCC frameworks to maintain cross-border shipment flexibility.
Automotive procurement departments are consolidating decoder sourcing through direct tier-1 partnerships, bypassing traditional distribution channels. Bosch, Harman, and Panasonic Automotive now specify decoder silicon directly with foundries, relegating merchant semiconductor vendors to secondary supplier status. This concentration is most visible in Germany and Japan, where OEMs maintain captive acoustic engineering teams that dictate component specifications upstream.
Digital Audio Decoders Market Segmentation
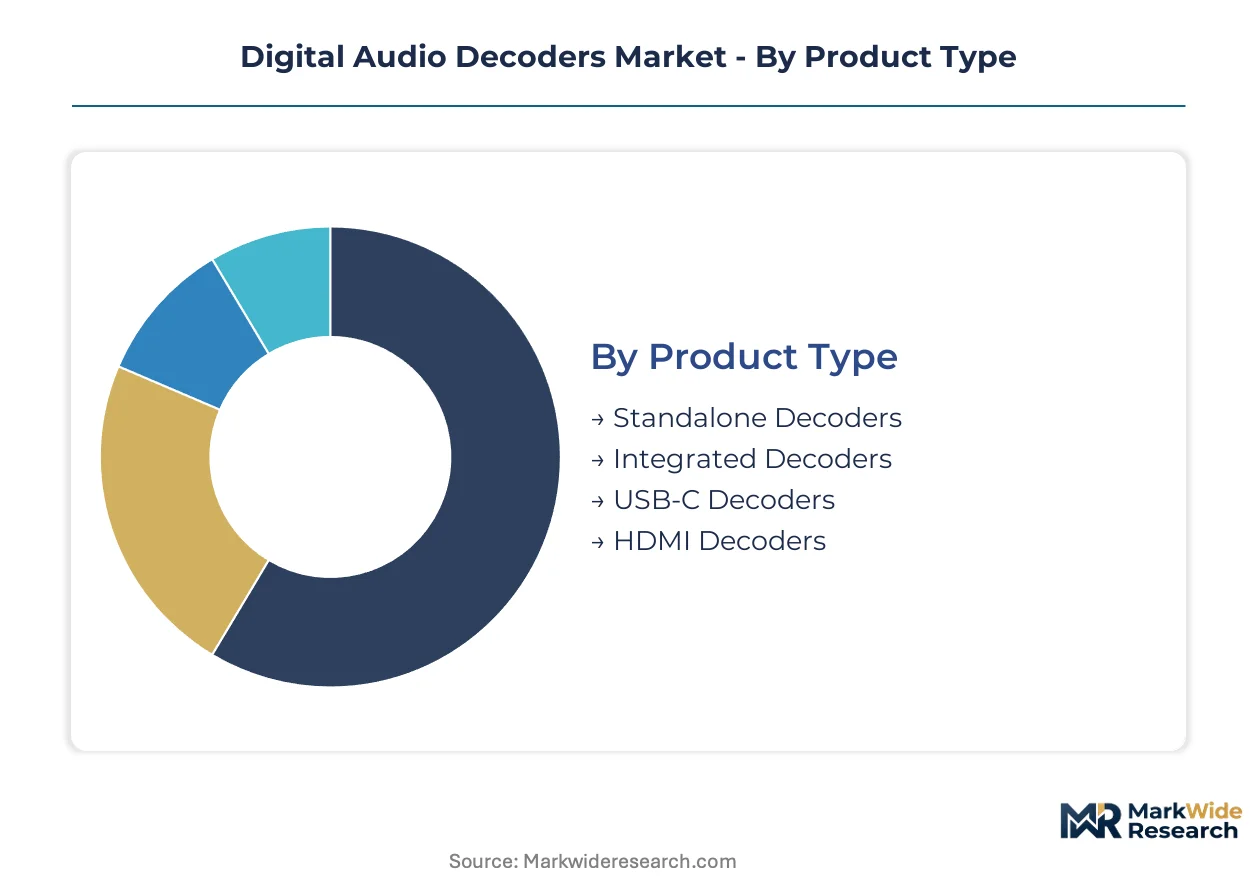
Decoder architecture fragmentation demands granular segmentation to map how silicon integration, interface standards, and end-use specifications reshape procurement patterns across consumer, automotive, and professional channels.
Product Type:
Use-case spectrum spans discrete audiophile components to system-on-chip implementations that automotive tier-1s now specify for cabin entertainment architectures.
- Integrated Decoders:System-on-chip architectures combine decoding, amplification, and wireless baseband functions into single-silicon solutions. Automotive OEMs in Germany and Japan now mandate these modules for 16+ channel cabin systems, compressing board area while forcing tier-2 suppliers to absorb integration costs previously borne by discrete vendors.
- USB-C Decoders:External DAC-decoder dongles attach via USB-C as mobile and laptop OEMs eliminate 3.5mm headphone jacks. Samsung and Apple supply chain specifications in South Korea and California are driving attach-rate expansion across laptop and tablet ecosystems where analog connectivity disappears.
- Standalone Decoders:Discrete board-mounted packages persist in high-fidelity home theater installations where audiophile customers demand swappable component architectures.
- HDMI Decoders:Audio return channel implementations in television and soundbar systems handle multichannel bitstream extraction from video interconnects.
The dominant share belongs to Integrated Decoders, while USB-C Decoders are gaining share fastest as computing OEMs complete jack elimination.
Technology:
Cost tier stratification separates premium licensed object-based codecs from royalty-free pulse-code modulation in price-sensitive industrial applications.
- Dolby Atmos:Object-based spatial audio technology commands premium positioning through proprietary licensing structures that impose fixed per-unit fees. Home theater and automotive segments in the United States absorb these royalties for differentiated user experiences, though margins compress on sub-$50 consumer modules.
- Digital Signal Processing:Programmable DSP architectures enable real-time codec flexibility and room correction algorithms. Professional audio equipment manufacturers in Nashville and London specify these solutions for live sound and studio monitoring where format agility outweighs licensing costs.
- DTS:Multichannel codec family competes in Blu-ray and streaming device implementations with alternative object-based spatial audio capabilities.
- PCM:Uncompressed pulse-code modulation serves as baseline format for industrial and medical audio equipment where latency minimization overrides compression efficiency.
Dolby Atmos captures the premium tier, while Digital Signal Processing is expanding most quickly through software-defined audio architectures.
End User:
Application maturity varies sharply between saturated home theater replacement cycles and automotive immersive audio mandates that compress upgrade timelines.
- Automotive Audio:OEMs embed 16+ channel object-based spatial audio as standard equipment in premium vehicle platforms. Bosch, Harman, and Panasonic Automotive procurement departments in Germany and Japan now specify decoder silicon directly with foundries, bypassing traditional distribution channels.
- Home Theater Systems:Replacement-driven demand concentrates in object-based codec upgrades for existing amplifier and soundbar installations. South Korean and Chinese consumer electronics brands dominate volume shipments through retail and e-commerce channels.
- Professional Audio Equipment:Studio monitors, live sound consoles, and broadcast infrastructure retain RCA and XLR connectivity, fragmenting decoder design requirements.
- Streaming Devices:Set-top boxes and smart television SoCs integrate decoding for multichannel bitstream output to external amplification.
Automotive Audio holds the dominant share, while Streaming Devices show the steepest expansion trajectory through smart television SoC integration.
Distribution Channel:
Customer type bifurcation separates direct tier-1 automotive procurement from retail and e-commerce paths serving consumer and professional segments.
- Direct Sales:Automotive tier-1s and professional audio OEMs negotiate decoder silicon directly with Analog Devices, Qualcomm, and Texas Instruments. Procurement consolidation in Germany and Japan relegates merchant semiconductor vendors to secondary supplier status.
- Online Retail:E-commerce platforms serve audiophile and pro-sumer segments for USB-C dongles, standalone DACs, and home theater components. Amazon and specialized audio retailers in the United States and China dominate this channel.
- Distributors:Arrow Electronics and Avnet maintain inventory for industrial and mid-tier consumer decoder modules where demand fragmentation prevents direct engagement.
- Offline Retail:Brick-and-mortar electronics chains persist in emerging markets where tactile evaluation influences purchase decisions for visible audio components.
Direct Sales commands the dominant share, while Online Retail is climbing the fastest as computing OEMs drive USB-C decoder attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive immersive audio mandates in Germany and Japan diverge sharply from mobile-centric USB-C decoder demand in South Korea and China, creating distinct procurement patterns across major consumption centers.
United States
FCC equipment authorization requirements constrain decoder electromagnetic emissions for automotive and consumer electronics channels. Dolby Laboratories' licensing structure shapes premium-tier pricing for home theater implementations. Austin and San Diego semiconductor design clusters concentrate mixed-signal audio engineering talent for automotive tier-1 suppliers.
Germany
Bosch and Harman procurement departments specify decoder silicon directly with foundries for 16+ channel cabin entertainment systems. The EU Radio Equipment Directive harmonizes electromagnetic compatibility certification across member state markets. Stuttgart and Ingolstadt automotive engineering centers anchor immersive audio integration into premium vehicle platforms.
China
MIIT enforcement of updated GB standards for audio equipment electromagnetic emissions forces decoder redesigns for stricter interference limits. Domestic semiconductor foundries scale mixed-signal audio chip production for local and export markets. Shenzhen and Shanghai consumer electronics manufacturing clusters drive volume shipments of integrated decoder SoCs.
South Korea
Samsung and Apple supply chain specifications drive attach-rate expansion for USB-C decoder dongles across laptop and tablet ecosystems. Domestic semiconductor fabrication capacity expansion loosens foundry allocation constraints for mixed-signal audio chips. Seoul and Suwon electronics manufacturing corridors concentrate decoder silicon packaging and testing operations.
Japan
METI industrial standards influence professional audio equipment decoder specifications for broadcast and studio monitoring applications. Panasonic Automotive procurement consolidates decoder sourcing through direct tier-1 partnerships with foundries. Nagoya and Tokyo acoustic engineering teams dictate component specifications upstream for automotive cabin systems.
Digital Audio Decoders Market Competitive Landscape
Capability concentration sits with precision converter specialists; scale advantage sits with mixed-signal manufacturing giants. The vendor base stratifies across three tiers: integrated platform providers bundling wireless transmission, discrete component specialists serving audiophile segments, and licensing entities controlling proprietary codec standards. Dominant competitive moves include direct automotive tier-1 partnerships that bypass traditional distribution channels, and system-on-chip integration that collapses discrete decoder boundaries into single-silicon solutions.
Within the precision converter tier, Analog Devices anchors high-fidelity professional audio applications through its signal-processing heritage. Qualcomm occupies a position among integrated platform providers, exemplifying the Snapdragon Sound architecture that bundles decoding with wireless transmission. Texas Instruments sits within the scale-driven manufacturing tier, sustaining broad industrial and automotive decoder supply through mixed-signal fabrication capacity. These three represent the structural archetypes reshaping competitive positioning as automotive procurement consolidation and silicon integration accelerate.
| Leading Market Players |
|---|
| Analog Devices |
| Cirrus Logic |
| Qualcomm |
| Realtek Semiconductor |
| STMicroelectronics |
| Texas Instruments |
| Dolby Laboratories |
| Sony Corporation |
| Synopsys |
| Others |
Value Network & Pricing Analysis
Taiwanese and South Korean foundry capacity for mixed-signal audio silicon directly shapes downstream pricing power across decoder tiers, with allocation constraints in advanced nodes compressing margins for fabless vendors while integrated IDMs capture volume premiums.
Pricing Analysis
Geographic price spreads between German automotive procurement and Chinese consumer electronics channels exceed factor-of-three differences for comparable decoder silicon. Three-tier pricing structure across premium, standard, and economy levels separates Dolby-licensed object-based modules from royalty-free PCM implementations and bare-die SoC supply. Cost compression in sub-$50 consumer tiers intensifies because fixed per-unit codec royalties consume disproportionate margin share. Automotive OEMs exhibit least price sensitivity due to cabin audio differentiation mandates, while laptop accessory vendors face acute margin pressure from USB-C dongle commoditization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for decoder hardware sourcing. Taiwan, South Korea, and China anchor mixed-signal fabrication capacity, with 300mm wafer supply for audio-specific nodes drawing from TSMC, Samsung Foundry, and SMIC operations. Silicon substrate, precision analog IP libraries, and advanced packaging substrates constitute critical input dependencies. Single-source vulnerability concentrates in Dolby Laboratories' proprietary codec licensing, which gates premium-tier market access. Distribution runs through direct tier-1 automotive partnerships alongside Arrow and Avnet inventory positions for fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where Dolby's proprietary licensing structure creates regulatory entrenchment that new entrants cannot replicate without years of patent negotiation and certification investment.
For Market Incumbents: Insulate core margin pools by deepening backward integration into mixed-signal fabrication capacity in South Korea or Taiwan, capturing foundry allocation priority before fabless competitors. Secure direct tier-1 automotive partnerships with Bosch, Harman, and Panasonic Automotive to lock out merchant semiconductor vendors from 16+ channel cabin system specifications. Counter USB-C dongle commoditization through software-defined audio subscription architectures that decouple hardware from format evolution revenue. For New Entrants and Emerging Players: Build out white-space positions in India's BIS-simplified certification pathway for mid-tier consumer electronics, where import type-approval acceleration reduces incumbent time-to-market advantages. Target industrial and medical audio equipment segments retaining RCA and XLR connectivity, where legacy interface fragmentation prevents incumbent SoC optimization and creates design service opportunities. Pursue foundry partnerships with domestic Chinese semiconductor fabrication expansion to serve MIIT GB-standard compliance demand with localized supply. For Investors and Strategic Acquirers: Long-term, this sits as a licensing-arbitrage play because Dolby's fixed-royalty structure compresses margins at volume while creating acquisition premiums for vendors with alternative codec portfolios or captive patent positions. Favor targets with automotive software-defined audio capabilities and direct OEM relationships over consumer-facing discrete component specialists. Monitor South Korean foundry utilization rates as the inflection signal: allocation tightening precedes pricing power shifts toward integrated IDMs and away from fabless design houses.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Tier-1 Direct Partnership | Bosch and Harman procurement consolidation bypasses distribution, locking decoder silicon specifications upstream. |
| System-on-Chip Integration | Single-silicon solutions combining decoding, amplification, and wireless baseband collapse discrete vendor addressable markets. |
| Software-Defined Audio Platform | Over-the-air codec updates enable subscription monetization at Mercedes-Benz and BMW cabin entertainment divisions. |
| Dual Certification Pre-Compliance | Simultaneous FCC and MIIT GB testing maintains cross-border shipment flexibility for Shenzhen manufacturing clusters. |
| USB-C Dongle Attach-Rate Expansion | Samsung and Apple supply chain specifications drive laptop and tablet ecosystem penetration as 3.5mm jacks disappear. |
Research Methodology
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings across the decoder value chain. Semiconductor design executives at Analog Devices, Qualcomm, and Texas Instruments provided fabrication capacity and automotive procurement intelligence. Tier-1 supplier procurement managers at Bosch and Harman detailed direct sourcing consolidation patterns. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard publications, EU Radio Equipment Directive harmonization texts, and SEC 10-K disclosures from listed semiconductor vendors. Bottom-up decoder shipment estimates by product configuration triangulate against top-down automotive content-per-vehicle and consumer electronics attach-rate assumptions.
Calibration against historical foundry utilization data and automotive platform rollout schedules shapes the projection framework. Segmentation dimensions span product architecture, codec technology licensing tier, end-use application maturity, and regional certification regime. CAGRs derive from unit shipment trajectories weighted by average selling price evolution across integrated, USB-C, standalone, and HDMI decoder configurations. Dolby royalty rate structures and South Korean fabrication capacity expansion curves constitute industry-specific forecast inputs.
Sensitivities concentrate around MIIT enforcement intensity for GB electromagnetic emissions standards and automotive OEM software-defined audio adoption velocity. Forecasts embed assumptions regarding foundry allocation continuity and codec licensing negotiation outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fluorite Market
Others
Reusable Wine Bags Market
Others
France Smart Home Market
Others
Advertising Intelligence Solution Market
Others
Content Experience Platforms Market
Others
Food Technology Market
Others
Global Learning Analytics Market
Others
Tanned Fish Skin Leather Market
Others
Shear Testing Equipment Market
Others
Embedded Computer Market
Others
Indoor LBS Market
Others
Global Hardware Acceleration Market
Others
Lychee Market
Others
AC Switchgear Market
Others
North America Flexographic Printing Market
Others
Asia Pacific Video Conferencing Hardware Market