
 Digital Education Projector Market | 2026-2036
Digital Education Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Education Projector Market Insights
Subscription-based lamp-replacement and remote diagnostics is expanding what institutions pay for beyond hardware. Epson leverages its captive supply of precision optics to dominate replacement cycles in North American districts. BenQ sustains competitive positioning through specialized short-throw geometries purpose-built for cramped classrooms. Sony anchors premium positioning in higher-education auditoriums with native 4K resolution and extended color-gamut calibration.
A digital education projector converts electrical signals into magnified visible light using solid-state or lamp-based illumination engines, typically outputting between 2,000 and 6,000 lumens for legible projection in ambient-lit rooms. LCD and DLP technologies occupy distinct performance tiers, with DLP commanding faster response times for video content while LCD preserves color accuracy for static instructional material. Ultra short throw installations are capturing margin pools in retrofit-heavy K-12 environments where ceiling infrastructure is absent. Portable units serve the fastest-growing segment among mobile STEM labs and pop-up corporate training facilities.
FCC equipment authorization and EU RoHS substance restrictions shape which lamp chemistries and power-supply architectures enter their respective markets. India's BIS compulsory registration scheme filters out uncertified imports, channeling procurement toward tested lumen and safety specifications. China's GB standards for classroom lighting and visual health impose minimum contrast ratios that manufacturers must engineer around. Stakeholders should monitor how energy-efficiency mandates from these regulators recalibrate total-cost-of-ownership calculations against upfront hardware pricing.
Market Dynamics
Laser-phosphor illumination is compressing replacement cycles and recalibrating total-cost-of-ownership calculations across institutional procurement offices. This solid-state technology eliminates lamp degradation curves while reducing thermal management requirements in ceiling-mounted installations.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic assembly incentives are accelerating interactive classroom deployments in K-12 schools across Maharashtra and Gujarat.
- Laser-phosphor illumination engines:These solid-state systems deliver 20,000-hour operational lifespans without lumen depreciation, reducing maintenance staffing burdens in under-resourced districts.
- China's GB standards for classroom visual health:Municipal education bureaus in tier-one cities mandate minimum contrast ratios that only mid-lumen laser projectors reliably achieve.
Market Restraints
- Precision optics supply concentration:Japanese and German glass-molding facilities control aspheric lens element production, creating single-source vulnerability for short-throw geometries.
- Rare-earth phosphor cost volatility:Cerium-doped yttrium aluminum garnet prices fluctuate with Chinese export quota adjustments, pressuring laser-engine bill-of-materials.
- EU RoHS substance restrictions:Mercury-containing high-pressure lamp architectures face phased elimination timelines, forcing accelerated R&D recoupment on laser alternatives.
Strategic Opportunities
- Subscription-based remote diagnostics:Cloud-connected projector fleets enable predictive failure alerting and automated brightness calibration, creating recurring revenue streams beyond hardware margins.
- Mobile STEM lab deployments:Battery-powered portable units serve pop-up corporate training facilities and rural outreach programs lacking fixed infrastructure.
- Ultra short throw retrofit penetration:Wall-mounted installations bypass ceiling infrastructure requirements in aging K-12 buildings across the American Midwest and Northeast corridors.
Industry Challenges
- Colorimetric calibration expertise scarcity:Extended color-gamut tuning for higher-education auditorium installations requires specialized technicians unavailable in secondary markets.
- FCC equipment authorization timelines:RF emissions testing for wireless presentation functionality delays product launches by four to six months in North American distribution channels.
- Legacy ceiling mount incompatibility:Existing infrastructure from lamp-era installations conflicts with laser-phosphor thermal dissipation requirements, forcing complete hardware replacement rather than engine swaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Education Projector Market |
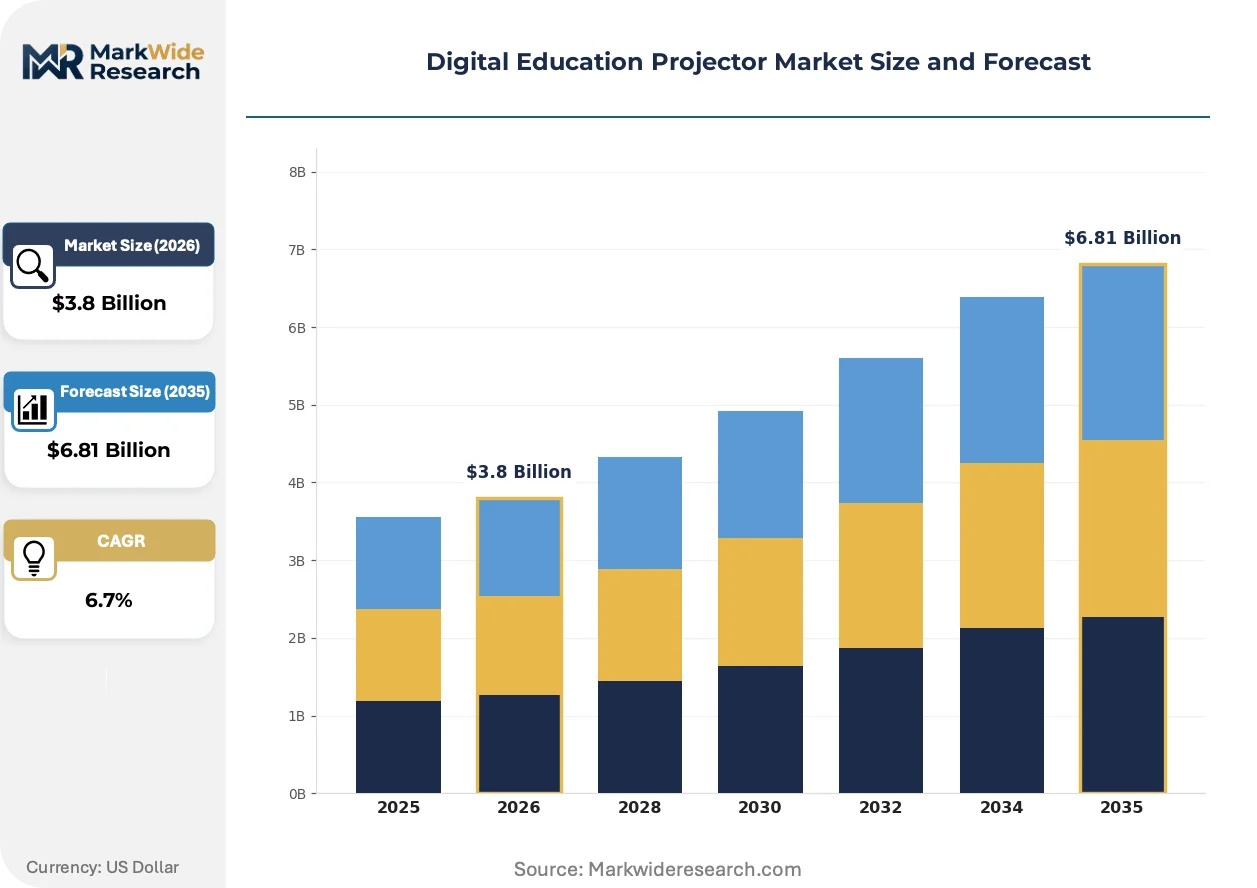
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Throw, Ultra Short Throw, Portable, Fixed Installation Technology: LCD, DLP, LED, LCoS End User: K-12 Schools, Higher Education, Corporate Training, Public Libraries Installation Type: Ceiling Mounted, Tabletop, Wall Mounted, Mobile Stand |
| Companies Covered | Epson, BenQ, Sony, ViewSonic, Optoma, Panasonic, Dell, Christie Digital Systems, InFocus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Education Projector Market Trends and Innovations
Institutional procurement offices are renegotiating vendor relationships around service-level agreements rather than capital expenditure schedules. This shift compresses hardware commoditization pressures while elevating software-integrated ecosystem stickiness.
Hybrid laser-LED illumination is integrating dynamic dimming algorithms with ambient light sensors to maintain perceived contrast in variable classroom conditions. University technology departments in California and Texas are piloting these adaptive systems for lecture-capture compatibility. The architecture is integrating real-time brightness adjustment that extends effective lumens-per-watt performance without manual intervention.
China's GB standards for classroom lighting and visual health are mandating blue-light hazard testing and flicker-free certification thresholds that exceed IEC baseline requirements. Domestic manufacturers in Shenzhen and Suzhou are re-engineering driver electronics to eliminate high-frequency modulation artifacts. Higher-education procurement offices in Beijing and Shanghai now require third-party ophthalmological safety documentation alongside traditional lumen specifications.
Leasing arrangements with bundled lamp-replacement guarantees are displacing outright purchase models in North American K-12 districts facing capital budget freezes. Distributors in Texas and Florida are restructuring compensation around multi-year service contracts rather than unit shipment volumes. This transformation is most visible in Title I school systems where federal stimulus allocations must demonstrate measurable student outcome improvements rather than infrastructure depreciation schedules.
Digital Education Projector Market Segmentation
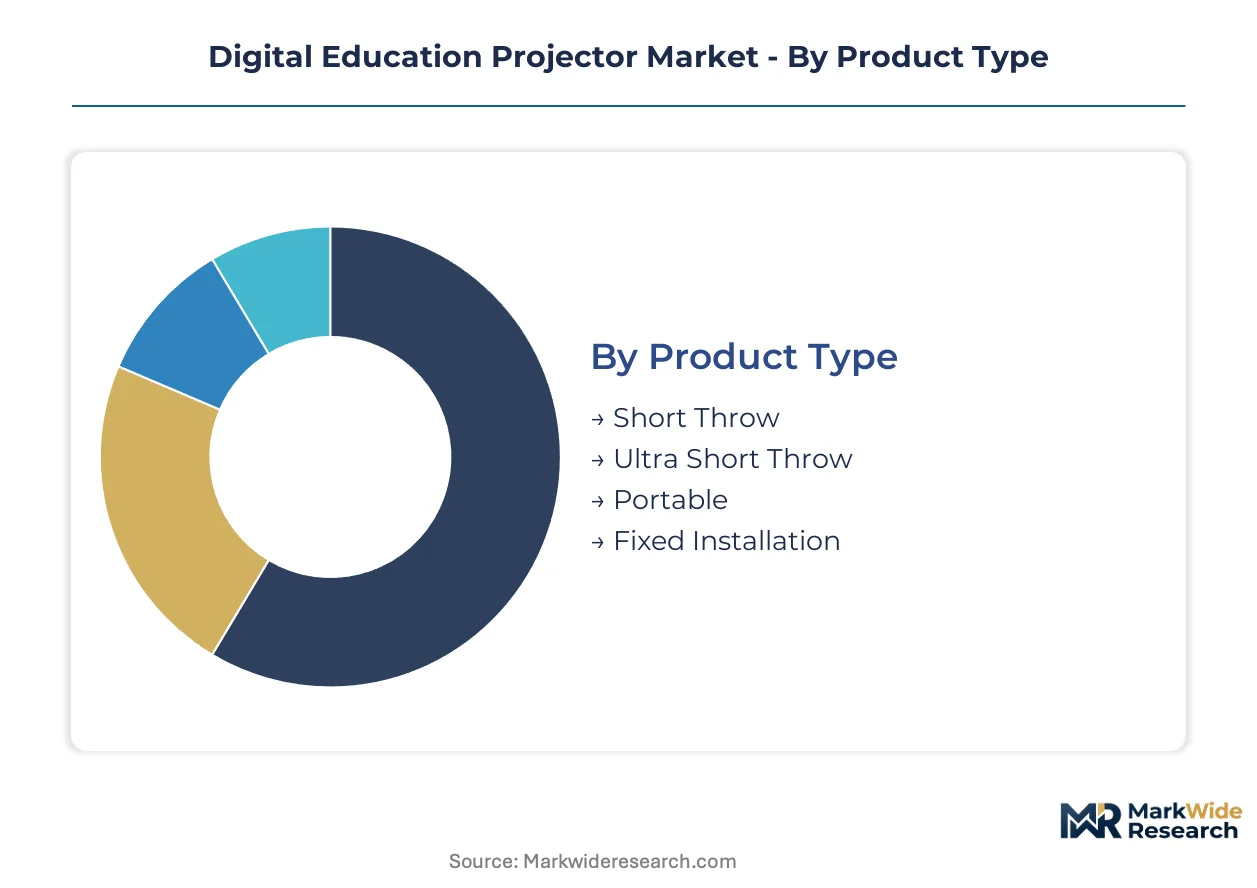
Institutional procurement offices segment projector purchases by physical installation constraints, illumination technology, and end-user environment. These dimensions determine maintenance staffing requirements, total-cost-of-ownership calculations, and compliance with regional classroom lighting mandates.
Product Type:
Optical engine supply concentrates in Japanese and German precision glass-molding facilities, with short-throw geometries commanding premium aspheric lens element allocation.
- Short Throw:Projection ratios between 0.4 and 1.0 enable front-of-room placement without instructor shadow interference. Demand clusters in American Midwest K-12 retrofits where ceiling infrastructure is absent and wall-mounting avoids asbestos abatement costs.
- Ultra Short Throw:Sub-0.4 throw ratios project 100-inch images from inches away, eliminating presenter shadows entirely. Municipal education bureaus in China's tier-one cities mandate these for GB standard compliance on minimum contrast ratios in ambient-lit classrooms.
- Portable:Battery-powered units below 10 pounds serve mobile STEM labs and rural outreach programs lacking fixed infrastructure.
- Fixed Installation:Hardwired ceiling or wall mounts dominate higher-education auditoriums requiring integrated control systems and lecture-capture compatibility.
Today's leader: Ultra Short Throw. Tomorrow's challenger: Portable.
Technology:
Cost tiers separate liquid-crystal modulation from solid-state alternatives, with laser-phosphor engines recalibrating depreciation schedules across institutional budgets.
- LCD:Three-panel liquid-crystal arrays preserve color accuracy for static instructional material and whiteboard capture. Higher-education procurement offices in California and Texas specify these for art history and medical imaging curricula where gamut fidelity outweighs motion performance.
- DLP:Single-chip digital micromirror devices deliver faster response times for video content and 3D visualization. K-12 districts in Florida and Texas favor these for STEM animation and virtual dissection applications.
- LED:Solid-state RGB illumination eliminates lamp replacement but limits brightness output to sub-4,000 lumen ranges suitable for small conference rooms.
- LCoS:Liquid crystal on silicon bridges LCD color accuracy with DLP contrast ratios at premium price points, anchoring niche positioning in museum and planetarium education wings.
Volume concentrates in DLP. Margin expansion centers on LCoS.
End User:
Application requirements diverge sharply between K-12 durability demands and higher-education performance specifications, with corporate training occupying a volatile middle tier.
- K-12 Schools:Ruggedized chassis and sealed optical blocks withstand daily classroom use by non-technical staff. India's PLI scheme accelerates interactive whiteboard bundle deployments across Maharashtra and Gujarat state school systems.
- Higher Education:Native 4K resolution and extended color-gamut calibration support auditorium-scale lecture capture and research presentation. Beijing and Shanghai procurement offices now require third-party ophthalmological safety documentation alongside lumen specifications.
- Corporate Training:Hybrid laser-LED illumination with ambient light sensors serves pop-up facilities and leased office spaces with variable lighting conditions.
- Public Libraries:Entry-lumen fixed installations with extended warranty terms dominate community education room budgets.
Replacement cycle revenue anchors in K-12. Specification escalation drives higher education.
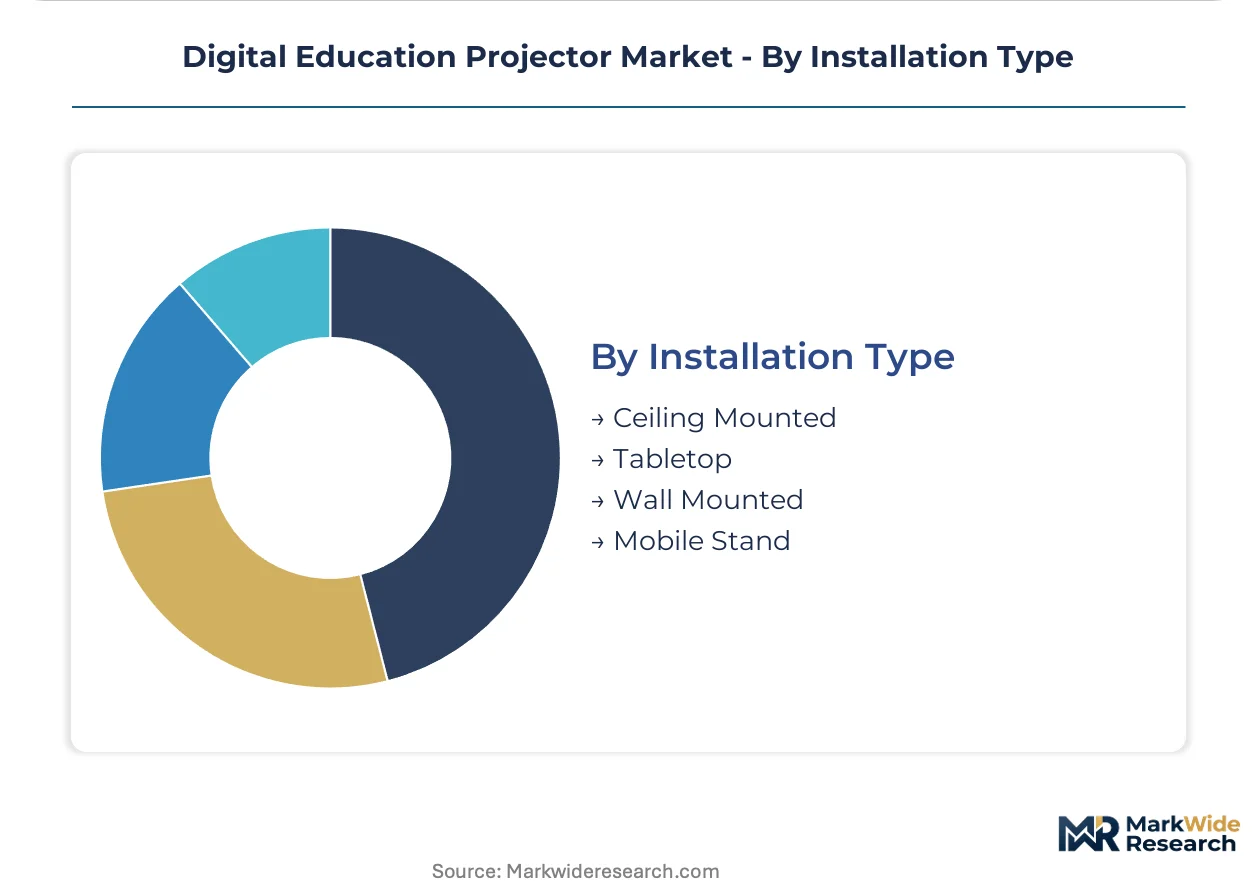
Installation Type:
Customer type determines infrastructure investment appetite, with ceiling-mounted systems requiring facilities coordination that tabletop alternatives bypass.
- Ceiling Mounted:Suspended installations optimize viewing angles in permanent classrooms but require structural assessment and electrical routing. Legacy mounts from lamp-era installations often conflict with laser-phosphor thermal dissipation requirements, forcing complete hardware replacement.
- Tabletop:Flexible placement suits multi-purpose rooms and temporary deployments, though presenter positioning risks shadow interference and theft exposure.
- Wall Mounted:Ultra short throw projectors integrate with interactive whiteboards at instructor eye level, eliminating ceiling infrastructure needs in aging American Northeast school buildings.
- Mobile Stand:Rolling carts with integrated power and source switching enable rapid room reconfiguration for professional development and parent engagement events.
Retrofit penetration favors Wall Mounted. Infrastructure-new builds prefer Ceiling Mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting projector assembly toward jurisdictions where India's PLI scheme and China's GB standard enforcement create divergent cost-of-compliance profiles for manufacturers.
United States
K-12 districts in Texas and Florida are restructuring procurement around multi-year service contracts with bundled lamp-replacement guarantees. FCC equipment authorization timelines for wireless presentation functionality delay product launches by four to six months. Epson leverages its captive supply of precision optics to dominate replacement cycles in North American districts.
China
Municipal education bureaus in Beijing and Shanghai mandate multimedia infrastructure upgrades with minimum contrast ratios that only mid-lumen laser projectors achieve. GB standards for classroom lighting and visual health impose blue-light hazard testing exceeding IEC baselines. Domestic manufacturers in Shenzhen and Suzhou are re-engineering driver electronics to eliminate high-frequency modulation artifacts.
India
Maharashtra and Gujarat state school systems are scaling interactive whiteboard bundle deployments under the PLI scheme for electronics manufacturing. BIS compulsory registration filters out uncertified imports, channeling procurement toward tested lumen specifications. Laser-phosphor engines with 20,000-hour lifespans reduce maintenance staffing burdens in under-resourced districts.
Germany
Higher-education procurement offices specify extended color-gamut calibration for art history and medical imaging curricula. EU RoHS substance restrictions force phased elimination of mercury-containing high-pressure lamp architectures. Precision glass-molding facilities in Baden-Württemberg control aspheric lens element production for short-throw geometries.
Japan
METI efficiency mandates recalibrate total-cost-of-ownership calculations against upfront hardware pricing in institutional budgets. Japanese glass-molding facilities face single-source vulnerability pressure as demand concentrates for ultra short throw retrofit installations. Domestic manufacturers anchor premium positioning in higher-education auditoriums with native 4K resolution systems.
Digital Education Projector Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with optical engine supply concentrating in Japanese and German precision glass-molding facilities. The vendor base organizes around three archetypes: captive optics integrators, specialized short-throw geometry developers, and premium auditorium-scale system providers. Competitive moves center on backward integration into lens element production and technology licensing arrangements for solid-state illumination engines.
Among Japanese precision optics specialists, Epson and Sony exemplify the captive supply archetype, while BenQ represents specialized short-throw positioning. These companies anchor distinct competitive vectors without overlapping segment focus.
| Leading Market Players |
|---|
| Epson |
| BenQ |
| Sony |
| ViewSonic |
| Optoma |
| Panasonic |
| Dell |
| Christie Digital Systems |
| InFocus |
| Others |
Pricing and Supply Chain Analysis
Precision optics technicians concentrated in Baden-Württemberg and Osaka prefectures command wage premiums that propagate through projector bill-of-materials, widening spreads between entry-lumen portable units and native 4K auditorium systems. Labor-cost differentials between Japanese glass-molding facilities and emerging assembly operations in Gujarat amplify tier separation in institutional procurement budgets.
Pricing Analysis
Capacity additions in India's PLI-certified assembly corridors are reshaping price floors for K-12 interactive bundles. Three-tier pricing structure across premium, standard, and economy levels separates laser-phosphor auditorium installations from lamp-based classroom retrofits and battery-powered portable units. Price differentiation hinges on GB standard compliance certification and bundled remote diagnostics service levels. Cost compression in economy-tier LCD projectors intensifies as domestic Indian manufacturers scale output, while higher-education buyers in Beijing and Shanghai exhibit lowest price sensitivity due to ophthalmological safety mandates.
Supply Chain Analysis
Certification gating through BIS compulsory registration and FCC equipment authorization filters component sourcing toward qualified optics suppliers. Manufacturing concentrates in Japan, Germany, and China, with aspheric lens elements drawing from Baden-Württemberg glass-molding facilities and driver electronics sourcing from Shenzhen and Suzhou. Rare-earth phosphor supply rests on Chinese export quota adjustments for cerium-doped yttrium aluminum garnet. Single-source vulnerability in precision optics creates chokepoint exposure. Distribution runs through regional AV integrators and education-technology distributors with municipal procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI assembly incentives and China's GB standard enforcement creates divergent cost-of-compliance profiles that reward flexible manufacturing footprints. Regulatory divergence in certification timelines and substance restrictions separates viable market entry corridors.
For Market Incumbents: To counter rare-earth phosphor cost volatility and precision optics supply concentration, incumbents should secure captive supply of aspheric lens elements through backward integration into Baden-Württemberg glass-molding partnerships. Parallel investment in laser-phosphor engine R&D accelerates mercury-lamp phase-out ahead of EU RoHS elimination timelines, converting replacement-cycle revenue into service-contract annuities. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for domestic assembly of ultra short throw projectors targeting Maharashtra and Gujarat state school systems. White-space concentration sits in battery-powered portable units for mobile STEM labs and rural outreach programs lacking fixed infrastructure. Go-to-market execution should anchor on BIS pre-certification and bundled interactive whiteboard partnerships with state education bureaus. For Investors and Strategic Acquirers: Optical component specialists are the most active acquirer in this space, seeking vertical integration into illumination engine supply. Long-term viability centers on recurring revenue share from subscription diagnostics and lamp-replacement guarantees displacing transactional hardware sales. Acquisition target archetype: regional AV integrators with locked municipal education contracts and service infrastructure. Signal to monitor: GB standard expansion into tier-two Chinese cities triggering specification escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Captive lens supply secures margin control against Japanese and German glass-molding bottlenecks. |
| Laser-Phosphor Engine R&D Scale-Up | 20,000-hour solid-state lifespans convert maintenance burdens into recurring service revenue streams. |
| PLI-Certified Assembly Expansion | Domestic Indian production unlocks state-level K-12 procurement channels under BIS registration. |
| Subscription Diagnostics Platform Launch | Cloud-connected fleets enable predictive failure alerting and automated brightness calibration. |
| GB Standard Pre-Certification Investment | Third-party ophthalmological documentation meets Beijing and Shanghai municipal mandates. |
Research Methodology
Bottom-up K-12 and higher-education procurement modeling reconciled against top-down optical engine and illumination component supply tracking forms the analytical core of this study. Primary interviews with district technology directors, university AV procurement officers, precision optics manufacturing engineers, and education-technology distributors combined with secondary validation from BIS registration databases, FCC equipment authorization filings, and municipal education bureau procurement disclosures. Triangulation across stakeholder inputs and trade data ensures segment-level consistency.
Historical trendline analysis of institutional replacement cycles and illumination technology transitions informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type (short throw, ultra short throw, portable, fixed installation), technology (LCD, DLP, LED, LCoS), end user (K-12, higher education, corporate training, public library), and installation type (ceiling mounted, tabletop, wall mounted, mobile stand). CAGRs derived from weighted average of technology diffusion curves and regulatory mandate implementation schedules, with specific inputs from PLI scheme uptake rates and GB standard enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth export quota disruptions or accelerated EU RoHS phase-out schedules. Model outputs reflect assumptions on laser-phosphor cost-down trajectories and municipal education infrastructure budget continuity. A model refresh is warranted upon material change in India's PLI scheme eligibility criteria or China's GB standard tier expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Sportswear Market
Others
Plastic Films and Sheets Market
Others
Delumper Market
Others
DIY Smart Home Market
Others
Solar Panel Testers Market
Others
3D Printing Construction Market
Others
Global Human Augmentation Market
Others
Cellular-Connected Laptops Market
Others
Hopper Dryers Market
Others
Global Aircraft Lighting Systems Market
Others
Vacuum Evaporators Market
Others
North America Automotive LED Lighting Market
Others
United States Indoor LBS Market
Others
Gesture Recognition for Smart TV Market
Others
Water and Waste Water Treatment Chemicals Market
Others
North America Smart Homes Market