
 Nutricosmetics Market | 2026-2036
Nutricosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Nutricosmetics Market Analysis
Collagen peptides is hardening as the dominant active ingredient, displacing simpler vitamin complexes in premium nutricosmetic formulations. Amway leverages its direct-selling infrastructure across Asia-Pacific to sustain volume leadership in nutritional supplements. Nestlé anchors its position through R&D intensity in functional beverages, while Shiseido competes on brand heritage in skin care edibles.
Nutricosmetics comprise ingestible products containing bioactive compounds designed to enhance skin, hair, and nail appearance through systemic delivery, typically formulated with hydrolyzed collagen peptides at 2,000–10,000 daltons molecular weight for optimal absorption. The segment generates commercial value by bridging dermatology and nutrition science, targeting consumers seeking non-topical beauty interventions. Nutritional supplements capture the largest margin pool due to higher per-unit pricing and subscription retention models, while functional beverages represent the fastest-growing category as convenience-oriented younger consumers prioritize ready-to-drink formats. Collagen dominates ingredient-type value, though antioxidants are gaining traction in anti-aging positioning across pharmacies and online retail channels.
The US FDA exercises oversight through dietary supplement GMPs and structure-function claim limitations, while EFSA in Europe evaluates health claims under the Nutrition and Health Claims Regulation, creating divergent market access requirements. Japan's Ministry of Health, Labour and Welfare maintains a distinct Foods with Function Claims system that permits specific efficacy labeling unavailable in other major markets. Stakeholders must monitor evolving substantiation standards for collagen bioavailability claims as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
The European Union's Novel Food Regulation is compressing ingredient approval timelines for ingestible beauty formulations, forcing reformulation cycles that favor established suppliers with dossier-ready collagen peptide portfolios over emerging botanical entrants.
Growth Catalysts
- Japan's Foods with Function Claims system:The MHLW framework permits specific efficacy labeling for collagen bioavailability that remains unavailable in FDA-regulated or EFSA-supervised markets, creating a regulatory arbitrage incentive for clinical substantiation investment.
- Urban millennial women:This demographic cluster in Tokyo, Seoul, and Shanghai is normalizing daily collagen consumption as a skincare routine replacement, driving subscription retention models that stabilize manufacturer revenue visibility.
- Hydrolyzed peptide processing:Enzymatic hydrolysis at controlled molecular weights between 2,000 and 10,000 daltons is unlocking dermal absorption claims that simpler gelatin formulations cannot support, elevating premium positioning.
Market Restraints
- Marine collagen supply concentration:Wild-caught fish scale and skin sourcing clusters in Southeast Asian coastal processing zones, exposing finished goods manufacturers to El Niño-driven catch volatility and sustainability audit failures.
- EFSA health claim substantiation:The 2012 rejection of collagen-specific skin elasticity claims under EU Regulation 1924/2006 forces European marketers into vague "beauty from within" positioning that dilutes price premiums against Japanese competitors.
- Bovine-derived peptide substitution threat:Religious dietary restrictions and prion disease concerns in Middle Eastern and South Asian markets push demand toward porcine or marine alternatives with constrained supply elasticity.
Strategic Opportunities
- Vietnam and Indonesia pharmacy channel penetration:These markets currently exhibit minimal nutricosmetic shelf space relative to skincare, creating first-mover advantage for brands establishing dermatologist endorsement networks before local competitors consolidate.
- Ready-to-drink functional beverage formats:Collagen-infused sparkling waters and shelf-stable shots address convenience gaps in morning consumption occasions that powder sachets and capsule regimens fail to capture.
- Convergence of microbiome science with dermatology:Synbiotic formulations pairing collagen peptides with targeted probiotic strains are opening gut-skin axis positioning that transcends commodity peptide competition.
Industry Challenges
- Clinical trial design complexity:Demonstrating statistically significant wrinkle depth reduction via oral collagen requires six-month intervention periods and standardized photography protocols that extend R&D timelines beyond typical supplement development cycles.
- Cross-border e-commerce compliance fragmentation:Direct-to-consumer shipments face divergent customs classifications—dietary supplement versus cosmetic food—across ASEAN member states, creating fulfillment network complexity and duty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutricosmetics Market |
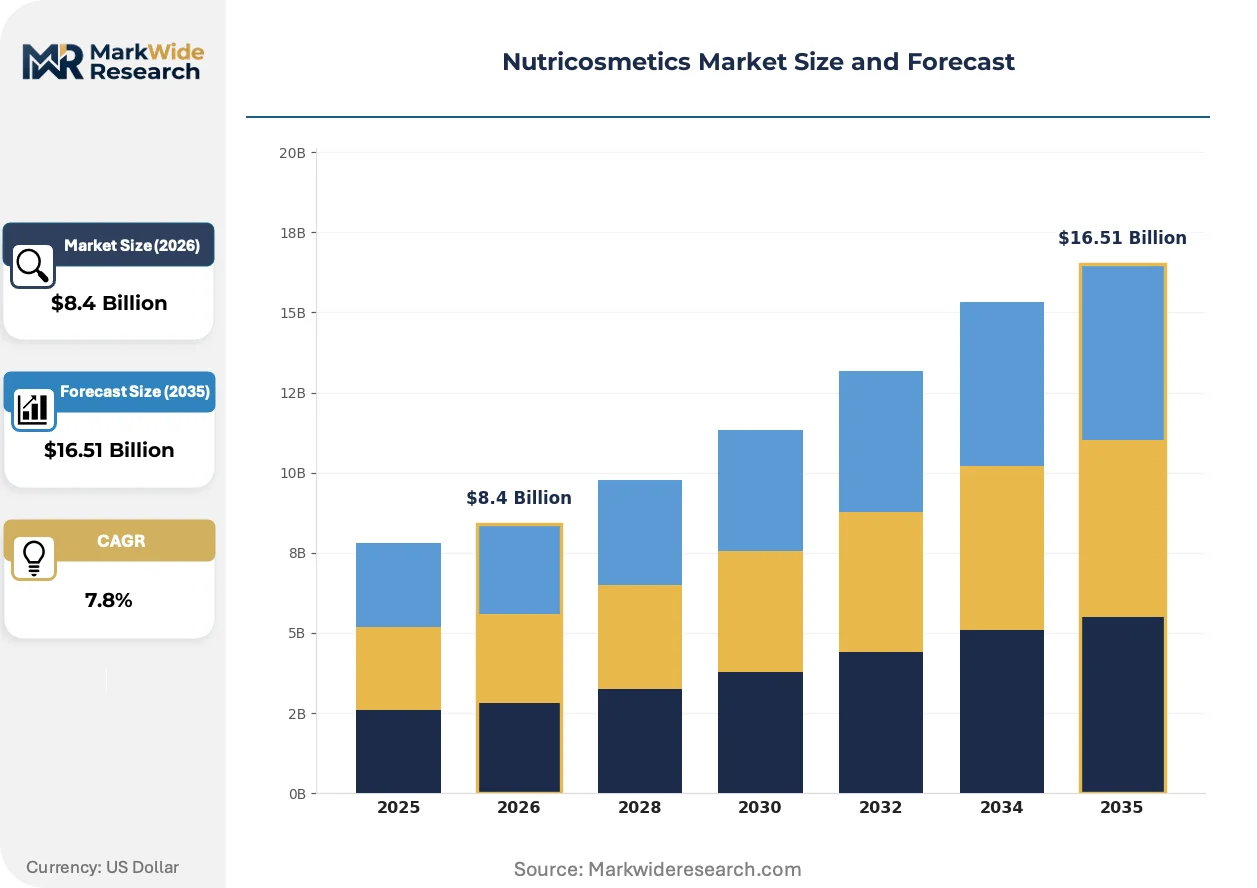
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Beverages, Nutritional Supplements, Skin Care Edibles, Hair Care Edibles Ingredient Type: Vitamins, Minerals, Antioxidants, Collagen Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores End User: Women, Men, Elderly, Athletes |
| Companies Covered | Amway, Nestlé, Herbalife Nutrition, Shiseido, Suntory Holdings, GNC Holdings, Vitabiotics, Koninklijke DSM, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutricosmetics Market Emerging Trajectories
Biotechnology-enabled ingredient precision is collapsing the traditional boundary between nutritional science and cosmetic efficacy, enabling systemic delivery mechanisms that topical formulations cannot replicate.
Microencapsulation technology using liposomal or alginate shell structures is protecting collagen peptides from gastric degradation, enabling targeted release in the small intestine where amino acid absorption peaks. Premium brands in Japan and South Korea are adopting this delivery innovation to justify 40-60% price premiums over standard hydrolyzed powders. The technology is electrifying competitive positioning by transforming bioavailability from a marketing claim into a measurable pharmacokinetic differentiator.
EFSA's ongoing evaluation of collagen-specific health claims under the Nutrition and Health Claims Regulation is tightening evidentiary standards for European market access. Manufacturers must now submit human intervention studies with validated dermatological endpoints rather than relying on in-vitro enzymatic assays. This regulatory pressure is compressing the European supplier base toward firms with dedicated clinical research budgets, excluding smaller botanical entrants lacking trial infrastructure.
Subscription-based replenishment models are displacing traditional pharmacy and department store purchasing for core collagen users. Direct-to-consumer platforms in urban China and the United States are capturing recurring revenue through personalized dosage algorithms and skin assessment apps that lock in twelve-month commitments. This channel shift is most visible in Shanghai and Shenzhen, where Tmall flagship stores now generate majority revenue for established Japanese nutricosmetic brands.
Nutricosmetics Market Segmentation
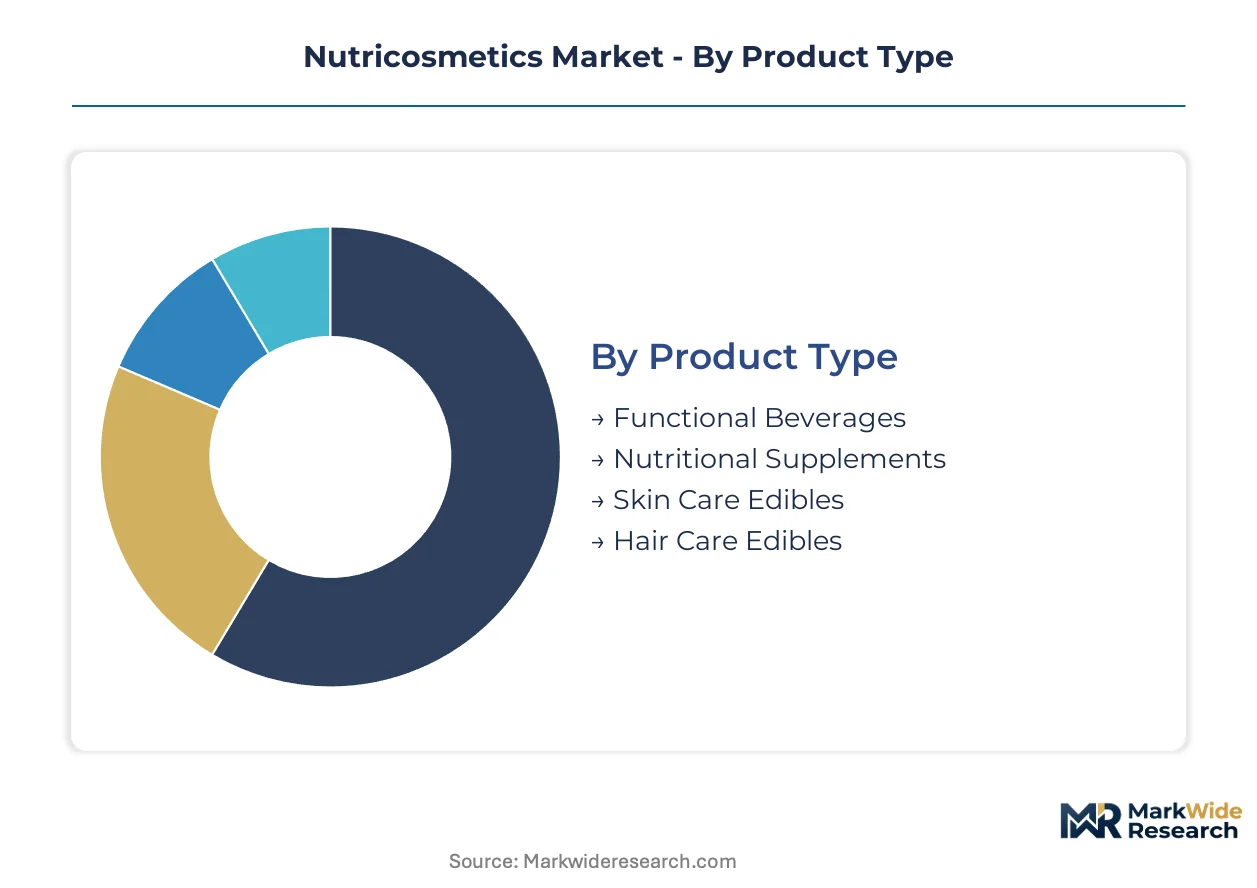
Segmentation in nutricosmetics separates convenience-driven formats from clinical-positioned regimens, with each cluster demanding distinct supply chain configurations and regulatory navigation strategies. Manufacturers must align peptide molecular weight specifications and delivery mechanisms to the consumption occasion each segment targets.
Product Type:
Volume concentrates in powder and capsule formats, while premium positioning clusters in ready-to-drink innovations that command shelf-space negotiations with beverage distributors.
- Functional Beverages:Collagen-infused waters, shots, and sparkling formulations leverage enzymatic hydrolysis for rapid absorption claims. Demand clusters in Tokyo, Seoul, and Shanghai among urban millennial women replacing morning skincare routines with grab-and-go consumption. Convenience positioning captures younger demographics unwilling to maintain powder-mixing regimens.
- Nutritional Supplements:Capsules, tablets, and powder sachets deliver standardized peptide doses with clinical substantiation backing. Subscription retention models in Japan and the United States stabilize manufacturer revenue visibility through twelve-month commitments. Efficacy labeling permitted under Japan's Foods with Function Claims system creates pricing power unavailable in FDA-regulated markets.
- Skin Care Edibles:Gummies and chewables targeting beauty-from-within positioning with flavor-masked formulations.
- Hair Care Edibles:Biotin-enriched supplements addressing nail and hair strength through keratin support mechanisms.
Today's leader: Nutritional Supplements. Tomorrow's challenger: Functional Beverages.
Ingredient Type:
Marine and bovine peptide sourcing geography determines cost structure, with wild-caught supply concentration in Southeast Asian coastal zones creating volatility exposure.
- Collagen:Hydrolyzed peptides at 2,000–10,000 daltons molecular weight optimize dermal absorption claims through controlled enzymatic processing. Japanese and South Korean manufacturers dominate premium positioning by investing in clinical substantiation for bioavailability. EFSA's rejection of skin elasticity claims under EU Regulation 1924/2006 forces European marketers into vague positioning that cedes price premium capture to Japanese competitors.
- Antioxidants:Polyphenol complexes and carotenoid formulations target oxidative stress reduction with dermatological endpoint validation. Pharmacy channel penetration in Vietnam and Indonesia creates first-mover advantage for brands establishing dermatologist endorsement networks before local consolidation.
- Vitamins:Standardized complexes delivering biotin, vitamin C, and vitamin E for baseline beauty support.
- Minerals:Zinc and selenium formulations supporting keratin synthesis and cellular repair mechanisms.
Collagen commands current value concentration. Antioxidants are climbing the fastest as anti-aging positioning intensifies across pharmacy and online retail channels.
Distribution Channel:
Direct-to-consumer platforms are displacing traditional retail, with personalized dosage algorithms and skin assessment apps locking in recurring revenue commitments.
- Online Retail:Tmall flagship stores in Shanghai and Shenzhen now generate majority revenue for established Japanese brands through subscription-based replenishment models. Cross-border e-commerce faces divergent customs classifications across ASEAN member states, creating fulfillment network complexity and duty exposure for direct-to-consumer shipments.
- Pharmacies:Dermatologist endorsement networks in Vietnam and Indonesia offer first-mover advantage before local competitors consolidate shelf space. Professional channel credibility supports premium pricing against mass-market alternatives.
- Supermarkets:Mass-market penetration for entry-level vitamin complexes and standardized peptide formulations.
- Health Stores:Specialty retail targeting wellness-focused consumers with curated ingredient transparency.
Online Retail is capturing share fastest from pharmacy incumbents as subscription algorithms deepen consumer lock-in.
End User:
Gender-skewed demand concentrates in female demographics, with male positioning emerging through athletic performance and grooming convergence.
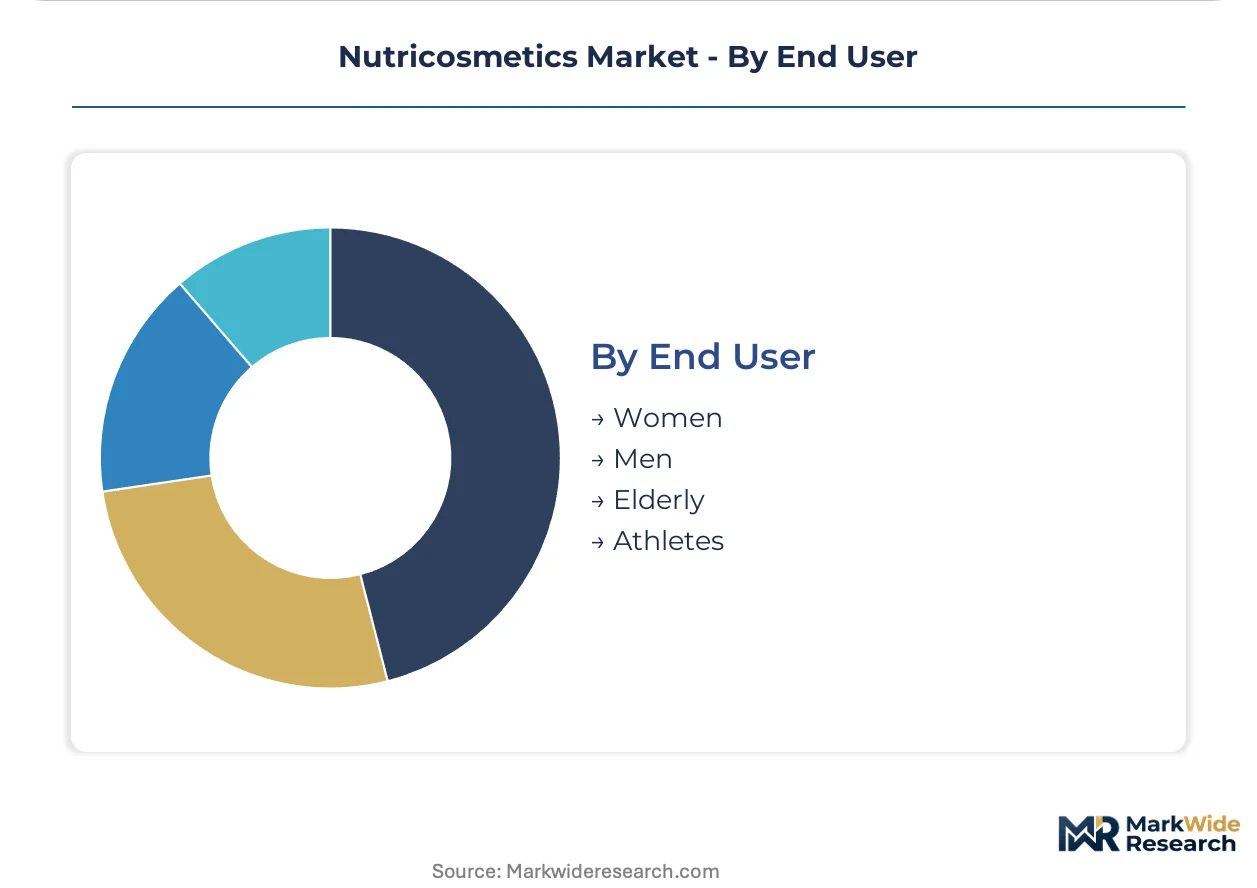
- Women:Urban millennial clusters in Tokyo, Seoul, and Shanghai normalize daily collagen consumption as skincare routine replacement. Subscription retention models stabilize manufacturer revenue visibility through personalized dosage algorithms and skin assessment applications.
- Athletes:Recovery and joint support positioning leverages peptide formulations for connective tissue repair claims. Functional beverage formats address post-workout consumption occasions that traditional supplement regimens fail to capture.
- Men:Emerging segment targeting grooming and wellness convergence with understated packaging and performance positioning.
- Elderly:Joint mobility and skin hydration formulations addressing age-related collagen depletion.
Women anchor current volume. Athletes represent the steepest expansion trajectory as sports nutrition and beauty positioning converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors nutricosmetics demand through decades of consumer trust in beauty-from-within formulations. The analysis spans five countries where regulatory frameworks and urban consumption patterns create distinct market access conditions.
Japan
Urban millennial women in Tokyo and Osaka normalize daily collagen consumption as skincare routine replacement. The Ministry of Health, Labour and Welfare's Foods with Function Claims system permits specific efficacy labeling unavailable elsewhere. Shiseido and Suntory Holdings leverage this regulatory arbitrage to command premium positioning through clinical substantiation investment.
United States
Subscription-based replenishment models through direct-to-consumer platforms capture recurring revenue in New York and Los Angeles. The FDA exercises oversight through dietary supplement GMPs and structure-function claim limitations. Silicon Valley and Manhattan host the algorithmic personalization infrastructure driving twelve-month consumer commitments.
China
Tmall flagship stores in Shanghai and Shenzhen now generate majority revenue for established Japanese brands. The National Medical Products Administration evaluates cross-border e-commerce classifications that create fulfillment complexity. Yangtze River Delta urban clusters concentrate demand for ready-to-drink functional beverage formats.
South Korea
Seoul's beauty ecosystem integrates nutricosmetics into multi-step skincare regimens through pharmacy and online retail channels. The Ministry of Food and Drug Safety maintains distinct substantiation standards for collagen bioavailability claims. Gangnam district retail networks anchor premium positioning for microencapsulated peptide formulations.
Germany
EFSA's rejection of collagen-specific skin elasticity claims under EU Regulation 1924/2006 forces vague "beauty from within" positioning. The Novel Food Regulation compresses ingredient approval timelines that favor established suppliers with dossier-ready portfolios. Munich and Hamburg concentrate reformulation expertise for European market access.
Nutricosmetics Market Vendor Landscape
Global majors compete with regional champions across regulatory navigation and clinical substantiation capabilities. The vendor base separates into three tiers: multinational nutrition conglomerates with R&D infrastructure, heritage beauty houses with consumer trust in ingestible formats, and direct-selling specialists with captive distribution networks. Strategic archetypes include the clinical-science anchor, the convenience-format innovator, and the subscription-platform operator. Dominant competitive moves center on geographic expansion through cross-border e-commerce and portfolio diversification into microbiome-skin axis positioning.
Within the heritage beauty tier, Shiseido exemplifies decades-long investment in beauty-from-within consumer education. Among nutrition conglomerates, Nestlé and Amway occupy positions bridging functional beverage R&D with direct-selling infrastructure. These three companies anchor distinct strategic vectors: Shiseido represents brand-trust monetization, Nestlé exemplifies upstream ingredient science, and Amway illustrates captive channel control across Asia-Pacific markets.
| Leading Market Players |
|---|
| Amway |
| Nestlé |
| Herbalife Nutrition |
| Shiseido |
| Suntory Holdings |
| GNC Holdings |
| Vitabiotics |
| Koninklijke DSM |
| BASF |
| Others |
Supply Flow & Price Mechanics
Enzymatic hydrolysis at controlled 2,000–10,000 dalton molecular weights is collapsing production cost curves for premium collagen peptides while simultaneously concentrating supply among Japanese and South Korean processors with proprietary enzymatic platforms. This technology transition rewards capital-intensive manufacturers capable of clinical substantiation investment, compressing margins for commodity gelatin converters unable to support bioavailability claims.
Pricing Analysis
Input-cost pass-through from wild-caught marine collagen sourcing dominates pricing dynamics, with El Niño-driven catch volatility in Indonesian and Vietnamese coastal zones transmitting directly to finished goods manufacturers. Three-tier pricing structure across premium microencapsulated formulations, standard hydrolyzed powders, and economy gelatin alternatives separates clinical-grade Japanese products from European competitors constrained by EFSA claim restrictions. Pricing pressure stems from bovine-peptide substitution demands in Middle Eastern markets with religious dietary restrictions. Mass-market powder buyers exhibit highest price sensitivity, while subscription-locked urban millennial women in Tokyo and Seoul accept sustained premium positioning.
Supply Chain Analysis
Direct-to-consumer platforms handle subscription replenishment demand from urban millennial clusters, bypassing traditional pharmacy and department store intermediaries. Raw material supply concentrates in Japan, South Korea, and Indonesia, with wild-caught fish scale and skin sourcing anchored in Southeast Asian coastal processing zones. Downstream distribution depends on cross-border e-commerce fulfillment networks facing divergent customs classifications across ASEAN member states. Single-source vulnerability in marine collagen extraction exposes finished goods manufacturers to sustainability audit failures and climate-driven supply interruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
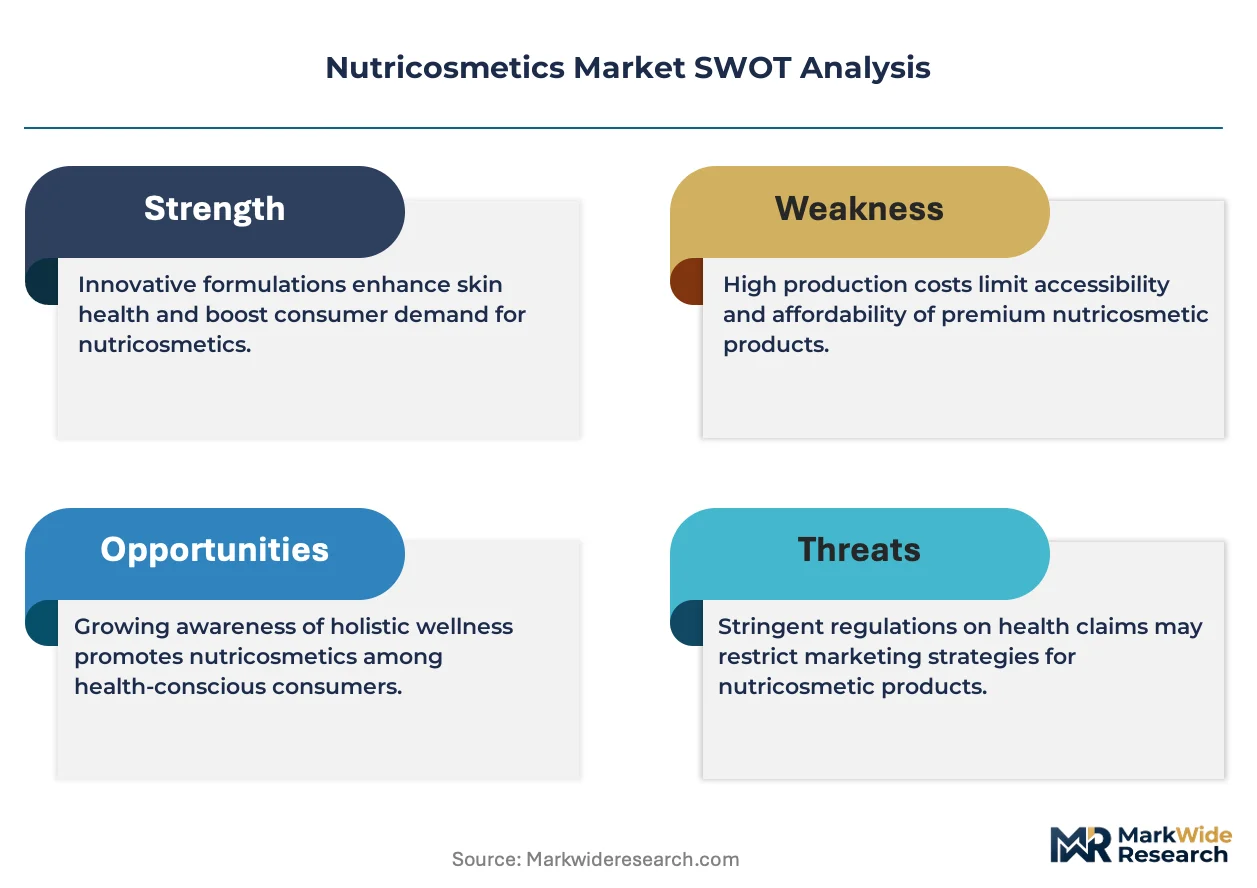
Nutricosmetics offer margin expansion through microbiome-convergence formulations commanding 40-60% premiums over commodity peptides, while enzymatic processing scale economies compress unit costs for clinical-grade hydrolyzed products.
For Market Incumbents: Deepen captive supply control over Southeast Asian marine collagen extraction through backward integration into Indonesian and Vietnamese coastal processing zones. Invest in liposomal microencapsulation R&D to defend premium positioning against emerging synbiotic competitors. Priority lever rests with securing dermatologist endorsement networks in underpenetrated Vietnam and Indonesia pharmacy channels before local consolidation. For New Entrants and Emerging Players: Capture white-space opportunity in ready-to-drink functional beverage formats addressing morning consumption occasions that powder regimens fail to serve. Target athlete segments through recovery-positioned collagen shots with understated packaging. Go-to-market angle leverages direct-to-consumer algorithmic personalization infrastructure in Shanghai and Shenzhen Tmall ecosystems. For Investors and Strategic Acquirers: Valuations sit cheapest among clinical-trial-capable mid-cap peptide processors lacking brand heritage but possessing substantiation infrastructure. Five-to-ten year viability favors firms with dedicated dermatological endpoint validation capabilities and Foods with Function Claims dossier experience. Signal to watch is regulatory harmonization pressure on Japan's MHLW framework as competitor markets demand equivalent labeling access.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables Japanese and South Korean manufacturers to justify 40-60% price premiums through measurable pharmacokinetic differentiation. |
| Cross-Border E-Commerce Expansion | Captures subscription retention revenue in Shanghai and Shenzhen through Tmall flagship store infrastructure. |
| Dermatologist Endorsement Network Buildout | Secures pharmacy channel credibility in Vietnam and Indonesia before local competitors consolidate shelf space. |
| Synbiotic Formulation Development | Opens gut-skin axis positioning that transcends commodity peptide competition through microbiome science convergence. |
| Backward Integration into Marine Sourcing | Reduces El Niño-driven supply volatility exposure in Indonesian and Vietnamese coastal processing zones. |
Methodological Framework
Multiple input streams — executive interviews with nutricosmetic brand managers and R&D directors, procurement leads at Southeast Asian marine collagen processors, pharmacy channel buyers in Tokyo and Seoul, and regulatory affairs specialists navigating EFSA and MHLW frameworks — were reconciled against secondary validation from FDA structure-function claim databases, EFSA health claim evaluation records, Japan's Foods with Function Claims registry, and customs trade data for hydrolyzed collagen peptide imports. Bottom-up demand modeling across product type, ingredient grade, and distribution channel segments was cross-checked against top-down market sizing from nutritional supplement and functional beverage revenue disclosures.
Historical volume trajectories were cross-referenced against panel input from category managers at direct-to-consumer platforms and subscription service operators to derive growth assumptions across the projection horizon. Segmentation dimensions modeled include product format (powder, capsule, ready-to-drink, gummy), peptide molecular weight tier, distribution channel (online retail, pharmacy, health store), and end-user demographic (urban millennial women, athletes, elderly). CAGRs were synthesized from elasticity-adjusted demand curves incorporating regulatory approval timeline differentials and clinical substantiation investment cycles.
Regulatory claim rejection, marine supply disruption from climate events, and cross-border customs reclassification are the dominant revision risks to forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Badminton Apparel Market
Others
Fluorapatite Market
Others
5G Edge Computing Market
Others
AI in Precision Medicine Market
Others
5G Devices Market
Others
North America IT Device Market
Others
Fluorite Market
Others
Fluid Dispensing Systems Market
Others
Smartphone Gimbal Market
Others
Global Surface Analysis Market
Others
South America Halal Food and Beverages Market
Others
Healthcare Bioconvergence Market
Others
HPHT Diamond Cubic Press Market
Others
Global Simulation in Healthcare Market
Others
Mobile Retina Services Market
Others
Remanufacturing-as-a-Service (RaaS) Market