
 Exosome Technologies Market | 2026-2036
Exosome Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Exosome Technologies Market Analysis
Modular exosome isolation workflows are repositioning buyer choice away from all-in-one kits toward configurable research platforms. Thermo Fisher Scientific leverages its consumables breadth to anchor laboratory adoption across academic and commercial settings. Lonza competes through cell culture media specialization that sustains bioproduction scale for therapeutic-grade exosome manufacturing. QIAGEN controls nucleic acid extraction adjacencies that extend its footprint into downstream exosome analytics.
Exosome technologies encompass the isolation, characterization, engineering, and application of extracellular vesicles 30-150 nm in diameter that shuttle proteins, nucleic acids, and lipids between cells. These vesicles serve as both therapeutic delivery vehicles and minimally invasive diagnostic biomarkers, with manufacturing requiring precise control over size distribution, surface marker presentation, and cargo loading efficiency. Drug delivery systems command the deepest margin pools due to regulatory complexity and clinical validation requirements, while microfluidics represents the fastest-growing technology dimension as chip-based purification displaces legacy ultracentrifugation in precision settings. Biomarker discovery occupies a mature revenue position in oncology, though gene therapy applications are gaining structural traction through engineered exosome platforms.
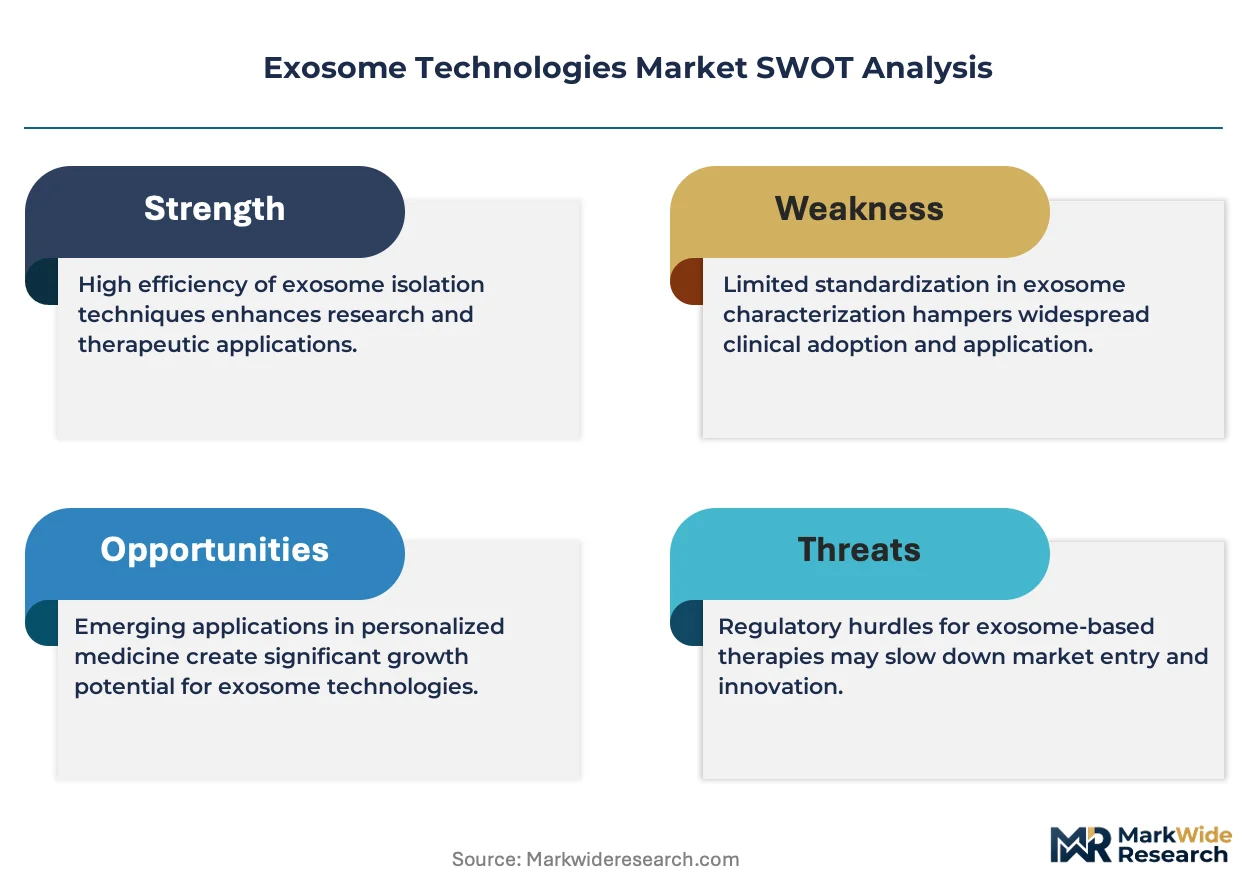
FDA oversight of extracellular vesicle products shapes manufacturing standards and Investigational New Drug pathway requirements for therapeutic developers in the United States. EMA's Advanced Therapy Medicinal Products framework in Europe imposes parallel quality benchmarks that filter market access for cross-Atlantic suppliers. ISO 13485 certification and evolving WHO guidance on cell-derived products further tighten compliance thresholds for commercial-scale operations. Stakeholders must monitor regulatory convergence between FDA and EMA on exosome characterization metrics to anticipate harmonized submission requirements that will reshape competitive readiness investments.
Market Dynamics
Microfluidic chip architectures are modularizing exosome purification workflows, compressing capital requirements for precision manufacturing while fragmenting vendor control over legacy ultracentrifugation equipment. This technology shift is redistributing competitive advantage toward consumables-anchored platform providers and away from capital-equipment incumbents.
Growth Catalysts
- FDA Investigational New Drug pathway clarification:The agency's evolving guidance on extracellular vesicle characterization metrics accelerates therapeutic developer submissions for engineered exosome drug delivery systems in oncology applications.
- Massachusetts biotech cluster procurement concentration:Venture-backed cell therapy developers in Cambridge and Boston anchor early commercial demand for GMP-compliant exosome manufacturing platforms and analytical services.
- Surface engineering chemistry advances:Click chemistry and lipid insertion techniques enable precise targeting ligand display on exosome membranes, expanding addressable indications in gene therapy and immuno-oncology.
Market Restraints
- Plasma-derived lipid input cost volatility:Pharmaceutical-grade phospholipid supply concentrates among three specialty chemical suppliers in Germany and Switzerland, exposing therapeutic-grade exosome producers to price instability.
- EMA Advanced Therapy Medicinal Products framework stringency:European quality benchmarks for cell-derived products impose 18-24 month compliance timelines that filter market access for cross-Atlantic suppliers lacking established QP relationships.
- Lipid nanoparticle substitution threat:mRNA vaccine manufacturers' mature LNP infrastructure offers competing non-viral delivery vehicles with lower regulatory uncertainty and established CMC pathways.
Strategic Opportunities
- India CDMO capacity expansion:The country's PLI scheme for pharmaceuticals and emerging biosimilar manufacturing base create white space for exosome analytics and process development services serving cost-sensitive developers.
- Neurological application convergence:Blood-brain barrier penetration capabilities position engineered exosomes for glioblastoma and neurodegenerative indications where antibody and viral vector delivery fails.
- ISO 13485 certification arbitrage:Early attainment of medical device quality management certification for diagnostic-grade exosome isolation platforms opens regulated market access ahead of harmonized WHO guidance implementation.
Industry Challenges
- Process analytical technology skill scarcity:Bioproduction engineers with combined expertise in extracellular vesicle biology and real-time quality attribute monitoring command 40% compensation premiums, constraining scale-up timelines.
- Surface marker standardization delays:Absence of consensus CD9/CD63/CD81 quantification reference materials forces therapeutic developers into proprietary assay validation, duplicating regulatory submission preparation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exosome Technologies Market |
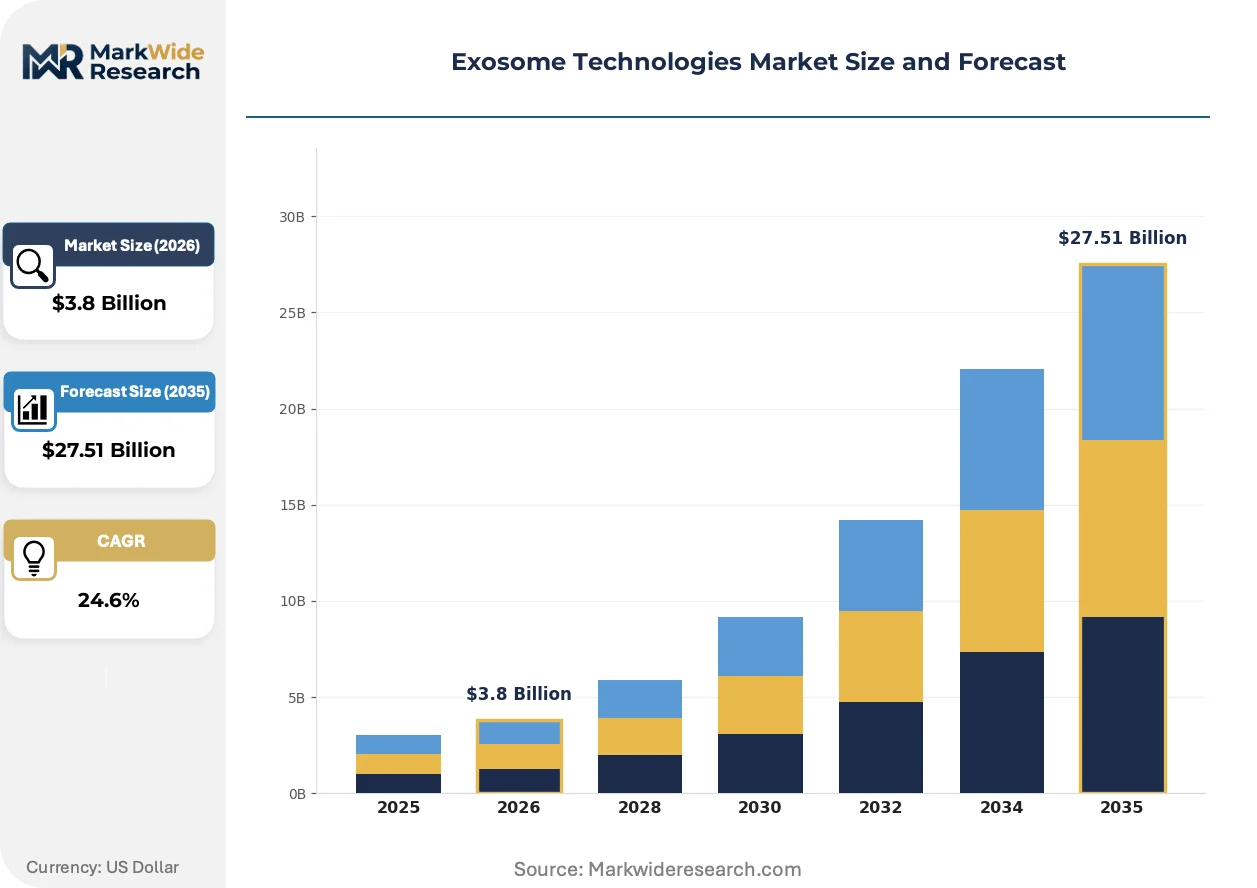
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Kits, Cell Culture Media, Drug Delivery Systems, Biomarkers End User: Pharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Diagnostics Labs Application: Therapeutic Delivery, Biomarker Discovery, Cancer Research, Gene Therapy Technology: Ultracentrifugation, Precipitation, Microfluidics, Filtration |
| Companies Covered | Bio-Techne, Thermo Fisher Scientific, Lonza, System Biosciences, Miltenyi Biotec, NanoSomix, QIAGEN, Evox Therapeutics, Norgen Biotek Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exosome Technologies Market Emerging Trajectories
Platform architectures are fragmenting competitive control over exosome workflows. Three developments dominate: chip-based purification displacing legacy methods, regulatory convergence compressing submission preparation, and procurement consolidation among integrated biotech developers reshaping vendor relationships.
Microfluidic isolation technology is modularizing exosome purification around disposable cartridge formats. Academic core facilities and emerging biotech developers adopt these platforms at 3x the pace of ultracentrifugation replacement. The technology is modularizing vendor revenue models from capital equipment toward recurring consumables, compressing payback periods and expanding addressable buyer segments.
EMA's Advanced Therapy Medicinal Products framework is converging with FDA extracellular vesicle guidance on critical quality attributes. This regulatory alignment reduces redundant characterization burden for developers pursuing parallel US-European trials. Therapeutic-grade exosome manufacturers with established EU Qualified Person relationships capture structural advantage in cross-Atlantic submission strategies.
Integrated biotech developers are consolidating procurement around full-stack platform partnerships rather than point-solution vendors. Lonza and Thermo Fisher Scientific anchor these relationships through combined cell culture media, isolation, and analytics offerings. Massachusetts and California biotech clusters exhibit this pattern most visibly, with early-stage developers trading vendor diversification for regulatory pathway support and CMC documentation assistance.
Exosome Technologies Market Segmentation
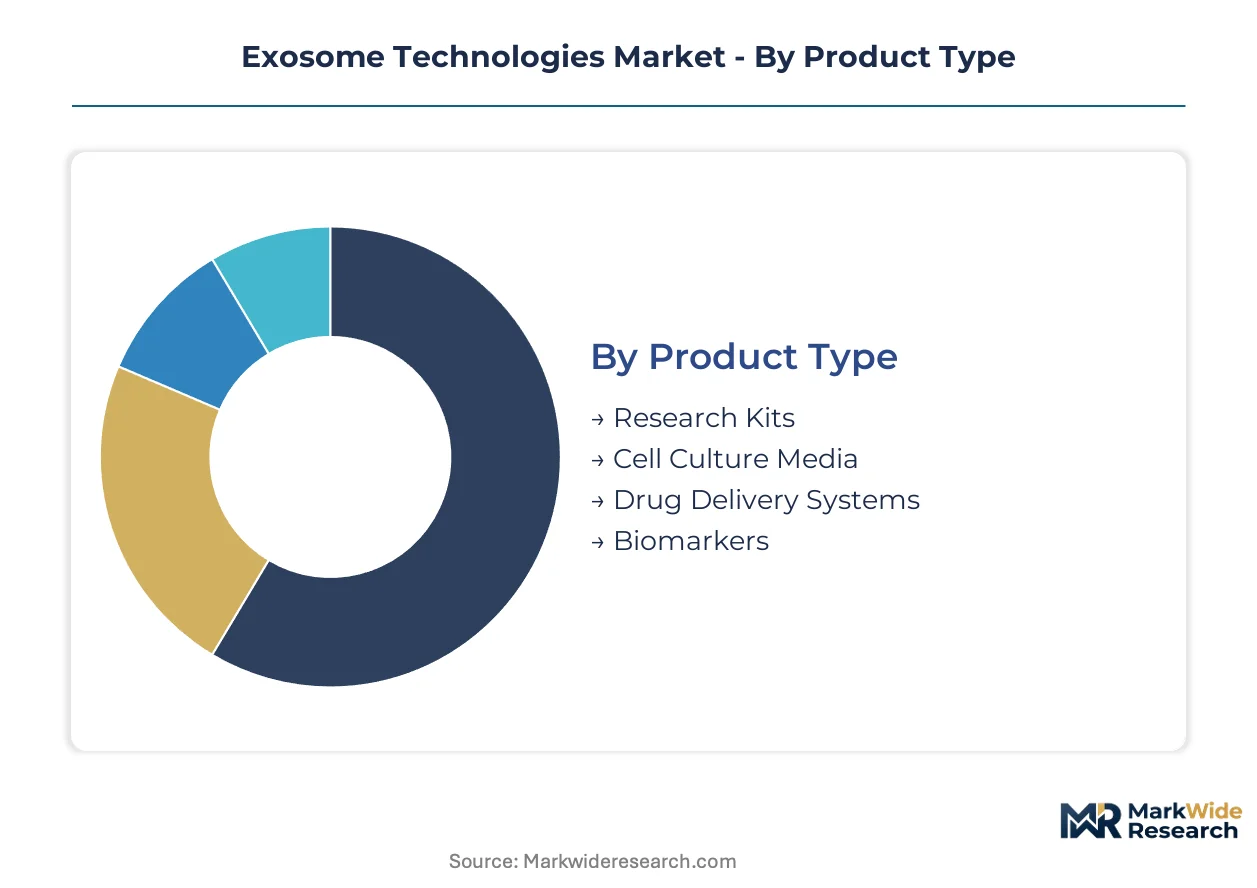
Exosome technologies fragment across four intersecting dimensions that determine procurement patterns, regulatory pathways, and margin structures. Product type stratification separates commodity research consumables from therapeutic-grade systems requiring GMP validation. End-user concentration in biotech clusters shapes geographic demand distribution.
Product Type:
FDA Investigational New Drug submissions concentrate in drug delivery systems and therapeutic-grade biomarkers, while research kits and cell culture media face lighter quality system burdens.
- Drug Delivery Systems:Engineered exosome platforms for targeted cargo transport require ISO 13485 quality management and FDA pre-IND meetings for surface characterization protocols. Massachusetts and California biotech developers anchor procurement for GMP-compliant manufacturing systems with integrated analytics.
- Biomarkers:Diagnostic-grade exosome isolation for liquid biopsy applications demands CLIA laboratory certification and evolving FDA in vitro diagnostic guidance. Oncology screening programs in academic medical centers drive volume for standardized CD9/CD63/CD81 detection panels.
- Research Kits:Modular isolation workflows for laboratory settings span precipitation-based and affinity capture formats with variable purity specifications.
- Cell Culture Media:Serum-free and chemically defined formulations sustain bioproduction scale for therapeutic-grade exosome harvest with lot-to-lot consistency requirements.
Leading the category by volume: Research Kits. Growing fastest: Drug Delivery Systems.
End User:
Procurement scale and technical specification intensity vary sharply across buyer types, with pharmaceutical companies commanding integrated platform partnerships and academic institutes prioritizing modular flexibility.
- Pharmaceutical Companies:Integrated biotech developers in Cambridge and Boston consolidate procurement around full-stack partnerships combining cell culture media, isolation, and regulatory documentation support. FDA submission preparation drives demand for CMC-ready manufacturing platforms.
- Academic Research Institutes:Core facilities adopt microfluidic cartridge systems at three times the pace of ultracentrifugation replacement, prioritizing consumables-based models over capital equipment.
- Contract Research Organizations:Process development services for therapeutic developers require scalable analytics and quality attribute monitoring capabilities.
- Diagnostics Labs:CLIA-certified clinical laboratories seek standardized exosome isolation for liquid biopsy commercialization with reproducible sensitivity specifications.
Pharmaceutical Companies capture the largest procurement value. Academic Research Institutes are expanding most quickly.
Application:
Therapeutic delivery commands premium pricing due to regulatory complexity, while biomarker discovery occupies mature revenue positions in oncology.
- Therapeutic Delivery:Engineered exosomes for gene therapy and immuno-oncology require precise surface ligand display through click chemistry and lipid insertion techniques. Blood-brain barrier penetration capabilities position the segment for glioblastoma indications where viral vectors fail.
- Gene Therapy:Non-viral delivery alternatives to AAV vectors demand rigorous biodistribution studies and immunogenicity profiling under FDA gene therapy guidance.
- Biomarker Discovery:Established oncology screening applications face substitution pressure from circulating tumor DNA assays with simpler analytical workflows.
- Cancer Research:Preclinical investigation of exosome-mediated tumor microenvironment modulation supports therapeutic target identification across solid malignancies.
Therapeutic Delivery leads application value. Gene Therapy shows the steepest expansion trajectory.
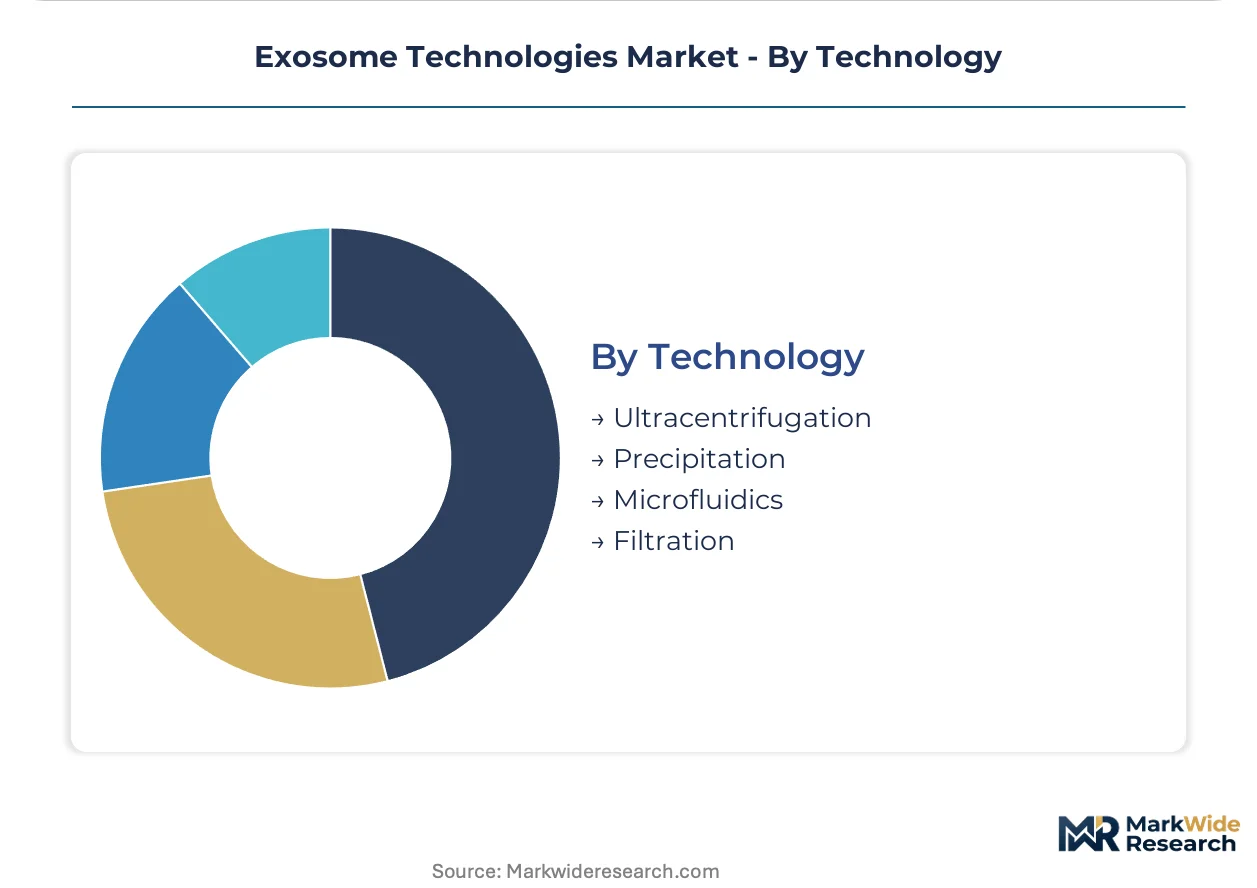
Technology:
Capital requirements and purification precision separate legacy ultracentrifugation from emerging chip-based methods fragmenting vendor control.
- Microfluidics:Disposable cartridge architectures compress capital barriers for precision manufacturing while shifting revenue models toward recurring consumables. Academic core facilities and emerging biotech developers drive adoption velocity.
- Ultracentrifugation:Density gradient separation remains the reference method for exosome purity validation despite throughput limitations and operator-dependent variability.
- Precipitation:Polymer-based enrichment offers cost-effective isolation for research applications with tolerance for co-purified protein contamination.
- Filtration:Tangential flow and size-exclusion membranes enable continuous processing scale for therapeutic-grade manufacturing with integrated concentration capabilities.
Ultracentrifugation retains the largest installed base. Microfluidics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts tax incentives for cell therapy manufacturing anchor North American exosome technology concentration, with similar special economic zones in Baden-Württemberg and Karnataka accelerating regional procurement patterns.
United States
FDA Investigational New Drug submissions for engineered exosome platforms concentrate therapeutic developer demand. The agency's evolving extracellular vesicle characterization guidance accelerates pre-IND meeting requests. Cambridge and Boston biotech clusters anchor procurement for GMP-compliant manufacturing systems with integrated analytics support.
Germany
Pharmaceutical-grade phospholipid suppliers in the Rhine-Main region sustain input cost leverage over therapeutic-grade producers. EMA Advanced Therapy Medicinal Products framework imposes 18-24 month compliance timelines that filter cross-Atlantic market access. Heidelberg and Munich academic medical centers drive diagnostic biomarker validation studies for liquid biopsy applications.
India
The PLI scheme for pharmaceuticals and emerging biosimilar manufacturing base create white space for exosome analytics services. CDSCO's evolving cell-derived product guidance shapes domestic regulatory expectations. Hyderabad and Bangalore biotech parks attract process development outsourcing from cost-sensitive therapeutic developers.
Switzerland
Specialty chemical suppliers in Basel concentrate pharmaceutical-grade lipid inputs for exosome membrane engineering. Swissmedic's alignment with EMA quality benchmarks streamlines QP relationships for cross-Atlantic suppliers. The country's precision manufacturing heritage supports analytical reference material production for surface marker standardization.
United Kingdom
Gene therapy developers in London and Oxford pursue engineered exosome alternatives to AAV vectors under MHRA post-Brexit regulatory frameworks. Academic core facilities adopt microfluidic cartridge systems at elevated rates. The Golden Triangle research corridor sustains biomarker discovery programs for oncology liquid biopsy applications.
Exosome Technologies Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented tier structures. Life science tools conglomerates leverage consumables breadth to anchor laboratory adoption through recurring revenue models. Cell therapy CDMOs compete through bioproduction scale and regulatory documentation capabilities. The dominant competitive moves involve strategic partnerships combining isolation platforms with analytics services, and geographic expansion into emerging biotech clusters.
Among diversified life science tools providers, Thermo Fisher Scientific and QIAGEN exemplify archetypes leveraging consumables-anchored platform strategies. Lonza occupies a position representing cell therapy manufacturing specialization. These three entities collectively illustrate how vendor control fragments between capital-equipment incumbents and consumables-focused challengers as microfluidic technologies modularize purification workflows.
| Leading Market Players |
|---|
| Bio-Techne |
| Thermo Fisher Scientific |
| Lonza |
| System Biosciences |
| Miltenyi Biotec |
| NanoSomix |
| QIAGEN |
| Evox Therapeutics |
| Norgen Biotek Corp. |
| Others |
Supply Flow & Price Mechanics
Captive integration into pharmaceutical-grade phospholipid supply anchors both cost predictability and margin defense for therapeutic-grade exosome manufacturers facing volatile specialty chemical markets. This vertical control over lipid inputs distinguishes GMP-compliant producers from research-grade competitors while compressing procurement leverage for downstream buyers dependent on spot markets.
Pricing Analysis
Short lead-time premiums for GMP-certified exosome manufacturing platforms command substantial markups over standard research-grade systems. Three-tier pricing structure across GMP-validated, CLIA-certified, and research-use-only levels stratifies the market by regulatory burden and documentation depth. Cost compression in research kits is intensifying because microfluidic cartridge commoditization fragments vendor pricing power. Academic core facilities exhibit highest price sensitivity, while integrated biotech developers in Massachusetts and California prioritize regulatory pathway support over unit cost.
Supply Chain Analysis
Pharmaceutical-grade phospholipid supply rests on specialty chemical producers concentrated in Germany and Switzerland, with secondary sourcing from Netherlands-based lipid manufacturers. Serum-free cell culture media formulations, synthetic cholesterol derivatives, and tangential flow filtration membranes constitute critical input dependencies. Single-source vulnerability in CD9/CD63/CD81 reference material production constrains diagnostic-grade standardization. Distribution runs through life science tools distributors serving academic medical centers and direct platform partnerships with cell therapy CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidic isolation technology is displacing legacy ultracentrifugation as the dominant purification architecture, compressing payback periods and fragmenting competitive control over consumables revenue.
For Market Incumbents: Extend consumables-anchored platform relationships through integrated cell culture media and analytics bundling that locks in biotech developer procurement. Defend against microfluidic pure-plays by accelerating GMP certification timelines for cartridge manufacturing. Prioritize backward integration into phospholipid supply to buffer input cost volatility from Rhine-Main chemical producers.
For New Entrants and Emerging Players: Surface engineering chemistry capabilities offer entry into engineered exosome drug delivery where established players lack specialized ligand display expertise. Target India CDMO services white space created by PLI scheme pharmaceutical incentives and cost-sensitive therapeutic developer outsourcing. Pursue platform partnerships with Hyderabad and Bangalore biotech parks as anchor distribution channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in cell therapy CDMO rollup strategies and consumables-platform tuck-ins serving GMP manufacturing scale-up. Long-term viability hinges on regulatory convergence between FDA and EMA quality benchmarks that validates cross-Atlantic commercial infrastructure. Watch EMA Qualified Person relationship depth as the signal distinguishing acquisition-ready assets from compliance-lagged competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Platform Integration | Disposable cartridge architectures compress capital barriers while shifting revenue to recurring consumables. |
| GMP Manufacturing Scale-Up | FDA pre-IND meeting preparation requires validated quality systems and CMC documentation capabilities. |
| Surface Engineering Partnership | Click chemistry licensing expands addressable indications in gene therapy and immuno-oncology applications. |
| India CDMO Capacity Buildout | PLI scheme incentives and biosimilar manufacturing base attract cost-sensitive process development outsourcing. |
| ISO 13485 Certification Pathway | Medical device quality management opens regulated diagnostic markets ahead of harmonized WHO guidance. |
Methodological Framework
Multi-period observation of FDA Investigational New Drug submission patterns, EMA Advanced Therapy Medicinal Products approvals, and microfluidic platform adoption rates anchored the trend analysis, supplemented by interviews with exosome manufacturing executives, regulatory affairs leads at therapeutic developers, academic core facility directors, and phospholipid procurement specialists. Secondary validation drew from FDA guidance documents, EMA scientific recommendations, ClinicalTrials.gov engineered exosome protocols, and ISO 13485 certification databases. Bottom-up triangulation across product type, end user, application, and technology segmentation dimensions converged with top-down market sizing.
Input-output matrices modeled supply-side capacity expansion against demand pull from biotech clusters in Massachusetts, California, and emerging hubs in India and Switzerland. Segmentation dimensions spanned product type stratification, end-user procurement concentration, therapeutic versus diagnostic application intensity, and technology displacement velocity. CAGRs were derived from fitted growth curves calibrated to regulatory milestone timing and platform adoption S-cycles. Forecast inputs incorporated phospholipid supply elasticity and microfluidic cartridge manufacturing scale constraints.
Several conditions sit outside the modeled scope, including unforeseen FDA guidance reversals on extracellular vesicle characterization metrics and disruptive lipid nanoparticle substitution in non-viral delivery. Forecasts reflect assumptions about regulatory convergence timelines and platform technology maturation curves that could shift with breakthrough surface engineering advances or EMA framework stringency modifications. A small set of named triggers warrants ongoing watch: EMA Qualified Person relationship formation rates, microfluidic cartridge cost curves, and plasma-derived phospholipid spot market volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Conditional Access System (CAS) Market
Others
Dried Fruit Extracts Market
Others
Digital LUX Meter Market
Others
Ultra Mobile Devices (UMD) Market
Others
Duty Free Retail Market
Others
Solid White Films Market
Others
Eye Balm Market
Others
India Foundry Market
Others
North America Wiring Duct Market
Others
Double Card Mobile Phone Market
Others
Europe Smart Homes Market
Others
Smart Card Market
Others
Versatile Video Coding Market
Others
8K Technology Market
Others
Ultrasonic Flow Meter Market
Others
Vegetable Carbon Market