
 Spain Smart Home Market | 2026-2036
Spain Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Smart Home Market Insights
Specialist electrical distributors and utility co-marketing channels is reshaping how smart home devices reach Spanish households. Schneider Electric leverages its legacy building automation expertise to dominate commercial-to-residential cross-selling. Samsung anchors its position through integrated appliance ecosystems that bundle screens, sensors, and hubs. Robert Bosch competes on installation service density, training thousands of certified technicians across Iberian retail partnerships.
Spain Smart Home comprises interconnected devices, control platforms, and communication protocols that automate residential environments through sensor networks, actuators, and cloud-based management interfaces operating on Wi-Fi, Zigbee, Z-Wave, or Bluetooth connectivity standards. These systems enable remote monitoring, predictive energy optimization, and automated security response for single-family dwellings, multi-unit buildings, and managed properties. Security Systems currently leads product type revenue due to insurance-mandated monitoring requirements in premium developments. Energy Management applications show the fastest trajectory as Iberian electricity tariffs fluctuate and homeowners seek load-shifting automation. Smart Speakers face margin compression from platform commoditization despite high unit penetration in urban centers.
Spain's Ministry for the Ecological Transition enforces building efficiency standards that mandate smart metering integration in renovated structures above certain floor areas. The Spanish Data Protection Agency supervises voice and video data flows from connected domestic devices under GDPR-derived national implementation rules. BIS-equivalent certification requirements for radio equipment ensure interoperability compliance at import. Stakeholders must weigh platform openness against ecosystem lock-in as utility partnerships become the primary customer acquisition path.
Market Dynamics
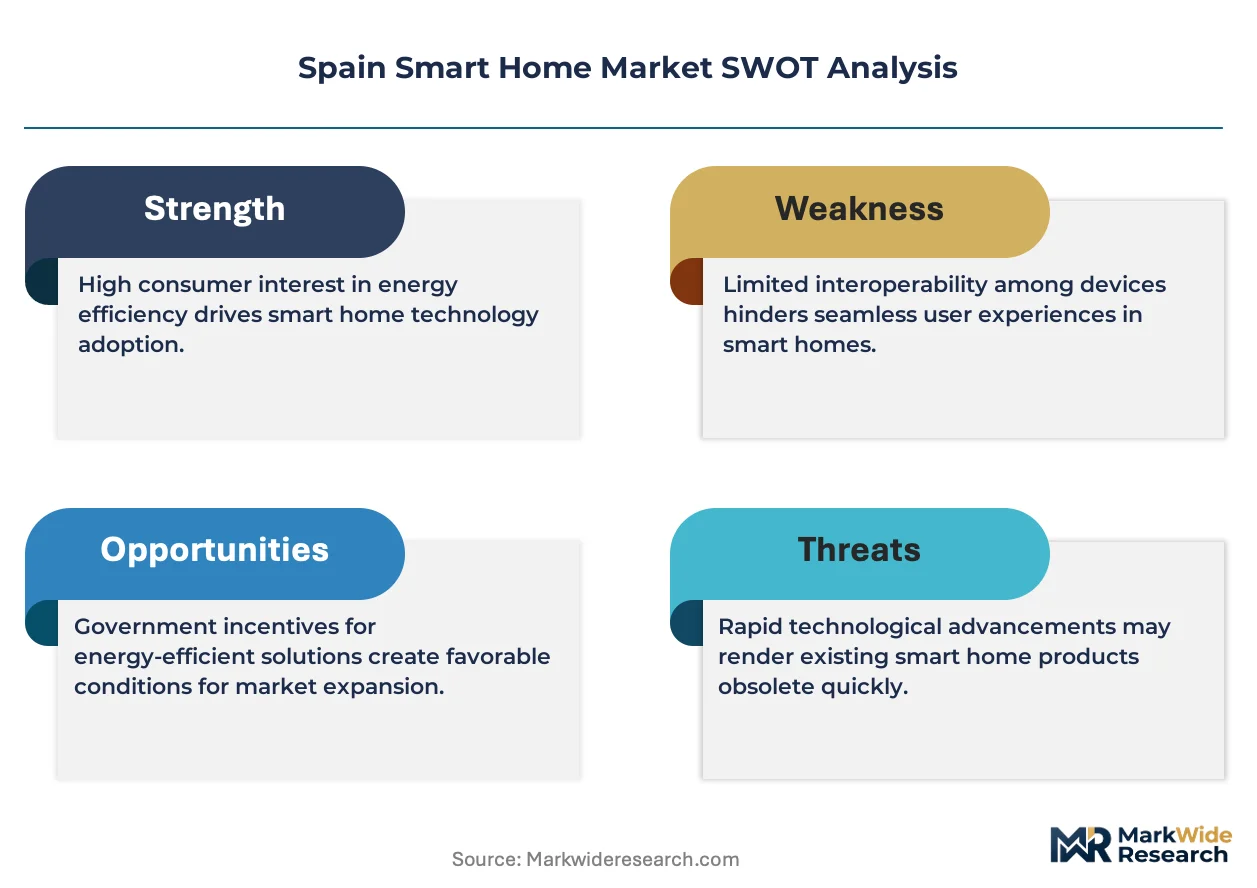
Utility-linked smart thermostat deployments are compressing traditional retail channels as Iberian electricity distributors bundle hardware with tariff contracts, fundamentally restructuring how Spanish households acquire automation infrastructure.
Growth Catalysts
- PNIEC Retrofit Mandates:Spain's National Integrated Energy and Climate Plan requires efficiency upgrades in existing housing stock above specified floor areas, mandating smart metering integration that pulls automation hardware into renovation workflows.
- Iberian Electricity Tariff Volatility:Fluctuating wholesale power prices are pushing homeowners toward load-shifting automation systems that optimize consumption during off-peak rate windows.
- Insurance-Mandated Monitoring:Premium residential developments in Madrid and Barcelona now require connected security infrastructure as a condition of coverage, creating baseline demand for integrated sensor networks.
Market Restraints
- Semiconductor Supply Concentration:Zigbee and Z-Wave radio chipsets depend on concentrated Asian foundry capacity, exposing Spanish device assemblers to allocation volatility and extended lead times.
- GDPR-Derived Compliance Friction:The Spanish Data Protection Agency's supervision of voice and video data flows imposes technical architecture constraints and audit burdens on cloud-connected device portfolios.
- Platform Commoditization Pressure:Smart speaker hardware margins are compressing as voice assistant platforms race to zero-cost entry points, draining resources from ecosystem development.
Strategic Opportunities
- Andalusian and Valencian Suburban Expansion:New construction outside Madrid and Barcelona remains underpenetrated by utility partnership channels, offering direct-to-builder sales openings for independent distributors.
- Matter Protocol Convergence:The interoperability standard is collapsing Wi-Fi, Thread, and Zigbee fragmentation, enabling single-hub architectures that reduce consumer configuration complexity and support costs.
- Managed Property Service Bundles:Multi-unit building operators are consolidating device procurement across portfolios, creating volume contracting opportunities for platforms offering centralized monitoring dashboards.
Industry Challenges
- Certified Installation Technician Scarcity:Complex multi-protocol deployments require trained field personnel, yet vocational programs have not scaled to match retrofit program volumes mandated under PNIEC timelines.
- Legacy Building Electrical Compatibility:Pre-1990s housing stock in Spanish city centers lacks neutral wiring at switch points, forcing expensive rewiring or limiting device compatibility for renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Smart Home Market |
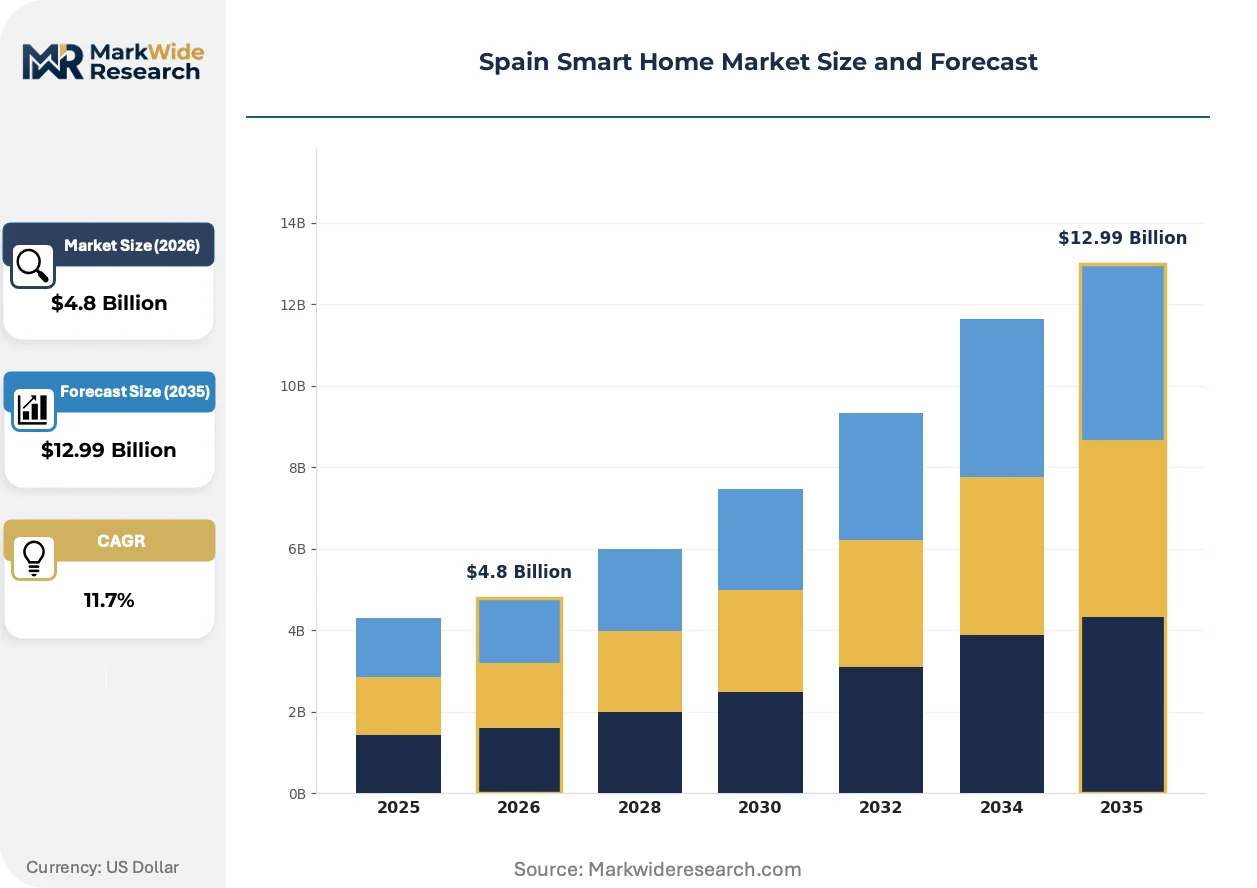
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, Security Systems, Smart Speakers, Thermostats Customer Type: Homeowners, Renters, Property Managers, Developers Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Energy Management, Home Security, Entertainment, Automation |
| Companies Covered | Schneider Electric, ABB, Siemens, Google, Amazon, Samsung, LG Electronics, Robert Bosch, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Smart Home Market Trends and Innovations
Edge computing architectures are displacing cloud-dependent processing in Spanish smart home deployments, driven by latency requirements for security responsiveness and data sovereignty concerns under national GDPR implementation.
Virtualized home automation controllers are consolidating previously discrete hub functions into software layers running on standard networking hardware. Property management firms in Barcelona are piloting these deployments to reduce hardware refresh cycles. The technology is virtualizing traditional device categorization, collapsing boundaries between security, climate, and lighting control systems into unified software-defined environments.
Spain's Ministry for the Ecological Transition has tightened BIS-equivalent certification requirements for radio equipment imports, extending compliance timelines for non-EU manufacturers. The regulation is forcing hardware vendors to pre-certify Matter-compatible devices before Iberian market entry. Energy Management applications face the steepest adaptation burden, as load-control modules must demonstrate interoperability with utility-grade metering infrastructure.
Homeowners are unbundling after-sales service from hardware purchase, subscribing to independent technical support contracts rather than relying on manufacturer warranties. This pattern concentrates in Madrid's premium renovation segment, where consumers prioritize rapid response over brand loyalty. Specialist electrical distributors are capturing this margin by offering white-glove configuration and ongoing maintenance subscriptions.
Spain Smart Home Market Segmentation
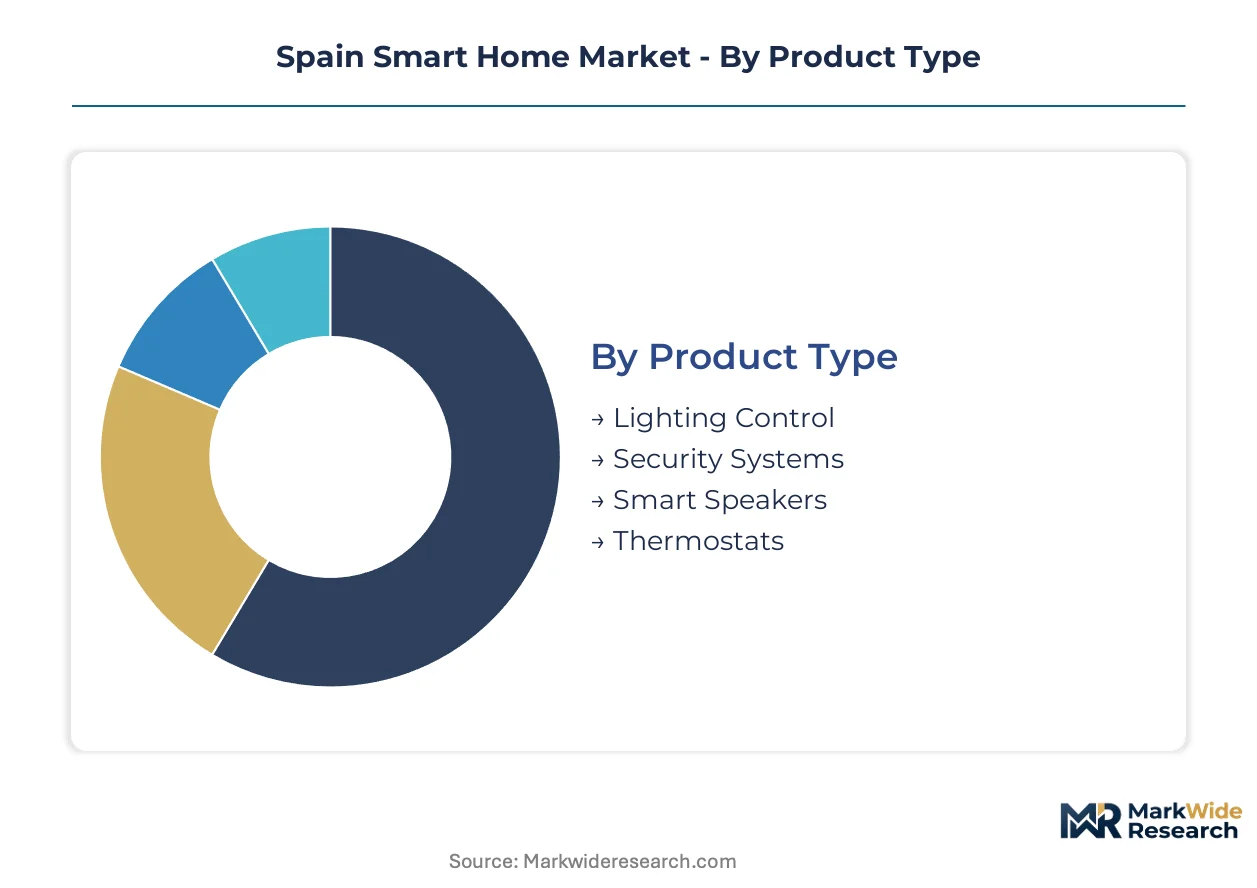
Smart home market segmentation in Spain reflects divergent technology maturity across hardware categories and customer readiness. Utility partnerships, retrofit mandates, and rental market structures create distinct demand profiles that reward targeted positioning over mass-market approaches.
Product Type:
Mature segments dominate revenue concentration while emerging categories reshape acquisition channels through bundled service models.
- Security Systems:Integrated sensor networks combining motion detectors, video surveillance, and cloud-connected monitoring hubs. Insurance-mandated installations in Madrid and Barcelona premium developments establish baseline demand that subsidizes hardware margins through recurring monitoring fees.
- Thermostats:Climate control devices with load-shifting algorithms optimizing consumption against Iberian electricity tariff windows. Iberdrola and Endesa bundle these with variable-rate contracts, capturing homeowners seeking protection from wholesale price volatility.
- Lighting Control:Dimmable LED arrays and automated switching systems. Neutral wiring limitations in pre-1990s Spanish housing stock constrain retrofit penetration.
- Smart Speakers:Voice-activated hubs with integrated virtual assistants. Platform commoditization has compressed hardware margins below sustainable levels for independent vendors.
Security Systems handles the majority of throughput; Thermostats is the fastest mover on share.
Customer Type:
Procurement authority and installation control determine segment accessibility, with direct ownership enabling complex multi-protocol deployments.
- Homeowners:Permanent residents with full property modification rights. PNIEC retrofit mandates pull automation hardware into renovation workflows for floor areas above regulatory thresholds.
- Developers:New construction specifiers integrating infrastructure during build phase. Utility partnership channels dominate Madrid and Barcelona greenfield projects.
- Property Managers:Multi-unit building operators consolidating procurement across portfolios. Centralized monitoring dashboards reduce per-unit support overhead.
- Renters:Tenants lacking structural modification rights. Portable plug-and-play devices with minimal installation requirements address this constraint.
Homeowners absorb the largest volume; Developers is climbing the fastest as new construction accelerates outside saturated urban cores.
Technology:
Protocol selection trades installation simplicity against mesh reliability and power consumption in Spain's heterogeneous housing stock.
- Zigbee:Low-power mesh networking standard enabling battery-operated sensor deployments. Concentrated Asian foundry capacity for radio chipsets exposes Spanish assemblers to allocation volatility.
- Wi-Fi:Ubiquitous IP-based connectivity leveraging existing residential infrastructure. High power consumption limits battery-operated device applications.
- Z-Wave:Sub-GHz mesh protocol optimized for residential automation. Smaller ecosystem limits device interoperability compared to Zigbee alternatives.
- Bluetooth:Point-to-point short-range connectivity for direct smartphone control. Matter protocol convergence is collapsing previous fragmentation advantages.
Zigbee carries the heaviest device volume; Wi-Fi is gaining share fastest through simplified consumer onboarding.
Application:
Use-case prioritization follows utility tariff structures and insurance requirements rather than lifestyle convenience alone.
- Energy Management:Load-shifting automation and predictive consumption optimization. Spanish Ministry for the Ecological Transition mandates smart metering integration in renovated structures above specified floor areas.
- Home Security:Intrusion detection and emergency response systems. Premium development coverage requirements in Madrid and Barcelona create non-discretionary demand.
- Automation:Cross-system orchestration of lighting, climate, and security through unified control layers. Virtualized controllers are collapsing previous hardware boundaries.
- Entertainment:Audio-visual integration and content streaming coordination. Smart TV and streaming device convergence has reduced dedicated hub relevance.
Energy Management commands the steepest expansion trajectory; Home Security maintains the largest installed base through insurance channel lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Madrid-Barcelona high-speed rail corridor underwrites Spain's smart home concentration by linking the two metropolitan demand centers where utility-linked thermostat deployments dominate new construction and renovation workflows.
Madrid
PNIEC retrofit mandates pull automation hardware into renovation workflows across the capital's pre-1990s housing stock. Spain's Ministry for the Ecological Transition enforces smart metering integration in structures above specified floor areas. Insurance-mandated security installations in premium developments around Salamanca and Chamberí establish baseline demand for integrated sensor networks.
Catalonia
Barcelona's property management firms pilot virtualized home automation controllers to reduce hardware refresh cycles across multi-unit portfolios. The Spanish Data Protection Agency supervises voice and video data flows under GDPR-derived national implementation rules. Utility partnerships with Iberdrola and Endesa dominate greenfield projects in the metropolitan periphery.
Basque Country
Industrial automation heritage from Bilbao's manufacturing base accelerates commercial-to-residential cross-selling of building control systems. BIS-equivalent certification requirements for radio equipment extend compliance timelines for non-EU manufacturers entering through northern ports. San Sebastián's premium renovation segment shows concentrated demand for white-glove configuration services.
Andalusia
New construction outside saturated urban cores remains underpenetrated by utility partnership channels, offering direct-to-builder sales openings for independent distributors. Neutral wiring limitations in Seville's historic center constrain retrofit penetration for lighting control systems. Málaga's coastal developments attract insurance-mandated security infrastructure for second-home properties.
Valencia
Suburban expansion around the port city creates volume contracting opportunities for platforms offering centralized monitoring dashboards to multi-unit operators. Matter protocol convergence enables single-hub architectures that reduce consumer configuration complexity. Alicante's rental market drives portable plug-and-play device demand among tenants lacking structural modification rights.
Spain Smart Home Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: electrical distributors with legacy building automation expertise, integrated appliance ecosystems bundling screens and sensors, and installation service networks training certified technicians. M&A activity concentrates on software-defined controller platforms, while geographic expansion targets underpenetrated suburban markets outside Madrid and Barcelona.
Among European electrical specialists, Schneider Electric and ABB exemplify the commercial-to-residential cross-selling archetype, leveraging industrial control heritage to dominate retrofit workflows. Samsung anchors the integrated ecosystem tier through appliance bundling strategies. Robert Bosch occupies a position within the service-density archetype, with technician training programs supporting Iberian retail partnerships. Google and Amazon represent platform commoditization pressures compressing smart speaker hardware margins despite high urban penetration.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| Amazon |
| Samsung |
| LG Electronics |
| Robert Bosch |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Concentrated Asian foundry capacity for Zigbee and Z-Wave radio chipsets anchors margin pools in the device assembly and certification tiers rather than component manufacturing. Utility-linked thermostat bundling with Iberian electricity contracts compresses hardware margins while shifting value toward installation service contracts and ongoing platform subscriptions.
Pricing Analysis
Volume-discount tiering structures separate premium certified-installation packages from standard retail self-install kits and economy-grade plug-and-play devices. Pricing stratifies across premium, standard, and economy tiers based on certification grade for PNIEC compliance and after-sales service bundling. Cost compression in the smart speaker tier is intensifying because platform commoditization races toward zero-cost entry points. Property managers show the least price sensitivity due to portfolio-scale procurement authority, while renters in Valencia and Alicante demand the most economical portable solutions.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for Spanish device assemblers importing radio chipsets and sensor modules. Manufacturing concentration in China, Taiwan, and South Korea for semiconductor components creates single-source vulnerability for Zigbee mesh networking hardware. Raw material dependencies span lithium-ion cells for battery-operated sensors, rare earth elements for actuator motors, and copper wiring for retrofit installations. Distribution runs through specialist electrical distributors and utility co-marketing channels rather than traditional consumer electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain Smart Home Market operates as a defensive-moat story where regulatory entrenchment through PNIEC retrofit mandates and utility partnership lock-in creates durable incumbent advantages. Switching costs for multi-protocol installations and GDPR compliance architecture further harden positions.
For Market Incumbents: Pre-empt emerging Matter protocol specialists by accelerating certification investment for interoperable device portfolios before BIS-equivalent import requirements tighten. Deepen channel control through exclusive technician training partnerships with Basque Country and Andalusian vocational programs to capture PNIEC-mandated retrofit volumes. Vertical integration into cloud-based energy management platforms addresses margin pressure from hardware commoditization. For New Entrants and Emerging Players: Pursue white-space opportunities in Andalusian and Valencian suburban new construction where utility partnership channels remain underdeveloped. Target direct-to-builder sales of single-hub Matter-compatible architectures that reduce configuration complexity for independent distributors. The most penetrable segment is portable plug-and-play devices for Spain's rental market, where tenants lack structural modification rights. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined controller platforms that virtualize previously discrete hub functions into unified management layers. Long-term viability over the coming decade hinges on consolidation of fragmented installation service networks into scaled technical support operations. The signal to watch is Matter protocol adoption velocity among Iberian utility distributors as an inflection indicator for interoperability standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Pre-certification with Iberian regulators accelerates market entry before BIS-equivalent requirements tighten for non-EU manufacturers. |
| Utility Partnership Expansion | Exclusive thermostat bundling with Endesa or Iberdrola contracts captures homeowner acquisition at the tariff decision point. |
| Technician Training Scale-Up | Certified installation networks address scarcity constraints in PNIEC-mandated retrofit timelines across Madrid and Barcelona. |
| Software-Defined Controller Development | Virtualized platforms reduce hardware refresh cycles for Barcelona property management firms operating multi-unit portfolios. |
| GDPR Compliance Architecture Investment | Technical infrastructure meeting Spanish Data Protection Agency requirements creates audit-defensible competitive positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smart home platform engineers, utility partnership directors, certified installation technicians, and electrical distributor category managers. Secondary validation drew from Spain's Ministry for the Ecological Transition regulatory filings, Iberdrola and Endesa tariff documentation, Spanish Data Protection Agency guidance publications, and customs import records for radio equipment. Bottom-up device shipment estimates were triangulated against top-down energy retrofit program allocations.
Calibration against historical PNIEC implementation trajectories and utility partnership penetration rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer procurement authority, communication protocol, and application use-case against Iberian electricity tariff structures. CAGRs were derived from retrofit mandate timelines and new construction permitting data. Forecast inputs incorporated Matter protocol adoption curves and edge computing architecture displacement rates.
Macroeconomic conditions sit as an overlay; deviation in Iberian wholesale electricity prices, semiconductor foundry allocation volatility, or GDPR enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and technology standardization velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Digital Signage Media Player Market
Others
Global Supply Chain Risk Management Software Market
Others
Global Drug Discovery Informatics Market
Others
Rugged Tablet Market
Others
South Korea Smart Home Market
Others
Digital Education Projector Market
Others
Wind and Solar Hybrid Street Light Market
Others
Middle East Paper Making Machine Market
Others
Rope Market
Others
Ultra Mobile Devices (UMD) Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Wingboards Market
Others
Process Spectroscopy Market
Others
Japan Smart Home Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Programmatic Display Market