
 Air Purification Systems Market | 2026-2036
Air Purification Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Purification Systems Market Intelligence
Expertise in sensor integration and data analytics for smart building environments is reorganizing the competitive landscape. Honeywell International Inc. leverages its deep building automation background to lead in integrated commercial systems. Dyson differentiates through its focus on aerodynamic engineering and consumer-centric design for residential units. Daikin Industries Ltd. competes by embedding advanced filtration technologies within its core HVAC product lines, targeting both commercial and residential end-users.
Air purification systems are devices designed to remove contaminants such as particulates, allergens, and volatile organic compounds from indoor air. Their effectiveness is often measured by the Clean Air Delivery Rate (CADR), indicating the volume of filtered air delivered. HEPA filters remain the dominant product type due to their proven high efficiency in capturing fine particles. In terms of application, demand from commercial complexes and healthcare facilities is outpacing the mature residential segment due to stricter health and safety mandates.
Regulatory frameworks from the US Environmental Protection Agency (EPA) establish performance benchmarks for indoor air quality. In parallel, European standards like CE marking and RoHS directives govern product safety and hazardous material content, impacting market access. Future profitability will hinge on developing systems that meet diverging regional energy efficiency targets and particulate matter removal standards.
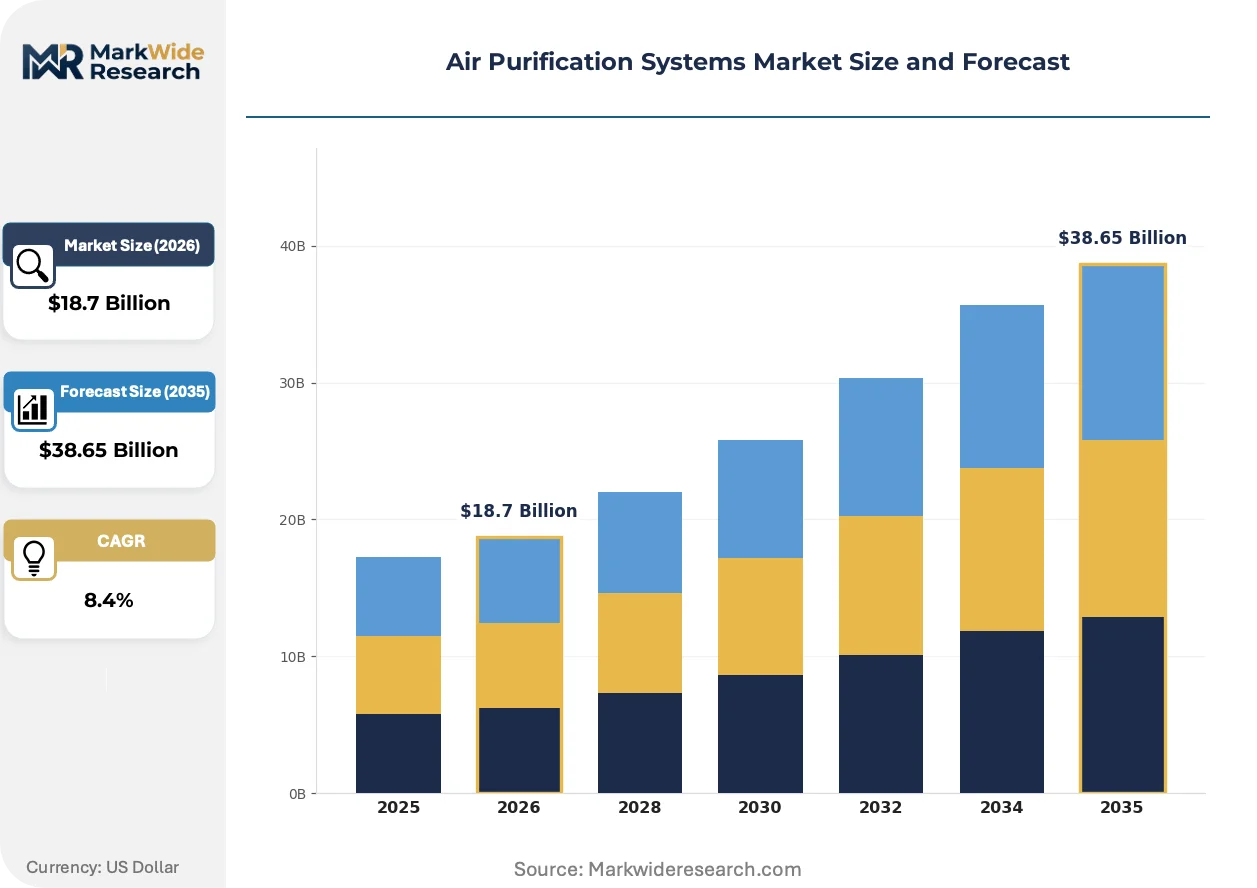
Market Dynamics
The convergence of smart building IoT platforms with public health mandates, particularly in high-density urban areas, is the central force shaping the market. This integration creates a feedback loop where regulatory pressure from bodies like the US EPA and China's MEE drives technology adoption for real-time air quality management.
Growth Catalysts
- Stricter IAQ Mandates:China’s GB standards and similar regulations are compelling the installation of advanced filtration in new commercial and public buildings, creating baseline demand.
- Pathogen Neutralization Tech:The integration of UV-C and photocatalytic oxidation technologies expands system use for neutralizing viruses and VOCs in healthcare and public transit settings.
- Corporate Health Focus:A focus on employee wellness is driving adoption in office buildings, with procurement specifying systems based on high Clean Air Delivery Rate (CADR) performance.
Market Restraints
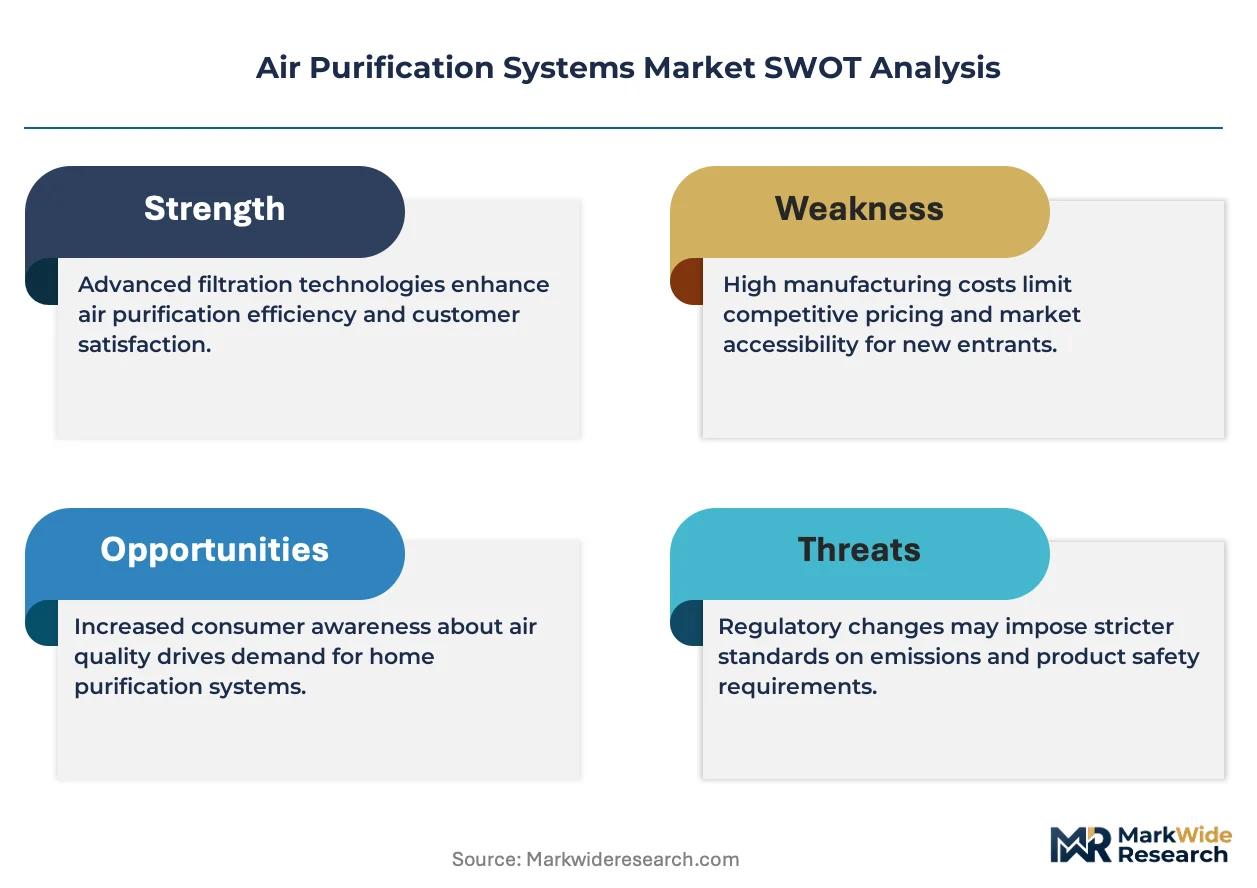
- High Total Cost of Ownership:Significant upfront investment and recurring filter replacement costs deter adoption in the price-sensitive residential and small business segments.
- Byproduct Generation Risk:Certain technologies like ozonation can generate harmful byproducts, creating consumer skepticism and inviting scrutiny from regulators like the US EPA.
- Concentrated Filter Supply:The supply of specialized HEPA filter media is geographically concentrated, exposing manufacturers to price volatility and geopolitical supply risks.
Strategic Opportunities
- New Geographic Expansion:Targeting urbanizing centers in Southeast Asia and Latin America, where air quality awareness is rising but system penetration remains low, offers growth.
- Public Transit Systems:Developing specialized units for public transportation like buses and trains addresses air quality needs in high-occupancy, enclosed environments.
- Predictive Maintenance Services:Using IoT data and AI to forecast filter replacement needs creates recurring service revenue and improves device efficiency for customers.
Industry Challenges
- Performance Metrics Standardization:A lack of global standards for measuring the effectiveness of VOC and pathogen neutralization creates consumer confusion and complicates direct product comparisons.
- Legacy System Integration:Integrating advanced purification systems with diverse and often outdated building management and HVAC systems presents significant technical challenges and installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Purification Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV Air Purifiers, Ionizers, Electrostatic Precipitators, Photocatalytic Oxidation Units Technology: Mechanical Filtration, Adsorption, Ultraviolet Light, Negative Ion Generation, Ozone Generation, Plasma Technology Application: Residential Spaces, Commercial Complexes, Educational Institutions, Public Transportation, Hospitality Venues, Data Centers End User: Office Environments, Healthcare Facilities, Manufacturing Plants, Retail Outlets, Laboratories, Fitness Centers |
| Companies Covered | Honeywell International Inc., Dyson, Daikin Industries Ltd., Philips Electronics, Blueair, Coway, LG Electronics, Panasonic Corporation, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Purification Systems Market Strategic Shifts & Innovations
Intelligent system integration and data-driven performance verification are redefining the market's value proposition. This evolution moves the technology beyond simple filtration, embedding it within broader smart building and public health infrastructures demanding real-time control.
Solid-state air purification, using advanced photocatalytic oxidation (PCO), neutralizes VOCs and pathogens without producing ozone. Commercial sectors like hospitality and healthcare are adopting these for active air sanitization. This active neutralization is supplanting older passive filtration methods that only capture contaminants.
The European Union's F-Gas Regulation impacts air purification by pushing HVAC makers toward new refrigerants. This forces redesigns of integrated units, creating an opportunity to engineer systems with higher energy efficiency and filtration. Manufacturers targeting the EU are bundling compliance with F-Gas and Ecodesign directives, marketing combined energy savings and superior indoor air quality.
Commercial end-users are shifting from one-time hardware purchases to subscription-based 'Air Quality as a Service' (AQaaS) models. This model bundles hardware, monitoring, and automated filter replenishment, disrupting traditional distribution channels. The trend is most visible in corporate real estate and premium hospitality, where predictable operational expenses are valued.
Air Purification Systems Market Segmentation
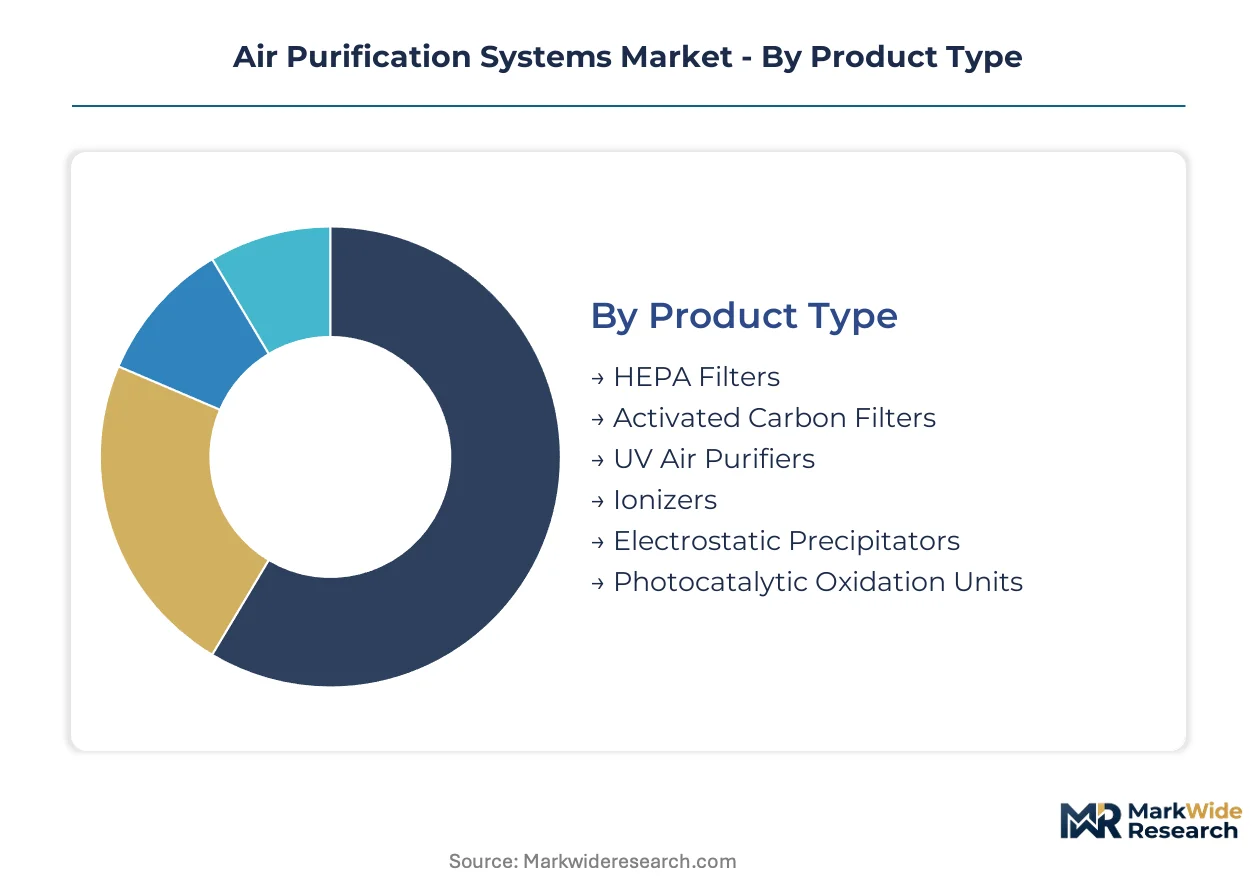
Understanding the varied requirements across different environments is crucial for air purification system manufacturers. This segmentation analysis dissects the market by product type, underlying technology, specific application areas, and diverse end-user sectors. Each category reveals unique demand patterns and operational considerations.
Product Type:
The distribution of air purification products reflects distinct user priorities, often channeled through specialized distributors for commercial clients or retail for residential consumers.
- HEPA Filters:These high-efficiency particulate air filters capture 99.97% of airborne particles 0.3 microns in size. Demand concentrates in healthcare facilities and cleanrooms due to stringent particle removal requirements.
- Photocatalytic Oxidation Units:PCO units use UV light and a catalyst to neutralize volatile organic compounds and pathogens. Hospitality and public transit systems increasingly adopt these for active air sanitization in enclosed spaces.
- Activated Carbon Filters:These filters absorb gaseous pollutants and odors effectively.
- UV Air Purifiers:Ultraviolet germicidal irradiation systems deactivate airborne microorganisms.
- Ionizers:Ionizers generate charged ions that attract and clump airborne particles.
- Electrostatic Precipitators:These devices use an electric field to charge and collect particulate matter.
HEPA Filters dominate the installed base across commercial and institutional settings. Photocatalytic Oxidation Units are where expansion concentrates, driven by active neutralization needs.
Technology:
The technological underpinnings of air purification systems dictate performance characteristics and operational costs. Different technologies target specific contaminants, influencing procurement decisions.
- Mechanical Filtration:This technology physically traps particles using filter media like HEPA. Commercial complexes and manufacturing plants prioritize this for robust particulate removal.
- Adsorption:Adsorption technology, primarily using activated carbon, captures gaseous pollutants and odors. Laboratories and industrial facilities utilize this for chemical fume control.
- Ultraviolet Light:UV-C technology deactivates bacteria, viruses, and molds.
- Negative Ion Generation:This process emits charged ions to attract and settle airborne particles.
- Ozone Generation:Ozone generators produce O3 to oxidize pollutants, though regulatory scrutiny exists.
- Plasma Technology:Plasma technology breaks down pollutants at a molecular level.
Mechanical Filtration represents the most established technology for particle removal. Adsorption technology for gas-phase contaminants is gaining share fastest in specialized industrial applications.
Application:
Specific application environments present unique challenges and regulatory requirements for air quality management. Each setting demands tailored solutions for effective contaminant removal.
- Commercial Complexes:These large-scale facilities require integrated HVAC systems with advanced filtration for occupant comfort and health. Stricter health mandates in urban centers drive this segment.
- Healthcare Facilities:Hospitals and clinics demand high-efficiency systems for pathogen neutralization and infection control. Regulatory bodies like the US EPA influence system specifications here.
- Residential Spaces:Home users prioritize compact, quiet units for allergy relief and general air quality improvement.
- Educational Institutions:Schools and universities install systems to reduce airborne contaminants in classrooms.
- Public Transportation:Buses, trains, and subways need specialized units for high-occupancy, enclosed environments.
- Data Centers:These facilities require precise particulate control to protect sensitive electronic equipment.
Commercial Complexes account for a substantial portion of new system installations. Healthcare Facilities demonstrate significant expansion potential due to ongoing health and safety upgrades.
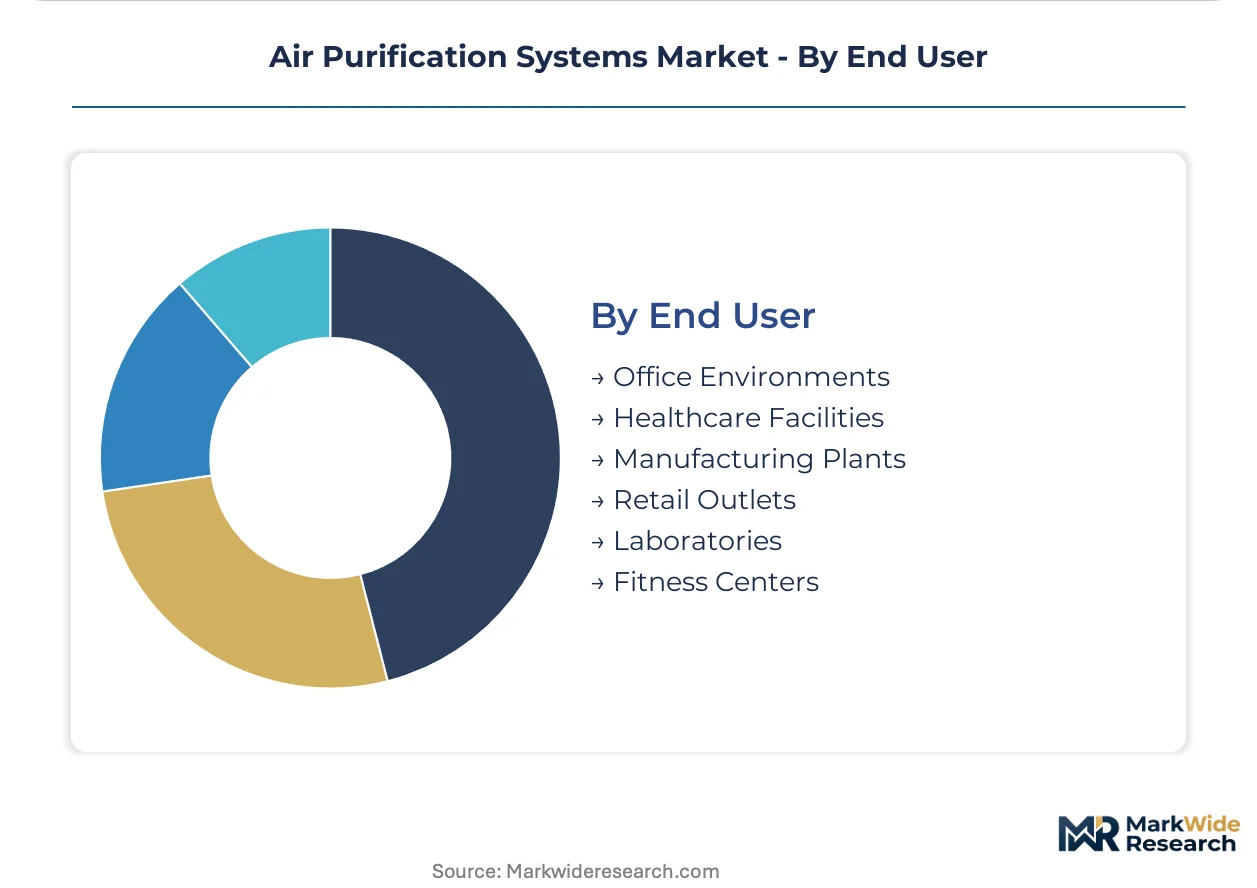
End User:
Diverse end-user segments necessitate different product features, service models, and procurement processes. Corporate wellness initiatives and specific industry regulations shape demand.
- Office Environments:Corporate health focus drives adoption of high-CADR systems to improve employee wellness and productivity. Procurement often involves facility management teams.
- Healthcare Facilities:Hospitals and clinics require robust systems for infection prevention and air quality compliance. These institutions demand proven pathogen neutralization capabilities.
- Manufacturing Plants:Industrial settings use air purification to control process-generated contaminants and protect workers.
- Retail Outlets:Stores employ systems to enhance customer experience and maintain indoor air quality.
- Laboratories:Labs need specialized filtration for fume extraction and cleanroom environments.
- Fitness Centers:Gyms install systems to manage odors and improve air quality in high-activity areas.
Office Environments represent a significant and growing end-user segment. Healthcare Facilities are exhibiting the steepest expansion trajectory, driven by public health infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency (EPA) establishes performance benchmarks for indoor air quality, influencing system specifications globally. This regulatory framework shapes demand for advanced air purification systems across various international markets. Demand for these systems is concentrating in urban centers, particularly in Asia and Europe.
United States
Demand for air purification systems in the United States stems from healthcare facilities requiring pathogen neutralization and a corporate focus on employee health. The US EPA's stringent indoor air quality standards drive adoption in commercial settings. Major metropolitan areas like New York City and Los Angeles are seeing significant deployment of integrated systems in commercial real estate projects.
China
China's market experiences robust demand due to stricter IAQ mandates in new commercial and public buildings, particularly in high-density urban areas. The Ministry of Ecology and Environment (MEE) actively promotes technology adoption for real-time air quality management. Urban centers such as Beijing and Shanghai are focal points for deploying advanced air purification systems, driven by GB standards.
India
Rising air quality awareness in India's urbanizing centers, coupled with public health mandates, fuels demand for air purification solutions. Local municipal bodies are implementing stricter air pollution controls, impacting new construction. Cities like Delhi and Mumbai exhibit growing demand for both commercial and residential air purification units.
Germany
Germany's market is driven by employee wellness initiatives in office buildings and the integration of purification technologies within core HVAC systems. European standards like CE marking and RoHS directives govern product safety and hazardous material content, influencing market access. Industrial hubs in North Rhine-Westphalia are actively integrating advanced filtration solutions into manufacturing facilities and commercial spaces.
Air Purification Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the air purification systems market. The competitive structure is tiered, with established industrial players contrasting with consumer-focused brands and specialized technology developers. Strategic archetypes include integrated building solutions providers, consumer-centric design innovators, and embedded filtration specialists. Dominant competitive moves involve portfolio diversification into adjacent smart building technologies and forming strategic partnerships for broader market access.
Integrated commercial systems leaders, such as Honeywell International Inc., leverage extensive building automation backgrounds to offer comprehensive solutions. Dyson exemplifies a consumer-centric design innovator, focusing on aerodynamic engineering for residential units. Daikin Industries Ltd., a Japanese corporation, represents the archetype of a core HVAC product line embedding advanced filtration technologies for both commercial and residential end-users. These companies anchor distinct segments of the market.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dyson |
| Daikin Industries Ltd. |
| Philips Electronics |
| Blueair |
| Coway |
| LG Electronics |
| Panasonic Corporation |
| Sharp Corporation |
| Others |
Cost & Logistics Intelligence
Subscription-based 'Air Quality as a Service' models lock in recurring revenue streams and provide customers with predictable operational costs. This contractual approach enhances price visibility for both providers and end-users.
Pricing Analysis
Geographic price disparities for air purification systems reflect varying regulatory stringencies and local competition. The market's dominant pricing structure shifts towards subscription-based 'Air Quality as a Service' (AQaaS) for commercial clients, while residential sales remain transactional. Price differentiation stems from Clean Air Delivery Rate (CADR) performance and seamless integration with smart building platforms. Residential consumers and small businesses exhibit the highest price sensitivity, driving pricing pressure to balance high upfront investment with recurring service costs.
Supply Chain Analysis
Inventory strategies in the air purification market balance just-in-time component sourcing with strategic stockpiling of critical filter media. Geographic supply concentration for specialized HEPA filter media primarily centers on East Asian manufacturing hubs, including China. Key dependencies involve advanced filter membranes and UV-C lamp components, creating a structural risk from geopolitical events impacting material access. Distribution runs through specialized commercial integrators for large installations and retail channels for residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air purification systems market faces a critical shortage in advanced integration capabilities. This gap in expertise for seamless smart building and HVAC system integration limits broader market penetration.
For Market Incumbents: Compound existing strengths in building automation and HVAC integration to counter fragmented performance metrics. Incumbents should diversify portfolios into adjacent smart building technologies and form strategic partnerships. Investing in R&D for solid-state air purification and advanced sensor integration reinforces leadership against non-standardized performance claims.
For New Entrants and Emerging Players: Differentiate on novel active pathogen neutralization technologies like advanced photocatalytic oxidation. Target underpenetrated urbanizing centers in Southeast Asia and Latin America, or specialized public transit systems. A go-to-market angle leveraging 'Air Quality as a Service' (AQaaS) models disrupts traditional hardware sales by offering predictable operational expenses.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized technology developers with strong IoT integration and data analytics capabilities. The market’s long-term viability appears robust, driven by evolving public health mandates and smart building trends. Acquisition targets should possess proven expertise in pathogen neutralization or advanced filtration media; watch for widespread adoption of predictive maintenance services.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen IoT Sensor Integration | This initiative enhances real-time air quality monitoring and enables automated filter adjustments. |
| Expand 'Air Quality as a Service' (AQaaS) | AQaaS models shift commercial procurement from capital expenditure to predictable operational expenses. |
| Invest in Photocatalytic Oxidation (PCO) | PCO technology provides active neutralization of VOCs and pathogens beyond passive filtration. |
| Target Emerging Urban Markets | Geographic expansion into Southeast Asia addresses rising air quality awareness and low system penetration. |
| Strengthen HVAC System Integration | Embedding advanced filtration within core HVAC product lines offers comprehensive solutions. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings of this study. Primary data involved discussions with facility managers, HVAC engineers, and public health officials across key geographies. Secondary validation drew from US EPA reports, China's MEE directives, and company annual reports. Both bottom-up and top-down triangulation methods were applied to ensure data consistency.
Sensitivity analysis integrated various macroeconomic and industry-specific scenarios across the projection horizon. The analytical framework modeled market dynamics across product type, underlying technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected adoption rates. Key industry-specific inputs included air quality index data and new commercial building construction rates.
Decision-makers should treat outputs as directional under current geopolitical stability and regulatory compliance assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions. Geopolitical supply risks or significant shifts in public health mandates could materially alter market trajectories, warranting revision when such conditions cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Liquid Density Meters Market
Others
Solar Lighting Tower Market
Others
France 3D Printing Construction Market
Others
Latin America Travel Retail Market
Others
Europe Legal Services Market
Others
Global Food Fiber Market
Others
Spend Analytics Market
Others
Global Mobile Video Optimization Market
Others
Reduced-Risk Products (Rrps) Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Space Power Supply Market
Others
Process Spectroscopy Market
Others
5G Devices Market
Others
Senior Cat Food Market
Others
AI In Government And Public Services Market
Others
Electrical Calibration Equipment Market