
 France Automotive LED Lighting Market | 2026-2036
France Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive LED Lighting Market Insights
A widening capability gap in semiconductor sourcing and optical design is bifurcating the France Automotive LED Lighting Market into capital-heavy integrated suppliers and module-dependent assemblers. Valeo leverages in-house photonics labs and regional foundry partnerships to sustain margin control across headlamp assemblies. HELLA GmbH & Co. KGaA anchors its position through advanced driver-assistance lighting integration, while OSRAM GmbH dominates chip-scale LED architectures for premium French OEM programs.
France Automotive LED Lighting comprises solid-state electroluminescent devices built on gallium nitride substrates, emitting directional photons through precision-molded polycarbonate lenses to replace incandescent and gas-discharge sources in vehicle illumination. The primary purpose is to reduce energy draw from alternators while enabling adaptive beam patterns and signature daytime visibility. Headlights occupy the deepest margin pools due to complexity in matrix-beam regulation and thermal management, whereas electric vehicle application demand outpaces other segments as French battery-platform architectures mandate ultra-efficient auxiliary loads. OLED technology trails in volume but leads in design differentiation for rear-lamp signatures on luxury nameplates.
France's national market operates under ECE certification administered by the KBA in Germany for type approval, supplemented by EU RoHS restrictions on hazardous substances in electronics and REACH protocols governing chemical substances in lens coatings. The EU Green Deal's embedded carbon requirements are forcing suppliers to document lifecycle emissions across LED supply chains, reshaping procurement criteria for French tier-one contracts. Stakeholders must monitor how France's adaptation of the EU AI Act intersects with adaptive lighting algorithms requiring software validation.
Market Dynamics
EU Green Deal embedded carbon mandates are forcing French tier-one suppliers to reconfigure procurement criteria around lifecycle emissions documentation, compressing margins for module-dependent assemblers while rewarding capital-heavy integrated photonics producers.
Growth Catalysts
- EU Green Deal carbon accounting:Embedded emissions requirements are reshaping supplier qualification for French OEM contracts, favoring domestic foundry partnerships over Asian chip sourcing.
- Paris-Saclay automotive cluster concentration:Proximity to Renault and Stellantis engineering centers accelerates prototype-to-production cycles for adaptive beam systems.
- Gallium nitride substrate advances:Higher electron mobility in GaN architectures reduces thermal load, enabling slimmer headlamp assemblies for electric vehicle platforms.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea foundries control advanced GaN wafer production, exposing French assemblers to geopolitical logistics disruption.
- REACH lens coating compliance:Chemical substance restrictions on polycarbonate additives extend formulation validation timelines by 8-14 months.
- OLED cost structure:Organic emitter deposition yields remain below inorganic LED economics, limiting rear-lamp adoption to luxury nameplates above EUR 80,000.
Strategic Opportunities
- Rhône-Alpes supplier network expansion:Underutilized Grenoble photonics infrastructure offers captive packaging capacity for matrix-beam modules.
- EU AI Act adaptive lighting convergence:Software validation frameworks for algorithmic beam shaping create first-mover advantage for compliant tier-one integrators.
- Vehicle-to-everything communication integration:LED arrays doubling as data transmitters open new revenue pools in connected mobility services.
Industry Challenges
- Thermal management engineering scarcity:French technical institutes produce fewer than 120 specialists annually in optoelectronics packaging, constraining R&D throughput.
- ECE type approval timeline compression:KBA certification queues for matrix-beam variants extend 11-16 months, delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive LED Lighting Market |
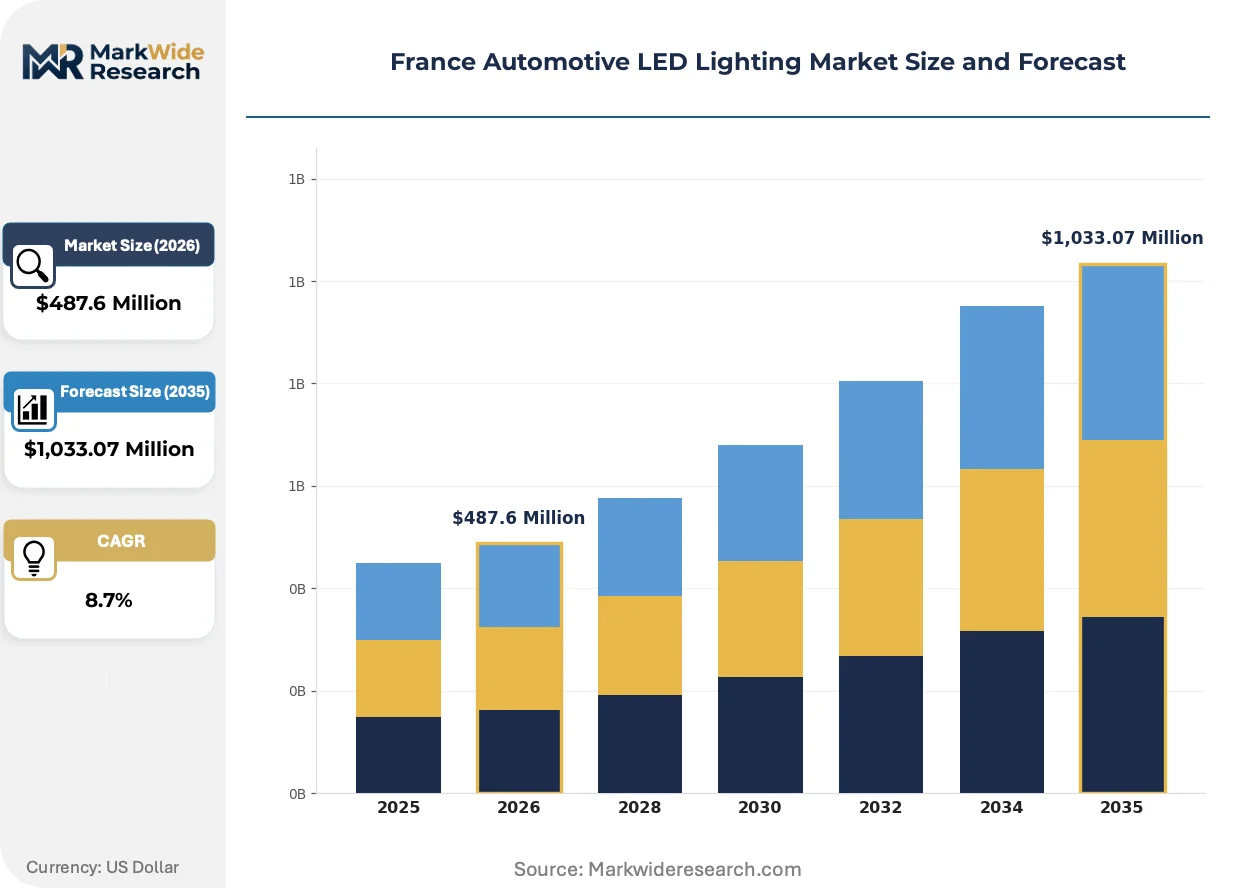
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Daytime Running Lights Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Electric Vehicles Technology: Halogen, Xenon, OLED, Laser Certification: ECE, SAE, DOT, RoHS |
| Companies Covered | Valeo, HELLA GmbH & Co. KGaA, OSRAM GmbH, Marelli Holdings Co., Ltd., Signify, ZKW Group, Stanley Electric Co., Ltd., Koito Manufacturing Co., Ltd., GRUPO ANTOLIN IRAUSA, S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive LED Lighting Market Trends and Innovations
Active matrix LED architectures are displacing passive designs across French premium platforms, while regulatory software validation requirements and procurement model consolidation reshape competitive positioning among tier-one suppliers.
Chip-scale LED packaging is miniaturizing optical engine footprints for headlamp assemblies. Stellantis and Renault are adopting these architectures for 2027 platform refreshes at accelerated procurement cycles. This compression is miniaturizing thermal management hardware, reducing assembly weight by one-third versus 2019 benchmarks.
France's adaptation of the EU AI Act is imposing software validation protocols on adaptive beam algorithms. Tier-one suppliers must now document machine-learning decision trees for KBA type approval, extending engineering resource allocation. Matrix-beam headlamp categories face the steepest compliance cost escalation as algorithmic complexity outpaces regulatory framework maturity.
French OEM procurement is consolidating supplier rosters around vertically capable photonics integrators. Module-dependent assemblers are losing position to in-house packaging specialists with captive foundry relationships. This concentration is most visible in Paris-Saclay cluster contracts, where Renault has reduced qualified headlamp suppliers from seven to four since 2022.
France Automotive LED Lighting Market Segmentation
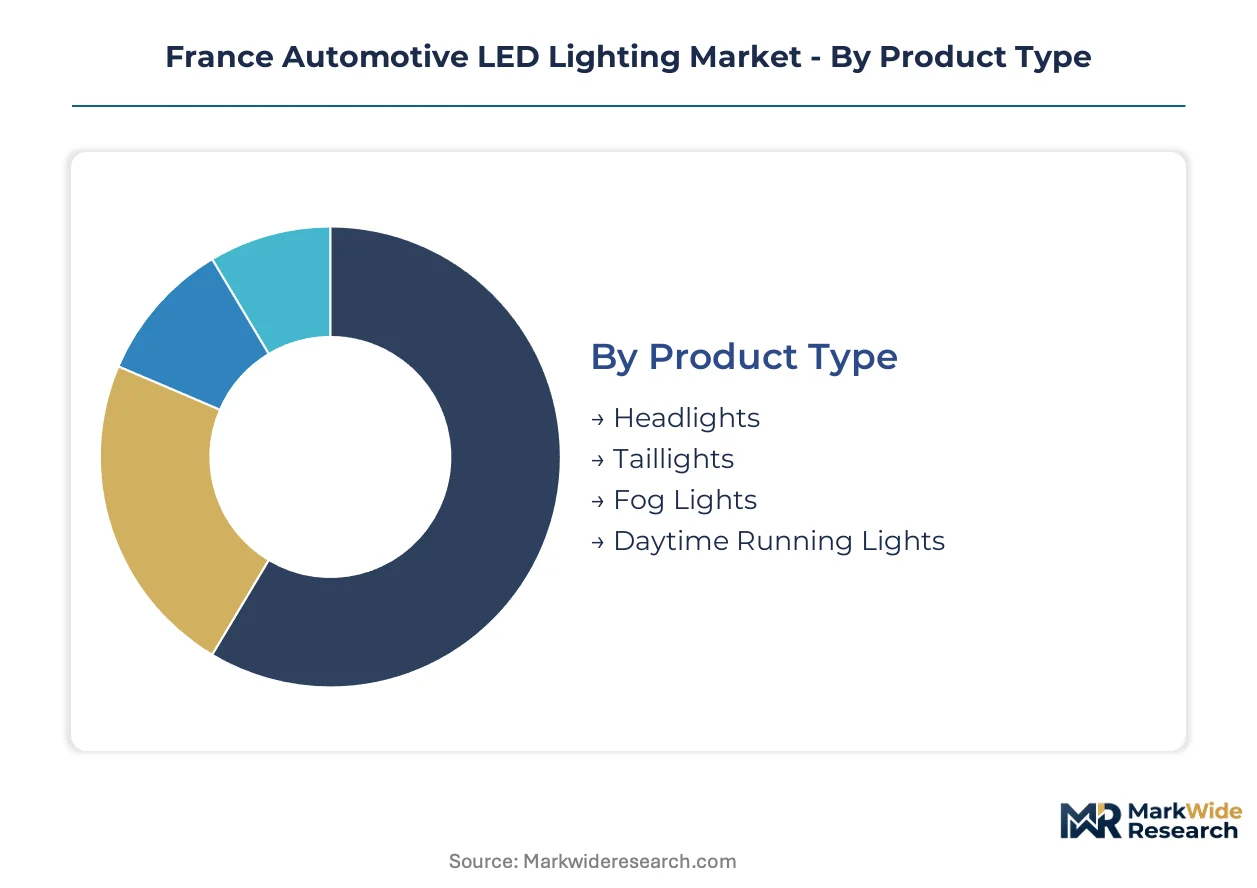
Segmentation in the France Automotive LED Lighting Market reveals how substitution dynamics and regulatory pressure concentrate value across distinct product configurations. Understanding these divides illuminates where capital deployment yields margin protection versus commoditization risk.
Product Type:
Substitution pressure from solid-state architectures weighs most heavily on legacy lamp categories, with matrix-beam LED systems displacing conventional assemblies across French premium platforms.
- Headlights:Matrix-beam LED architectures built on gallium nitride substrates enable adaptive beam patterns with pixel-level control. Demand concentrates at Renault and Stellantis engineering centers in the Paris-Saclay cluster, where KBA type approval timelines for advanced variants extend 11-16 months and compress platform launch schedules.
- Taillights:OLED emitter arrays deliver signature rear-lamp differentiation through segmented organic deposition on flexible substrates. Adoption clusters on luxury nameplates above EUR 80,000 where design premium justifies yield-limited economics, while inorganic LED alternatives dominate volume production.
- Fog Lights:Compact LED modules with secondary optics replace halogen units in lower bumper assemblies.
- Daytime Running Lights:Strip-form LED configurations serve brand signature functions with minimal thermal load.
Headlights anchor the volume base while OLED-enabled taillights gain share at the steepest rate.
Application:
Cost tier stratification separates electrified platforms from internal combustion architectures, with battery-electric mandates reshaping auxiliary load specifications across French OEM procurement.
- Passenger Vehicles:Premium and mass-market nameplates drive matrix-beam adoption, with Stellantis and Renault specifying chip-scale packaging for 2027 platform refreshes.
- Electric Vehicles:Ultra-efficient LED architectures minimize alternator draw on battery platforms, with French battery-electric mandates accelerating specification upgrades. Rhône-Alpes supplier networks capture module assembly contracts for dedicated EV lighting lines.
- Commercial Vehicles:Durability-focused LED sealed-beam units serve fleet operators with extended service intervals.
- Motorcycles:Compact single-emitter designs with vibration-resistant packaging address two-wheeler form factor constraints.
Passenger vehicles retain the largest installed base while electric vehicle applications expand most quickly.
Technology:
Maturity gradients separate incumbent discharge sources from emerging solid-state emitters, with regulatory phase-outs accelerating transition timelines for French type approvals.
- Halogen:Tungsten-filament technology with quartz-halogen regeneration cycles faces EU efficiency mandates restricting new platform adoption.
- Xenon:High-intensity discharge arc lamps with mercury content trigger RoHS compliance costs and supply chain documentation requirements.
- OLED:Organic electroluminescent layers deposited on glass or polymer substrates enable surface-emitting rear lamp signatures. French luxury nameplate demand concentrates design differentiation investment here despite yield gaps versus inorganic alternatives.
- Laser:Coherent blue excitation of remote phosphor converters extends throw distance for high-beam functions in premium segments.
Halogen retains residual volume in entry segments while laser-augmented systems climb the fastest.
Certification:
Supply concentration around German-administered approval pathways creates asymmetric compliance burdens for French suppliers serving export markets.
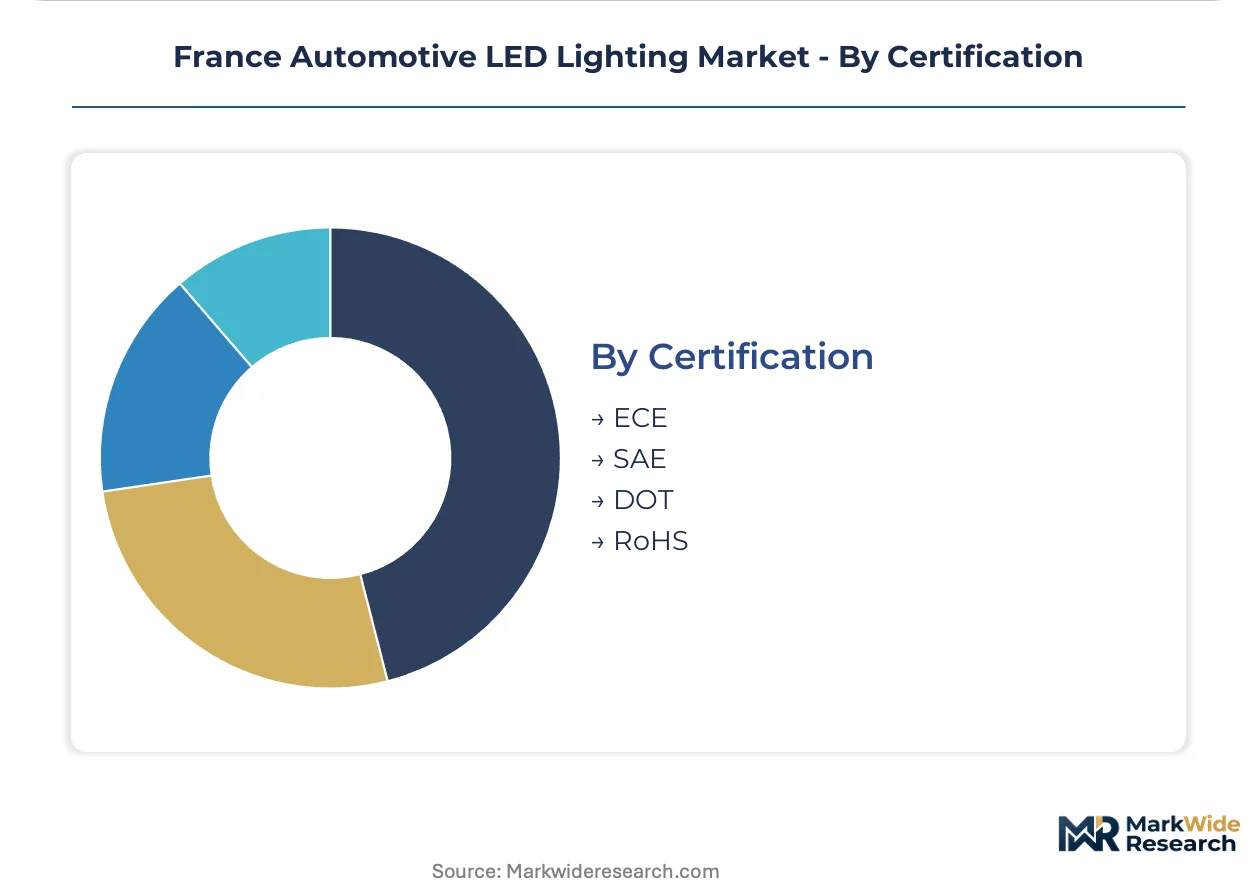
- ECE:UN Regulation 48 administered by KBA in Germany governs type approval for lighting devices across EU member states. French tier-one suppliers must queue for matrix-beam variant certification, with documentation requirements intensifying under EU AI Act software validation protocols.
- RoHS:EU Directive 2011/65/EU restricts hazardous substances including mercury in discharge lamps and cadmium in certain phosphor formulations. REACH lens coating compliance extends formulation validation timelines by 8-14 months for polycarbonate additives.
- SAE:North American technical standards require parallel testing for French suppliers accessing US export markets.
- DOT:Federal Motor Vehicle Safety Standards administered by NHTSA govern US market entry.
ECE certification anchors the regulatory burden while RoHS documentation requirements expand most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for automotive LED lighting varies sharply across French sub-regions, with Île-de-France buyers absorbing premium matrix-beam costs while peripheral markets prioritize standard LED configurations.
Île-de-France
Renault and Stellantis engineering centers in the Paris-Saclay cluster drive specification of chip-scale LED architectures for 2027 platform refreshes. EU AI Act software validation protocols administered through KBA type approval extend certification timelines for adaptive beam algorithms. Paris-Saclay's concentration of OEM R&D facilities compresses prototype-to-production cycles for tier-one photonics integrators.
Auvergne-Rhône-Alpes
Grenoble's underutilized photonics infrastructure offers captive packaging capacity for matrix-beam modules serving battery-electric vehicle lines. REACH lens coating compliance for polycarbonate additives extends formulation validation timelines by 8-14 months across regional suppliers. Rhône-Alpes supplier networks capture dedicated EV lighting assembly contracts as French battery-platform mandates accelerate.
Provence-Alpes-Côte d'Azur
Luxury nameplate demand above EUR 80,000 concentrates in this coastal region, justifying OLED rear-lamp differentiation despite yield-limited economics. RoHS restrictions on hazardous substances in electronics govern discharge lamp phase-outs across regional distribution channels. Sophia Antipolis technology park hosts specialized optical design consultancies serving Mediterranean-tier OEM programs.
Hauts-de-France
Entry-segment vehicle production in this northern industrial zone sustains residual halogen demand amid EU efficiency mandate pressures. ECE certification administered by Germany's KBA creates asymmetric compliance burdens for suppliers serving export-oriented assembly plants. Lille-Roubaix manufacturing corridors concentrate durability-focused LED sealed-beam units for commercial fleet operators.
Nouvelle-Aquitaine
Aerospace-to-automotive supplier migration patterns in Bordeaux-Toulouse corridors transfer thermal management expertise into LED packaging operations. EU Green Deal embedded carbon requirements reshape procurement documentation for tier-one contracts across southwestern OEM supply chains. Pau-Bayonne industrial zones develop secondary optics capabilities for compact fog-light modules.
France Automotive LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-heavy photonics producers controlling margin pools in matrix-beam headlamp assemblies while module-dependent assemblers face procurement compression. Three archetypes dominate: vertically capable integrators with captive foundry relationships, algorithm-focused specialists navigating EU AI Act compliance, and scale-driven packaging houses serving volume OEM programs. Competitive moves concentrate on strategic partnerships with GaN substrate foundries and portfolio diversification into vehicle-to-everything communication lighting.
Among integrated European suppliers, Valeo and HELLA GmbH & Co. KGaA exemplify the capital-heavy archetype with sustained margin control across headlamp assembly categories. OSRAM GmbH occupies a position within chip-scale LED architecture supply, anchoring the specialist tier for premium OEM programs. These three entities represent the competitive core around which French tier-one procurement consolidation has tightened since 2022.
| Leading Market Players |
|---|
| Valeo |
| HELLA GmbH & Co. KGaA |
| OSRAM GmbH |
| Marelli Holdings Co., Ltd. |
| Signify |
| ZKW Group |
| Stanley Electric Co., Ltd. |
| Koito Manufacturing Co., Ltd. |
| GRUPO ANTOLIN IRAUSA, S.A. |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate migration from silicon carbide alternatives redraws procurement geography toward East Asian foundry networks while compressing margin structures for French module assemblers locked into legacy sourcing agreements. This substitution dynamic simultaneously elevates pricing power for integrated photonics producers with captive GaN wafer partnerships and erodes position for tier-two suppliers dependent on spot-market chip procurement.
Pricing Analysis
After-sales service contracts and replacement lamp programs anchor lifetime value capture across French OEM supply chains. Three-tier pricing structure across premium matrix-beam, standard LED, and residual halogen levels stratifies according to KBA certification complexity and thermal management sophistication. Cost compression in standard LED modules is intensifying because Stellantis and Renault procurement consolidation has reduced qualified supplier rosters since 2022. Fleet operators and entry-segment buyers exhibit highest price sensitivity, while luxury nameplate programs above EUR 80,000 absorb premium positioning for OLED rear-lamp differentiation.
Supply Chain Analysis
Strategic stockpiling of GaN wafers and polycarbonate lens substrates has displaced just-in-time preferences as French tier-one suppliers buffer against Taiwan and South Korea foundry concentration. Raw material dependencies center on gallium nitride epitaxial wafers, precision-molded polycarbonate optical components, and phosphor formulations for white-light conversion. Single-source vulnerability in advanced GaN substrate supply exposes French assemblers to geopolitical logistics disruption. Distribution runs through Rhône-Alpes module assembly networks into Paris-Saclay OEM integration facilities, with secondary channels serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Automotive LED Lighting Market sits at a regulatory inflection where EU AI Act software validation protocols and EU Green Deal embedded carbon mandates simultaneously reshape competitive viability and procurement qualification criteria.
For Market Incumbents: Fortify margin position through backward integration into GaN substrate sourcing or captive foundry partnerships that insulate against Taiwan supply concentration. Accelerate KBA pre-certification investment for matrix-beam algorithm variants to compress 11-16 month approval queues threatening platform launch schedules. Prioritize thermal management engineering recruitment to address French technical institute output of fewer than 120 optoelectronics packaging specialists annually. For New Entrants and Emerging Players: ECE certification fast-track specialization for adaptive beam software modules offers entry wedge against incumbent algorithm portfolios. Target Rhône-Alpes underutilized photonics infrastructure for matrix-beam packaging capacity where Grenoble facilities offer captive assembly economics. Pursue vehicle-to-everything communication lighting integration as white-space revenue pool outside incumbent headlamp assembly dominance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated photonics producers with software validation capabilities over module-dependent assemblers. Long-term viability across the analysis window rests on EU AI Act compliance infrastructure and GaN substrate supply security. Watch KBA certification queue compression as signal for tier-one procurement rebalancing toward algorithm-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Captive wafer supply insulates French integrators from Taiwan concentration risk. |
| Matrix-Beam Pre-Certification | Early KBA queue positioning compresses platform launch timelines for Stellantis programs. |
| Thermal Management Recruitment | French technical institute partnerships address optoelectronics specialist scarcity constraining R&D throughput. |
| Software Validation Infrastructure | EU AI Act compliance documentation creates procurement barrier against non-compliant assemblers. |
| V2X Communication Lighting Development | LED array data transmission opens connected mobility revenue beyond illumination function. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution managers, and thermal management R&D leads and refined through secondary validation against vehicle production databases, IHS Markit registration data, KBA type approval filings, and EU regulatory directive texts. Bottom-up volume modeling across headlamp, taillight, and interior LED categories triangulated against top-down OEM procurement spend analysis.
Variance decomposition separated volume growth drivers from pricing dynamics across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, OEM tier positioning, content per vehicle tier, and regional production cluster concentration. CAGRs were derived from fitted growth curves calibrated to platform refresh cycles and regulatory phase-out timelines. Industry-specific forecast inputs incorporated battery-electric vehicle adoption curves and EU Green Deal carbon accounting implementation schedules.
Underlying assumptions cover GaN substrate supply continuity, KBA certification throughput stability, and REACH lens coating compliance timeline adherence, with deviation risk concentrated in Taiwan geopolitical disruption and EU AI Act software validation framework maturity. Revision becomes warranted when KBA queue durations or GaN spot pricing volatility cross thresholds that materially alter tier-one supplier procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East Smart Home Market
Others
Bimodal Identity Management Solutions Market
Others
Global Hydraulics Market
Others
Smartphone Gimbal Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Post Consumer Recycled Bottles Market
Others
Embedded Computer Market
Others
Connected TV Market
Others
Global Smart Kitchen Market
Others
Global Magnetic Flow Meters Market
Others
Communication Base Station Body Market
Others
Tobacco Packaging Market
Others
Latin America Fire Sprinklers Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Mobile Computer Cart Market
Others
Dried Fruit Extracts Market