
 Augmented Reality in Energy and Utilities Market | 2026-2036
Augmented Reality in Energy and Utilities Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality in Energy and Utilities Market Outlook
Multi-source AR procurement is broadening as energy operators diversify beyond single-vendor smart-glass contracts. PTC anchors industrial software integration through its ThingWorx platform for utility asset visualization. RealWear competes with ruggedized voice-controlled headsets designed for hazardous electrical environments. Vuzix specializes in waveguide optics that sustain readability under direct sunlight on solar farms and transmission towers.
Augmented reality in energy and utilities overlays digital information onto physical infrastructure through spatial computing, enabling technicians to visualize buried cable maps, thermal sensor data, and step-by-step repair protocols via transparent displays or camera-fed mobile screens. Smart glasses and head-mounted displays capture the deepest margin pools where hardware-software bundling locks in utility procurement cycles. Remote assistance applications are expanding fastest as oil majors and renewable operators reduce expert travel to offshore platforms and remote wind sites. Markerless tracking technology leads adoption in outdoor energy settings where environmental markers degrade or disappear.
FAA guidelines govern AR drone integration for aerial power-line inspection in the United States, while OSHA mandates govern wearable device safety certification for electrical workers. The EU AI Act imposes risk-classification requirements on automated AR decision-support systems deployed across European grid networks. EMEA utilities must reconcile CE marking for hardware with GDPR constraints on biometric data capture from headset cameras. Stakeholders should monitor whether emerging national cybersecurity frameworks for critical infrastructure will mandate sovereign data residency for AR cloud backends serving nuclear and grid operations.
Market Dynamics
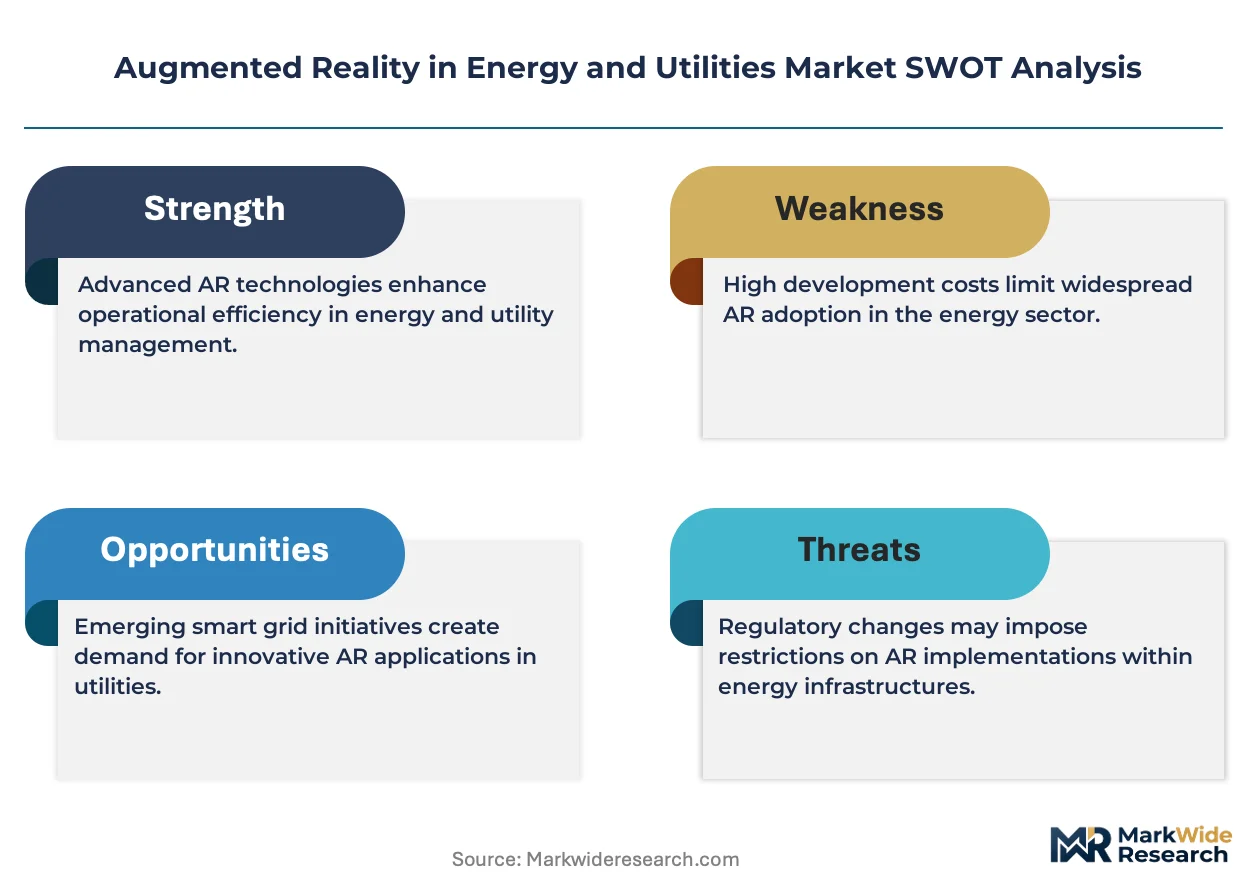
Utility procurement cycles for AR hardware-software bundles are compressing as grid operators accelerate field technician guidance deployments under tightening OSHA electrical-safety mandates and EU AI Act risk-classification requirements.
Growth Catalysts
- OSHA Wearable Certification:United States electrical-safety mandates for head-mounted displays in hazardous environments are accelerating utility procurement of certified AR hardware for substation maintenance crews.
- Offshore Wind Expansion:Remote assistance applications for offshore platform technicians are displacing expert travel as North Sea and Atlantic Coast operators prioritize downtime reduction.
- Markerless Tracking Maturation:Computer vision advances enabling environmental-agnostic spatial mapping are unlocking outdoor transmission tower and solar farm deployments where physical markers degrade.
Market Restraints
- Waveguide Optics Cost Concentration:Specialized optical component supply concentrates among Asian precision manufacturers, creating input cost volatility for sunlight-readable display modules.
- Biometric Data Friction:GDPR constraints on headset camera footage capture impose compliance architecture costs for European utilities deploying facial-recognition-enabled remote assistance.
- Legacy SCADA Integration:Proprietary utility data protocols require custom middleware development, extending deployment timelines for AR visualization of real-time asset telemetry.
Strategic Opportunities
- India Grid Modernization:Central Electricity Authority mandates for distribution automation create first-mover positioning for AR-assisted rural substation commissioning and workforce training.
- Digital Twin Convergence:Integration of AR overlays with physics-based asset simulations enables predictive maintenance visualization for transformer fleets and pipeline integrity management.
- Subscription Licensing Models:SaaS-based remote assistance platforms are displacing perpetual software licenses, reducing upfront capital barriers for mid-sized municipal utilities.
Industry Challenges
- Field Technician Upskilling:Spatial computing interfaces require retraining programs for electrical workers accustomed to paper schematic workflows, compressing effective deployment windows.
- Multi-Jurisdiction Certification:CE marking, FCC authorization, and ATEX hazardous-area approvals must align for cross-border utility fleets, fragmenting product launch sequencing.
- Cloud Backend Sovereignty:Emerging national cybersecurity frameworks for critical infrastructure may mandate domestic data residency for AR platforms serving nuclear generation and transmission control centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality in Energy and Utilities Market |
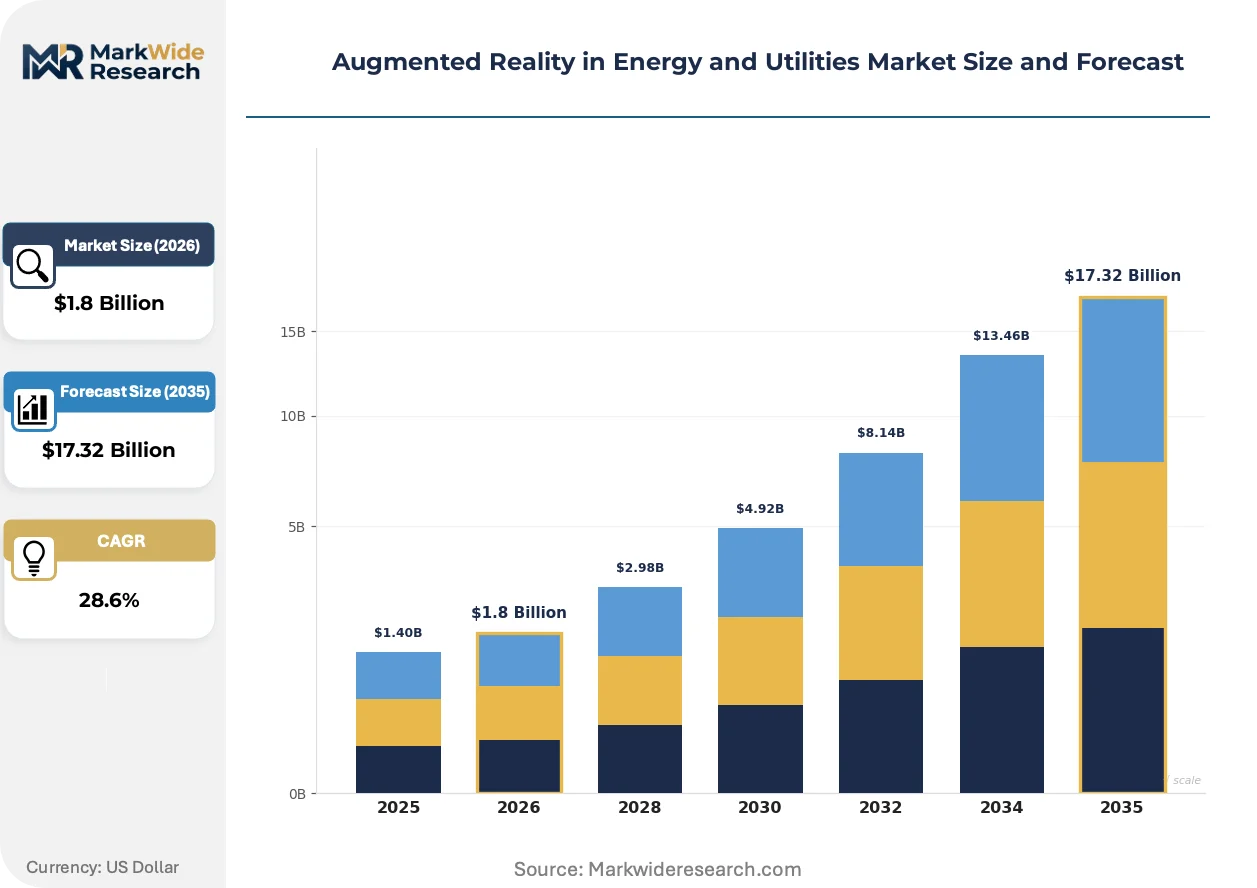
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Mobile Applications, Software Solutions, Head-Mounted Displays Application: Maintenance, Training, Remote Assistance, Asset Management End User: Utilities Providers, Oil & Gas Companies, Renewable Energy Firms, Industrial Enterprises Technology: Marker-Based, Markerless, Projection-Based, Superimposition |
| Companies Covered | Magnopus, RealWear, PTC, ThirdEye Gen, TeamViewer, Treeview, Vuzix, Unity Technologies, Lucid Reality Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality in Energy and Utilities Market Strategic Shifts
Spatial computing architectures are fragmenting into specialized form factors as energy operators reject one-size-fits-all hardware strategies. Three convergent developments are compressing vendor margins while expanding addressable use cases.
Edge-native AR software stacks are modularizing deployment architectures for utility field operations. Lightweight containerized applications now run on headset-local processors without continuous cloud connectivity, enabling substation technicians to access cable maps and thermal overlays inside Faraday-caged environments. German grid operators are piloting these disconnected-capable systems for electromagnetic-sensitive switchgear maintenance.
The EU AI Act's risk-classification framework is restructuring vendor compliance roadmaps for automated decision-support features. High-risk categorization for AR systems providing real-time repair protocols triggers conformity assessment requirements that smaller software providers cannot absorb. European transmission system operators are consolidating procurement around platforms with pre-certified algorithmic transparency documentation.
Outcome-guaranteed service contracts are displacing hardware-centric procurement for remote assistance deployments. Oil majors and offshore wind operators now demand uptime-based pricing tied to mean-time-to-repair reductions rather than per-seat software licenses. This shift concentrates vendor risk while accelerating adoption among capital-constrained renewable operators in the North Sea and Gulf of Mexico.
Augmented Reality in Energy and Utilities Market Segmentation
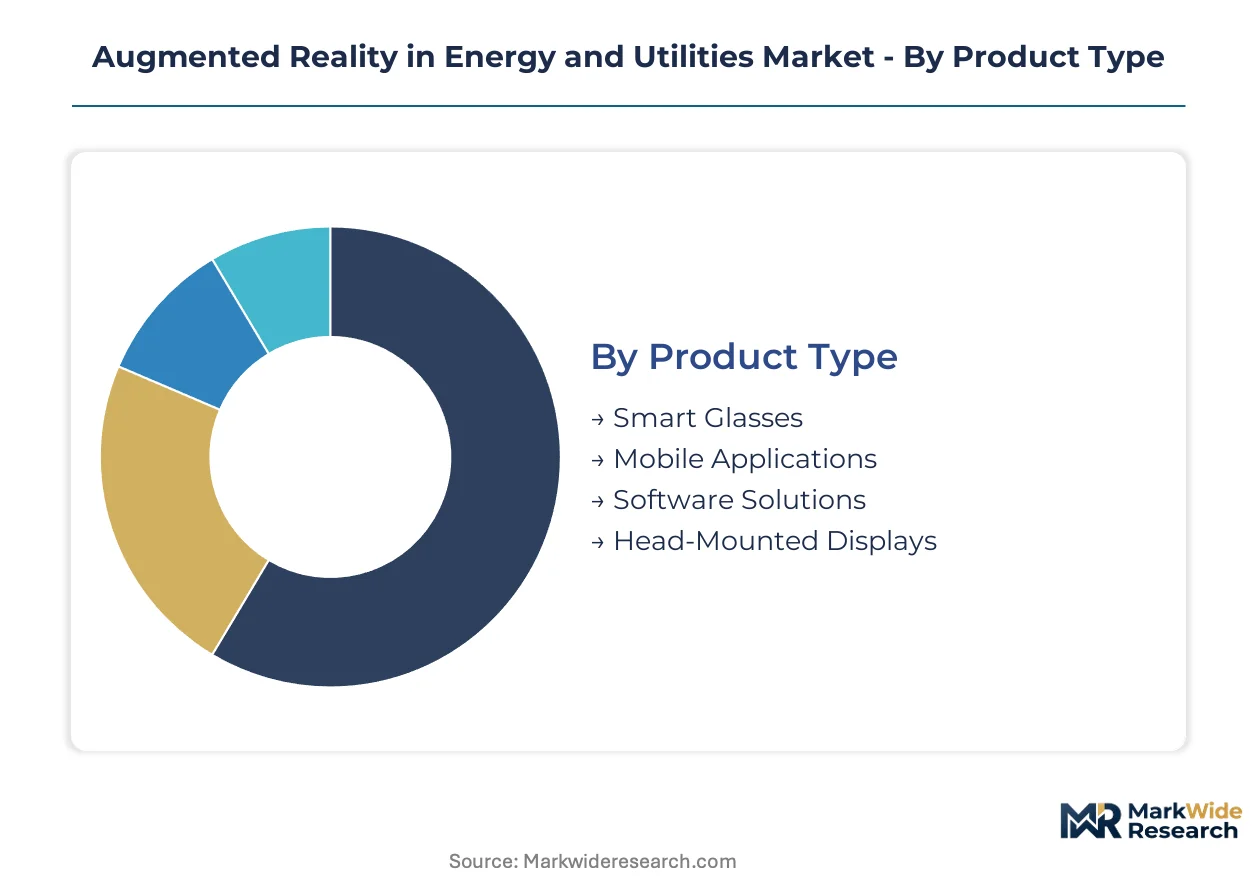
Segmentation in AR energy deployments reveals how hardware-software bundling and use-case specificity determine procurement patterns. Utility operators select form factors based on electromagnetic exposure, connectivity constraints, and technician workflow integration.
Product Type:
Upgrade cycles for field hardware are compressing as OSHA mandates and EU AI Act compliance deadlines force simultaneous software-hardware refreshes across utility fleets.
- Smart Glasses:Transparent waveguide displays enable hands-free schematic overlay during live electrical work. German grid operators pilot these for substation maintenance where electromagnetic interference demands localized processing.
- Head-Mounted Displays:Ruggedized voice-controlled units dominate hazardous-area certifications for oil platform technicians. North Sea operators deploy these for remote expert guidance without removing protective equipment.
- Mobile Applications:Camera-fed smartphone AR reduces capital barriers for municipal utilities with limited smart-glass budgets.
- Software Solutions:SaaS remote assistance platforms displace perpetual licenses through outcome-based pricing tied to repair-time reduction.
Smart glasses sit at the top of the volume ranking, with head-mounted displays climbing the fastest as offshore wind expansion accelerates hazardous-environment procurement.
Application:
Cost-tier differentiation separates capital-intensive predictive systems from operational expense-driven remote support tools across utility budgeting structures.
- Remote Assistance:Real-time video streaming with spatial annotation eliminates expert travel to offshore platforms and remote wind sites. Oil majors in the Gulf of Mexico prioritize this for subsea equipment troubleshooting.
- Maintenance:Step-by-step repair protocols overlay thermal sensor data and cable maps onto physical infrastructure. Field technicians access buried asset visualization without paper schematics.
- Training:Simulated hazardous scenarios reduce live-environment risk for apprentice electrical workers.
- Asset Management:Digital twin integration enables predictive visualization for transformer fleet monitoring.
Remote assistance dominates current procurement volumes, while maintenance applications gain share fastest as markerless tracking matures for outdoor transmission environments.
End User:
Customer-type fragmentation reflects divergent regulatory exposure and capital availability across energy sector verticals.
- Utilities Providers:Transmission and distribution operators face OSHA electrical-safety mandates and EU AI Act risk-classification requirements. Procurement concentrates around certified hardware-software bundles for substation crews.
- Oil & Gas Companies:Offshore platform operators demand ATEX-certified devices with satellite connectivity backup. Expert travel reduction drives remote assistance prioritization.
- Renewable Energy Firms:Wind and solar operators favor markerless tracking for outdoor environments where physical markers degrade.
- Industrial Enterprises:Captive power generation facilities adopt AR for internal maintenance workforce development.
Utilities providers anchor current demand volumes, with renewable energy firms expanding most quickly as rural solar and wind installations proliferate.
Technology:
Technology maturity curves determine deployment feasibility across electromagnetic-sensitive and environmentally exposed energy infrastructure.
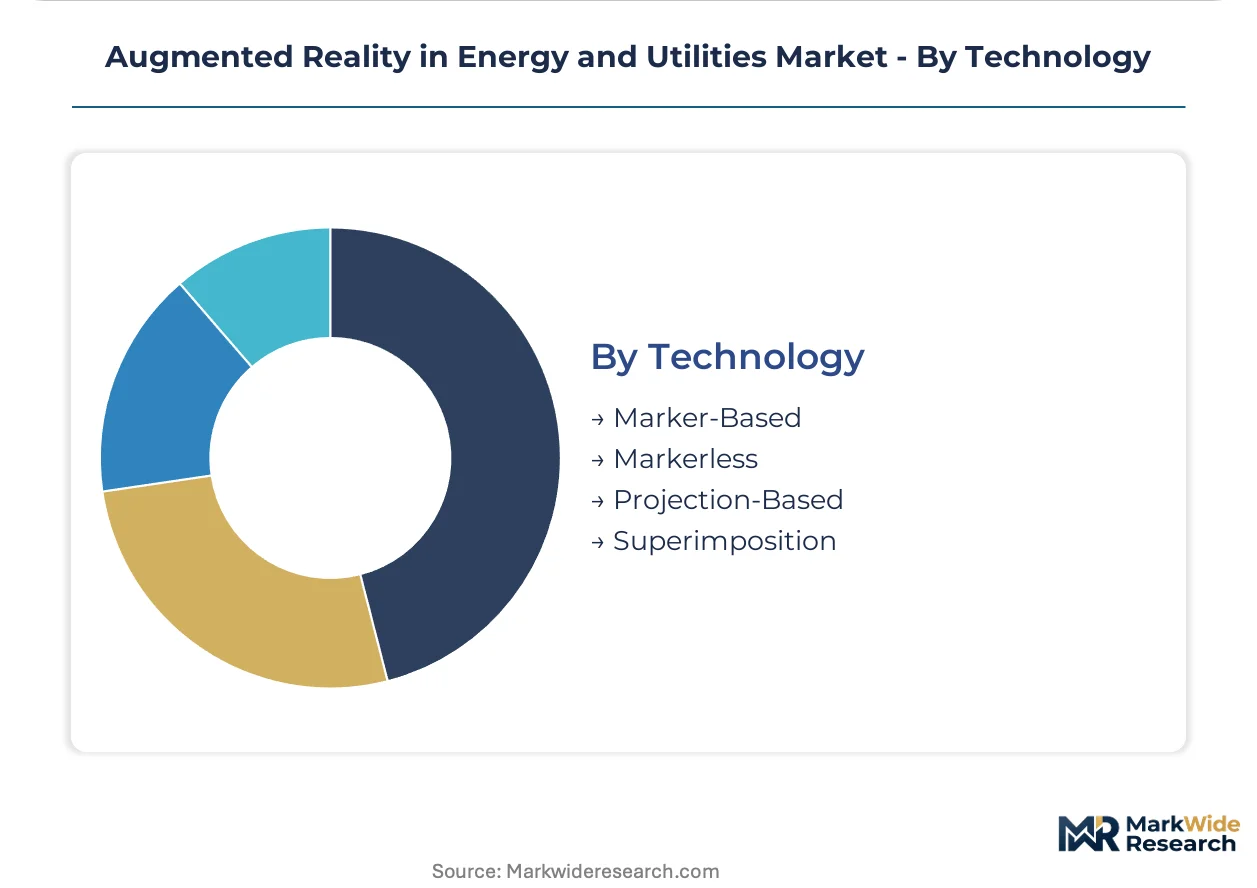
- Markerless Tracking:Environmental-agnostic spatial mapping unlocks outdoor transmission tower and solar farm deployments. Computer vision advances eliminate dependency on physical markers that degrade in weather exposure.
- Marker-Based:QR and fiducial marker systems retain niche utility in controlled indoor training environments.
- Projection-Based:Spatial light projection onto physical surfaces enables collaborative maintenance review without individual headset distribution.
- Superimposition:Real-time 3D model overlay integrates with SCADA telemetry for asset condition visualization.
Markerless tracking leads technology adoption volumes, with superimposition climbing fastest as digital twin convergence accelerates predictive maintenance visualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German grid operators anchor AR deployment volumes through substation maintenance pilots, while regulatory divergence across major economies fragments vendor certification roadmaps and compresses procurement timelines for field hardware.
United States
OSHA electrical-safety mandates for head-mounted displays accelerate utility procurement of certified AR hardware for substation crews. FAA guidelines govern AR drone integration for aerial power-line inspection across transmission networks. Gulf of Mexico oil majors prioritize remote assistance applications for subsea equipment troubleshooting without expert travel.
Germany
Transmission system operators consolidate procurement around platforms with pre-certified algorithmic transparency documentation under EU AI Act risk-classification requirements. CE marking for hardware must reconcile with GDPR constraints on biometric data capture from headset cameras. Bavarian grid operators pilot edge-native AR software stacks for electromagnetic-sensitive switchgear maintenance inside Faraday-caged environments.
China
Dual carbon goals and grid modernization investments drive AR-assisted workforce training for rural substation commissioning. MIIT standards for industrial wearable devices shape domestic hardware certification requirements. Yangtze River Delta utilities evaluate markerless tracking systems for outdoor transmission tower deployments where environmental markers degrade.
India
Central Electricity Authority mandates for distribution automation create first-mover positioning for AR-assisted field technician guidance. BIS certification requirements for electronic safety equipment filter procurement toward ruggedized voice-controlled headsets. Maharashtra and Gujarat grid operators pilot thermal overlay visualization for transformer fleet monitoring in high-temperature operational environments.
United Kingdom
North Sea offshore wind operators demand ATEX-certified devices with satellite connectivity backup for platform maintenance. GDPR compliance architecture costs constrain facial-recognition-enabled remote assistance deployment across transmission networks. Scottish renewable operators favor outcome-guaranteed service contracts tied to mean-time-to-repair reductions rather than perpetual software licenses.
Augmented Reality in Energy and Utilities Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized optical components and edge-native software architectures. The vendor base stratifies across industrial software integrators, ruggedized hardware specialists, and spatial computing engine providers. Three archetypes dominate: platform-anchored system integrators, component-focused optical engineers, and verticalized remote-assistance SaaS operators. Consolidation pressure concentrates around M&A activity targeting middleware capabilities and strategic partnerships bridging SCADA protocol integration gaps.
Within the platform-anchored tier, PTC exemplifies industrial software integration through utility asset visualization architectures. RealWear and Vuzix occupy positions across the hardware-specialist spectrum, with the former representing ruggedized voice-controlled headset engineering and the latter anchoring waveguide optics development for sunlight-readable display modules. These three entities collectively illustrate how hardware-software bundling locks in utility procurement cycles across electromagnetic-sensitive and environmentally exposed energy infrastructure.
| Leading Market Players |
|---|
| Magnopus |
| RealWear |
| PTC |
| ThirdEye Gen |
| TeamViewer |
| Treeview |
| Vuzix |
| Unity Technologies |
| Lucid Reality Labs |
| Others |
Value Chain & Pricing Dynamics
Edge-native AR software modularization is compressing hardware-software bundling economics while redistributing margin capture toward specialized optical component suppliers. German grid operators now demand disconnected-capable systems for Faraday-caged substations, forcing vendors to absorb certification costs across smaller production runs.
Pricing Analysis
Waveguide optics cost pass-through from Asian precision manufacturers drives hardware tiering across utility procurement cycles. Pricing stratifies across ATEX-certified premium headsets, OSHA-compliant standard units, and mobile application economy tiers. Cost compression in standard-tier hardware intensifies as RealWear and Vuzix expand ruggedized voice-controlled production. Municipal utilities exhibit highest price sensitivity, while offshore oil majors prioritize uptime guarantees over per-seat economics.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and China's MIIT standards for industrial wearables are reshaping component sourcing for Western AR vendors. Waveguide optics and thermal sensor modules draw from Taiwan, South Korea, and Japan. Single-source vulnerability concentrates in specialized optical foundries serving sunlight-readable display requirements. Distribution runs through utility procurement consortia and oil major framework agreements rather than open channel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act risk-classification timelines compress compliance investment windows for vendors relative to OSHA's phased electrical-safety mandates, creating arbitrage opportunities for first-movers in European transmission system operator procurement.
For Market Incumbents: Hedge waveguide optics supply exposure through dual-sourcing agreements with Taiwanese and South Korean precision manufacturers. Accelerate pre-certified algorithmic transparency documentation for EU AI Act high-risk categorization before smaller competitors absorb conformity assessment costs. Lock in multi-year hardware-software bundles with German grid operators piloting edge-native architectures. For New Entrants and Emerging Players: Capture India's rural substation commissioning segment where Central Electricity Authority mandates outpace incumbent localization timelines. Target Maharashtra and Gujarat thermal overlay pilots with SaaS-based remote assistance platforms priced below perpetual license alternatives. Pursue outcome-guaranteed contracts tied to mean-time-to-repair reductions rather than per-seat models. For Investors and Strategic Acquirers: Valuations sit cheapest among middleware specialists bridging SCADA protocol integration gaps for legacy utility telemetry systems. Long-term viability centers on vendors with pre-certified EU AI Act documentation and ATEX hazardous-area approvals spanning multiple jurisdictions. Watch for emerging national cybersecurity frameworks mandating sovereign data residency as inflection triggers for domestic cloud backend consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Software Modularization | Enables Faraday-caged substation deployments for German grid operators without continuous cloud connectivity. |
| EU AI Act Pre-Certification Investment | Locks in high-risk conformity assessment ahead of smaller competitors facing documentation barriers. |
| Dual-Source Waveguide Optics Agreements | Mitigates Taiwan-South Korea supply concentration for sunlight-readable display module inputs. |
| Outcome-Guaranteed Service Contracts | Aligns vendor incentives with North Sea offshore wind operator uptime targets. |
| SCADA Middleware Acquisition | Bridges proprietary utility data protocol gaps that extend AR telemetry visualization timelines. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining utility planning officers, AR platform engineers, grid operator procurement leads, and EPC contractors with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up and top-down triangulation cross-checks hardware shipment estimates against software license recognition patterns.
Rate-of-change decomposition separates hardware replacement cycles from software subscription ramps across the analysis window. Segmentation dimensions include product type, application, end user, and technology maturity tier. CAGRs derive from utility capital expenditure trajectories, OSHA mandate implementation phases, and offshore wind installation forecasts without year-specific anchoring.
Regulatory timeline acceleration, supply chain chokepoint formation, and cybersecurity framework emergence are the dominant revision risks for forecast trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Post Consumer Recycled Bottles Market
Others
Europe Military 4D Printing Market
Others
Finished Leather Market
Others
North America Micro Market
Others
Smart Home Technologies Market
Others
Idaas Market
Others
Global Microcontroller Embedded Systems Market
Others
Japan Indoor LBS Market
Others
Global Aircraft Lighting Systems Market
Others
Conditional Access System (CAS) Market
Others
Underwater Lighting Market
Others
Global Sportswear Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
North America Flexographic Printing Market
Others
Digital Audio Decoders Market
Others
Fluorite Market