
 Global OTA Testing Market | 2026-2036
Global OTA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global OTA Testing Market Outlook
The capital-intensity divergence between anechoic chamber infrastructure and software-defined testing platforms is unwinding competitive dynamics across the OTA testing landscape. Rohde & Schwarz leverages its integrated signal generation and analysis portfolio to dominate high-end cellular conformance testing. Keysight Technologies anchors its position through advanced channel emulation capabilities that support 5G millimeter-wave validation. Bluetest AB specializes in compact reverberation chamber systems that compete on throughput efficiency for mass-market device certification.
Over-the-air testing evaluates wireless device radiated performance by measuring transmitter and receiver characteristics in controlled electromagnetic environments, typically within anechoic or reverberation chambers calibrated from 400 MHz to 90 GHz depending on the wireless protocol under evaluation. This discipline ensures that antennas, RF front-ends, and baseband algorithms meet specified total radiated power and total isotropic sensitivity thresholds before commercial deployment. Cellular testing commands the largest revenue pool within the technology dimension, driven by carrier certification mandates for 5G NR and legacy LTE devices. Wi-Fi OTA validation is accelerating fastest as Wi-Fi 6E and Wi-Fi 7 deployments expand in enterprise access points and consumer routers, while Bluetooth testing occupies a mature margin position sustained by wearable and hearing-aid volume.
The FCC enforces Part 15 and Part 27 radiated emission rules that shape device approval pathways for the US market, while CE marking under the Radio Equipment Directive governs European market access and ETSI harmonized standards. China's MIIT issues mandatory type-approval certificates through SRRC testing that foreign vendors must navigate for domestic commercialization. Stakeholders must monitor how regional spectrum reallocations and evolving MIMO test methodologies reshape capital deployment priorities across laboratory networks.

Market Dynamics
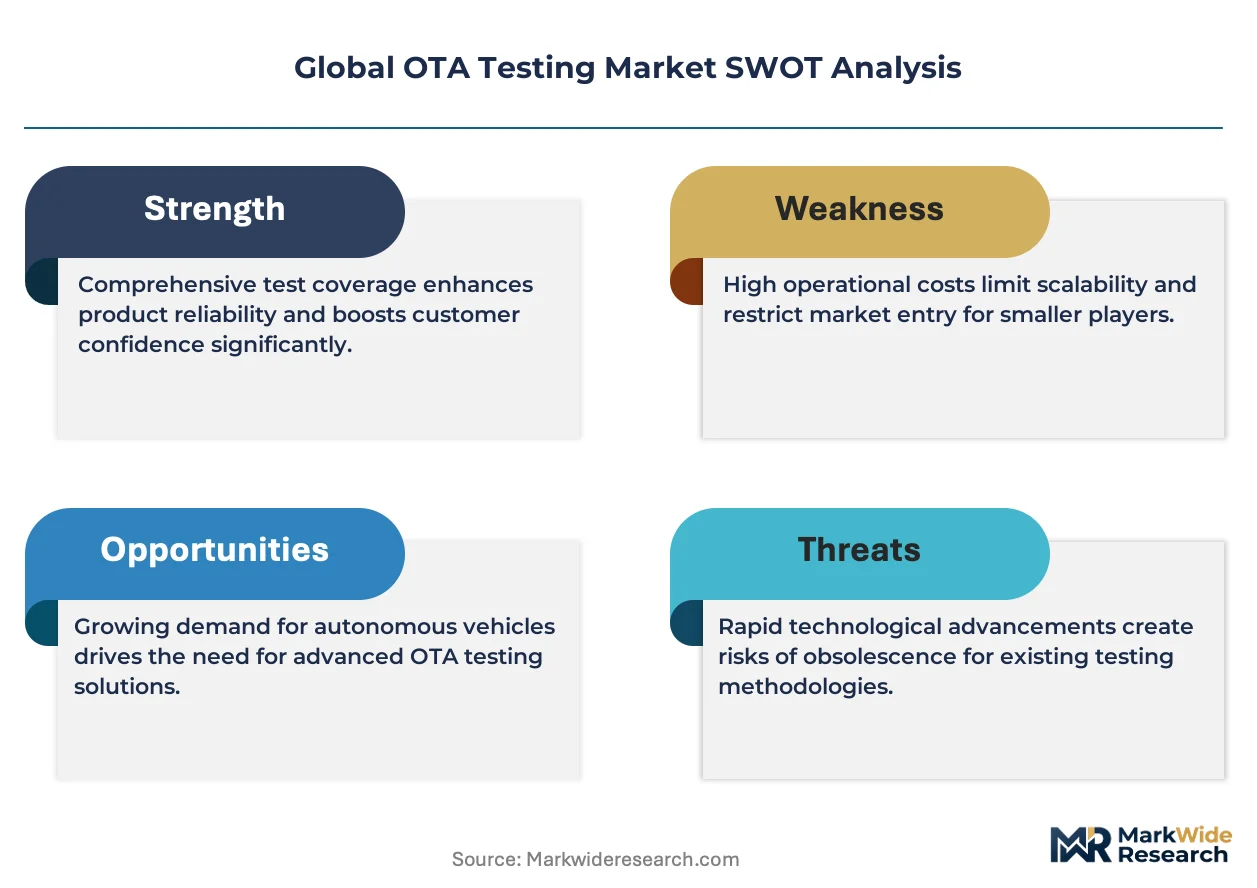
The proliferation of 5G millimeter-wave and Wi-Fi 7 protocols is fragmenting testing demand between legacy sub-6 GHz validation and new spectrum bands requiring upgraded chamber infrastructure and channel emulation capabilities.
Growth Catalysts
- Carrier Certification Mandates:FCC Part 27 and CE marking under the Radio Equipment Directive enforce total radiated power and total isotropic sensitivity thresholds for 5G NR devices, compelling manufacturers to maintain captive OTA testing programs.
- Automotive Connected Platforms:German and Japanese automotive manufacturers are expanding validation programs for vehicle-to-everything communication modules, creating sustained demand for anechoic chamber capacity.
- China Domestic Laboratory Buildout:Smartphone brands and IoT module vendors in China are constructing in-house testing facilities to reduce third-party dependency and accelerate product iteration cycles.
Market Restraints
- Anechoic Chamber Capital Intensity:Absorber materials and precision positioning systems require substantial upfront investment, limiting laboratory expansion to well-capitalized equipment vendors and large device manufacturers.
- Absorber Supply Concentration:Specialized pyramidal absorber production concentrates among a handful of European and Japanese material suppliers, creating input cost volatility and lead time risk.
- Frequency Range Technical Limitation:Existing chamber calibration protocols face signal integrity degradation above 90 GHz, constraining validation capabilities for emerging terahertz communication research.
Strategic Opportunities
- India Device Manufacturing:PLI scheme incentives for electronics manufacturing are attracting smartphone and IoT module assembly, yet domestic OTA testing infrastructure remains underdeveloped relative to production scale.
- Software-Defined Testing Convergence:Integration of vector signal generators with cloud-based analytics platforms enables remote test orchestration and reduces physical chamber occupancy requirements.
- Medical Device Wireless Integration:FDA guidance on wireless coexistence for connected implantables and hearing aids is expanding addressable testing demand beyond traditional consumer electronics.
Industry Challenges
- Millimeter-Wave Calibration Expertise Gap:Technician proficiency in probe positioning and path loss compensation at frequencies above 28 GHz remains scarce, extending test campaign timelines and raising labor costs.
- Multi-Protocol Certification Complexity:Devices supporting simultaneous cellular, Wi-Fi, Bluetooth, and ultra-wideband require sequential or parallel testing across multiple chamber configurations, compressing laboratory throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OTA Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, IoT Devices Technology: Wi-Fi, Bluetooth, Cellular, NFC End User: Telecommunications, Automotive, Consumer Electronics, Industrial Service Type: Consulting, Testing, Support, Implementation |
| Companies Covered | Rohde & Schwarz, Keysight Technologies, Anritsu, SGS SA, Intertek Group plc, UL LLC, Bluetest AB, ETS-Lindgren, TÜV Rheinland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OTA Testing Market Strategic Shifts
Testing methodologies are converging around throughput efficiency and spectral flexibility as device complexity outpaces traditional chamber-based validation timelines. Three developments are restructuring competitive positioning.
Reverberation chamber technology is miniaturizing. Compact mode-stirred systems from Swedish specialists now deliver statistically equivalent measurements to anechoic configurations for mass-market device certification. Smartphone and IoT module vendors in East Asia are adopting these systems to quadrify daily test volumes without proportional facility expansion. This compression is miniaturizing the addressable market for traditional large-chamber vendors while expanding accessible testing capacity for mid-tier manufacturers.
CE marking enforcement under the Radio Equipment Directive is tightening harmonized standard interpretations for MIMO over-the-air performance. European notified bodies are rejecting test reports that lack explicit spatial correlation matrix documentation, forcing laboratories to upgrade channel emulation capabilities. Automotive telematics modules and industrial IoT gateways face the steepest compliance cost escalation as they deploy higher-order antenna arrays.
Device manufacturers are unbundling certification testing from product development cycles. Procurement teams now contract fixed-price validation packages spanning multiple regulatory domains rather than per-hour chamber rental. This preference compression is displacing traditional time-and-materials laboratory relationships with outcome-based certification partnerships, most visibly among Shenzhen and Dongguan electronics clusters serving export markets.
Global OTA Testing Market Segmentation
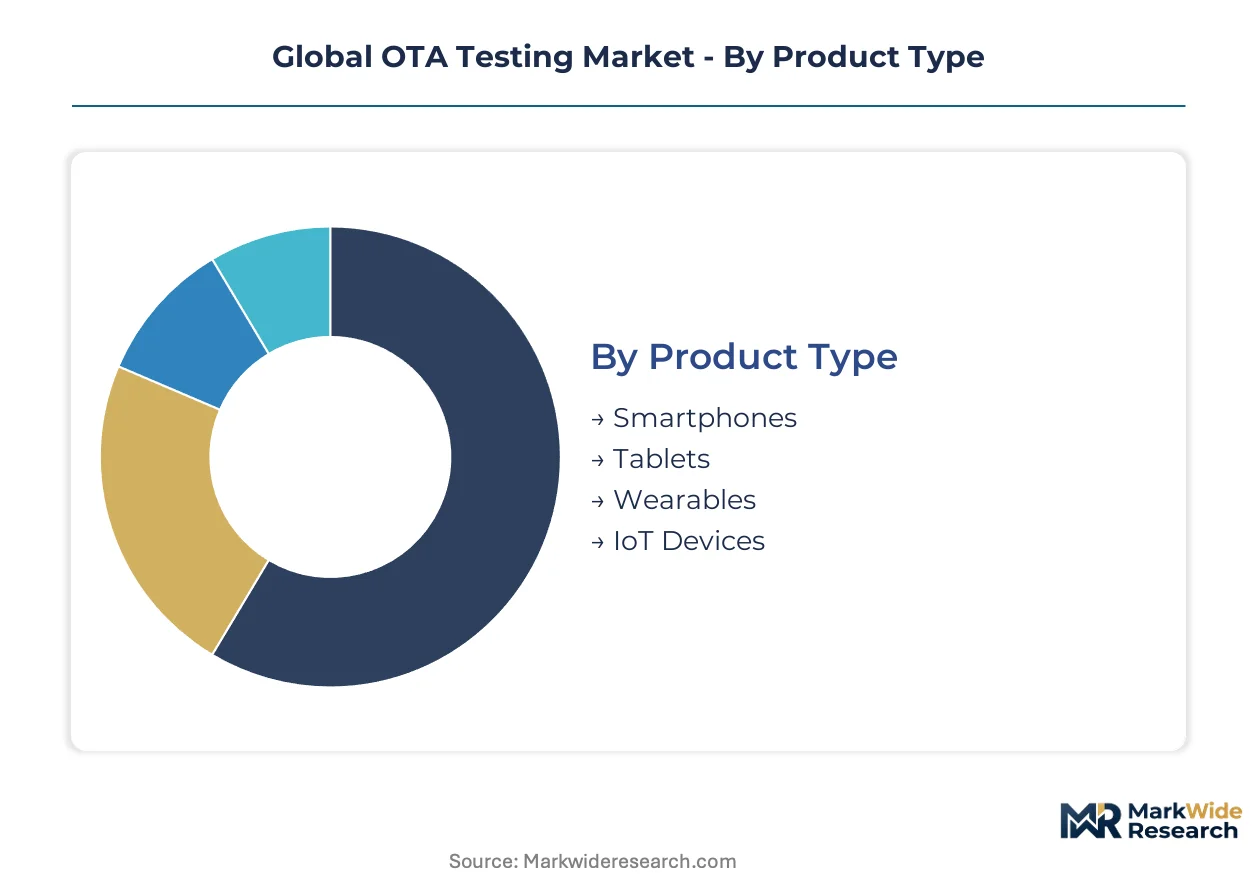
OTA testing demand fragments across device categories, wireless protocols, and service delivery models. Each segment exhibits distinct chamber utilization patterns and regulatory certification pathways that reshape laboratory capacity planning and vendor positioning.
Product Type:
Smartphone validation concentrates in Shenzhen, Dongguan, and Shanghai captive facilities serving export markets, while wearables and IoT devices increasingly route through domestic laboratories in Germany and Japan for automotive integration.
- Smartphones:5G NR and Wi-Fi 7 multi-antenna configurations demand large anechoic chamber capacity with millimeter-wave probe arrays. Carrier certification mandates from FCC Part 27 and CE marking enforcement compress development timelines for flagship launches.
- Tablets:Enterprise and education procurement cycles sustain steady validation volumes. Testing protocols emphasize Wi-Fi 6E coexistence with cellular bands in compact form factors that challenge antenna isolation design.
- Wearables:Hearing aids and fitness trackers drive Bluetooth LE and ultra-wideband validation. FDA wireless coexistence guidance for connected implantables expands addressable testing scope beyond consumer electronics.
- IoT Devices:Industrial sensors and smart home modules prioritize cost-efficient reverberation chamber certification. Chinese module vendors build captive laboratories to accelerate iteration cycles for export markets.
Smartphones hold the largest share; momentum sits with IoT devices as industrial deployment scales.
Technology:
Cellular and Wi-Fi protocols command premium chamber infrastructure investments, while Bluetooth and NFC validation compress into compact test systems with lower capital barriers.
- Wi-Fi:Wi-Fi 6E and Wi-Fi 7 spectrum expansion at 6 GHz and 7 GHz forces chamber recalibration and channel emulation upgrades. Enterprise access point vendors in Taiwan and South Korea drive fastest protocol adoption.
- Cellular:5G millimeter-wave testing above 28 GHz requires precision positioning systems and path loss compensation expertise that remains scarce. Carrier mandates from FCC, CE marking, and China MIIT sustain mandatory certification spend.
- Bluetooth:Audio streaming and hearing-aid applications sustain mature validation volumes. Compact reverberation systems from Swedish specialists capture mid-tier manufacturer demand.
- NFC:Payment and access control modules require near-field probe configurations with limited chamber footprint. European automotive keyless entry systems sustain specialized test demand.
Cellular commands the largest revenue pool; Wi-Fi is expanding most quickly as enterprise deployment accelerates.
End User:
Telecommunications and automotive sectors anchor capital-intensive anechoic chamber investments, while consumer electronics and industrial segments adopt throughput-optimized reverberation alternatives.
- Telecommunications:Base station and network equipment validation demands multi-probe systems for massive MIMO beamforming characterization. Ericsson and Nokia supply chains in Finland and Sweden sustain Nordic laboratory specialization.
- Automotive:Vehicle-to-everything modules from German and Japanese manufacturers require anechoic chambers with vehicle-scale positioning rigs. KBA type approval and UNECE regulations enforce radiated performance thresholds.
- Consumer Electronics:Smartphone, tablet, and router vendors in China's Pearl River Delta cluster certification programs. Fixed-price validation packages displace traditional time-and-materials laboratory relationships.
- Industrial:Smart factory and logistics IoT prioritize cost-per-test efficiency over absolute measurement precision. Indian PLI scheme manufacturing buildout strains domestic testing capacity.
Telecommunications holds the largest share; automotive shows the steepest expansion trajectory as connected platforms proliferate.
Service Type:
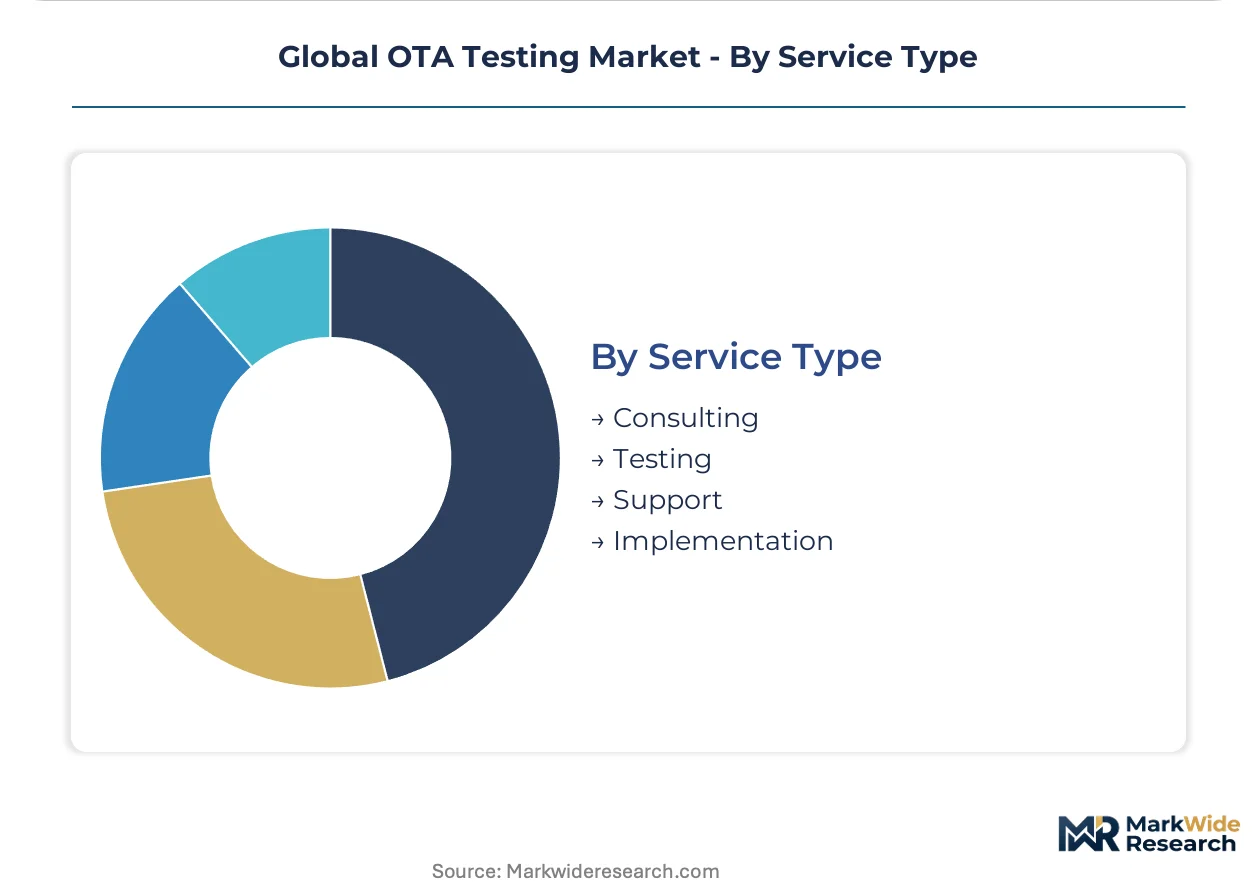
Testing services concentrate revenue in equipment vendors and specialized laboratories, while consulting and implementation functions fragment across engineering consultancies and system integrators.
- Testing:Chamber rental and certification execution generates recurring revenue from device manufacturers. CE marking enforcement under Radio Equipment Directive tightens documentation requirements for MIMO spatial correlation matrices.
- Consulting:Antenna design and regulatory strategy advisory supports early-stage product development. European notified body relationships command premium positioning for complex multi-protocol certifications.
- Support:Calibration maintenance and technician training services extend equipment vendor relationships. Millimeter-wave expertise scarcity elevates labor costs for probe positioning and path loss compensation.
- Implementation:Laboratory buildout and chamber integration projects concentrate among German and Japanese material suppliers. Pyramidal absorber supply concentration creates lead time risk for facility expansion.
Testing holds the largest share; consulting is gaining share fastest as regulatory complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Device manufacturers in Germany and Japan absorb premium pricing for anechoic chamber validation, while Chinese smartphone brands and Indian PLI scheme entrants prioritize cost-per-test efficiency in reverberation systems.
United States
FCC Part 15 and Part 27 enforcement sustains mandatory certification spend for 5G NR devices. The Radio Equipment Directive's extraterritorial influence shapes export-oriented testing protocols. Silicon Valley and Austin clusters anchor millimeter-wave R&D programs for base station and network equipment validation.
Germany
Automotive telematics modules from BMW, Mercedes-Benz, and Volkswagen drive vehicle-scale anechoic chamber investments. KBA type approval and UNECE regulations enforce radiated performance thresholds for vehicle-to-everything communication. Stuttgart and Munich host specialized laboratories serving Tier-1 supplier networks.
China
MIIT's SRRC mandatory type-approval certificates compel foreign vendors to navigate domestic testing pathways. Domestic smartphone brands and IoT module vendors construct captive laboratories to accelerate iteration cycles. Shenzhen, Dongguan, and Shanghai clusters concentrate export-oriented certification programs.
Japan
METI standards harmonization and automotive OEM validation programs sustain demand for precision positioning systems. Toyota, Honda, and Nissan expand connected platform testing for V2X module deployment. Nagoya and Tokyo metropolitan areas concentrate RF front-end characterization expertise.
India
PLI scheme incentives for electronics manufacturing attract smartphone and IoT module assembly without proportional testing infrastructure buildout. The country's national telecommunications regulator mandates equipment certification for commercial deployment. Karnataka and Tamil Nadu manufacturing corridors strain domestic OTA testing capacity.
Global OTA Testing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the OTA testing landscape. Consolidated equipment vendors dominate high-end cellular conformance testing through integrated signal generation portfolios. Tiered laboratory networks fragment across premium anechoic facilities and throughput-optimized reverberation alternatives. Strategic archetypes include integrated test equipment conglomerates, specialized chamber manufacturers, and multi-protocol certification laboratories. Competitive moves concentrate on channel emulation capability upgrades and fixed-price validation package offerings.
Among German-based test equipment conglomerates, Rohde & Schwarz GmbH & Co. KG and TÜV Rheinland AG occupy positions anchoring premium cellular conformance segments. Keysight Technologies Inc. represents the integrated signal analysis archetype with advanced millimeter-wave validation positioning. Swedish specialist Bluetest AB exemplifies the compact reverberation chamber tier competing on mass-market throughput efficiency.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| Keysight Technologies |
| Anritsu |
| SGS SA |
| Intertek Group plc |
| UL LLC |
| Bluetest AB |
| ETS-Lindgren |
| TÜV Rheinland |
| Others |
Value Chain & Pricing Dynamics
Chamber utilization rates above seventy percent in German and Japanese automotive laboratories sustain premium pricing power for anechoic validation services, while Chinese captive facilities compress test-cost floors through reverberation system scale. This divergence concentrates margin capture among integrated equipment vendors serving Tier-1 automotive OEMs and forces third-party laboratories toward fixed-price outcome contracts.
Pricing Analysis
Calibration and maintenance service contracts generate lifetime value multiples exceeding initial chamber hardware sales. Three-tier pricing structure across premium anechoic, standard multi-probe, and economy reverberation levels segments buyers by certification complexity. Cost compression in economy-tier reverberation testing is intensifying because Chinese module vendors quadrify daily throughput without facility expansion. Automotive OEMs exhibit lowest price sensitivity due to KBA and UNECE regulatory non-negotiability, while Indian PLI scheme entrants maximize cost-per-test efficiency.
Supply Chain Analysis
Pyramidal absorber production chokepoints in Germany and Japan constrain global chamber expansion timelines regardless of downstream demand signals. Specialized ferrite and foam absorber formulations draw from carbon-black feedstock and precision machining capabilities concentrated in European and East Asian material suppliers. Single-source vulnerability for millimeter-wave probe arrays elevates lead time risk for laboratories targeting 5G NR above 28 GHz. Distribution runs through direct equipment vendor relationships for high-end cellular conformance and regional distributor networks for compact reverberation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OTA testing market exhibits cyclical recovery characteristics as 5G millimeter-wave deployment waves and Wi-Fi 7 upgrade cycles refresh capital equipment demand after sub-6 GHz saturation.
For Market Incumbents: Fortify channel emulation capability moats through software-defined architecture investments that reduce physical chamber dependency. Defensive consolidation of millimeter-wave probe positioning expertise addresses technician scarcity extending test campaign timelines. Priority rests on backward integration into absorber material supply to mitigate European and Japanese supplier concentration risk.
For New Entrants and Emerging Players: Lead with compact reverberation system offerings targeting Indian PLI scheme manufacturing corridors where domestic testing infrastructure lags assembly scale. White-space concentration sits with medical device wireless coexistence validation under FDA guidance expansion. Go-to-market execution should emphasize fixed-price certification packages displacing incumbent time-and-materials relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors channel emulation software specialists over chamber hardware manufacturers as virtualization compresses physical asset intensity. Long-term viability across the analysis window hinges on regulatory mandate durability rather than discretionary R&D spend. Acquisition target archetype: multi-protocol certification laboratories with European notified body relationships. Signal to watch: CE marking enforcement tightening on MIMO spatial correlation documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Channel Emulation Capability Upgrade | Software-defined testing platforms from Rohde & Schwarz reduce physical chamber occupancy requirements. |
| Fixed-Price Validation Package Launch | Outcome-based contracts displace time-and-materials relationships in Shenzhen electronics clusters. |
| Millimeter-Wave Probe Positioning Investment | Precision systems above 28 GHz address technician scarcity compressing test timelines. |
| Absorber Material Backward Integration | In-house pyramidal absorber production mitigates German and Japanese supplier concentration. |
| Medical Device Wireless Coexistence Certification | FDA guidance on connected implantables expands addressable testing beyond consumer electronics. |
Study Parameters
Operator-level perspectives from chamber operations managers, RF test engineers, regulatory affairs leads at device manufacturers, and procurement officers at automotive Tier-1 suppliers anchored the qualitative base. Primary interview intelligence combined with secondary validation from FCC Part 27 enforcement databases, CE marking notified body registries, MIIT SRRC type-approval filings, and ETSI harmonized standard documentation. Bottom-up laboratory capacity modeling and top-down equipment vendor revenue triangulation cross-verified segment sizing.
Sensitivity analysis across chamber utilization assumptions, protocol adoption curves, and regulatory enforcement intensity shaped the analytical framework. Segmentation dimensions modeled include wireless protocol category, device form factor, service delivery model, and end-use industry vertical. CAGRs were derived from installed base replacement cycles and net new facility buildout trajectories. Industry-specific forecast inputs incorporated 5G NR carrier certification mandate schedules and Wi-Fi 6E spectrum allocation timelines.
Underlying assumptions cover regulatory mandate continuity and absorber material supply stability, with deviation risk concentrated in millimeter-wave calibration protocol evolution and India PLI scheme manufacturing acceleration. Practitioners should keep alternative scenarios live as CE marking MIMO documentation requirements and China MIIT foreign vendor pathway adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sound Reinforcement Market
Others
Global Sports and Fitness Wears Market
Others
Textile Composites Market
Others
Gas Holders Market
Others
Bamboo Straws Market
Others
Free Space Optics (FSO) Market
Others
Security Bottles Market
Others
Industrial Computers Market
Others
High Voltage Measuring Equipment Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Global Aircraft Lighting Systems Market
Others
Egg Market
Others
Global Hardware Acceleration Market
Others
Turbo Mills Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Europe Transportation Management Systems Market