
 Czech Republic Market | 2026-2036
Czech Republic Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Market Analysis
Central Bohemia is tilting toward advanced manufacturing capacity as Prague-Ostrava industrial corridors deepen supplier density. Škoda Auto leverages its Mladá Boleslav engineering base to sustain powertrain and EV component development. AGROFERT anchors agrochemical and food processing supply chains across Moravia. ČEZ dominates electricity generation and grid infrastructure, positioning its Temelín and Dukovany nuclear assets as baseload pillars for industrial electrification.
The Czech Republic market encompasses industrial output, consumer goods, energy systems, and financial services produced or delivered within the country's borders, with automotive stamping and precision engineering representing core technical competencies forged through century-old metallurgical traditions. Automotive Parts command structural priority within product type segmentation, reflecting Škoda Auto's Tier-1 supplier ecosystem and the concentration of stamping, forging, and electronics assembly around Mladá Boleslav. Industrial Equipment segments compete for capital allocation as Czech manufacturers automate to offset labor cost pressures from neighboring Germany and Poland. Online Retail distribution channels are capturing share from Brick-and-Mortar networks, though Wholesalers retain leverage in B2B industrial procurement where contract terms and technical service bundling matter.
BIS-equivalent Czech Office for Standards, Metrology and Testing enforces product conformity, while EU REACH and RoHS directives govern chemical content in manufactured goods sold across the single market. The Czech National Bank supervises financial services segments, constraining capital deployment rhythms for banking and insurance sub-sectors. Stakeholders must monitor how EU CSRD disclosure mandates and the F-Gas Regulation reshape compliance costs for energy-intensive and cooling-dependent production lines.
Market Dynamics
The EU Green Deal's decarbonization mandates are restructuring energy-intensive production requirements across Czech industrial corridors, forcing capital reallocation toward electrification and low-carbon process technologies.
Growth Catalysts
- EU Green Deal mandates:Binding emissions targets are accelerating industrial electrification investments. ČEZ's nuclear baseload expansion supports this transition.
- EV powertrain localization:Škoda Auto's engineering base in Mladá Boleslav is pulling precision forging and electronics assembly capacity into Central Bohemia.
- Supplier ecosystem density:Prague-Ostrava industrial corridors concentrate stamping and metallurgical competencies that reduce procurement lead times for automotive OEMs.
Market Restraints
- Input cost volatility:Natural gas and electricity price fluctuations strain energy-intensive metallurgical and chemical processing operations.
- Supply concentration risk:Critical rare earth and battery materials dependence on non-EU sources creates vulnerability in EV component supply chains.
- REACH compliance friction:Chemical content restrictions in manufactured goods add testing and documentation burdens for exporters to the single market.
Strategic Opportunities
- Moravia agrochemical processing:AGROFERT's established supply chains create white space for bio-based fertilizer and sustainable packaging integration.
- Nuclear-to-hydrogen bridging:Temelín and Dukovany baseload capacity enables electrolytic hydrogen production for steel and chemical decarbonization.
- Online Retail channel expansion:Industrial equipment and spare parts e-procurement platforms are capturing share from traditional wholesaler networks.
Industry Challenges
- Automation engineering talent scarcity:Czech manufacturers competing with German and Polish wage premiums face recruitment gaps in robotics integration and PLC programming.
- CSRD disclosure timelines:EU Corporate Sustainability Reporting Directive mandates require new data infrastructure and third-party verification capabilities.
- Legacy equipment interoperability:Brownfield manufacturing sites struggle to integrate Industry 4.0 sensors with decades-old mechanical control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Market |
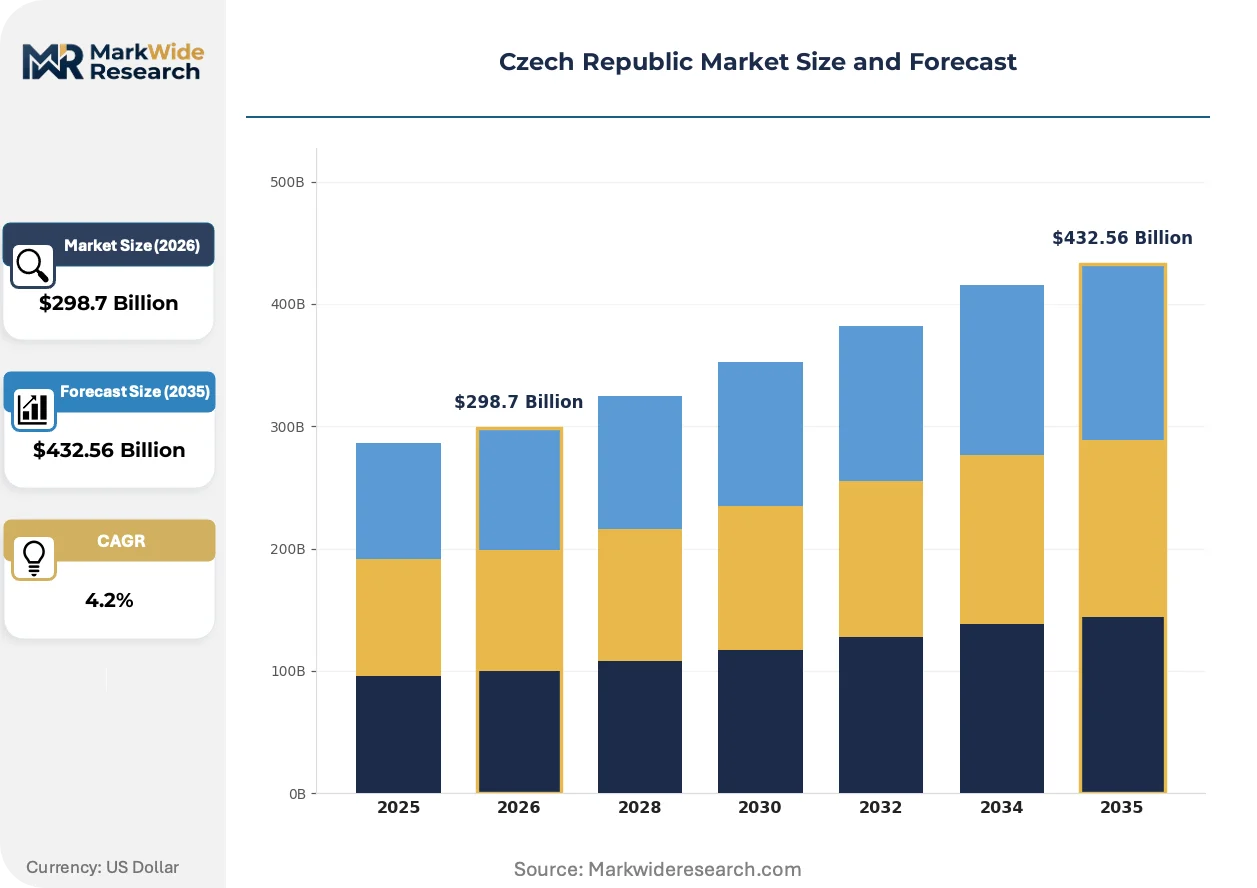
| Market Size in 2026 | $298.7 Billion |
| Market Size in 2035 | $432.56 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Home Appliances, Automotive Parts, Industrial Equipment End User: Households, Manufacturers, Retailers, Service Providers Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Direct Sales Application: Entertainment, Home Improvement, Industrial Production, Transportation |
| Companies Covered | AGROFERT, Škoda Auto, ČEZ, Česká spořitelna, Československá obchodní banka, Komerční banka, MONETA Money Bank, Colt CZ Group, Philip Morris CR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Market Emerging Trajectories
Digital thread technologies and predictive maintenance platforms are compressing equipment downtime across Czech automotive and industrial machinery sectors, while regulatory pressure on embedded carbon intensifies process innovation.
Industrial IoT sensor networks paired with edge computing analytics are digitizing condition monitoring for stamping presses and forging equipment. Tier-1 automotive suppliers in Central Bohemia are deploying these systems at scale. Real-time vibration and thermal data streams are digitizing maintenance scheduling from calendar-based to failure-predictive models.
EU F-Gas Regulation phase-down schedules are forcing refrigeration and cooling-dependent processors toward natural refrigerant retrofits. Food processing facilities across Moravia face accelerated capex cycles. Meat and dairy cold chain operators are responding with ammonia and CO2 system replacements ahead of hydrofluorocarbon quota reductions.
Buyers in the Czech industrial equipment segment are consolidating vendor relationships and demanding outcome-based performance guarantees. Traditional machinery wholesalers with technical service bundling are losing ground to manufacturer-direct digital platforms. This pattern is most visible in precision engineering clusters around Brno and Ostrava.
Czech Republic Market Segmentation
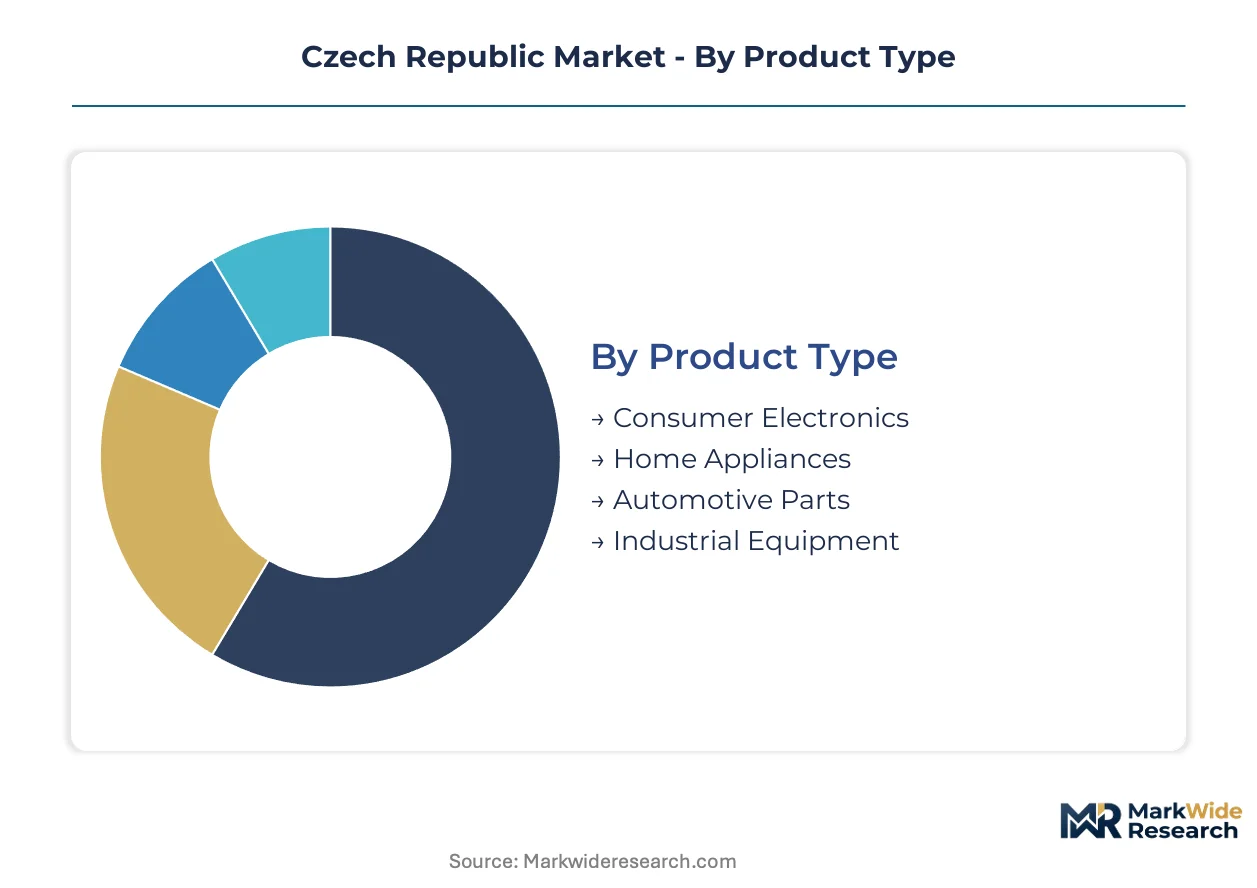
Czech industrial output fragments across distinct procurement logics, each demanding tailored channel strategies and compliance postures. Segmentation clarity determines where capital flows and which regulatory frameworks bite hardest.
Product Type:
Demand spans consumer durables through heavy industrial machinery, with each tier carrying divergent margin profiles and technical certification burdens.
- Automotive Parts:Stamping, forging, and electronics assemblies anchor Central Bohemia's supplier density. Škoda Auto's Tier-1 ecosystem concentrates procurement around Mladá Boleslav, with REACH compliance costs filtering smaller stampers from export qualification.
- Industrial Equipment:Automation hardware and precision machinery face capital allocation competition as Czech manufacturers deploy robotics to offset German and Polish wage pressure. Brownfield sensor integration challenges constrain retrofit demand.
- Consumer Electronics:Assembly operations serve regional distribution hubs with lower local value capture.
- Home Appliances:White goods production clusters near component import corridors with limited domestic brand presence.
The dominant share belongs to Automotive Parts, while Industrial Equipment is closing the gap fastest.
End User:
Procurement sophistication varies sharply between fragmented household demand and consolidated industrial buyers with technical service requirements.
- Manufacturers:Automotive OEMs and precision engineering firms command volume pricing and bundled maintenance contracts. Their specifications drive RoHS and CE marking compliance upstream through supplier tiers.
- Households:Consumer electronics and appliance purchases flow through retail channels with price elasticity concentrated in entry-level segments.
- Retailers:Electronics and appliance chains intermediate between importers and households, capturing margin through private label sourcing.
- Service Providers:Maintenance and installation contractors procure industrial spare parts with outcome-based performance demands displacing traditional wholesaler relationships.
Manufacturers capture the largest procurement value, though Service Providers are expanding their equipment spend most steeply.
Distribution Channel:
Channel economics split between high-touch technical service and low-margin digital fulfillment, with industrial procurement tilting toward direct manufacturer relationships.
- Online Retail:Consumer electronics and spare parts platforms capture share from traditional networks. Industrial equipment e-procurement is gaining traction in Brno and Ostrava precision engineering clusters where technical documentation standardization enables remote specification.
- Wholesalers:B2B industrial procurement retains leverage where contract terms, inventory pooling, and field service bundling matter. AGROFERT's agrochemical supply chains demonstrate this resilience.
- Brick-and-Mortar:Consumer appliance and electronics retail faces compression from digital alternatives.
- Direct Sales:Capital equipment manufacturers bypass intermediaries for large industrial accounts with customized engineering requirements.
Wholesalers retain the deepest industrial penetration, yet Online Retail is climbing the fastest in absolute growth terms.
Application:
Use-case intensity determines energy consumption profiles and regulatory exposure across Czech industrial corridors.
- Industrial Production:Metallurgical and chemical processing operations face EU Green Deal electrification mandates. ČEZ's nuclear baseload underpins cost competitiveness for energy-intensive sites.
- Transportation:EV powertrain development and automotive assembly concentrate precision engineering demand in Central Bohemia, with rare earth supply concentration creating vulnerability.
- Entertainment:Consumer electronics consumption tracks household disposable income with limited domestic production.
- Home Improvement:Appliance replacement cycles and renovation activity flow through retail channels with seasonal demand patterns.
Industrial Production commands the heaviest equipment investment, while Transportation applications are expanding most quickly under EV localization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial consumption patterns across Central Europe diverge sharply from Western European norms, with Czech buyers prioritizing supplier proximity and technical service bundling over lowest-unit-cost sourcing. Energy-intensive production clusters anchor demand in sub-regions with nuclear baseload or district heating infrastructure. Prague-based financial services and Brno-precision engineering create distinct procurement ecosystems.
Central Bohemia
Mladá Boleslav automotive stamping and forging operations consume precision-engineered components at scale, pulling Tier-1 suppliers into dense supplier networks. EU REACH and RoHS directives filter smaller stampers from export qualification to Germany and Poland. Prague-Ostrava industrial corridors concentrate metallurgical competencies that reduce procurement lead times for Škoda Auto and its ecosystem.
South Moravia
Brno precision engineering clusters drive demand for automation hardware and industrial IoT sensor networks as manufacturers deploy robotics to offset wage pressure. Czech Office for Standards, Metrology and Testing enforces CE marking conformity for machinery exports. AGROFERT's agrochemical processing facilities anchor food processing supply chains across the region with cold chain refrigeration retrofits accelerating under F-Gas Regulation phase-downs.
North Moravia
Ostrava metallurgical and chemical processing operations face EU Green Deal electrification mandates forcing capital reallocation toward low-carbon process technologies. ČEZ's Temelín and Dukovany nuclear baseload expansion supports industrial electrification cost competitiveness. Brownfield manufacturing sites struggle with Industry 4.0 sensor integration against decades-old mechanical control systems.
Prague Capital Region
Financial services concentration at Česká spořitelna, Komerční banka, and MONETA Money Bank constrains capital deployment rhythms for industrial borrowers. Czech National Bank supervision shapes lending terms for energy-intensive sector capex. Online Retail distribution channels capture consumer electronics and appliance share from Brick-and-Mortar networks in the metropolitan consumer base.
Czech Republic Market Vendor Landscape
Capability concentration sits with integrated industrial conglomerates; scale advantage sits with specialized automotive and energy operators. The market structures around three tiers: diversified holding companies with cross-sector exposure, sector-focused engineering and manufacturing specialists, and state-influenced infrastructure operators. Competitive moves center on supplier ecosystem deepening and regulatory compliance infrastructure rather than price-based displacement.
Among diversified holding companies, AGROFERT exemplifies the cross-sector archetype spanning agrochemicals and food processing. Škoda Auto and ČEZ represent sector-specialized operators with engineering and infrastructure scale respectively. These three entities anchor distinct competitive vectors: AGROFERT in supply chain integration, Škoda Auto in Tier-1 supplier ecosystem density, and ČEZ in baseload energy positioning for industrial electrification.
| Leading Market Players |
|---|
| AGROFERT |
| Škoda Auto |
| ČEZ |
| Česká spořitelna |
| Československá obchodní banka |
| Komerční banka |
| MONETA Money Bank |
| Colt CZ Group |
| Philip Morris CR |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision forging and EV powertrain stamping across Central Bohemia is compressing supplier margins while amplifying contract pricing power for Tier-1 automotive stampers with secured offtake agreements. Škoda Auto's localization mandates draw capacity toward Mladá Boleslav, forcing buyers to accept longer-term contract structures with price escalation clauses tied to energy input indices.
Pricing Analysis
Long-term offtake contracts dominate procurement for automotive stampers and forging operations, with spot purchasing limited to maintenance spares and emergency capacity. Price differentiation hinges on REACH certification tier and bundled technical service levels, with export-qualified suppliers commanding premium positioning over domestic-only operators. Cost compression in standard-grade stampings is intensifying because of natural gas price volatility and Czech National Bank interest rate effects on working capital. Household appliance retailers exhibit the highest price sensitivity, while automotive OEM procurement teams prioritize supply security over unit cost minimization.
Supply Chain Analysis
Contract manufacturing concentration for electronics assembly sits with Foxconn and Jabil facilities in Poland and Slovakia, with limited Czech domestic EMS capacity. Geographic supply draws from Germany for precision machinery, China for rare earth magnet inputs, and Poland for labor-intensive component finishing. Raw material dependencies center on steel coil from ArcelorMittal Ostrava, aluminum from Slovak smelters, and battery cell precursors from South Korean suppliers. Single-source vulnerability in rare earth processing creates exposure for EV powertrain localization timelines. Distribution runs through AGROFERT's wholesaler networks for agrochemical and industrial chemical flows, with manufacturer-direct platforms gaining share in precision engineering equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from Polish and Romanian manufacturing clusters offering lower labor costs and comparable EU market access, requiring defensive positioning around technical service bundling and certification infrastructure.
For Market Incumbents: Harden supplier ecosystem control by deepening backward integration into precision forging capacity around Mladá Boleslav and securing captive supply of nuclear-powered electricity through ČEZ direct contracting. Invest in EU CSRD disclosure infrastructure ahead of compliance deadlines to filter smaller competitors from export qualification. The Polish wage arbitrage threat demands automation engineering retention through equity participation structures.
For New Entrants and Emerging Players: Brownfield manufacturing sites in North Moravia with existing grid interconnection represent the most penetrable entry point for industrial IoT retrofit services and predictive maintenance platforms. Bio-based fertilizer processing adjacent to AGROFERT's agrochemical infrastructure offers white-space positioning under EU Green Deal agricultural decarbonization mandates. Go-to-market execution should leverage Czech Office for Standards, Metrology and Testing certification partnerships to accelerate CE marking pathways.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized automation integrators with proven PLC programming and robotics deployment track records in Brno precision engineering clusters. Long-term viability across the analysis window rests on nuclear-to-hydrogen bridging technology positioning and F-Gas Regulation compliance infrastructure. The signal to watch is Temelín capacity expansion announcements and their effect on electrolytic hydrogen cost curves for steel decarbonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Forging | Captive supply of stamped components secures Škoda Auto Tier-1 qualification and REACH export compliance. |
| Nuclear Power Purchase Agreement | ČEZ baseload contracting insulates energy-intensive metallurgical operations from gas price volatility. |
| EU CSRD Disclosure Infrastructure | Third-party verification capabilities filter smaller competitors from single-market export access. |
| Industrial IoT Platform Integration | Predictive maintenance offerings penetrate Brno and Ostrava precision engineering clusters. |
| Green Hydrogen Production Partnership | Temelín electrolytic capacity supports steel and chemical sector decarbonization mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Czech Statistical Office industrial output data, EUROSTRUCT construction permits, and ČEZ generation disclosures. Primary interviews engaged automotive procurement directors at Škoda Auto and Tier-1 suppliers, plant managers at AGROFERT processing facilities, automation engineering heads in Brno precision clusters, and Czech National Bank supervisory officers. Secondary validation drew from BIS-equivalent Czech Office for Standards, Metrology and Testing regulatory filings, EU REACH substance restriction updates, and F-Gas Regulation implementation schedules. Bottom-up segment sizing triangulates against top-down GDP industrial value-add allocations.
Forecast inputs span automotive powertrain localization timelines, EU Green Deal electrification mandates, and nuclear capacity expansion announcements across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement sophistication, distribution channel digital penetration, and regional industrial corridor density. CAGRs derive from regression against historical industrial output correlations with German automotive demand and energy input cost indices. Industry-specific forecast inputs incorporate rare earth supply concentration risk and CSRD compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in Czech koruna-euro exchange rates, German automotive production cycles, or EU ETS carbon pricing would shift the trajectory. Forecasts reflect documented assumptions regarding nuclear baseload availability and Škoda Auto platform standardization timelines. Cross-checking against IHS Markit vehicle production forecasts and Eurostat industrial energy consumption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military and Aerospace Sensors Market
Others
Bio-Based Leather Market
Others
Smart Card Contactless Ticketing Market
Others
Education and Learning Analytics Market
Others
Baking Paper Market
Others
Mexico 3D Printing Construction Market
Others
Digital Mortgage Software Market
Others
Asia-Pacific Social Media Management Market
Others
US Quantum Computing Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Smart Home Water Softener Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Paraffin Physical Therapy Market
Others
Silicone Molding Machinery Market
Others
Global Injectable Nanomedicine Market
Others
Rope Market