
 China 3D Printing Construction Market | 2026-2036
China 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China 3D Printing Construction Market Insights
China's dual carbon goals from MEE is consolidating procurement standards for low-carbon building methods across provincial construction bureaus. WinSun leverages its early mover advantage in large-scale contour crafting systems for multi-story housing prototypes. Shanghai Construction Group anchors municipal demonstration projects in the Yangtze River Delta with government-backed pilot approvals. BLT specializes in metal binder jetting for structural connectors that bridge printed concrete and traditional rebar frames.
China 3D printing construction deploys gantry-mounted or robotic-arm extrusion systems to deposit cementitious, polymeric, or metallic feedstock in layerwise geometries controlled by digital building information models, typically achieving compressive strengths of 30-60 MPa for structural wall elements. The primary industrial purpose is reducing formwork waste, labor hours, and embodied carbon in vertical construction while enabling complex topological optimizations impossible with conventional cast-in-place methods. Fused Deposition Modeling dominates current installed capacity for concrete extrusion given its lower capital threshold and compatibility with standard Portland cement blends. Metal segments command premium positioning as binder jetting of steel reinforcement nodes gains traction in hybrid construction systems that combine printed shells with conventional structural cores.
MEE enforces progressive carbon intensity benchmarks on building materials, while SAMR oversees GB standards compliance for printed structural component certification and quality consistency. MIIT channels industrial policy through smart manufacturing directives that subsidize robotic construction equipment deployment in designated pilot zones. Stakeholders must track how provincial implementation rules for GB/T carbon accounting standards differentiate between on-site printed structures and prefabricated printed components shipped to job sites.
Market Dynamics
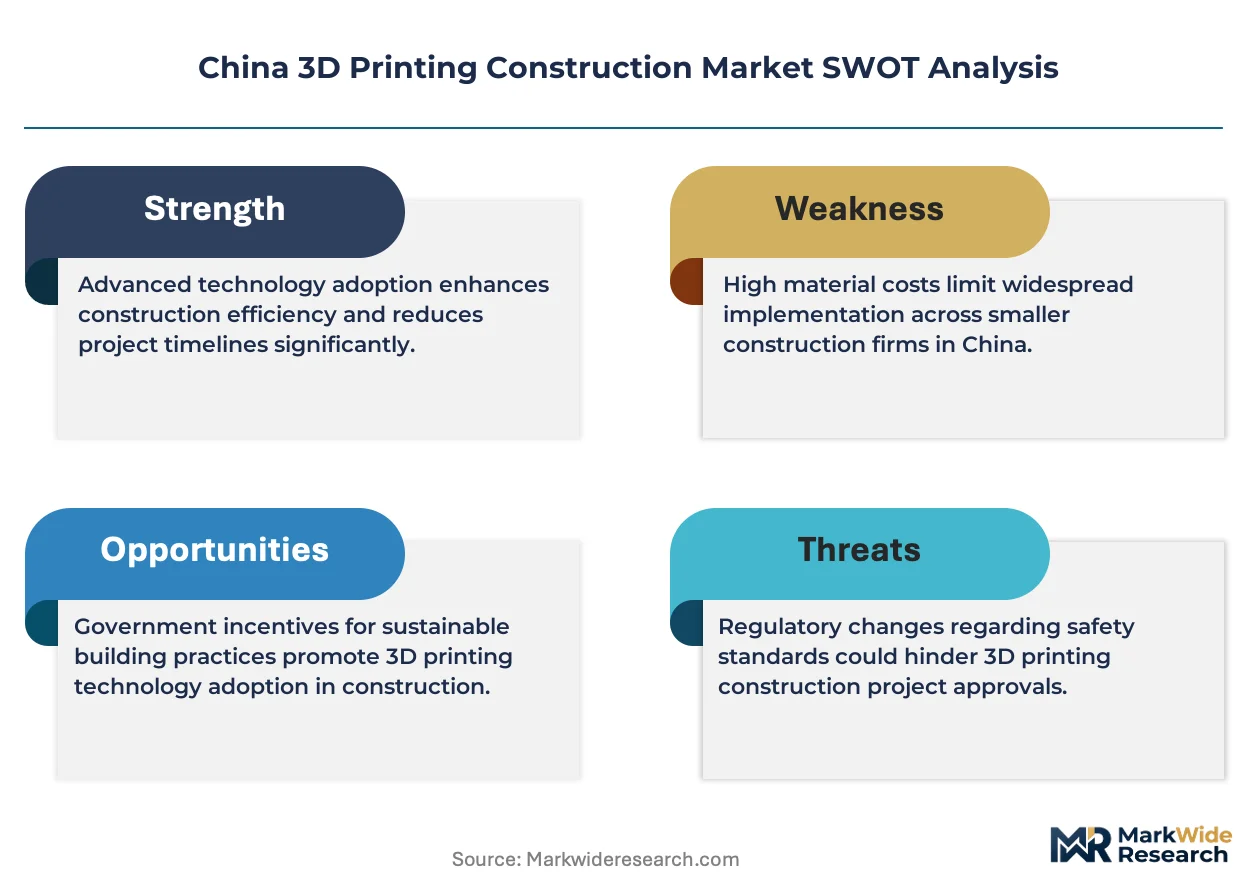
China's dual carbon goals from MEE are compressing embodied carbon limits on conventional concrete pours, forcing municipal housing authorities toward low-carbon procurement standards. This regulatory pressure is consolidating demand around printed structural components that slash formwork waste and labor hours.
Growth Catalysts
- MEE Carbon Benchmarks:The Ministry of Ecology and Environment enforces progressive intensity limits on building materials, mandating lower-carbon alternatives in provincial construction bureaus across the Yangtze River Delta.
- Affordable Housing Pipeline:Municipal housing authorities in Shanghai and Beijing are expanding procurement of prefabricated residential wall panels for public housing developments.
- Contour Crafting Scale:Large-scale gantry-mounted extrusion systems achieve compressive strengths of 30-60 MPa for structural wall elements while eliminating traditional formwork.
Market Restraints
- Portland Cement Cost Volatility:Feedstock price swings for standard cement blends compress margins for extrusion-based construction methods dependent on conventional binders.
- Equipment Supply Concentration:Gantry-mounted systems and robotic-arm extrusion hardware rely on a narrow base of domestic precision manufacturing clusters in Jiangsu and Zhejiang provinces.
- GB Standards Certification Friction:SAMR oversight of printed structural component certification creates extended approval timelines for novel geometries not covered by legacy building codes.
Strategic Opportunities
- Metal Binder Jetting Convergence:Hybrid construction systems combining printed concrete shells with steel reinforcement nodes printed via binder jetting open premium positioning in structural connectors.
- MIIT Smart Manufacturing Zones:Industrial policy subsidies for robotic construction equipment deployment in designated pilot zones reduce capital barriers for equipment adoption.
- Prefabricated Component Distribution:Printed wall panels fabricated off-site and shipped to job sites bypass on-site curing constraints, enabling penetration into inland provinces with limited skilled labor pools.
Industry Challenges
- Digital Building Information Modeling Talent:Shortage of technicians proficient in layerwise geometry control software limits deployment speed for municipal demonstration projects.
- GB/T Carbon Accounting Complexity:Provincial implementation rules differentiate accounting methodologies between on-site printed structures and prefabricated printed components, creating compliance ambiguity.
- Legacy Rebar Integration:Bridging printed concrete elements with traditional reinforcement frames requires specialized structural engineering expertise not yet standardized across construction firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China 3D Printing Construction Market |
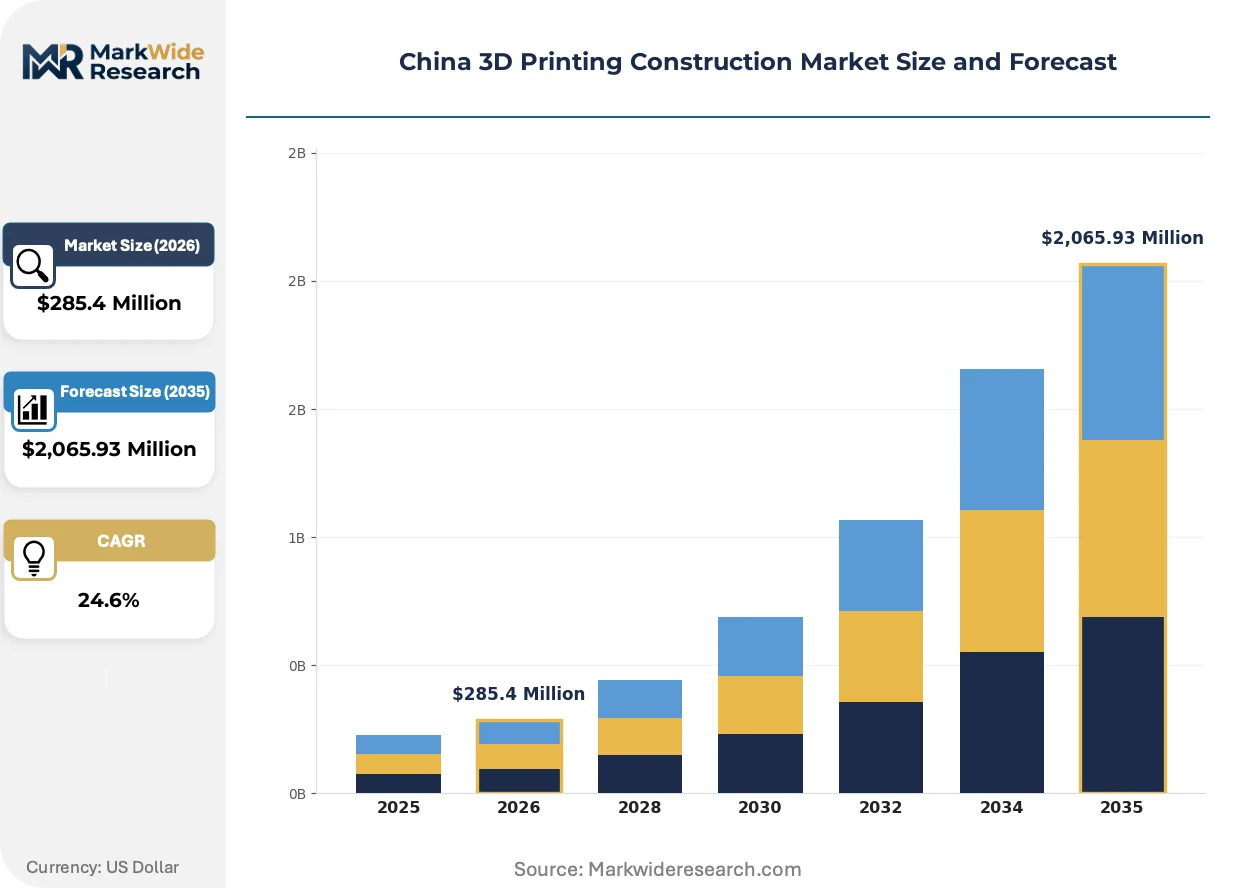
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,065.93 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
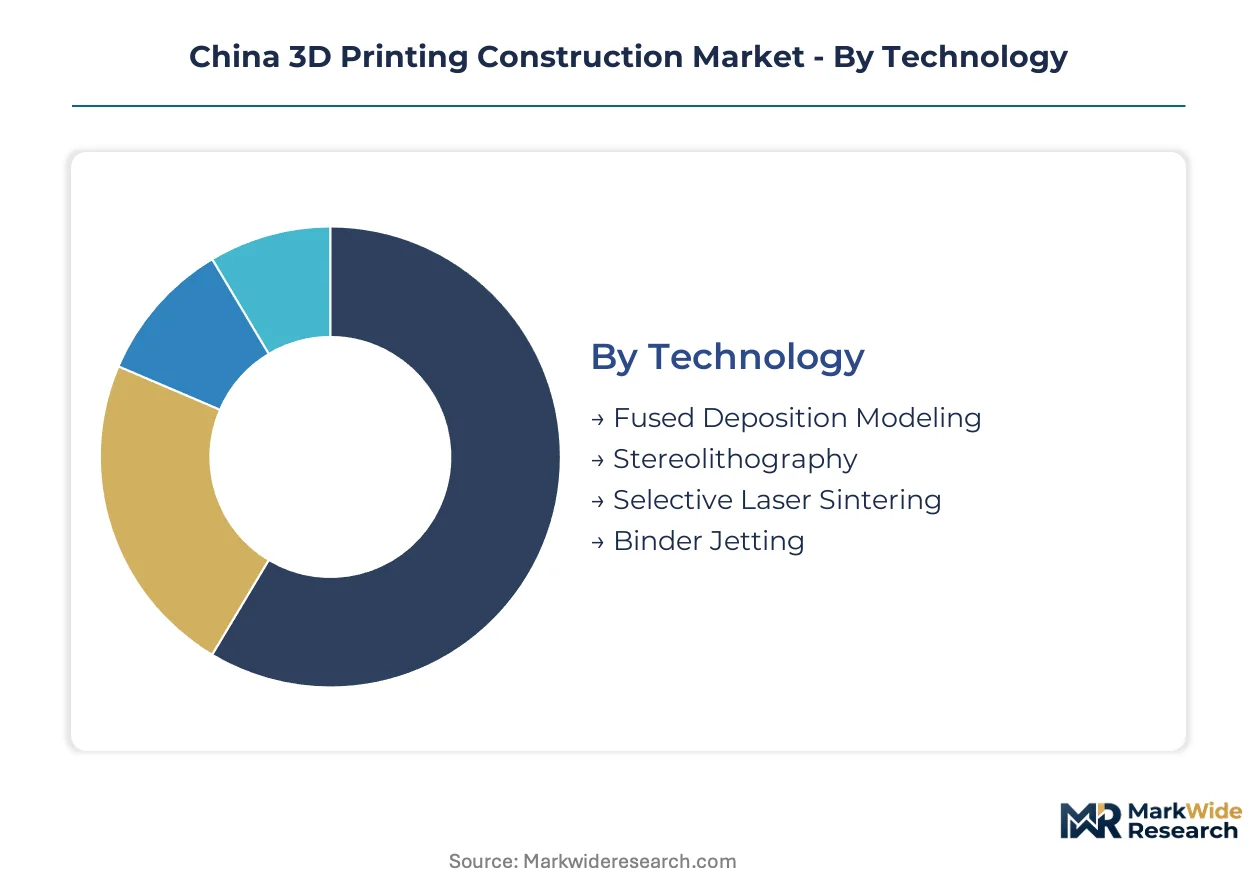
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting Material: Cement, Plastic, Metal, Composite Application: Residential Buildings, Commercial Structures, Infrastructure, Decorative Elements End User: Construction Firms, Architects, Engineers, Developers |
| Companies Covered | WinSun, Huizhou MCC, Shanghai Construction Group, China State Construction Engineering, Monolithic 3D Printers China, Sany Group, BLT, INTAMSYS, Farsoon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China 3D Printing Construction Market Trends and Innovations
Digital fabrication methods are compressing traditional construction timelines while enabling topological optimizations impossible with cast-in-place techniques. Three developments are restructuring competitive positioning in China's built environment sector.
Multi-material extrusion systems integrating cementitious feedstock with fiber reinforcement are electrifying the structural performance envelope for mid-rise housing prototypes. Shanghai Construction Group and municipal developers are piloting these configurations in government-backed demonstration projects. The technology is compressing the gap between printed shell strength and conventional reinforced concrete specifications.
MIIT channels smart manufacturing directives that subsidize robotic construction equipment deployment in designated pilot zones across the Yangtze River Delta. Provincial construction bureaus are consolidating procurement standards to favor equipment meeting GB standards compliance thresholds. Metal segments command premium positioning as binder jetting of steel reinforcement nodes gains traction in hybrid systems.
Municipal housing authorities are unbundling traditional general-contractor relationships in favor of direct procurement of prefabricated printed components from certified fabricators. This disintermediation compresses margin capture for conventional construction intermediaries while concentrating volume with digital fabrication specialists. The pattern is most visible in affordable housing developments across Jiangsu and Zhejiang provinces.
China 3D Printing Construction Market Segmentation
Technology-material combinations determine capital intensity and carbon reduction potential for Chinese construction firms navigating MEE benchmarks. Application scope separates volume-driven affordable housing from premium commercial demonstrators.
Technology:
Fused Deposition Modeling anchors volume deployment through lower equipment thresholds, while Binder Jetting commands premium positioning in hybrid structural systems.
- Fused Deposition Modeling:Layerwise extrusion of cementitious feedstock achieves 30-60 MPa compressive strength using standard Portland cement blends compatible with existing supply chains. Municipal housing authorities in Shanghai specify FDM systems for affordable housing wall panels to minimize capital outlay in pilot zones.
- Binder Jetting:Powder-bed deposition with liquid binding agents enables steel reinforcement node fabrication for bridging printed concrete shells with traditional rebar frames. MIIT smart manufacturing subsidies reduce equipment barriers for metal segment penetration in Yangtze River Delta demonstration projects.
- Stereolithography:Photopolymer curing systems serve decorative element prototyping and architectural model verification for Beijing design studios.
- Selective Laser Sintering:High-energy laser fusion of polymer or metal powders supports precision connector components in hybrid construction assemblies.
Mature deployment sits with Fused Deposition Modeling. Newer deployment is concentrated in Binder Jetting.
Material:
Cement formulations dominate procurement volumes for structural wall elements, while Metal segments capture margin premiums in load-bearing connectors.
- Cement:Standard Portland blends and geopolymer variants constitute the primary feedstock for gantry-mounted extrusion systems in multi-story housing prototypes. SAMR certification requirements for printed structural components favor cement-based systems with established GB standards compliance documentation.
- Metal:Steel and aluminum powder feedstocks enable binder jetting of structural nodes that integrate printed shells with conventional reinforcement frames. Provincial construction bureaus specify metal connectors for mid-rise commercial structures requiring seismic performance certification.
- Plastic:Acrylonitrile butadiene styrene and polylactic acid filaments serve non-structural formwork and temporary mold applications.
- Composite:Fiber-reinforced cementitious matrices enhance tensile performance for cantilevered architectural elements in decorative applications.
Volume concentration rests with Cement. Margin expansion concentrates in Metal.
Application:
Residential Buildings absorb procurement volume from municipal affordable housing pipelines, while Infrastructure applications face extended certification timelines.
- Residential Buildings:Prefabricated wall panel production for public housing developments across Jiangsu and Zhejiang provinces leverages contour crafting to eliminate formwork waste. Shanghai Construction Group anchors municipal demonstration projects with government-backed pilot approvals for multi-story printed housing prototypes.
- Commercial Structures:Mid-rise office and retail shells utilize hybrid systems combining printed concrete envelopes with conventional structural cores. Beijing municipal authorities specify printed commercial demonstrators to validate embodied carbon reduction claims for dual carbon goal compliance.
- Infrastructure:Bridge components and utility housing face extended SAMR certification timelines for load-bearing applications under legacy GB codes.
- Decorative Elements:Facade panels and architectural features serve lower-risk entry points for design firms testing digital fabrication workflows.
Procurement volume clusters in Residential Buildings. Technical validation concentrates in Commercial Structures.
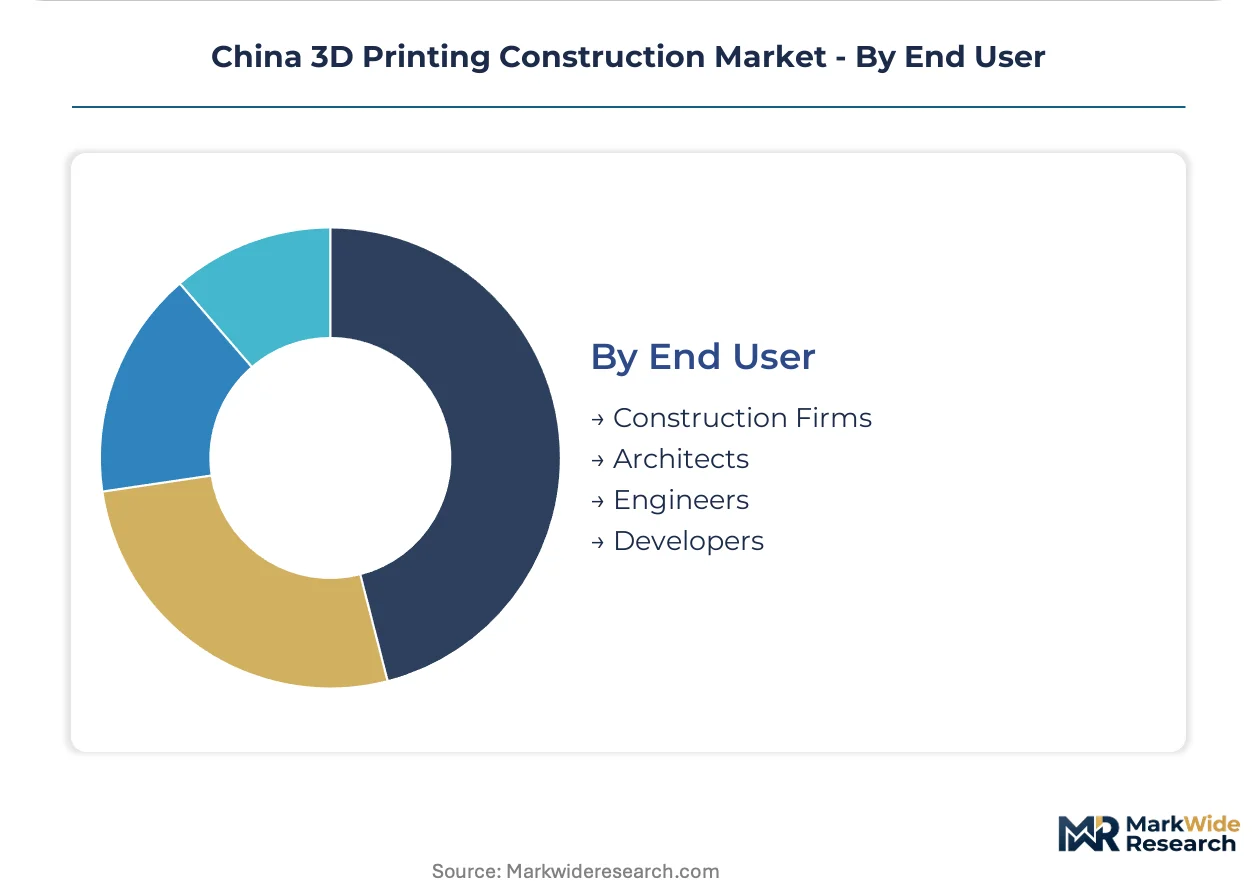
End User:
Construction Firms capture direct procurement relationships as municipal authorities disintermediate traditional general contractors, while Architects influence early-stage technology selection.
- Construction Firms:Shanghai Construction Group and provincial state-owned enterprises deploy gantry systems for affordable housing volume production. Direct component procurement from certified fabricators compresses margin capture for conventional construction intermediaries.
- Architects:Design studios in Beijing specify topological optimizations impossible with cast-in-place methods for signature commercial demonstrators. Shortage of technicians proficient in layerwise geometry control software limits deployment speed for complex geometries.
- Engineers:Structural specialists bridge printed elements with traditional reinforcement frames, requiring expertise not yet standardized across firms.
- Developers:Private and state-backed project sponsors evaluate total cost of ownership for printed versus conventional methods in carbon-constrained procurement environments.
Execution capability sits with Construction Firms. Design influence concentrates with Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors China's 3D printing construction activity, with Shanghai and Suzhou hosting the densest concentration of gantry-mounted extrusion systems and municipal pilot approvals.
Shanghai
Municipal housing authorities in Shanghai are expanding direct procurement of prefabricated printed wall panels for affordable housing developments. MEE carbon intensity benchmarks enforce progressive limits on conventional concrete pours across construction bureaus. The Pudong and Jiading districts host demonstration projects validating multi-story printed housing prototypes with government-backed approvals.
Beijing
Beijing municipal authorities specify printed commercial demonstrators to validate embodied carbon reduction claims for dual carbon goal compliance. SAMR oversight of printed structural component certification creates extended timelines for novel geometries. The Tongzhou sub-center and Daxing districts concentrate mid-rise office and retail shell projects utilizing hybrid construction systems.
Jiangsu Province
Provincial construction bureaus in Jiangsu are consolidating procurement standards to favor equipment meeting GB standards compliance thresholds. MIIT smart manufacturing directives subsidize robotic construction equipment deployment in designated pilot zones. Nanjing and Suzhou industrial clusters supply gantry-mounted systems and robotic-arm extrusion hardware to regional fabricators.
Zhejiang Province
Hangzhou and Ningbo anchor precision manufacturing clusters for domestic extrusion equipment production. Provincial implementation rules for GB/T carbon accounting standards differentiate methodologies between on-site printed structures and prefabricated components. Municipal developers in Shaoxing and Jiaxing are piloting off-site printed wall panel fabrication for distribution to inland job sites.
Sichuan-Chongqing
The Chengdu-Chongqing economic circle is emerging as a secondary demand node for printed construction methods addressing seismic performance requirements. Local housing authorities evaluate prefabricated component distribution models to bypass on-site curing constraints. Chongqing's Liangjiang New Area hosts validation projects for hybrid systems combining printed concrete shells with conventional structural cores.
China 3D Printing Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and equipment sophistication tiers. The vendor base stratifies between large-scale contour crafting specialists, state-owned construction enterprises with pilot project mandates, and metal additive fabricators supplying structural connectors. Three archetypes dominate: equipment-integrated service providers, state-backed construction conglomerates, and precision metal printing specialists. Competitive moves concentrate on securing municipal demonstration project approvals and expanding prefabricated component distribution networks.
Among Chinese market participants, WinSun and Shanghai Construction Group exemplify the equipment-integrated and state-backed archetypes respectively, while BLT occupies a position in the precision metal segment for structural connector applications. These three entities anchor distinct competitive vectors within a market where direct procurement relationships with municipal housing authorities determine volume allocation.
| Leading Market Players |
|---|
| WinSun |
| Huizhou MCC |
| Shanghai Construction Group |
| China State Construction Engineering |
| Monolithic 3D Printers China |
| Sany Group |
| BLT |
| INTAMSYS |
| Farsoon Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive integration of gantry-mounted extrusion systems by state-owned construction groups anchors both supply security and pricing power for municipal demonstration projects. Shanghai Construction Group and provincial SOEs internalize equipment procurement to bypass third-party margin stacking while locking in preferential access to MIIT-subsidized hardware deployments across Jiangsu and Zhejiang manufacturing clusters.
Pricing Analysis
Outcome-based pricing tied to embodied carbon reduction certificates anchors municipal procurement contracts for prefabricated wall panels. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified structural components from uncertified prototypes and decorative non-load-bearing elements. Cost compression in economy-tier cement extrusion is intensifying because Portland cement feedstock volatility compresses margins for equipment operators without captive supply agreements. Municipal housing authorities exhibit highest price sensitivity, while commercial developers absorbing dual carbon compliance costs show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Suzhou and Hangzhou anchor hub-and-spoke patterns for prefabricated component shipment to inland job sites. Equipment manufacturing concentrates in Jiangsu, Zhejiang, and Guangdong provinces, with precision servo motors and extrusion nozzles drawing from Japanese and German component suppliers. Single-source vulnerability runs through domestic gantry system fabricators dependent on imported motion control systems. Distribution runs through certified fabricator direct-to-site models that disintermediate traditional construction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's 3D printing construction sector is consolidating around equipment-integrated service providers with SAMR certification depth and municipal pilot relationships. MEE carbon intensity benchmarks are forcing smaller equipment operators without state backing toward acquisition or exit.
For Market Incumbents: Deploy certification depth as the primary defensive lever. WinSun and Shanghai Construction Group should accelerate GB standards compliance documentation for novel geometries ahead of provincial bureau consolidation of procurement standards. Capacity addition in Sichuan-Chongqing addresses seismic performance validation gaps before secondary demand nodes mature. Threat substitution from conventional precast concrete with lower embodied carbon claims demands preemptive carbon accounting transparency.
For New Entrants and Emerging Players: Capture prefabricated component distribution to inland provinces with limited skilled labor pools as the most penetrable white-space target. Metal binder jetting for structural connectors offers premium positioning with lower capital barriers than full gantry systems. Go-to-market angle should emphasize hybrid system integration expertise bridging printed shells with conventional rebar frames, addressing the legacy reinforcement integration challenge documented across construction firms.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-backed construction conglomerates seeking equipment integration capabilities and municipal relationship portfolios. Long-term viability favors entities with demonstrated multi-story housing prototypes and active MIIT smart manufacturing zone deployments. Signal to watch is provincial implementation clarity on GB/T carbon accounting standards differentiating on-site versus prefabricated methodologies, which will determine volume allocation between business models.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Certification Investment | SAMR compliance documentation accelerates municipal procurement approval timelines for novel geometries. |
| Prefabricated Component Distribution Network | Off-site fabrication bypasses on-site curing constraints in inland provinces with limited labor pools. |
| Metal Binder Jetting Capability Addition | Steel reinforcement node production opens premium positioning in hybrid structural systems. |
| MIIT Smart Manufacturing Zone Deployment | Subsidized equipment procurement reduces capital barriers for robotic construction hardware adoption. |
| Carbon Accounting Transparency Program | Provincial MEE benchmark compliance validates embodied carbon reduction claims for dual carbon goals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with equipment engineering directors, municipal housing procurement officers, construction firm project managers, and SAMR certification specialists combined with MIIT smart manufacturing directive documentation and GB standards technical committees. Secondary sources included MIIT industrial policy circulars, MEE carbon intensity benchmark disclosures, Shanghai and Beijing municipal construction bureau procurement records, and Jiangsu province equipment manufacturing cluster export data. Bottom-up equipment deployment tallies triangulated against top-down construction output value estimates.
Data-stream reconciliation across technology-material-application segmentation dimensions modeled volume and value outputs throughout the forecast period. Modeled dimensions included extrusion technology type, feedstock material category, building application class, and end-user procurement archetype. CAGRs derived from equipment installation run-rate projections, municipal affordable housing pipeline announcements, and carbon constraint policy implementation phasing. Industry-specific inputs incorporated SAMR certification timeline assumptions and MIIT subsidy program renewal patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to provincial GB/T carbon accounting implementation rules and Portland cement feedstock cost trajectories. Forecasts reflect documented assumptions on equipment cost decline curves and municipal procurement standard consolidation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial PC Market
Others
Smart Plug Market
Others
Global Pumpkin Candles Market
Others
Indoor LBS Market
Others
Gym Wipes Market
Others
Smart Card Market
Others
Europe Electric Forklift Market
Others
Europe Street Lighting Market
Others
Underwater Communication System Market
Others
Healthcare Bioconvergence Market
Others
Ultra Mobile Devices (UMD) Market
Others
Folding Screen Mobile Phone Market
Others
Global Crowdsourced Testing Market
Others
Mobile Social Networks Market
Others
Digital Tattoos Market
Others
Global Webinar and Webcast Market