
 North America Medical Simulation Market | 2026-2036
North America Medical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Simulation Market Intelligence
ACLS certification from the American Heart Association is bifurcating the competitive landscape into vendors whose platforms integrate validated resuscitation protocols and those that do not. Laerdal Medical leverages its longstanding relationship with the AHA to sustain channel control across hospital systems. CAE Inc. anchors its North American position through deep integration with military medical training contracts. Mentice differentiates by specializing in endovascular simulation where catheter-based procedure fidelity determines purchasing decisions.
Medical simulation encompasses physical manikins, software platforms, and immersive technologies that replicate clinical scenarios for learner assessment without patient risk. High-fidelity manikins incorporate physiologic modeling with programmable cardiac rhythms, respiratory patterns, and pharmacologic responses to mirror human pathophysiology. Software platforms and virtual reality simulators command expanding margin pools as healthcare systems shift capital expenditure toward scalable, repeatable digital training environments. Surgical training applications within academic medical centers absorb the largest share of institutional budgets, while emergency care training and patient safety drills represent faster-growing use cases driven by hospital accreditation requirements.
The FDA's software as a medical device framework and the Joint Commission's accreditation standards jointly determine which simulation products achieve institutional adoption across the United States. Health Canada and provincial health authorities in Ontario, Quebec, and British Columbia impose parallel validation requirements that gate Canadian market access. Stakeholders must monitor how CMS reimbursement policy for graduate medical education evolves, as training hour restrictions and competency-based progression directly alter simulation procurement volume and platform specifications.
Market Dynamics
The FDA's software as a medical device framework is compressing development timelines for simulation platforms while elevating validation requirements that gate institutional procurement across hospital systems.
Growth Catalysts
- Competency-Based Graduate Medical Education:The ACGME's shift toward milestone-based progression mandates simulation hours for surgical residency programs, embedding training platforms into accreditation compliance.
- Joint Commission Patient Safety Mandates:Biennial emergency response drills and team-based crisis simulations are now embedded in hospital accreditation standards, institutionalizing recurring procurement cycles.
- California-Texas-New York Hospital Cluster Density:Concentrated academic medical center networks in these states create regional purchasing gravity that sustains vendor field operations and service infrastructure.
Market Restraints
- High-Fidelity Manikin Hardware Costs:Programmable physiologic modeling systems require specialized polymers, pneumatic actuators, and embedded sensor arrays that resist commoditization.
- Canadian Provincial Validation Fragmentation:Health Canada and Ontario's Ministry of Health impose parallel but non-identical software validation requirements that extend market entry timelines.
- Extended FDA 510(k) Pathways for VR Surgical Platforms:Software as a medical device classification for haptic-enabled procedural trainers triggers clinical evidence requirements comparable to implantable devices.
Strategic Opportunities
- Home-Based Nursing Simulation:Remote care training platforms for community health workers and home infusion nurses remain underdeveloped relative to hospital-centric offerings.
- AI-Generated Patient Scenario Libraries:Machine learning models trained on EHR data can produce infinite procedural variations, reducing content development costs for platform vendors.
- Military-Civilian Training Bridge Contracts:The US Department of Defense's combat casualty simulation programs create technology transfer pathways into civilian trauma center certification programs.
Industry Challenges
- Biomedical Engineer Talent Scarcity:The intersection of clinical physiology, software architecture, and haptic engineering requires hybrid skill sets that academic programs produce insufficiently.
- Legacy LMS Integration Complexity:Hospital learning management systems from the 2010s lack API standardization, forcing costly custom middleware for simulation data capture.
- Multistate Licensure Tracking for Tele-Simulation:Cross-border remote proctoring of simulation-based assessments triggers nursing board jurisdiction questions that compliance teams must navigate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Simulation Market |
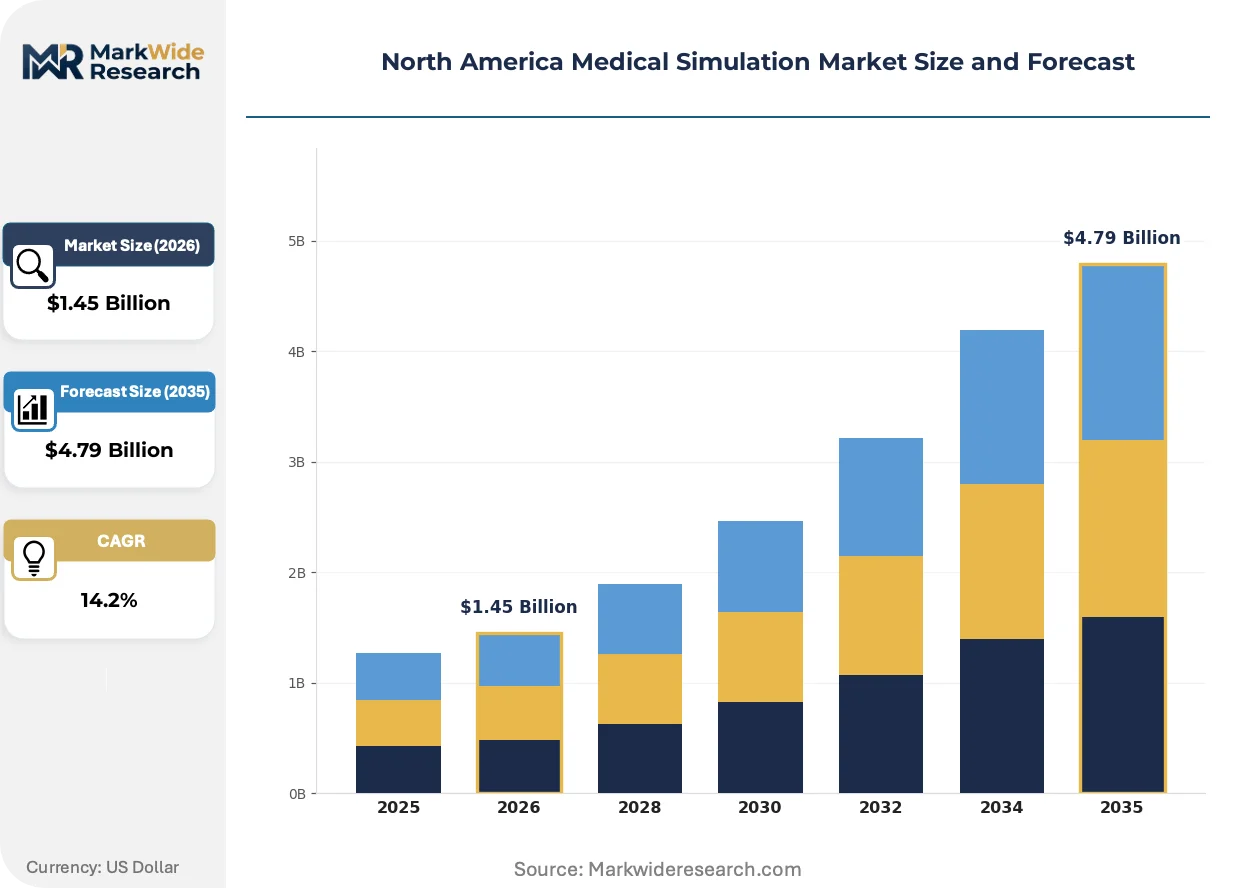
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $4.79 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manikins, Software Platforms, Virtual Reality Simulators, Augmented Reality Simulators, Task Trainers Application: Surgical Training, Emergency Care Training, Anesthesia Training, Nursing Education, Patient Safety Drills End User: Medical Schools, Teaching Hospitals, Research Institutes, Military Medical Units, Simulation Centers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Simulation Units |
| Companies Covered | 3D Systems, Gaumard Scientific, Laerdal Medical, Simulab Corporation, CAE Inc., Elevate Healthcare, Simulaids, Mentice, Surgical Science Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Simulation Market Strategic Shifts & Innovations
Immersive technologies are restructuring how procedural competence is assessed, shifting validation authority from time-based training logs toward objective performance metrics captured in synthetic environments.
Haptic-enabled virtual reality surgical trainers is bifurcating the market between academic medical centers demanding sub-millimeter force feedback fidelity and community hospitals accepting visual-only immersion. Orthopedic residency programs at Johns Hopkins and Mayo Clinic are piloting these systems for arthroscopy modules. The technology is bifurcating vendor R&D budgets toward either premium haptic engineering or scalable software-only deployments.
The FDA's 2023 guidance on predetermined change control plans for machine learning-enabled devices is altering how simulation platforms incorporate adaptive difficulty algorithms. Vendors must now lock algorithmic update protocols prior to market authorization. Endovascular simulation modules with AI-generated lesion morphologies face the steepest compliance burden under this framework.
Hospital consortium purchasing is consolidating vendor relationships as regional health systems centralize simulation procurement under single-source contracts. The Kaiser Permanente and HCA Healthcare networks now negotiate enterprise licenses spanning dozens of facilities. This concentration is most visible in Texas, where Methodist Hospital System's standardization on one VR platform has displaced incumbent manikin suppliers from affiliated residency programs.
North America Medical Simulation Market Segmentation
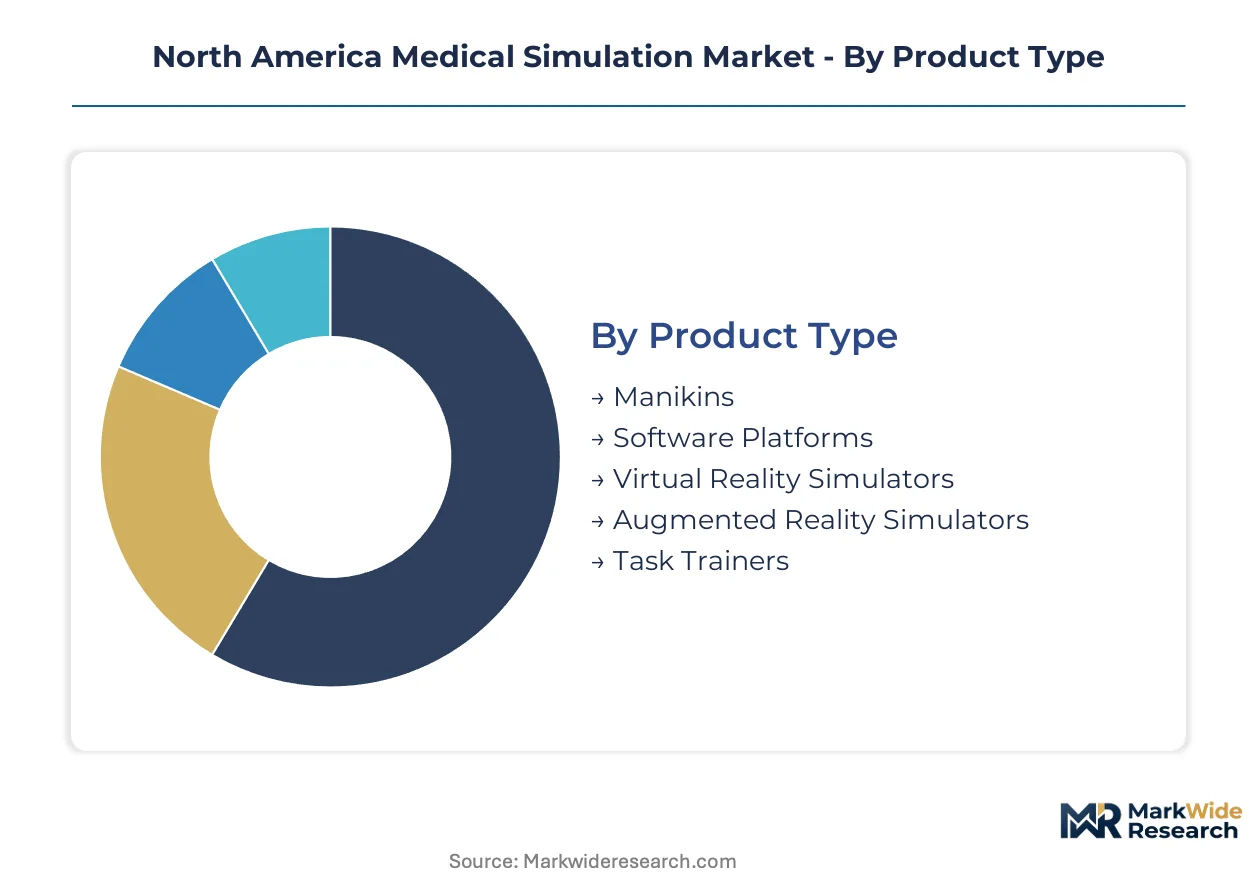
Simulation procurement patterns diverge sharply across product architectures, with hardware-heavy manikin systems anchoring capital budgets while software platforms capture recurring revenue streams. Academic medical centers and teaching hospitals prioritize different capability bundles based on accreditation compliance requirements and residency program scale.
Product Type:
Margin pools concentrate in programmable physiologic systems where pneumatic actuation and embedded sensor arrays resist commoditization.
- Manikins:High-fidelity programmable systems incorporate cardiac rhythm modeling, respiratory pattern simulation, and pharmacologic response programming. Demand clusters at Johns Hopkins, Mayo Clinic, and Cleveland Clinic residency programs where ACGME milestone requirements mandate hands-on physiologic training.
- Software Platforms:Scalable digital environments enable infinite scenario repetition without hardware degradation. Kaiser Permanente and HCA Healthcare networks are consolidating enterprise licenses across dozens of facilities, rotating procurement toward subscription models.
- Virtual Reality Simulators:Immersive headsets with haptic controllers for procedural training.
- Augmented Reality Simulators:Overlay digital anatomy onto physical task trainers for guided instruction.
- Task Trainers:Anatomic models for repetitive skill acquisition without full physiologic modeling.
Manikins hold installed capacity. Software Platforms are rotating up the share rankings.
Application:
Hospital accreditation mandates determine purchasing velocity, with biennial emergency response requirements institutionalizing recurring procurement cycles.
- Surgical Training:Orthopedic arthroscopy and endovascular modules absorb the largest institutional budgets. Johns Hopkins and Mayo Clinic pilots for haptic-enabled VR arthroscopy are reshaping vendor R&D priorities toward sub-millimeter force feedback fidelity.
- Emergency Care Training:ACLS certification protocols from the American Heart Association bifurcate vendor competitiveness. Laerdal Medical leverages exclusive AHA relationships to sustain channel control across hospital systems where Joint Commission mandates require team-based crisis simulations.
- Anesthesia Training:Airway management and crisis resource scenarios for operating room preparedness.
- Nursing Education:Clinical skills validation for licensure and competency maintenance.
- Patient Safety Drills:Team communication and error prevention protocols for accreditation compliance.
Surgical Training commands budget share. Emergency Care Training is climbing the fastest as accreditation requirements tighten.
End User:
Customer concentration in California, Texas, and New York creates regional purchasing gravity that sustains vendor field operations.
- Teaching Hospitals:Academic medical centers anchor demand with multi-million-dollar capital allocations for residency program infrastructure. Methodist Hospital System in Texas standardized on one VR platform, displacing incumbent manikin suppliers from affiliated programs.
- Medical Schools:Pre-clinical training environments prioritize high-fidelity manikins for foundational skills acquisition.
- Simulation Centers:Dedicated training facilities serving multiple institutional clients with shared resource models.
- Military Medical Units:Combat casualty simulation programs create technology transfer pathways into civilian trauma certification.
- Research Institutes:Validation studies and protocol development for emerging simulation modalities.
Teaching Hospitals dominate procurement volume. Military Medical Units are gaining strategic importance through dual-use technology pipelines.
Deployment:
IT infrastructure maturity determines adoption barriers, with legacy learning management systems forcing costly custom middleware for data capture.
- On-Premise:Dedicated server installations within hospital firewalls for maximum data control. Large teaching networks in California and New York prefer this architecture for patient privacy compliance.
- Cloud-Based:Scalable subscription models reduce upfront capital requirements. Community hospitals and smaller simulation centers are migrating fastest as cybersecurity frameworks mature.
- Hybrid:Local processing for latency-sensitive haptic feedback with cloud content delivery.
- Mobile Simulation Units:Deployable training systems for rural outreach and disaster preparedness exercises.
On-Premise retains legacy commitments. Cloud-Based is expanding most quickly as vendor security certifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal graduate medical education funding and state-level health workforce development grants are reshaping procurement patterns across North American teaching institutions. The Joint Commission's accreditation mandates create synchronized replacement cycles that concentrate demand in specific metropolitan hospital clusters.
United States
Academic medical centers in California, Texas, and New York anchor continental purchasing volume through multi-million-dollar capital allocations for surgical residency infrastructure. The FDA's software as a medical device framework gates market entry for VR surgical platforms, requiring clinical evidence comparable to implantable devices. Methodist Hospital System in Texas standardized enterprise-wide on a single VR platform, displacing incumbent manikin suppliers from affiliated programs.
Canada
Provincial health authorities in Ontario, Quebec, and British Columbia impose parallel validation requirements that extend vendor market entry timelines beyond US pathways. Health Canada and Ontario's Ministry of Health maintain non-identical software validation protocols for simulation platforms. Toronto's University Health Network and McGill University Health Centre in Montreal anchor national procurement clusters for high-fidelity manikin systems.
Mexico
Federal health workforce expansion programs are accelerating simulation center deployment in public medical schools and regional hospital networks. The national pharmaceutical regulator validates imported medical devices through COFEPRIS registration pathways that favor established North American vendors. Mexico City's National Autonomous University and Monterrey's Tecnológico de Monterrey anchor demand concentration in central and northern states.
North America Medical Simulation Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with established hospital system relationships and specialized simulation pure-plays with deep vertical expertise. The vendor base separates into three strategic archetypes: diversified conglomerates leveraging cross-selling infrastructure, simulation specialists with protocol-level partnerships, and emerging VR-native platforms attacking price-sensitive community hospital segments. Dominant competitive moves include enterprise license consolidation across regional health networks and haptic engineering partnerships with academic medical centers for premium product development.
Within the diversified conglomerate tier, CAE Inc. and 3D Systems occupy positions anchored by military medical training contracts and additive manufacturing expertise respectively. Among simulation specialists, Laerdal Medical exemplifies the protocol-partnership archetype through its American Heart Association channel control, while Mentice represents endovascular vertical specialization where catheter-based fidelity determines purchasing decisions. Gaumard Scientific sits within the high-fidelity manikin tier where programmable physiologic modeling resists commoditization pressure.
| Leading Market Players |
|---|
| 3D Systems |
| Gaumard Scientific |
| Laerdal Medical |
| Simulab Corporation |
| CAE Inc. |
| Elevate Healthcare |
| Simulaids |
| Mentice |
| Surgical Science Sweden AB |
| Others |
Cost & Logistics Intelligence
Software platform substitution for pneumatic manikin hardware is redrawing procurement geography across California, Texas, and New York hospital clusters while compressing margin structures for legacy programmable physiologic systems. This input shift simultaneously elevates recurring subscription revenue for cloud-native vendors and deflates capital equipment pricing power among incumbent manikin manufacturers tethered to specialized polymer and actuator supply chains.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared surgical platforms and uncertified training modules. Three-tier pricing structure across premium haptic-enabled systems, standard VR visual-only deployments, and economy task trainers reflects this regulatory stratification. Cost compression in the standard tier is intensifying because Methodist Hospital System's enterprise consolidation in Texas established volume benchmarks that regional competitors now demand. Community hospitals exhibit highest price sensitivity, while Johns Hopkins and Mayo Clinic residency programs absorb premium tier premiums for sub-millimeter force feedback fidelity.
Supply Chain Analysis
Specialized pneumatic actuator manufacturing in Germany, Japan, and the United States constitutes a chokepoint for high-fidelity manikin production. Programmable physiologic systems draw from medical-grade silicone polymers, embedded sensor arrays, and precision servo motors. Single-source vulnerability concentrates in German actuator suppliers serving Laerdal Medical and Gaumard Scientific. Distribution runs through hospital GPO contracts and direct academic medical center procurement teams rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Medical Simulation Market rewards vendors who control scarce hybrid skill sets spanning clinical physiology, software architecture, and haptic engineering. Biomedical engineer talent pipelines at Johns Hopkins, MIT, and Stanford anchor competitive positioning for platform developers who secure exclusive recruiting relationships.
For Market Incumbents: Consolidate channel control through exclusive American Heart Association protocol partnerships and deepen backward integration into haptic actuator manufacturing to defend against VR-native entrants. Methodist Hospital System's single-source standardization in Texas demonstrates how enterprise license consolidation displaces fragmented supplier relationships. Prioritize FDA 510(k) clearance maintenance for machine learning-enabled adaptive difficulty algorithms under the 2023 predetermined change control guidance. For New Entrants and Emerging Players: Differentiate on home-based nursing simulation and remote tele-proctoring capabilities where incumbent platforms remain underdeveloped. Target community health worker training programs in California's Central Valley and Texas border regions where hospital-centric vendors lack service infrastructure. Pursue cloud-native deployment models that bypass legacy LMS integration complexity through API-first architecture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed simulation specialists pursuing roll-up strategies in the endovascular vertical. Five-to-ten-year viability hinges on successful military-civilian technology transfer from Department of Defense combat casualty programs into civilian trauma certification. Monitor CMS reimbursement policy shifts for graduate medical education as the critical inflection signal for simulation procurement volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for ML-Enabled Platforms | Predetermined change control plans lock algorithmic protocols prior to market authorization under 2023 guidance. |
| Hospital System Partnership | Kaiser Permanente and HCA Healthcare enterprise licenses consolidate vendor relationships across dozens of facilities. |
| Software Companion Development | AI-generated patient scenario libraries reduce content development costs through EHR-trained machine learning models. |
| CE Marking Pathway | Health Canada and Ontario Ministry of Health validation requirements extend market entry timelines beyond US pathways. |
| Reimbursement Strategy | ACGME milestone-based progression mandates embed simulation hours into accreditation compliance across surgical residency programs. |
Research Approach
Cross-validation between primary interviews with simulation center directors, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, hospital procurement databases, and CMS Medicare graduate medical education expenditure data. Bottom-up triangulation across product type, application, and end user segments reconciles with top-down market sizing from academic medical center capital budget disclosures and military medical training contract announcements.
Sensitivity analysis across deployment model adoption curves, haptic technology penetration rates, and cloud security certification timelines informs the analytical framework. Segmentation dimensions span product architecture, clinical application, end user institution type, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, ACGME accreditation requirement evolution, and Joint Commission patient safety mandate enforcement patterns throughout the projection horizon.
Material uncertainties — FDA software as medical device reclassification, Canadian provincial validation harmonization failure, and biomedical engineer talent pipeline contraction — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ACGME milestone implementation velocity and military-civilian technology transfer success. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Stand-Up Pouch Valves Market
Others
Global Lavender Extracts Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Refractometer Market
Others
Egg and Egg Products Market
Others
Folding Smartphone Market
Others
Global Sports and Fitness Wears Market
Others
Consumer Video Feedback Software Market
Others
Managed Video As a Service Market
Others
Lychee Market
Others
Hopper Dryers Market
Others
Depth Gauge Market
Others
Tobacco Packaging Market
Others
Folding Mobile Phone Market
Others
Construction Wearables Market
Others
Africa 3D Printing Construction Market